
 Diabetic Eye Disease Devices Market | 2026-2036
Diabetic Eye Disease Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Eye Disease Devices Market Analysis
Hospital procurement of diabetic eye disease devices is rewriting how capital equipment reaches clinical settings. Alcon Inc. leverages its surgical portfolio to anchor premium laser photocoagulation placements in integrated delivery networks. Carl Zeiss Meditec dominates diagnostic imaging through dense service contracts with academic medical centers. Topcon Corp. competes on ophthalmic clinic access, sustaining volume through distributor relationships in outpatient settings.
Diabetic eye disease devices encompass instruments for detecting, monitoring, and treating retinal complications of diabetes mellitus, including optical coherence tomography systems resolving retinal layers at 3-5 micron precision and laser photocoagulation units delivering 50-200 millisecond thermal burns to seal leaking microaneurysms. These tools serve the primary commercial purpose of preventing vision loss in diabetic populations through early intervention and longitudinal disease management. Retinal scanners lead product type revenue due to their role in routine screening workflows, while AI-based imaging represents the fastest-expanding technology segment as machine learning algorithms reduce specialist interpretation burden. Ophthalmic clinics capture disproportionate end-user margin pools compared to hospitals, driven by lower overhead and higher procedure throughput per device.
FDA premarket review under the 21st Century Cures Act shapes AI diagnostic validation requirements, while the EU MDR imposes stricter clinical evidence standards on laser therapeutic devices entering European markets. ISO 13485 quality management certification functions as a baseline predicate for market access across OECD jurisdictions. Stakeholders must monitor how reimbursement policy for remote diabetic retinopathy screening reshapes site-of-care economics and capital deployment priorities.
Market Dynamics
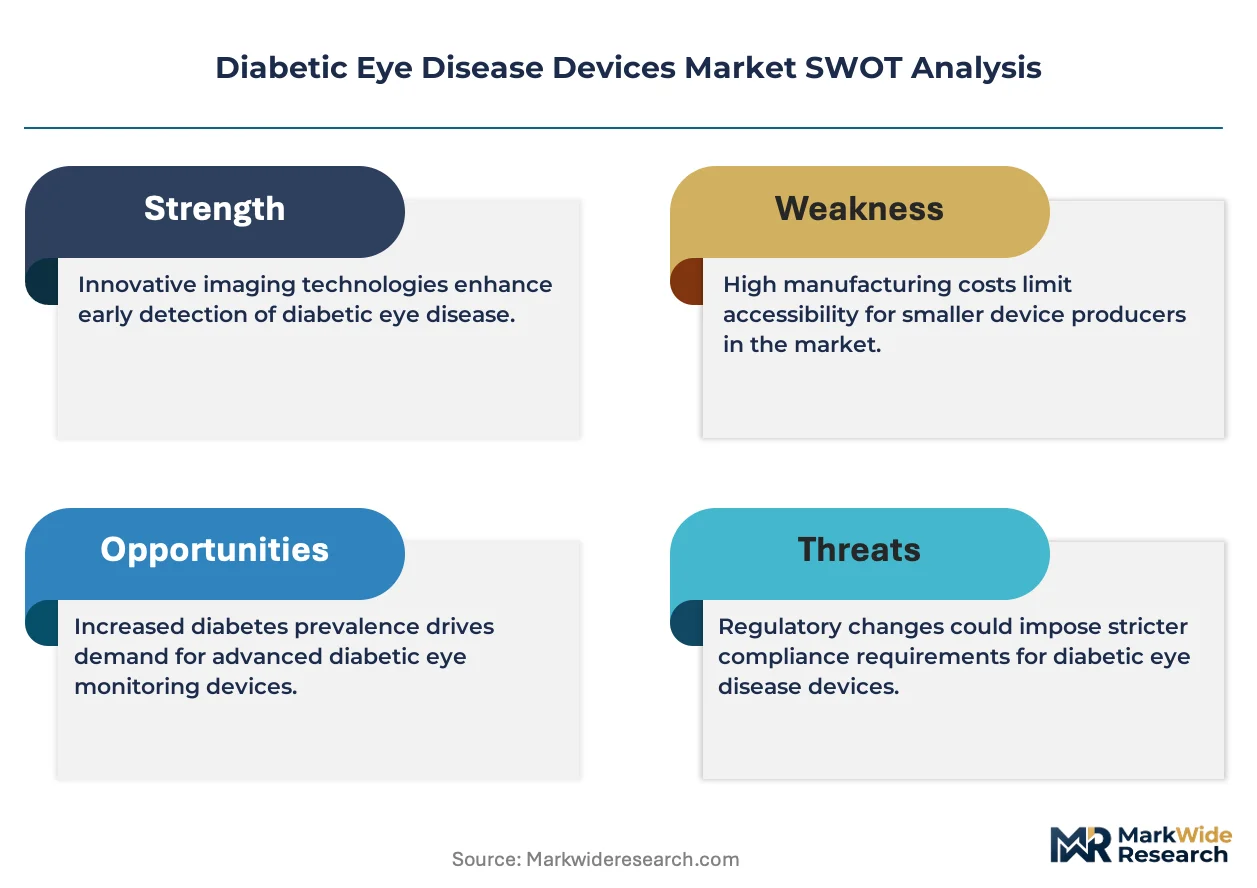
AI diagnostic algorithms are compressing specialist interpretation timelines, forcing device manufacturers to embed machine learning directly into hardware rather than offering it as aftermarket software. This integration imperative reshapes R&D budgets and partnership strategies across the sector.
Growth Catalysts
- Medicare tele-ophthalmology reimbursement:The United States federal payment framework now covers remote diabetic retinopathy screening, channeling patient volume toward devices capable of cloud-connected image capture and transmission.
- Hospital screening program expansion:Integrated delivery networks in North America are deploying capital for point-of-care retinal scanners to intercept disease progression before specialist referral becomes necessary.
- FDA Breakthrough Device Designation:This accelerated review pathway compresses time-to-market for AI-based diagnostic systems, rewarding manufacturers who invest in prospective clinical validation studies.
Market Restraints
- Specialist workforce scarcity:The limited pool of board-certified retinal specialists constrains interpretation capacity, creating bottlenecks that hardware deployment alone cannot resolve.
- EU MDR clinical evidence requirements:Stricter conformity assessment procedures for laser therapeutic devices extend European market entry timelines and inflate regulatory consulting expenditures.
- Optical component supply concentration:Precision optics for OCT systems source from a narrow German and Japanese supplier base, exposing manufacturers to single-source disruption risk.
Strategic Opportunities
- Primary care integration:Underpenetrated rural and community health centers in the United States represent install base expansion potential for tabletop screening devices with simplified operator interfaces.
- AI-software-as-service models:Recurring revenue architectures for algorithm updates and cloud storage detach profitability from hardware replacement cycles.
- Home-based monitoring convergence:Smartphone camera adapters paired with patient-facing applications open longitudinal tracking opportunities outside traditional clinical settings.
Industry Challenges
- ISO 13485 quality management certification:Documented design controls and risk management files demand dedicated personnel, stretching mid-tier manufacturers with limited regulatory affairs bandwidth.
- Legacy EMR interoperability:DICOM conformance and HL7 FHIR integration requirements consume engineering resources as hospital IT departments insist on seamless data flow into existing electronic record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Eye Disease Devices Market |
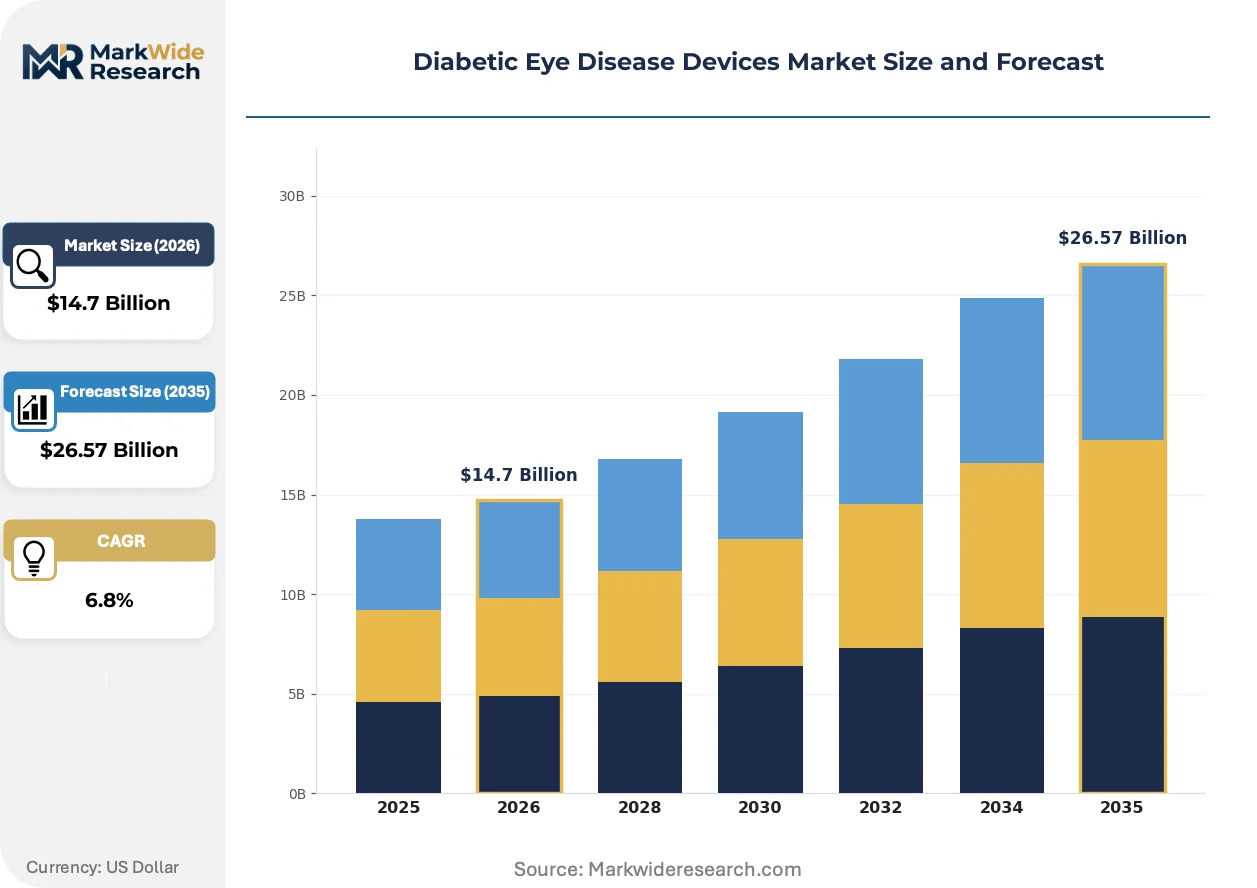
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retinal Scanners, Laser Photocoagulation Devices, Optical Coherence Tomography, Diagnostic Imaging Devices End User: Ophthalmic Clinics, Hospitals, Ambulatory Surgical Centers, Home Care Technology: Fundus Photography, Wavefront Technology, AI-Based Imaging, Fluorescein Angiography Application: Diagnosis, Monitoring, Treatment, Research |
| Companies Covered | Alcon Inc., Bausch Health Companies Inc., Carl Zeiss Meditec, Ellex Medical Lasers Ltd., IRIDEX Corp., Topcon Corp., Lumenis, NIDEK Co. Ltd., Quantel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Eye Disease Devices Market Emerging Trajectories
Device functionality is fragmenting across hardware miniaturization, algorithmic autonomy, and service model reinvention. These vectors collectively shift value capture from capital sale toward longitudinal patient relationship economics.
Optical coherence tomography angiography is migrating from research-grade hospital installations toward compact systems suitable for high-volume ophthalmic clinics. Outpatient settings in the United States are adopting these units to differentiate screening services without specialist co-location. The technology is migrating from diagnostic confirmation toward frontline disease stratification, compressing referral thresholds and expanding addressable procedure volume.
The FDA's 21st Century Cures Act software precertification pilot is restructuring validation requirements for machine learning-based diagnostic tools. Manufacturers must now maintain real-world performance monitoring systems rather than front-loading all clinical evidence prior to clearance. AI-enabled imaging platforms face the steepest compliance adaptation burden, particularly those targeting autonomous diagnosis without clinician overlay.
After-sales service contracts are unbundling from capital equipment purchases as ophthalmic clinics seek operational flexibility. Independent service organizations and manufacturer-direct subscription tiers now compete for maintenance revenue previously captured by bundled warranty extensions. This shift is most visible in the United States, where clinic chains with centralized procurement functions negotiate multi-site service agreements separate from device acquisition decisions.
Diabetic Eye Disease Devices Market Segmentation
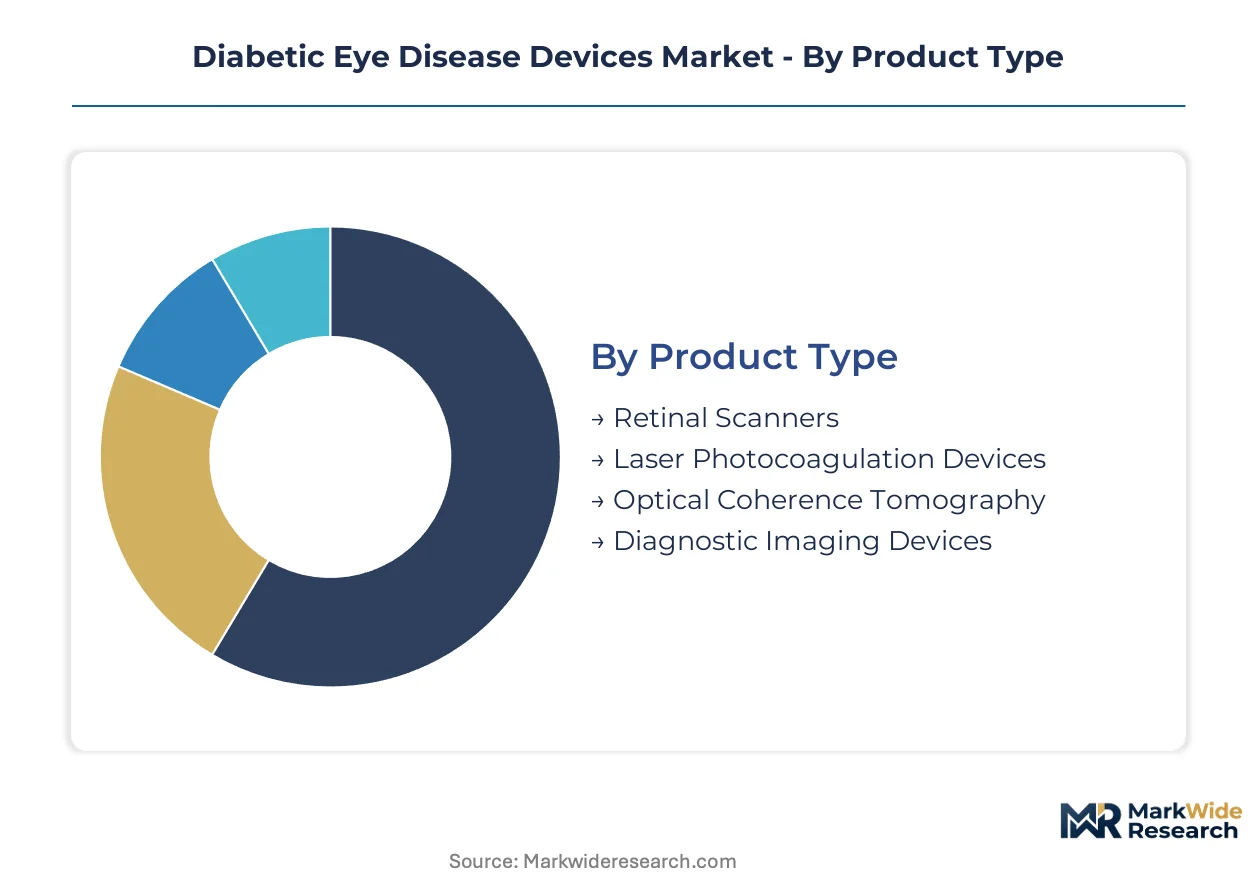
Device segmentation in diabetic eye disease management reflects divergent clinical workflows across screening, diagnosis, and intervention stages. Procurement patterns vary sharply between capital-intensive hospital installations and high-turnover ophthalmic clinic deployments. Understanding these segment boundaries clarifies where manufacturers must adapt hardware specifications, software integration, and service architectures to capture margin pools.
Product Type:
The use-case spectrum spans preventive screening infrastructure through therapeutic intervention platforms, with each product category commanding distinct capital cycles and operator skill requirements.
- Retinal Scanners:Non-mydriatic fundus cameras capture wide-field retinal images without pupil dilation, enabling rapid throughput in high-volume screening environments. Demand concentrates in United States ophthalmic clinics where Medicare reimbursement for remote diabetic retinopathy screening drives install base expansion. The FDA's Breakthrough Device Designation pathway accelerates approvals for cloud-connected models that transmit images to off-site specialists.
- Optical Coherence Tomography:Interferometric imaging systems resolve retinal microstructure at 3-5 micron axial resolution, supporting diagnostic confirmation and treatment planning for diabetic macular edema. Academic medical centers in the United States anchor demand through dense service contracts with manufacturers offering research-grade spectral-domain platforms. Carl Zeiss Meditec dominates this segment through embedded software ecosystems that lock in longitudinal maintenance revenue.
- Laser Photocoagulation Devices:Thermal laser units deliver targeted burns to seal leaking microaneurysms in proliferative diabetic retinopathy.
- Diagnostic Imaging Devices:Multimodal platforms combine angiography, autofluorescence, and structural imaging for comprehensive disease characterization.
The dominant share belongs to Retinal Scanners, while Optical Coherence Tomography is closing the gap fastest.
End User:
Site-of-care economics create tiered margin profiles, with overhead structure and procedure volume per device determining procurement negotiation leverage.
- Ophthalmic Clinics:Outpatient specialty practices generate disproportionate margin pools through higher device utilization rates and lower fixed cost absorption per procedure. United States clinic chains leverage centralized procurement to negotiate multi-site service agreements separate from capital acquisition. Topcon Corp. sustains volume in this segment through distributor relationships that provide localized technical support without manufacturer direct sales overhead.
- Hospitals:Integrated delivery networks deploy point-of-care retinal scanners to intercept disease progression before specialist referral becomes necessary. North American hospital systems are expanding screening programs to reduce blindness incidence from diabetic retinopathy, channeling capital toward devices with EMR interoperability and quality reporting integration.
- Ambulatory Surgical Centers:Freestanding surgical facilities concentrate therapeutic laser procedures for patients requiring immediate intervention.
- Home Care:Smartphone camera adapters paired with patient-facing applications enable longitudinal tracking outside traditional clinical settings.
Ophthalmic Clinics command the highest margin capture per device, though Hospitals are expanding install base most aggressively.
Technology:
Underlying imaging modalities determine regulatory pathway complexity and the pace of algorithmic enhancement through machine learning integration.
- AI-Based Imaging:Deep learning algorithms automate lesion detection and severity grading, reducing specialist interpretation burden in screening workflows. The FDA's software precertification pilot under the 21st Century Cures Act now mandates real-world performance monitoring rather than front-loaded clinical evidence, reshaping validation budgets for autonomous diagnostic platforms.
- Fundus Photography:Standard color imaging of the retina remains the backbone of population-level screening programs due to equipment cost accessibility and established reimbursement codes.
- Fluorescein Angiography:Intravenous dye-based vascular imaging provides dynamic assessment of retinal perfusion and leakage patterns.
- Wavefront Technology:Aberrometry systems map optical imperfections to guide customized treatment planning.
AI-Based Imaging is gaining share fastest, while Fundus Photography retains the largest installed base.
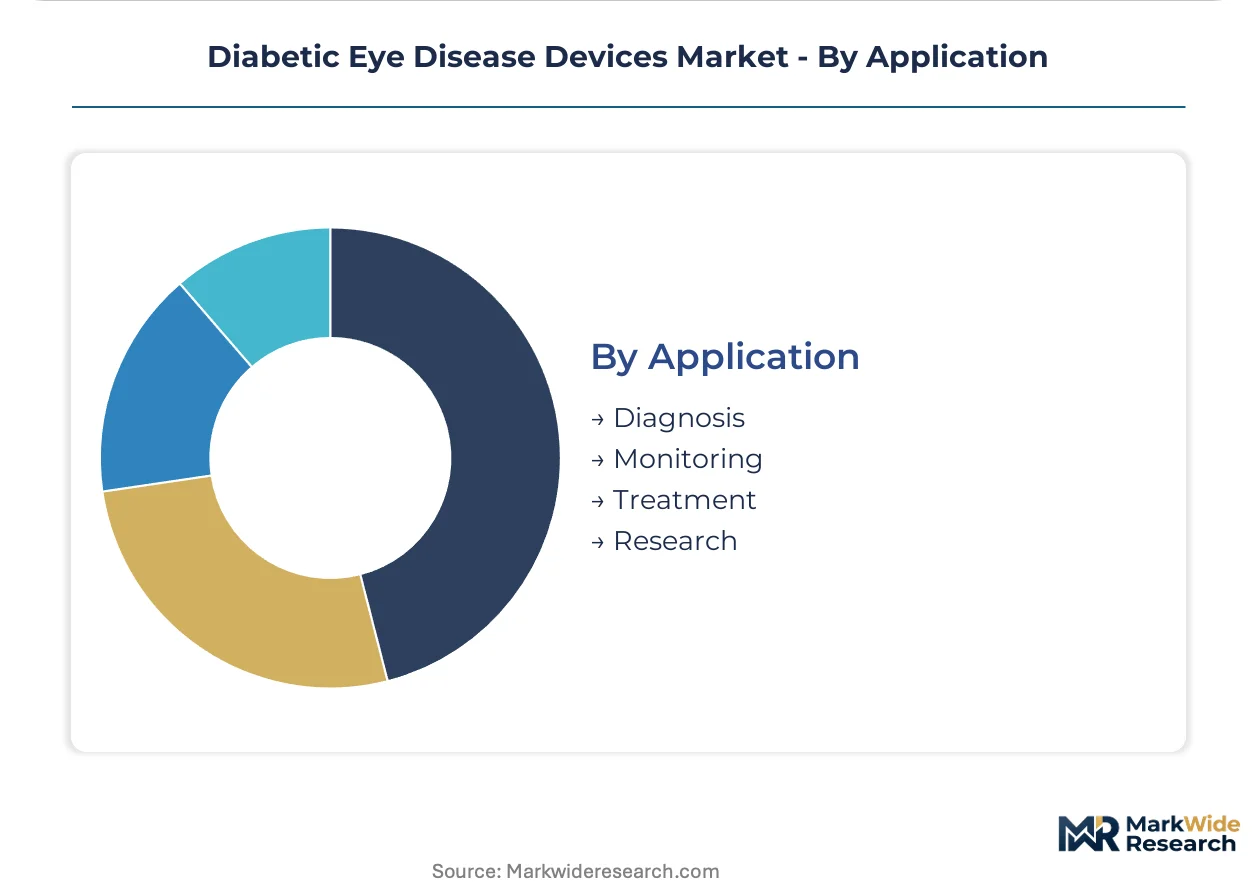
Application:
Functional purpose across the care continuum shapes device specification requirements and customer purchasing criteria.
- Diagnosis:Frontline detection of diabetic retinopathy and diabetic macular edema drives volume for screening-optimized hardware with simplified operator interfaces. Primary care integration in underpenetrated rural United States health centers represents expansion potential for tabletop devices capable of autonomous image quality assessment.
- Monitoring:Longitudinal tracking of disease progression demands devices with robust data management and comparison analytics.
- Treatment:Therapeutic intervention platforms require precise energy delivery control and intraoperative imaging integration.
- Research:Academic and pharmaceutical study applications prioritize imaging resolution and data export flexibility.
Diagnosis absorbs the majority of device shipments, though Monitoring applications are expanding most quickly as value-based care contracts emphasize longitudinal outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for diabetic eye disease devices concentrates in the United States, where Medicare reimbursement premiums exceed European procurement benchmarks by substantial margins. German hospital systems negotiate centralized tenders that compress vendor margins, while Japanese academic centers sustain premium positioning through research-grade equipment specifications.
United States
Medicare tele-ophthalmology reimbursement and hospital screening program expansion drive demand for cloud-connected retinal scanners. The FDA's Breakthrough Device Designation accelerates AI diagnostic approvals, rewarding prospective clinical validation investments. Massachusetts and California host dense clusters of academic medical centers where Carl Zeiss Meditec anchors service-contract relationships.
Germany
Hospital procurement centralization through regional purchasing cooperatives intensifies price competition for OCT systems. The EU MDR imposes stricter clinical evidence requirements on laser therapeutic devices, extending conformity assessment timelines. Baden-Württemberg's precision optics supplier base feeds component demand for domestic and Asian OEM manufacturers.
Japan
PMDA regulatory pathways favor incremental innovation in fundus camera miniaturization for high-volume ophthalmic clinics. METI funding programs support AI diagnostic algorithm development for aging population screening. Tokyo and Osaka metropolitan areas concentrate specialist practice networks that sustain premium diagnostic equipment placements.
China
NMPA priority review pathways for AI-enabled medical devices attract domestic and multinational validation investments. Provincial hospital tiering systems channel screening device volume toward secondary and tertiary facilities in Jiangsu and Guangdong. Yangtze River Delta manufacturing clusters supply optical components for regional OCT system assemblers.
India
CDSCO streamlined approval processes for Class B and C ophthalmic devices accelerate market entry for tabletop screening systems. Ayushman Bharat insurance expansion creates reimbursement infrastructure for diabetic retinopathy detection in tier-2 and tier-3 cities. Karnataka and Tamil Nadu ophthalmology chains drive volume procurement of cost-optimized fundus cameras.
Diabetic Eye Disease Devices Market Vendor Landscape
Integrated surgical-diagnostics conglomerates and pure-play ophthalmic specialists split the market along capital intensity and service bundling vectors. The vendor base concentrates around three strategic archetypes: diversified medtech portfolios leveraging cross-selling infrastructure; focused ophthalmic equipment manufacturers competing on distributor density; and AI-software developers seeking hardware embedding partnerships. Dominant competitive moves include service contract unbundling to capture recurring maintenance revenue, and strategic partnerships between device OEMs and cloud-based algorithm platforms.
Among diversified medtech conglomerates, Alcon Inc. and Carl Zeiss Meditec occupy positions that exemplify divergent route-to-market strategies. Alcon anchors integrated delivery network relationships through surgical equipment pull-through, while Carl Zeiss Meditec represents the diagnostic imaging specialist archetype with embedded software ecosystems. Topcon Corp. sits within the focused ophthalmic equipment tier, sustaining outpatient clinic access through distributor relationships that minimize direct sales overhead.
| Leading Market Players |
|---|
| Alcon Inc. |
| Bausch Health Companies Inc. |
| Carl Zeiss Meditec |
| Ellex Medical Lasers Ltd. |
| IRIDEX Corp. |
| Topcon Corp. |
| Lumenis |
| NIDEK Co. Ltd. |
| Quantel |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's precision optics cluster supplies interferometric components to OCT system assemblers across Germany and Japan, concentrating upstream capacity among a narrow supplier base that transmits pricing power downstream to device manufacturers serving Medicare-reimbursed United States clinics.
Pricing Analysis
The customization-premium spread separates research-grade spectral-domain OCT platforms from tabletop fundus cameras by roughly the cost of embedded AI diagnostic modules and multi-year service bundling. Three-tier pricing structure across premium, standard, and economy levels tracks FDA Breakthrough Device Designation status, ISO 13485 certification tier, and after-sales contract comprehensiveness. Cost compression in economy-tier screening devices is intensifying because Indian and Chinese OEMs are flooding community health centers with cost-optimized hardware. Ophthalmic clinic chains with centralized procurement functions exhibit the sharpest price sensitivity, while academic medical centers absorbing research-grade equipment tolerate premium positioning.
Supply Chain Analysis
Contract-manufacturing concentration for optical assemblies rests with German and Japanese precision optics specialists that feed both Carl Zeiss Meditec and Topcon Corp. fabrication lines. Component sourcing draws from Germany, Japan, and China for laser diodes, interferometric sensors, and CMOS detectors. Single-source vulnerability concentrates in high-precision OCT gratings and specialized laser crystals. Distribution runs through manufacturer-direct service organizations in the United States and dense distributor networks in outpatient ophthalmic settings across Europe and Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: FDA 21st Century Cures Act precertification requirements and ISO 13485 quality management documentation create switching costs that lock hospital systems into validated supplier relationships.
For Market Incumbents: Pre-empt AI-software-as-service revenue erosion by embedding machine learning inference directly into hardware firmware rather than permitting cloud-only algorithm deployment. Threats from smartphone camera adapter substitutes and home-based monitoring convergence demand backward integration into precision optics manufacturing to defend component cost structures. Priority investment in real-world performance monitoring systems satisfies FDA post-market surveillance mandates.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated rural United States primary care centers where simplified-operator-interface tabletop retinal scanners face limited incumbent service infrastructure. White-space targets include community health centers in tier-2 Indian cities and provincial Chinese secondary hospitals. Go-to-market angle: AI-diagnostic-only software licensing to existing hardware install bases, avoiding capital-intensive manufacturing entry barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-software developers with FDA Breakthrough Device Designation momentum and hospital system pilot contracts over pure-play hardware manufacturers facing replacement cycle compression. Long-term viability hinges on recurring revenue architectures detaching profitability from device obsolescence. Acquisition target archetype: cloud-connected imaging platforms with embedded algorithm ecosystems. Signal to watch: Medicare reimbursement expansion for autonomous diagnosis without specialist overlay.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerated review pathway compresses time-to-market for AI diagnostic platforms seeking Medicare reimbursement eligibility. |
| Cloud-Connected Image Capture Integration | Tele-ophthalmology reimbursement requirements channel procurement toward devices with HL7 FHIR interoperability and secure transmission protocols. |
| Service Contract Unbundling | Independent maintenance tiers capture recurring revenue streams previously locked in bundled warranty extensions at ophthalmic clinic chains. |
| Primary Care Distribution Partnership | Localized technical support through distributor relationships penetrates rural health centers without manufacturer direct sales overhead. |
| Real-World Performance Monitoring Infrastructure | FDA software precertification pilot mandates continuous algorithm validation systems for autonomous diagnostic platforms. |
Methodological Framework
The analysis maps retinal scanners, OCT systems, laser photocoagulation devices, and AI-based imaging platforms, each validated through ophthalmologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR conformity assessment documentation. Bottom-up install base modeling and top-down expenditure flow analysis triangulate market sizing across the projection horizon.
Assumption sets held regulatory pathway timelines and Medicare reimbursement rates fixed while varying AI diagnostic adoption curves and specialist workforce scarcity intensity across geographies. Segmentation dimensions modeled include product type, end-user site-of-care, underlying technology modality, and application purpose across the care continuum. CAGRs derive from procedure volume elasticity to reimbursement expansion and device replacement cycle compression. Forecast inputs incorporate cloud-connected screening penetration rates and AI algorithm validation cost trajectories.
Sensitivities concentrate around FDA software precertification rulemaking changes, EU MDR clinical evidence requirement inflation, and Medicare tele-ophthalmology reimbursement scope revisions. Forecasts reflect documented assumptions subject to revision from these triggers. Quarterly review of FDA Breakthrough Device Designation grant velocity and CMS remote screening code utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Ventilators Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Pectus Bar System Market
Medical Devices
Global Veress Needle Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Venous Device Market
Medical Devices
Implantable Drug Eluting Devices Market