
 Spain Cosmetic Surgery Market | 2026-2036
Spain Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Cosmetic Surgery Market Insights
The pipeline of board-certified plastic surgeons in Spain is collapsing as training program enrollment stagnates against rising procedure volumes. EGOS Group leverages its Madrid-Barcelona clinic network to secure talent through dedicated fellowship partnerships. Hospital Ruber Internacional anchors premium reconstructive capacity while competing for specialists against public hospital salaries. Quirónsalud Marbella differentiates through its Costa del Sol medical tourism hub, drawing Northern European patients year-round.
Cosmetic surgery encompasses elective aesthetic procedures modifying facial or body appearance through surgical intervention, typically requiring accredited operating facilities and specialist anesthesia protocols. Its primary commercial purpose centers on appearance enhancement for patient-directed aesthetic goals rather than medically necessary reconstruction. Breast augmentation and liposuction dominate procedure revenue, while minimally invasive technologies capture the fastest expansion as recovery times shrink and clinic throughput rises. Laser surgery and injectable fillers attract younger demographics, shifting margin pools toward repeat-visit maintenance protocols rather than one-time surgical events.
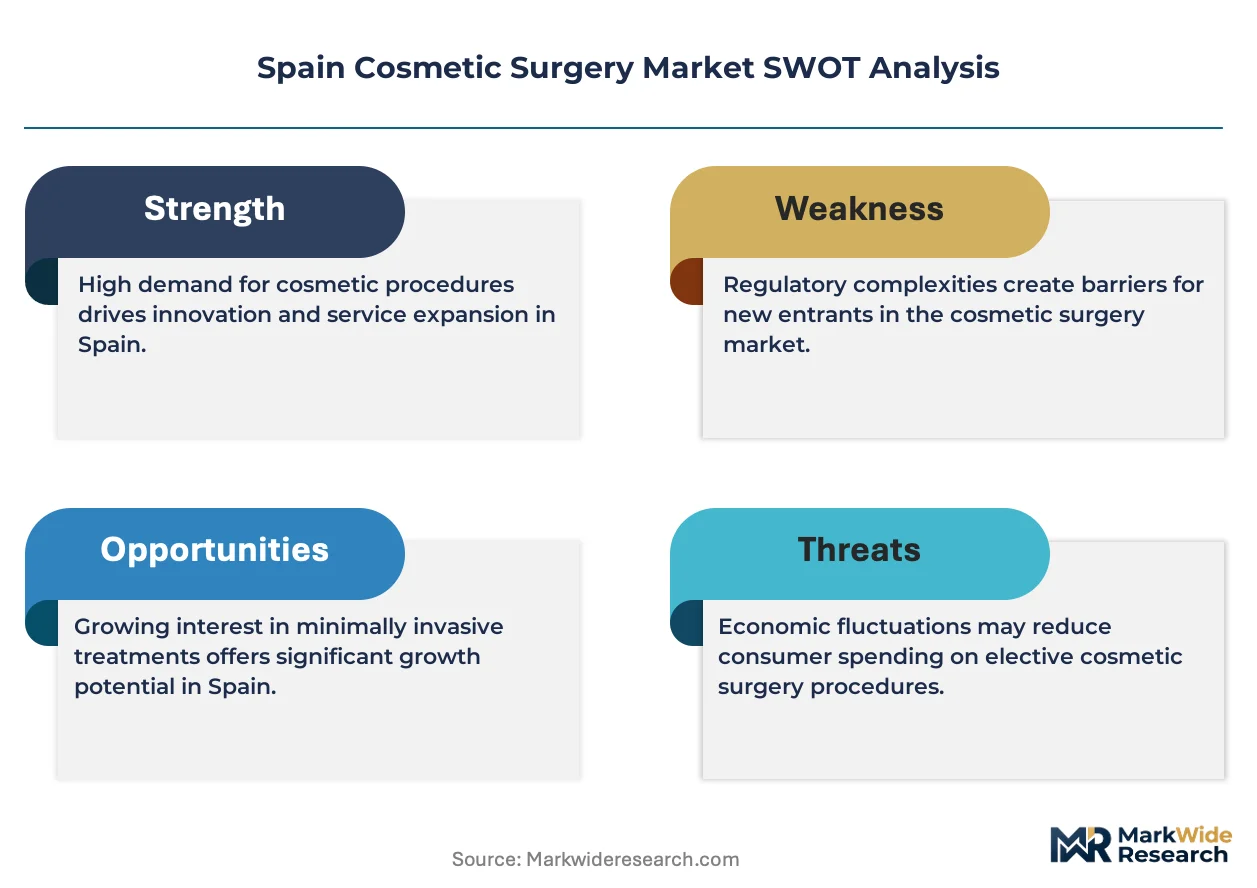
Spain's Ministry of Health regulates clinic licensing and advertising content, while the General Medical Council enforces practitioner certification standards that limit market entry. The EU Medical Device Regulation, adopted into Spanish law, reclassifies implantable aesthetic devices and extends pre-market documentation requirements. Stakeholders must monitor how regional health authority inspections of private clinics intensify and whether medical tourism credentialing schemes emerge to capture cross-border patient flows.
Market Dynamics
The Spain cosmetic surgery market contends with a structural talent squeeze as procedure volumes expand faster than specialist training pipelines, forcing clinics to compete aggressively for board-certified plastic surgeons against public hospital compensation packages.
Growth Catalysts
- EU Medical Device Regulation:The MDR's reclassification of implantable aesthetic devices raises documentation barriers that favor established Spanish clinics with dedicated regulatory affairs teams, consolidating patient flows toward accredited facilities.
- Minimally invasive technologies:Laser surgery and injectable fillers compress recovery windows from weeks to days, enabling Madrid and Barcelona clinics to triple daily patient throughput compared to traditional surgical protocols.
- Medical tourism corridors:Northern European patients increasingly route through Costa del Sol facilities, drawn by year-round climate advantages and EU-recognized credentialing standards that simplify cross-border insurance processing.
Market Restraints
- Anesthesia specialist scarcity:Spain's public hospital system captures the majority of accredited anesthesiologists, leaving private cosmetic clinics dependent on costly locum arrangements that erode margin structures on lower-complexity procedures.
- Advertising restrictions:Spain's Ministry of Health tightened content rules for aesthetic procedure promotion, eliminating price-based marketing channels that previously drove patient acquisition for mid-tier Madrid operators.
- Implant supply concentration:High-grade silicone implant manufacturing concentrates among three EU-based suppliers, exposing Spanish clinics to euro-denominated input volatility and extended procurement lead times.
Strategic Opportunities
- Andalusia medical tourism infrastructure:Underdeveloped credentialing schemes for cross-border patient flows present first-mover advantages for Malaga and Marbella clinics that establish direct billing relationships with Northern European insurers.
- Maintenance protocol monetization:Injectable filler regimens create recurring revenue streams that surgical-only practices cannot capture, shifting margin pools toward Barcelona-based chains with dedicated aesthetic nursing staff.
- Fellowship pipeline control:Dedicated training partnerships with Spanish medical schools offer clinic networks captive specialist supply, insulating against public sector salary competition in Madrid's concentrated provider market.
Industry Challenges
- Operating facility certification timelines:Regional health authority inspections for private clinic licensing extend six to nine months, delaying revenue recognition for capital-intensive Madrid facility expansions.
- Digital patient record integration:Legacy practice management systems in established Barcelona clinics resist interoperability with telemedicine platforms, complicating remote consultation workflows that younger demographics expect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Cosmetic Surgery Market |
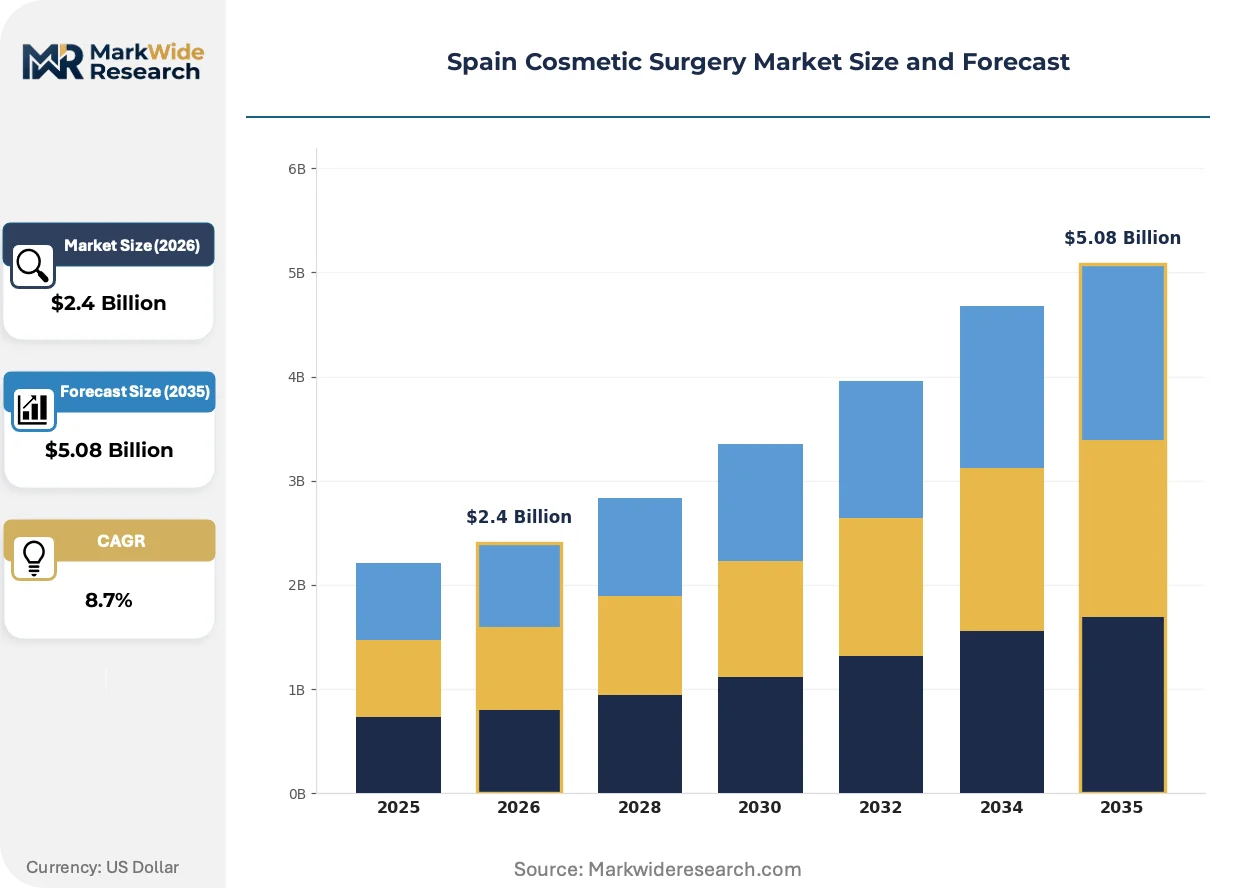
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Liposuction, Rhinoplasty, Tummy Tuck End User: Women, Men, Adolescents, Aging Population Technology: Laser Surgery, Injectable Fillers, Minimally Invasive, Traditional Surgery Service Type: Private Clinics, Public Hospitals, Home Care, Medical Tourism |
| Companies Covered | Clinica Granado Tiagonce, Aurea Clinic, EGOS Group, ANDSURGEONS Clinic, Hospital Ruber Internacional, Centro Médico Teknon, Quirónsalud Marbella, Centre Quirurgic Maresme, Clínica Planas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Cosmetic Surgery Market Trends and Innovations
Technological fragmentation is reshaping competitive positioning across Spanish cosmetic surgery, as minimally invasive modalities capture volume share from traditional surgical suites and regulatory frameworks force operational adaptation.
Energy-based devices utilizing radiofrequency and high-intensity focused ultrasound are bifurcating the non-surgical segment, enabling skin tightening and body contouring without incision. Madrid aesthetic clinics deploy these platforms to attract patients aged thirty-five to fifty who reject surgical downtime. The technology is bifurcating procedure economics, compressing per-treatment revenue while expanding total addressable volume through reduced barrier-to-entry.
Spain's Ministry of Health advertising restrictions now prohibit before-and-after imagery and promotional pricing in aesthetic medicine communications. The policy eliminates primary patient acquisition channels for independent operators, forcing consolidation toward clinic networks with established referral ecosystems and organic search visibility. Premium Barcelona facilities respond by investing in educational content marketing that navigates regulatory boundaries while building specialist authority.
Patient acquisition through social media influencer partnerships has displaced traditional medical referral networks among Spanish consumers under forty. Instagram and TikTok content creators now drive consultation bookings for Madrid injectable specialists, bypassing general practitioner gatekeeping that historically filtered aesthetic demand. This channel shift concentrates marketing spend toward digital-native clinic operators with in-house content production capabilities, most visible in Barcelona's competitive private practice landscape.
Spain Cosmetic Surgery Market Segmentation
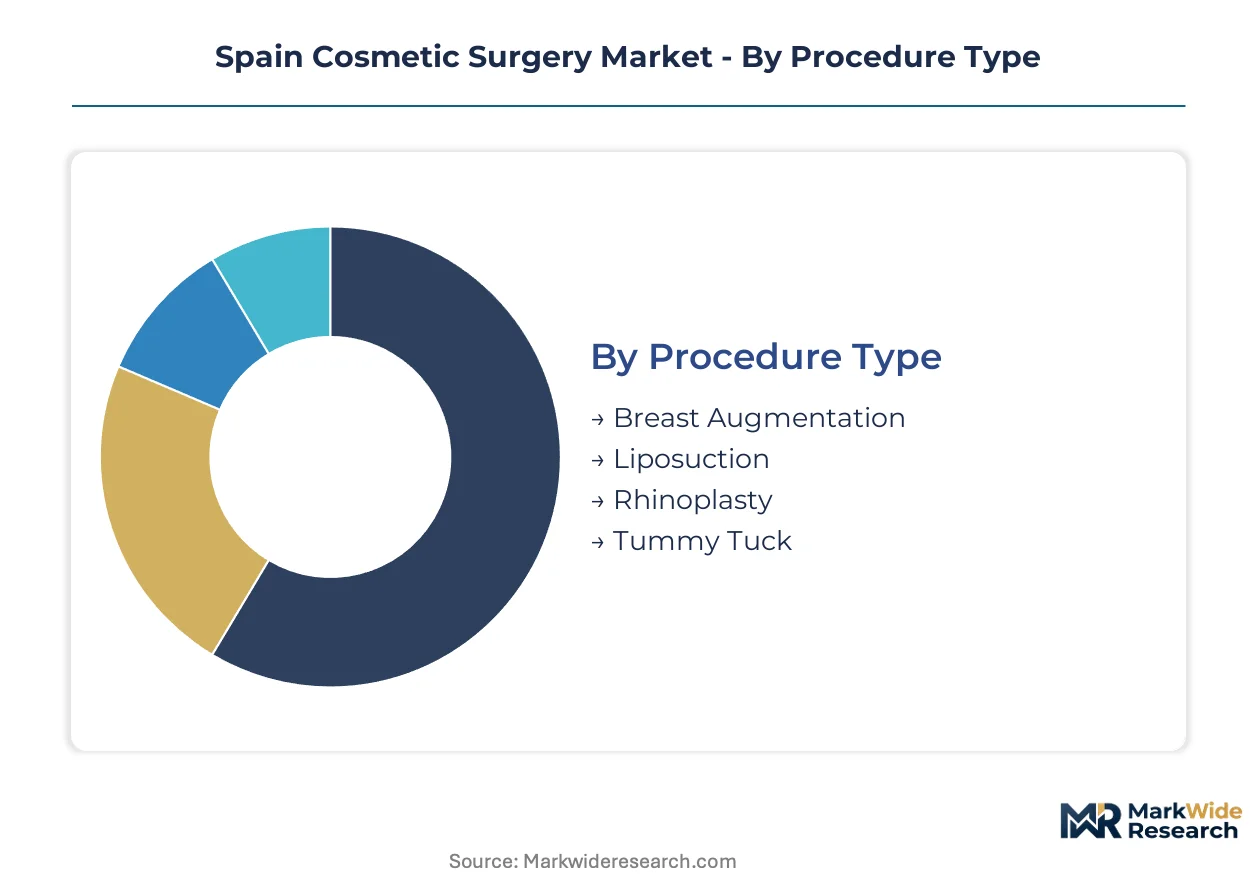
Segmentation in Spain's cosmetic surgery market reveals how procedure economics, patient demographics, and facility types concentrate margin pools differently across Madrid and Barcelona versus Costa del Sol medical tourism corridors. Understanding these splits exposes where regulatory constraints and technology shifts reshape competitive positioning.
Procedure Type:
Highest margin capture sits with complex surgical interventions requiring accredited anesthesia protocols and overnight facility stays.
- Breast Augmentation:Silicone and saline implant procedures demand specialized operating suites and EU MDR-compliant device documentation. Madrid private clinics concentrate demand among women aged twenty-five to forty-five, though Spain's Ministry of Health advertising restrictions now limit before-and-after promotional content that previously drove patient acquisition.
- Liposuction:Fat removal techniques span traditional tumescent methods to laser-assisted modalities with compressed recovery windows. Barcelona facilities capture volume through combination packages with body contouring, while supply chain concentration among three EU-based implant suppliers creates procurement vulnerability for high-grade silicone-dependent augmentation procedures.
- Rhinoplasty:Nasal reshaping requires otolaryngology or maxillofacial specialist credentials under General Medical Council certification standards.
- Tummy Tuck:Abdominoplasty procedures cluster in post-pregnancy demographic segments across Andalusia medical tourism hubs.
The dominant share belongs to Breast Augmentation, while Liposuction is closing the gap fastest through minimally invasive technology adoption.
End User:
Volume concentration tracks age-correlated aesthetic concerns and gender-differentiated procedure preferences across Spanish metropolitan markets.
- Women:The core patient base spanning breast, body contouring, and facial aesthetic procedures. Barcelona and Madrid clinics target this segment through maintenance protocol monetization with injectable filler regimens creating recurring revenue streams.
- Men:Gynecomastia correction and facial rejuvenation procedures expand fastest among forty-five to sixty-five demographic. Costa del Sol facilities report rising Northern European male medical tourism for discreet recovery environments.
- Adolescents:Otoplasty and rhinoplasty dominate with parental consent requirements under Spanish health authority regulations.
- Aging Population:Eyelid surgery and facial tightening concentrate among sixty-plus segments seeking functional and aesthetic outcomes.
Women retain the largest volume footprint, though Men are expanding most quickly as social stigma erosion and remote-work discretion preferences reshape demand.
Technology:
Capital intensity and per-procedure revenue compression diverge sharply between surgical suite investments and energy-based device platforms.
- Laser Surgery:Energy-based skin resurfacing and hair removal deploy in outpatient settings without anesthesia specialist requirements. Madrid aesthetic clinics utilize these platforms to triple daily patient throughput compared to traditional surgical protocols.
- Injectable Fillers:Hyaluronic acid and neuromodulator administration shifts margin pools toward repeat-visit maintenance rather than one-time surgical events. Barcelona-based chains with dedicated aesthetic nursing staff capture this recurring revenue structure most effectively.
- Minimally Invasive:Radiofrequency and high-intensity focused ultrasound enable skin tightening without incision recovery.
- Traditional Surgery:Incision-based procedures maintain premium positioning for complex reconstructive and augmentation cases.
Traditional Surgery holds the revenue base, while Injectable Fillers are gaining share fastest through younger demographic penetration and clinic throughput advantages.
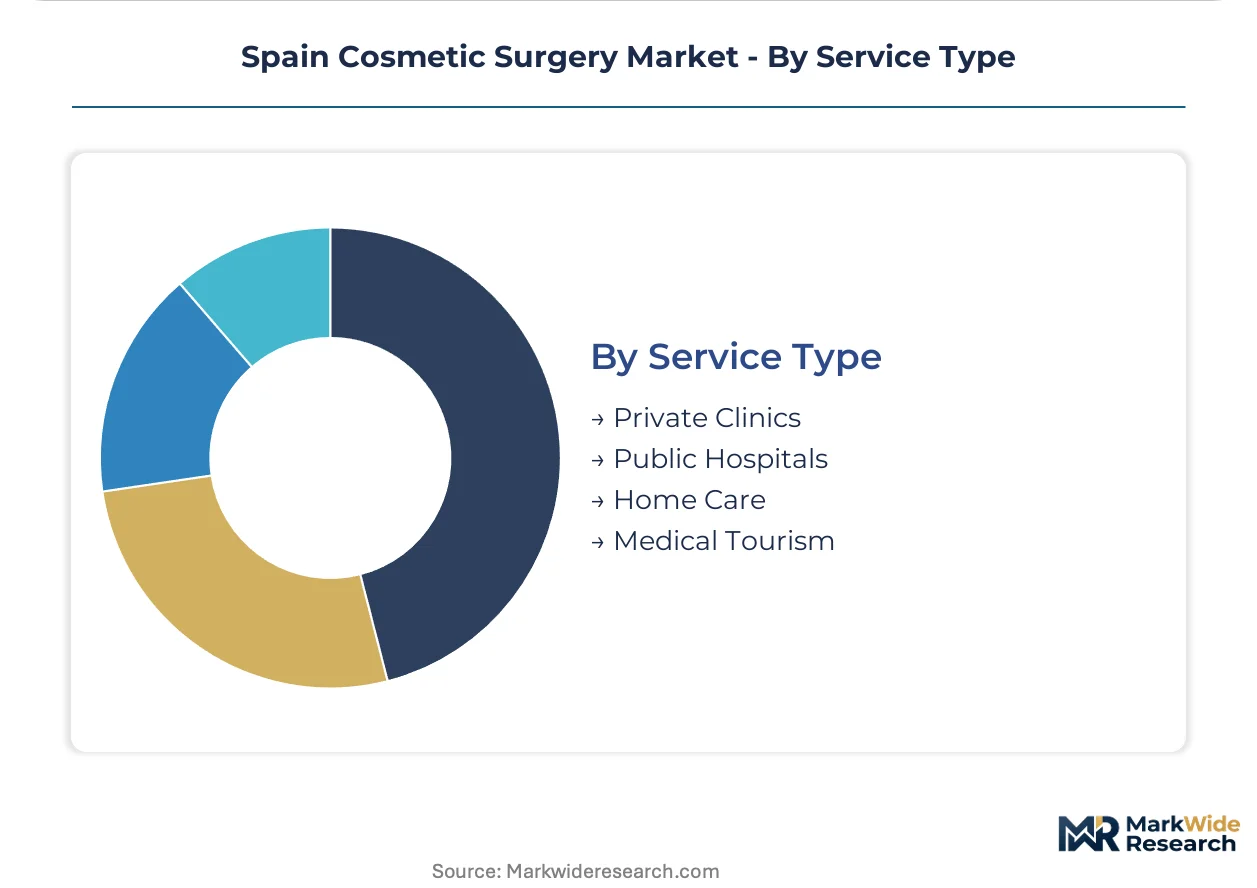
Service Type:
Facility certification timelines and reimbursement structures create divergent competitive moats across Spain's public-private healthcare boundary.
- Private Clinics:Independent and networked facilities dominate aesthetic procedure volume with faster scheduling flexibility than public alternatives. EGOS Group and Hospital Ruber Internacional anchor Madrid-Barcelona capacity, while six-to-nine-month regional health authority licensing inspections delay competitor entry.
- Public Hospitals:Reconstructive and trauma-related cosmetic procedures concentrate here with salary-competitive anesthesia specialist capture. Quirónsalud Marbella competes against this talent pool through dedicated fellowship partnerships.
- Home Care:Post-operative recovery and injectable maintenance services extend clinic relationships beyond facility walls.
- Medical Tourism:Costa del Sol facilities leverage year-round climate and EU-recognized credentialing to attract Northern European patients with simplified cross-border insurance processing.
Private Clinics command the current volume leadership, though Medical Tourism is climbing the fastest as Malaga and Marbella operators establish direct Northern European insurer billing relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Spanish autonomous communities diverge sharply between metropolitan aesthetic demand and medical tourism corridors, with Madrid and Barcelona patients prioritizing minimally invasive maintenance protocols while Costa del Sol visitors seek discrete surgical recovery environments.
Madrid
Spain's capital concentrates the highest density of board-certified plastic surgeons and accredited private clinics, with women aged twenty-five to forty-five driving breast augmentation and body contouring volumes. The Ministry of Health's tightened advertising restrictions eliminate price-based marketing channels, forcing operators toward educational content strategies. EGOS Group leverages its Madrid clinic network to secure talent through dedicated fellowship partnerships with Spanish medical schools.
Catalonia
Barcelona anchors Catalonia's aesthetic medicine cluster, where injectable filler regimens capture younger demographics through dedicated aesthetic nursing staff and repeat-visit maintenance protocols. The General Medical Council enforces practitioner certification standards that limit market entry for independent operators. Premium Barcelona facilities respond to advertising bans by investing in organic search visibility and specialist authority content marketing.
Andalusia
Malaga and Marbella facilities exploit year-round climate advantages to attract Northern European medical tourists seeking EU-recognized credentialing standards and simplified cross-border insurance processing. Quirónsalud Marbella differentiates through its Costa del Sol hub positioning, drawing patients from Germany, Scandinavia, and the United Kingdom. Regional health authority inspections for private clinic licensing extend six to nine months, delaying competitor entry.
Basque Country
Bilbao and San Sebastián clinics serve a smaller but affluent patient base with preference for premium reconstructive and facial aesthetic procedures. Hospital Ruber Internacional competes for specialists against public hospital salary packages in this northern corridor. The EU Medical Device Regulation's reclassification of implantable aesthetic devices raises documentation barriers that favor established operators with dedicated regulatory affairs teams.
Valencia
The Mediterranean coastal city captures emerging demand from domestic patients priced out of Madrid and Barcelona premium tiers, with mid-market clinics expanding laser surgery and energy-based device platforms. Valencia's private operators face anesthesia specialist scarcity as Spain's public hospital system captures the majority of accredited anesthesiologists, forcing reliance on costly locum arrangements.
Spain Cosmetic Surgery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with clinic networks commanding patient flows through scale advantages in talent acquisition and regulatory compliance capacity. The competitive terrain splits between Madrid-Barcelona metropolitan operators and Costa del Sol medical tourism specialists, each deploying distinct positioning around convenience versus discretion. Two strategic archetypes dominate: vertically integrated clinic networks with captive training pipelines, and premium standalone facilities anchored to reconstructive reputation. Consolidation pressure intensifies through regional health authority licensing delays and advertising restriction compliance costs that disadvantage independent operators.
Among Madrid-based integrated operators, EGOS Group and Hospital Ruber Internacional occupy positions exemplifying the network archetype, with the former leveraging dedicated fellowship partnerships to insulate against public sector salary competition. On the medical tourism vector, Quirónsalud Marbella represents the geographic specialization archetype, anchoring premium capacity in the Costa del Sol corridor. Aurea Clinic and ANDSURGEONS Clinic sit within the metropolitan specialist tier, competing for patient acquisition through digital-native marketing capabilities and minimally invasive technology deployment.
| Leading Market Players |
|---|
| Clinica Granado Tiagonce |
| Aurea Clinic |
| EGOS Group |
| ANDSURGEONS Clinic |
| Hospital Ruber Internacional |
| Centro Médico Teknon |
| Quirónsalud Marbella |
| Centre Quirurgic Maresme |
| Clínica Planas |
| Others |
Pricing and Supply Chain Analysis
Nine-to-twelve-month procurement lead times for EU MDR-compliant silicone implants concentrate pricing power among established Madrid-Barcelona clinic networks while compressing margins for independent operators unable to secure volume commitments with the three dominant EU-based suppliers.
Pricing Analysis
Long-term offtake agreements dominate procurement for high-grade silicone implants, locking in Madrid premium clinics against spot-market volatility while mid-tier Barcelona operators absorb euro-denominated input swings. Three-tier pricing structure across premium, standard, and economy levels separates EGOS Group's fellowship-trained specialist premium from Valencia's laser-surgery mid-market and Costa del Sol's medical tourism economy tiers. Price differentiation hinges on anesthesia specialist certification and overnight facility accreditation. Cost compression in the economy tier intensifies because locum anesthesiologist arrangements erode margins on lower-complexity procedures. Medical tourists from Northern Europe exhibit lowest price sensitivity; domestic patients in Valencia and peripheral markets show highest.
Supply Chain Analysis
Germany, France, and the Netherlands anchor high-grade silicone implant manufacturing for Spanish cosmetic surgery, with regulatory documentation clustering among established EU notified bodies. Raw material dependencies span medical-grade silicone elastomers, hyaluronic acid precursors, and radiofrequency device components. Single-source vulnerability concentrates in EU MDR technical file preparation capacity, where only a handful of specialized consultancies serve Iberian clinic networks. Distribution runs through direct manufacturer-to-clinic relationships for implants, with energy-based devices flowing through Madrid-based medical equipment distributors holding exclusive Spanish territorial rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain cosmetic surgery market reads as high-growth disruption because minimally invasive technologies displace surgical revenue models faster than training pipelines can supply qualified practitioners, compressing the window for strategic repositioning.
For Market Incumbents: Compound network density through captive fellowship partnerships with Spanish medical schools before public hospital salary competition escalates further. Lock in long-term offtake agreements with the three EU-based implant suppliers to insulate against euro volatility and MDR documentation bottlenecks that threaten smaller competitors. For New Entrants and Emerging Players: Maintenance protocol monetization gaps in Andalusia's medical tourism corridor offer white-space entry where established chains under-serve repeat-visit filler regimens. Target Malaga's underdeveloped direct-billing relationships with Northern European insurers as the most penetrable geography, using telemedicine-enabled remote consultation workflows as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regional health authority licensing delays and advertising restriction compliance costs structurally disadvantage independent operators against scaled networks. Acquisition candidates cluster among Barcelona-based injectable specialists with dedicated aesthetic nursing staff and organic search visibility. Watch for EU MDR enforcement intensity against non-compliant implant documentation as the signal for accelerated market clearing.| Strategic Initiative | Industry Significance |
|---|---|
| Fellowship Pipeline Partnership | Secures captive specialist supply against public hospital salary competition in Madrid's concentrated market. |
| Direct Insurer Billing Infrastructure | Unlocks Northern European medical tourism flows through simplified cross-border payment processing in Costa del Sol. |
| MDR Compliance Documentation Investment | Raises barriers against independent operators lacking dedicated regulatory affairs teams. |
| Injectable Filler Maintenance Protocol | Captures recurring revenue streams that surgical-only practices cannot replicate. |
| Telemedicine Platform Integration | Responds to younger demographic expectations for remote consultation workflows. |
Research Methodology
Cross-validation between primary interviews with Spanish plastic surgeons, clinic operations directors, and regional health authority inspectors and secondary validation through EU Medical Device Regulation filings, Spanish Ministry of Health licensing databases, and General Medical Council certification records anchors the qualitative findings. Bottom-up procedure volume estimates from Madrid, Barcelona, and Costa del Sol clinic networks triangulate against top-down market sizing from medical device import data and private healthcare expenditure trends.
Sensitivity analysis around anesthesia specialist availability, euro-denominated implant procurement costs, and Northern European medical tourism demand elasticity shapes the analytical framework across the projection horizon. Segmentation dimensions span procedure type, technology platform, end-user demographic, and service delivery model. CAGRs derive from regression analysis against aging population projections, disposable income trends, and minimally invasive technology adoption curves. Forecast inputs incorporate EU MDR implementation timelines and Spanish advertising restriction enforcement intensity.
Material uncertainties — regulatory enforcement variability, cross-border insurance policy shifts, and training program enrollment stagnation — sit outside the modeled envelope. Forecasts reflect assumptions about sustained Northern European medical tourism preference for Spanish facilities and stable public-private talent competition dynamics. Recalibration cycles align with material shifts in EU MDR notified body capacity and regional health authority inspection scheduling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market