
 Europe Compression Bandages Market | 2026-2036
Europe Compression Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Compression Bandages Market Intelligence
Poland's expanding medical device manufacturing base is reconfiguring supply chains for compression bandages across the continent. Mölnlycke Health Care AB leverages its extensive clinical research to command a premium in the wound care segment. Essity, through its BSN medical subsidiary, sustains a dominant market presence with a broad portfolio and strong distribution networks. Meanwhile, Paul Hartmann AG competes on product innovation, particularly in self-adhesive and cohesive bandages for specialized applications.
Compression bandages are specialized medical textiles designed to apply controlled pressure to a limb or body part. These products are engineered with specific elasticity and material compositions, such as cotton or synthetic fibers, to achieve therapeutic pressure levels for managing edema and improving venous return. Self-adhesive bandages are gaining share due to ease of use in non-clinical settings, supporting the shift towards home care. While wound care remains the largest application, the treatment of varicose veins represents a significant and steadily growing area of use.
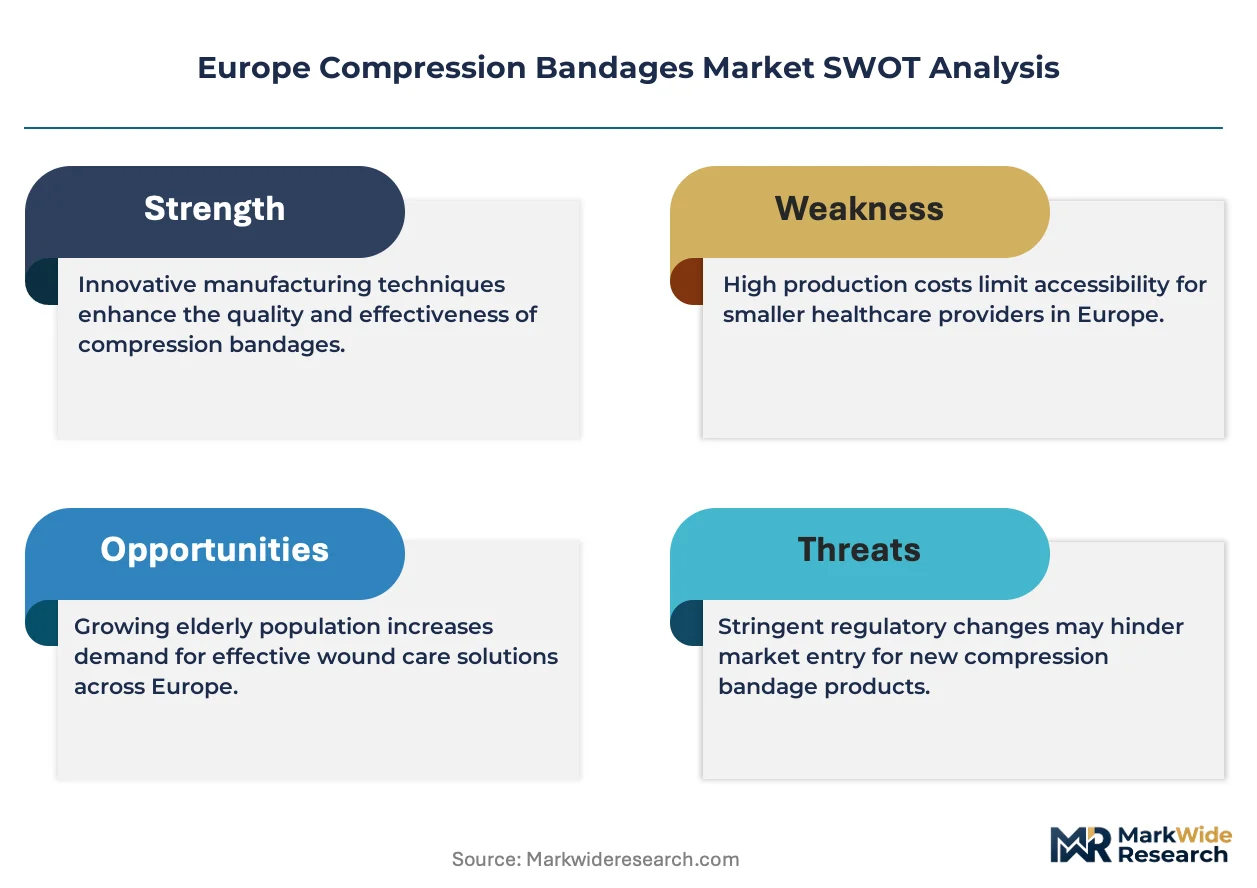
The European Union's Medical Device Regulation (MDR 2017/745) imposes stricter requirements for clinical evaluation and post-market surveillance on manufacturers. Compliance, demonstrated by CE marking, is non-negotiable for market access and influences product development timelines and costs. Navigating the complexities of material sourcing, especially for latex-free variants, will be critical for maintaining supply chain resilience and market position.
Market Dynamics
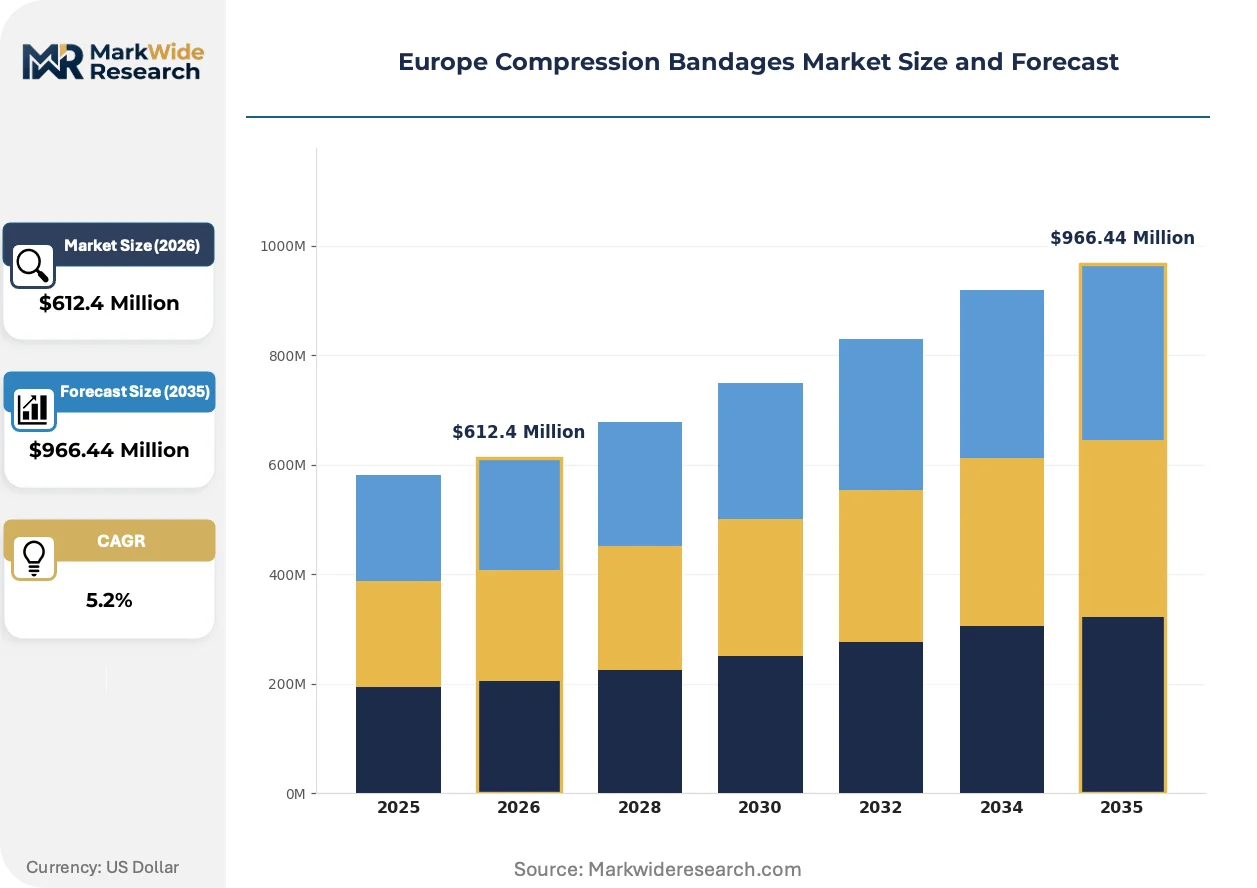
The European compression bandages market is fundamentally being reshaped by the stringent requirements of the Medical Device Regulation (MDR). This regulatory framework elevates the burden of proof for clinical efficacy and safety, influencing product design, manufacturing costs, and market access strategies across the continent.
Growth Catalysts
- Demographic Shift to Home Care:An aging population, particularly in Western European nations like Germany, is increasing the prevalence of chronic venous diseases, driving demand for compression bandages in more accessible home healthcare settings.
- Reimbursement Policies:Favorable reimbursement frameworks within national health systems, such as those in France and the UK, support patient access to prescribed compression therapies for conditions like venous leg ulcers and lymphedema.
- Manufacturing Hub Expansion:The growth of Poland's medical device manufacturing sector provides a geographically advantageous and cost-competitive production base, improving supply chain logistics for distributors throughout the European Union.
Market Restraints
- Raw Material Price Volatility:Fluctuation in the cost of specialized synthetic fibers and latex-free elastomers, critical for product performance and patient safety, creates margin pressure and complicates long-term cost planning for manufacturers.
- Regulatory Compliance Burden:The EU's MDR imposes significant costs and extended timelines for achieving and maintaining CE marking, creating a substantial barrier to entry for smaller innovators and non-European companies.
- Alternative Treatment Competition:The availability of alternative therapies, including intermittent pneumatic compression (IPC) devices and pharmacological treatments for venous insufficiency, presents a substitution threat in certain clinical scenarios.
Strategic Opportunities
- Eastern Europe Penetration:Markets in countries like Romania and the Czech Republic represent significant growth opportunities as their healthcare spending increases and clinical adoption of advanced wound care practices accelerates.
- Smart Bandage Development:Integrating micro-sensors into bandages to monitor pressure levels, moisture, or wound healing markers offers a path to value-added products that improve therapeutic outcomes and support telehealth models.
- Sports Medicine Applications:Expanding use in sports medicine for injury prevention, management of acute soft-tissue injuries, and post-activity recovery opens a new commercial channel beyond traditional clinical applications.
Industry Challenges
- Clinical Evidence Generation:Manufacturers face the operational challenge of designing and funding the extensive clinical investigations required to meet the heightened evidence standards under the EU MDR for both new and existing products. *Supply Chain Resilience: Securing a stable supply of compliant, high-quality raw materials, especially for latex-free variants, is a persistent operational hurdle amid global supply disruptions and evolving material regulations.
- Clinician and Patient Training:Ensuring correct application techniques, particularly for multi-layer systems and in home care settings, requires continuous investment in education to maximize therapeutic effectiveness and patient safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Compression Bandages Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $966.44 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Bandages, Self-Adhesive Bandages, Cohesive Bandages, Stockinette Bandages End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Material: Latex-Free, Cotton, Synthetic Fiber, Elastic Fiber Application: Wound Care, Sports Injuries, Varicose Veins, Post-Surgical Care |
| Companies Covered | Mölnlycke Health Care AB, B. Braun Melsungen, Essity (BSN medical GmbH), Cardinal Health, Inc., 3M Company, Paul Hartmann AG, Lohmann & Rauscher GmbH & Co. KG, ConvaTec, Smith & Nephew plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Compression Bandages Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards products that offer enhanced therapeutic functionality while simplifying use for both clinicians and patients. This convergence of material science and human-centric design is driven by regulatory pressures and the decentralization of care from hospitals to homes.
Advanced material science is a core focus, leading to the development of bandages with improved moisture management and sustained compression profiles. These products often incorporate synthetic elastomers and breathable fabrics to enhance patient comfort and wear-time. Adoption is strongest within specialized lymphedema and wound care centers across Europe. This innovation is hybridizing the function of a simple mechanical device with the properties of an advanced wound dressing, creating integrated therapeutic systems.
The European Union's Medical Device Regulation (MDR 2017/745) continues to be the most significant policy shift impacting the sector. It requires manufacturers to provide more robust clinical data and implement rigorous post-market surveillance systems to prove safety and performance. This regulation particularly affects bandages making specific therapeutic claims, forcing companies to re-evaluate their product portfolios and invest heavily in regulatory affairs to maintain their CE marking and market access.
A clear behavioral shift is occurring in product selection, prioritizing ease of application and reproducibility of results. This trend is disrupting the market for complex, technique-dependent systems, especially in channels like community nursing and patient self-care. Products with integrated visual indicators for correct tensioning are gaining share, a pattern most visible in the UK and Scandinavian countries where healthcare systems emphasize efficiency and standardized care protocols.
Europe Compression Bandages Market Segmentation
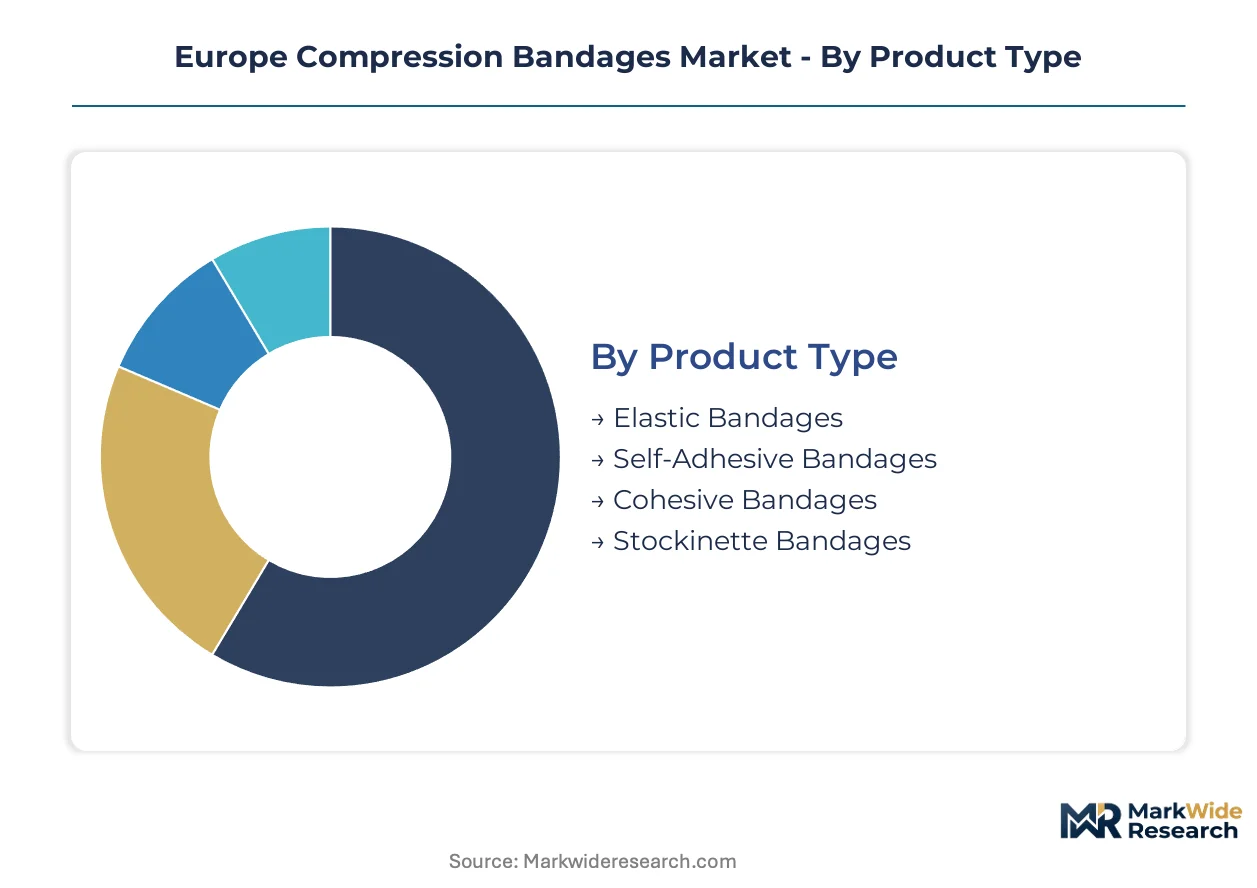
The European compression bandages market is highly stratified, reflecting diverse clinical needs, patient demographics, and evolving healthcare delivery models. Understanding these distinct segments is crucial for manufacturers to tailor product development, distribution strategies, and regulatory compliance efforts across the continent.
Product Type:
Product types exhibit varying turnover rates, with simpler elastic bandages often having shorter replacement cycles compared to more specialized self-adhesive or cohesive variants used for longer-term management.
- Elastic Bandages:These products provide adjustable compression through woven or knitted elastic materials, commonly used for support and mild edema management. Demand remains consistent in general first aid and basic post-injury care across Europe.
- Self-Adhesive Bandages:Engineered with a cohesive layer, these bandages adhere to themselves without clips or fasteners, simplifying application and removal. Demand is concentrating in home care settings, driven by an aging population requiring easier self-management of chronic conditions.
- Cohesive Bandages:Similar to self-adhesive types, cohesive bandages offer consistent, non-slip compression, often designed for specific anatomical contours or specialized applications. Their use for lymphedema management is expanding, particularly in specialized clinics in Germany.
- Stockinette Bandages:Tubular knitted bandages primarily used as a protective layer under other compression systems or for light support.
Elastic Bandages dominate the installed base for general support. Self-Adhesive Bandages are where expansion concentrates due to user convenience.
End User:
Different end-user segments exhibit varying procurement scales and budget sensitivities for compression therapies.
- Hospitals:These facilities represent high-volume purchasers for acute care, post-surgical recovery, and complex wound management. Demand is driven by established clinical protocols and the need for standardized products across various departments.
- Clinics:Including specialized wound care centers and outpatient facilities, clinics focus on specific treatments like venous leg ulcers and lymphedema, often prioritizing advanced or specialized bandage types. Demand for specialized solutions is high in these settings, particularly in France.
- Home Care:This segment includes patients managing chronic conditions in their own residences, often with support from community nurses. Demand is significantly increasing, driven by the demographic shift towards an aging population and the need for user-friendly products.
- Rehabilitation Centers:These centers utilize compression bandages for injury recovery, edema control, and post-operative swelling reduction following physical therapy.
Hospitals represent a foundational volume segment, while home care settings are increasingly influencing product design for ease of application.
Material:
Material composition directly impacts product performance, patient comfort, and regulatory compliance, particularly concerning allergenicity.
- Latex-Free:These bandages are manufactured without natural rubber latex to prevent allergic reactions, offering enhanced patient safety and broader applicability. Demand is influenced by stricter medical device regulations and a growing emphasis on hypoallergenic products across European healthcare systems.
- Cotton:Known for its breathability and absorbency, cotton is a traditional material used in many compression bandage designs, offering comfort for prolonged wear. Its use is prevalent in foundational bandage layers.
- Synthetic Fiber:Materials like nylon, polyester, and elastane provide durability, controlled elasticity, and moisture-wicking properties, enabling advanced compression profiles. Demand is increasing for products offering enhanced therapeutic outcomes and extended wear times.
- Elastic Fiber:Often blended with other materials, elastic fibers provide the necessary stretch and recoil for consistent, therapeutic compression.
Latex-Free materials are becoming a standard requirement, with synthetic fibers enabling advanced therapeutic features.
Application:
The range of clinical applications for compression bandages dictates specific product requirements and market maturity levels.
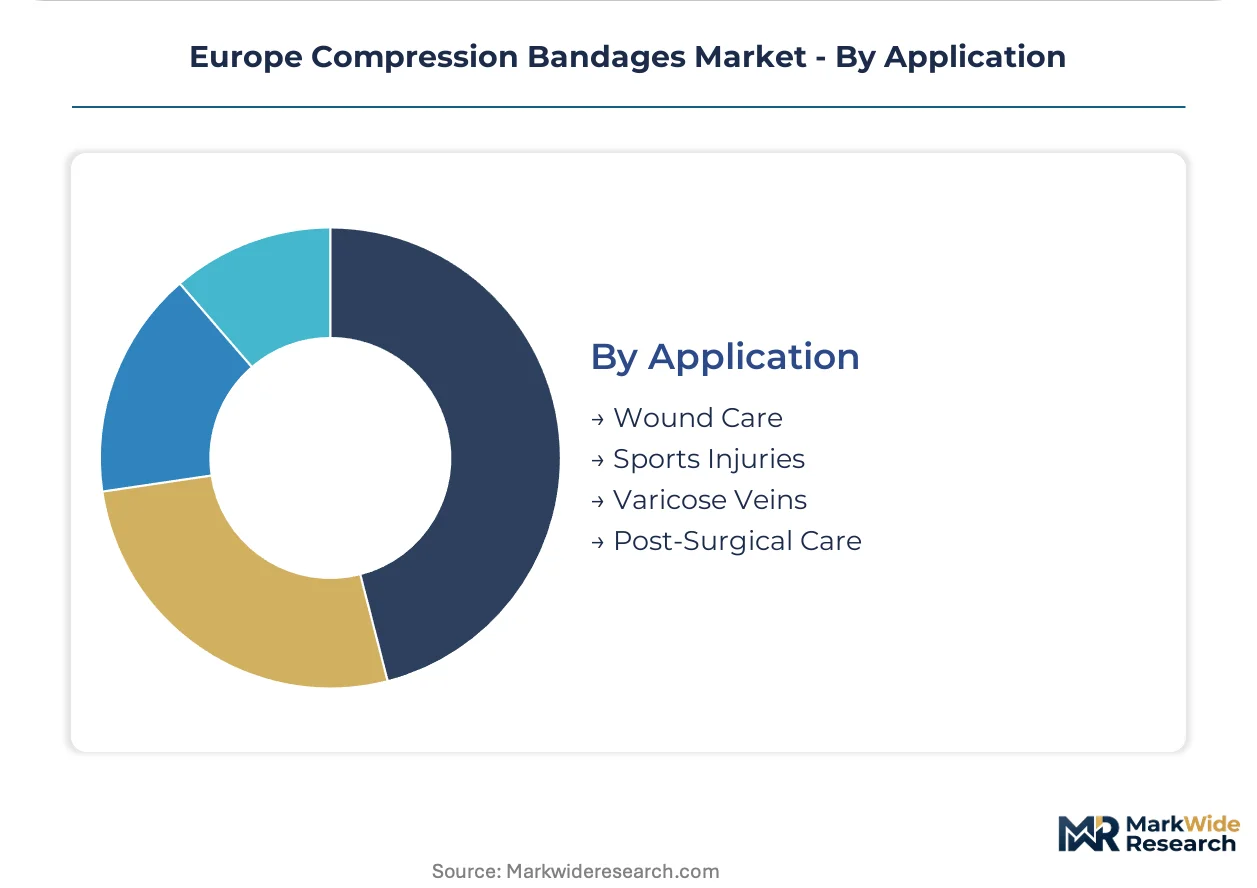
- Wound Care:This segment involves the management of chronic wounds, particularly venous leg ulcers, where compression bandages are essential for reducing edema and promoting healing. Demand is sustained by the high prevalence of chronic venous insufficiency among the elderly population in Europe.
- Sports Injuries:Compression bandages are used for acute soft-tissue injuries, sprains, strains, and post-activity recovery in athletic populations. This application is expanding due to increased awareness of injury prevention and faster recovery protocols.
- Varicose Veins:Compression therapy is a primary non-invasive treatment for varicose veins, helping improve venous return and alleviate symptoms. This represents a significant and steadily growing area of use, especially in countries with high prevalence like Germany.
- Post-Surgical Care:Bandages are applied after surgical procedures to control swelling, provide support, and prevent complications like deep vein thrombosis.
Wound Care remains the largest application segment, while Sports Injuries represent a significant growth opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for compression bandages varies across Europe, reflecting diverse healthcare priorities and demographic pressures. Western European nations emphasize advanced wound care, while Eastern European markets prioritize basic access and cost-effective solutions. This regional divergence shapes product demand and distribution strategies.
Germany
Germany's aging demographic significantly drives demand for compression bandages, particularly for chronic venous insufficiency management. Favorable reimbursement policies within the German healthcare system support broad patient access to prescribed compression therapies. The medical technology cluster in Bavaria actively develops innovative products, enhancing therapeutic functionality for various conditions.
France
French specialized clinics drive demand for advanced compression bandages, particularly for venous leg ulcers and lymphedema treatment. National health system frameworks ensure patient access to prescribed compression therapies, influencing product procurement. Clinics within the Paris metropolitan area frequently adopt specialized bandage types for complex wound management protocols.
United Kingdom
The United Kingdom's healthcare system emphasizes efficiency and standardized care protocols, driving demand for easy-to-apply compression solutions. National Health Service guidelines promote the use of cost-effective and user-friendly products in community settings. Community nursing services across England increasingly utilize products with integrated visual indicators for correct application.
Poland
Poland's expanding medical device manufacturing base reconfigures supply chains for compression bandages across Europe. Compliance with the EU Medical Device Regulation (MDR) ensures product quality and market access for Polish manufacturers. Manufacturing hubs in cities like Poznań are improving supply chain logistics for distributors throughout the European Union.
Czech Republic
Czech Republic markets represent growth opportunities as healthcare spending increases and clinical adoption accelerates. National health insurance systems are expanding coverage for advanced medical devices, including specialized compression therapies. Medical facilities in Prague are at the forefront of adopting advanced wound care practices and innovative bandage solutions.
Europe Compression Bandages Market Key Industry Players
Capability concentration sits with one tier, focusing on advanced material science and clinical evidence generation; scale advantage sits with another, leveraging broad distribution and manufacturing efficiency. The European compression bandages market exhibits a tiered structure, with established multinational corporations alongside specialized innovators. Strategic archetypes include premium wound care specialists, broad-portfolio providers, and innovation-driven niche players. Dominant competitive moves involve portfolio diversification and geographic expansion into Eastern European markets.
Within the premium wound care segment, Mölnlycke Health Care AB exemplifies a strategy based on extensive clinical research and value-based offerings. Essity, through its BSN medical subsidiary, represents a broad-portfolio provider, maintaining a dominant market presence with strong distribution networks across Europe. Paul Hartmann AG anchors the innovation-driven archetype, competing through product innovation, particularly in self-adhesive and cohesive bandages for specialized applications. These companies navigate stringent regulatory compliance under the EU MDR, which elevates standards for clinical evaluation and post-market surveillance, influencing product development timelines and costs.
| Leading Market Players |
|---|
| Mölnlycke Health Care AB |
| B. Braun Melsungen |
| Essity (BSN medical GmbH) |
| Cardinal Health, Inc. |
| 3M Company |
| Paul Hartmann AG |
| Lohmann & Rauscher GmbH & Co. KG |
| ConvaTec |
| Smith & Nephew plc |
| Others |
Cost & Logistics Intelligence
The Rhine-Main logistics corridor's cost dynamics directly influence compression bandage supply concentration and downstream price differentiation across Europe. These cost structures impact manufacturers' ability to maintain competitive pricing while navigating stringent regulatory requirements and raw material volatility.
Pricing Analysis
Geographic price spreads for compression bandages vary significantly across Europe, reflecting diverse market maturity and reimbursement policies. The pricing model often combines transactional per-unit sales with value-based differentiation for specialized products requiring extensive clinical evidence. Price differentiation stems from CE marking compliance, validated clinical efficacy, and advanced material quality. Pricing softness is emerging in basic elastic bandage segments due to increased competition and raw material cost fluctuations. Home care settings typically exhibit higher price sensitivity compared to specialized clinics or hospitals, which prioritize validated therapeutic outcomes.
Supply Chain Analysis
Contract manufacturing concentration in Poland holds significant capacity for European compression bandage production, improving logistical efficiencies. Geographic supply concentration primarily rests in Poland and Germany, leveraging established medical device ecosystems. Raw material dependencies center on specialized synthetic fibers, latex-free elastomers, and high-quality cotton. A structural risk involves raw material price volatility, particularly for petroleum-derived synthetics, which creates margin pressure. Distribution runs through a dual model, with direct sales to large hospital systems and specialized clinics, complemented by distributor networks serving pharmacies and home care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European compression bandages market is experiencing a shift in buyer power, driven by the expanding home care segment and its fragmented, yet volume-driven, procurement patterns.
For Market Incumbents:
Build a regulatory moat through sustained investment in EU MDR compliance and clinical evidence generation. Enhance product portfolios for specialized applications like lymphedema, leveraging advanced material science to maintain premium positioning. Strengthen distribution networks within the rapidly expanding home care segment, countering the threat from alternative therapies. Invest in R&D for smart bandage technology to differentiate offerings.
For New Entrants and Emerging Players:
Eastern European markets represent a significant underpenetration opportunity for compression bandage manufacturers. Target countries like Romania and the Czech Republic, where healthcare spending and clinical adoption of advanced wound care are accelerating. Focus on user-friendly, cost-effective solutions for the growing home care segment and specialized applications in sports medicine. A go-to-market angle emphasizing ease of application and patient comfort can drive initial traction.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core wound care assets. The long-term viability of this market is strong, anchored by an aging demographic and persistent chronic conditions. Identify acquisition archetypes in niche innovators with proprietary material science or regional manufacturers possessing robust distribution channels. Successful CE marking for novel products under the EU MDR is a critical signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Ensures continued market access and regulatory compliance for products under the stringent EU MDR. |
| Product Innovation in Smart Bandages | Enhances therapeutic outcomes and supports integration with emerging telehealth models and remote monitoring. |
| Home Care Channel Expansion | Addresses increasing demand from an aging population managing chronic conditions outside clinical settings. |
| Clinical Evidence Generation | Validates product efficacy and safety, supporting premium pricing and regulatory approvals across Europe. |
| Raw Material Supply Chain Diversification | Mitigates risks from price volatility and ensures consistent availability of compliant, high-quality materials. |
Research Approach
Initial hypotheses were tested against primary input from wound care specialists, hospital procurement managers, regulatory affairs leads, and home care providers, and refined through iterative feedback. Secondary validation drew from EU MDR guidelines, European Medical Device Information Database, national health statistics, and industry association reports. A robust bottom-up and top-down triangulation approach ensured comprehensive market sizing and segmentation.
Demand-supply-balance modeling underpins the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions included product type, end-user, material, application, and regional healthcare expenditure patterns. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected growth drivers. Key industry-specific forecast inputs included chronic venous insufficiency prevalence and evolving healthcare reimbursement policy changes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by alternative therapy providers or new material science innovators would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Quarterly review of clinical adoption rates and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
North America Wound Care Management Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Advanced Wound Care Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Wound Closure Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Wound Evacuators Market
Wound Care
Global Active Wound Care Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
Bioactive Wound Dressing Market