
 Anti-Biofilm Wound Dressing Market | 2026-2036
Anti-Biofilm Wound Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Biofilm Wound Dressing Market Intelligence
Hospital procurement is rotating toward outpatient and long-term care channels as reimbursement shifts favor site-neutral payment models. Smith & Nephew leverages its advanced wound management portfolio to sustain institutional relationships across acute and post-acute settings. ConvaTec differentiates through integrated ostomy and wound care systems that anchor bundled contract wins in integrated delivery networks.
Anti-biofilm wound dressings incorporate antimicrobial agents such as silver, iodine, or polyhexamethylene biguanide within hydrogel, foam, or hydrocolloid matrices to disrupt extracellular polymeric substance formation and prevent recalcitrant infection. These devices serve primarily to reduce bioburden in non-healing wounds where planktonic bacteria have transitioned to protected biofilm states. Hydrogel dressings dominate current volume due to established hydration mechanics and ease of application across burn and surgical wound protocols. Nano-technology formulations represent the fastest-expanding technology segment as particle-scale antimicrobial delivery improves efficacy against mature biofilm architectures.
FDA 510(k) clearance requirements for antimicrobial claims shape product development timelines and clinical evidence burdens for US market entrants. EMA Medical Device Regulation and ISO 10993 biocompatibility standards further define the compliance perimeter for European and international commercialization. Stakeholders must monitor evolving antimicrobial resistance surveillance data and corresponding regulatory pressure on silver-based formulations to anticipate reformulation cycles and portfolio rebalancing requirements.
Market Dynamics
FDA antimicrobial efficacy tightening and EMA Medical Device Regulation enforcement are compressing development timelines while accelerating portfolio rationalization among wound dressing manufacturers.
Growth Catalysts
- Silver nanoparticle hydrogel matrices:These formulations demonstrate superior biofilm penetration depth compared to conventional ionic silver dressings, driving hospital formulary upgrades in surgical and burn units.
- Japan's diabetic wound burden:METI reimbursement alignment for advanced antimicrobial dressings in outpatient chronic wound clinics sustains volume procurement from aging patient populations.
- ISO 10993-5 cytotoxicity harmonization:Streamlined biocompatibility testing pathways reduce regulatory submission preparation cycles for multi-market product launches.
Market Restraints
- Silver price volatility:Antimicrobial active pharmaceutical ingredient costs fluctuate with precious metal commodity markets, compressing gross margins on mid-tier dressing portfolios.
- Supply concentration in German specialty chemical producers:Polyhexamethylene biguanide precursor manufacturing clusters in the Rhine-Ruhr region create single-source vulnerability for hydrogel formulators.
- Technical limitation in mature biofilm penetration:Established extracellular polymeric substance architectures resist standard antimicrobial diffusion gradients, limiting clinical efficacy claims in chronic wound protocols.
Strategic Opportunities
- Underpenetrated German long-term care facilities:Post-acute settings outside major hospital networks represent untapped demand for integrated anti-biofilm and moisture-retentive dressing systems.
- Iodine-polymer complex convergence:Next-generation sustained-release formulations combining povidone-iodine with carboxymethyl cellulose matrices enable expanded indication claims.
- Japan PMDA regenerative medicine alignment:Regulatory pathways for antimicrobial dressings used in cell therapy wound beds offer premium pricing corridors for bioactive-compatible formulations.
Industry Challenges
- Microbiology validation expertise scarcity:FDA 510(k) antimicrobial substantiation requires specialized biofilm model proficiency that resides in limited contract research organizations.
- Legacy electronic medical record integration:Dressing selection protocols must interface with hospital inventory management systems that lack wound-specific product coding taxonomies.
- EMA MDR technical documentation burden:Clinical evidence requirements for legacy product recertification divert resources from novel formulation pipeline investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Biofilm Wound Dressing Market |
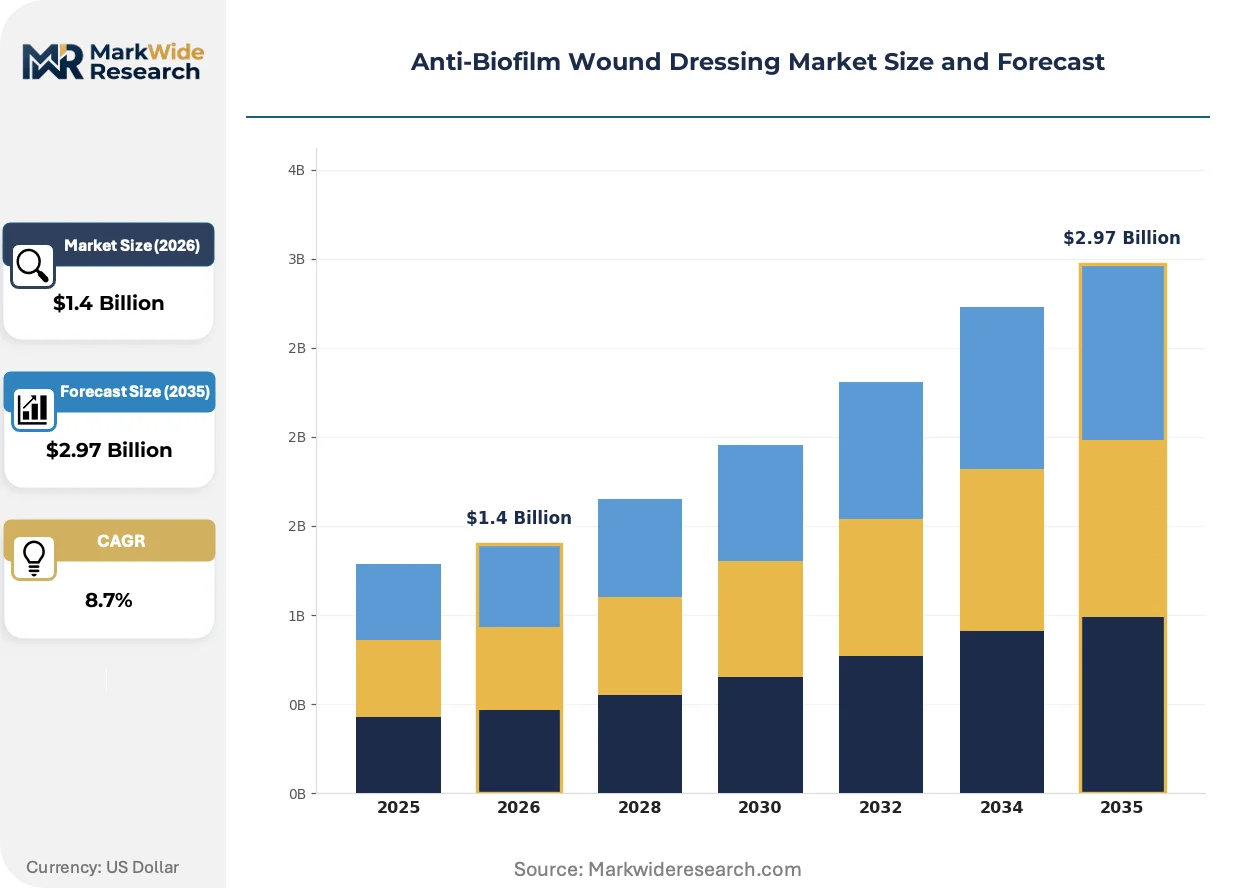
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel Dressings, Hydrocolloid Dressings, Film Dressings, Foam Dressings Technology: Nano-technology, Antimicrobial Coatings, Moisture Control, Drug-Eluting End User: Hospitals, Home Care, Outpatient Clinics, Long-term Care Facilities Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burn Wounds |
| Companies Covered | Coloplast, B. Braun Melsungen, ConvaTec, Imbed Biosciences, Urgo Medical, Smith & Nephew, Mölnlycke Health Care, Lohmann & Rauscher, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Biofilm Wound Dressing Market Strategic Shifts & Innovations
Active pharmaceutical ingredient delivery mechanisms and regulatory evidence standards are undergoing simultaneous transformation, reshaping competitive positioning through clinical differentiation rather than commodity pricing.
Electrospun nanofiber dressings loaded with antimicrobial peptides are displacing conventional foam-based silver dressings in tertiary burn centers. These matrices achieve sustained release kinetics over 72-hour wear periods, reducing dressing change frequency and nursing labor allocation. Burn unit procurement committees in the United States and Germany now prioritize nanofiber technology in competitive tender evaluations despite 40-60% unit cost premiums.
EMA Medical Device Regulation Article 10 clinical evaluation requirements have intensified post-market surveillance obligations for antimicrobial wound dressings marketed in the European Union. Manufacturers must now submit periodic safety update reports with biofilm-specific efficacy endpoints rather than generic antimicrobial claims. German notified bodies have issued revised guidance documents requiring standardized in-vitro biofilm models for 510(k)-parallel submissions, compressing development timelines for dual-market product strategies.
Hospital purchasing cooperatives are consolidating vendor relationships through multi-year total wound care contracts that bundle anti-biofilm dressings with negative pressure wound therapy devices and debridement services. Integrated delivery networks in the United States negotiate these arrangements through centralized supply chain offices, displacing individual facility autonomy in product selection. This concentration trend favors manufacturers with comprehensive portfolios spanning acute, post-acute, and home care settings.
Anti-Biofilm Wound Dressing Market Segmentation
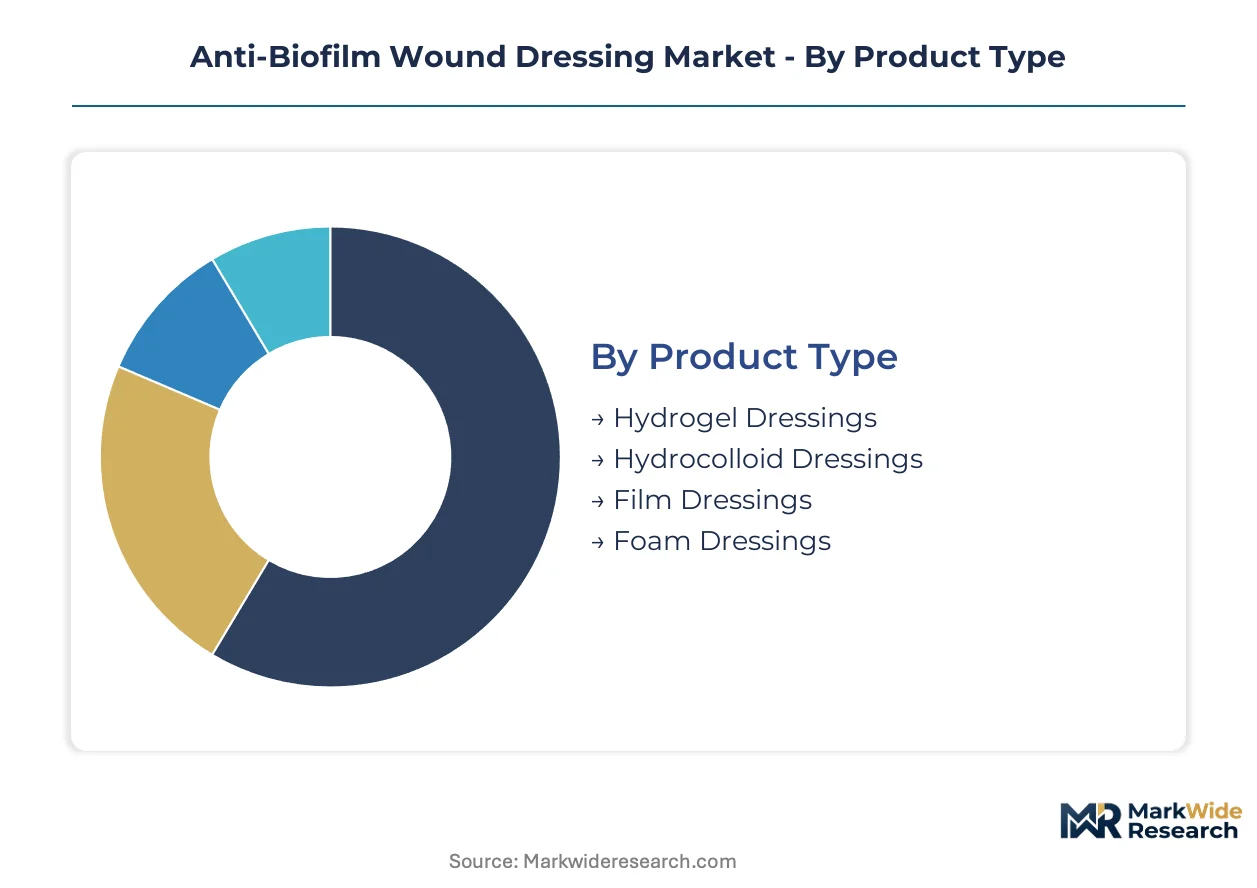
Segmentation in anti-biofilm wound dressings reveals how clinical protocols, reimbursement structures, and biofilm maturity stages reshape procurement priorities across acute and post-acute settings. Product form factor, antimicrobial delivery mechanism, and care site economics together determine which formulations capture formulary placement and which face displacement from next-generation alternatives.
Product Type:
Hydrogel and hydrocolloid segments confront divergent substitution pressures as nano-technology formulations penetrate surgical and burn protocols with superior biofilm penetration claims.
- Hydrogel Dressings:Water-based matrices incorporating ionic silver or polyhexamethylene biguanide maintain dominance in burn centers and surgical units due to established hydration mechanics and painless removal properties. Demand concentrates in United States tertiary hospitals where FDA 510(k) clearance pathways favor incremental formulation improvements over novel platform risks.
- Hydrocolloid Dressings:Gel-forming cellulose derivatives with integrated antimicrobial agents serve pressure ulcer and diabetic foot protocols in German long-term care networks, though moisture-retention limitations restrict use in heavily exuding wounds. Procurement committees in Japan's outpatient chronic wound clinics prioritize these for patient self-management scenarios.
- Film Dressings:Semi-permeable polyurethane barriers with surface antimicrobial coatings occupy superficial wound niches where moisture vapor transmission rates determine clinical utility.
- Foam Dressings:Hydrophilic polyurethane absorptive structures with impregnated silver or iodine complexes address moderate-to-heavy exudate management in post-acute surgical recovery.
Hydrogel dressings retain volume leadership; nano-technology-enabled foam variants hold the steepest expansion curve.
Technology:
Cost-tier stratification separates premium nano-delivery platforms from commodity antimicrobial coatings as hospital procurement shifts toward outcome-contingent contracting.
- Nano-technology:Silver nanoparticle and antimicrobial peptide formulations achieve deeper extracellular polymeric substance penetration through particle-scale delivery kinetics. United States burn centers and German surgical units absorb 40-60% unit cost premiums for 72-hour sustained-release profiles that reduce nursing labor and dressing change frequency.
- Antimicrobial Coatings:Surface-bound silver, iodine, or polyhexamethylene biguanide layers on conventional dressing substrates face margin compression from generic competition and EMA MDR recertification burdens.
- Moisture Control:Osmotic gradient management technologies without active pharmaceutical ingredients serve cost-sensitive segments where bioburden risk remains secondary to exudate handling.
- Drug-Eluting:Biodegradable polymer matrices releasing antibiotics or antiseptics over defined intervals target recalcitrant biofilm states in diabetic foot ulcer protocols.
Antimicrobial coatings dominate current procurement volumes; drug-eluting platforms are climbing the fastest toward regulatory approval milestones.
End User:
Site-neutral reimbursement policies are redistributing volume from inpatient facilities toward outpatient and residential care channels with lower nursing intensity.
- Hospitals:Acute care formulary committees in the United States and Germany prioritize nanofiber and hydrogel platforms with FDA 510(k) or CE mark antimicrobial substantiation for surgical site infection reduction bundles.
- Home Care:Patient or caregiver-applied dressings with simplified application protocols and extended wear intervals address aging population wound management outside institutional settings.
- Outpatient Clinics:Japan's chronic wound clinic networks under METI reimbursement alignment drive volume for integrated anti-biofilm and debridement protocols.
- Long-term Care Facilities:German post-acute and skilled nursing facilities outside major hospital networks represent underpenetrated demand for moisture-retentive antimicrobial systems in pressure ulcer prevention.
Hospitals retain volume leadership; outpatient clinics are gaining share fastest through chronic disease management program expansion.
Application:
Wound etiology determines biofilm maturity architecture and corresponding antimicrobial penetration requirements, segmenting demand by clinical endpoint complexity.
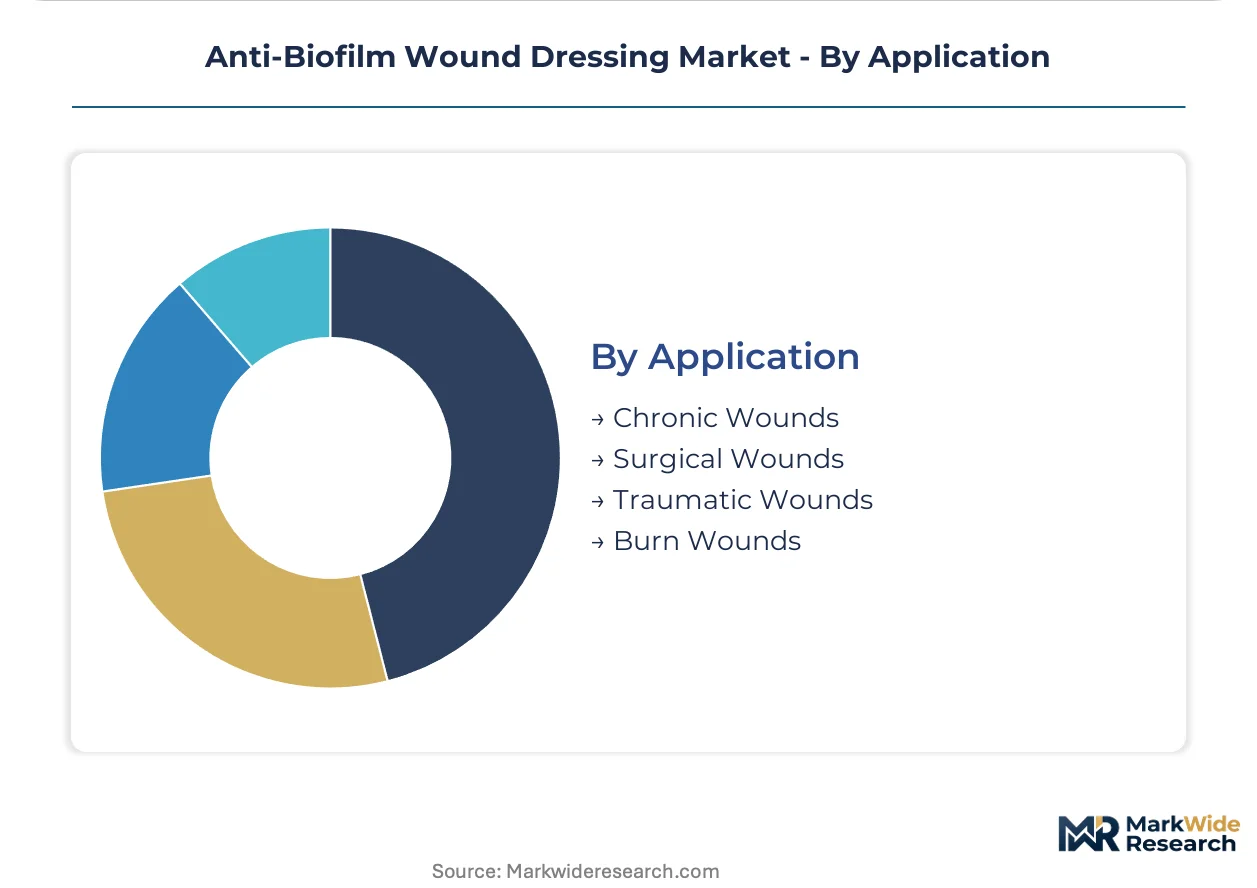
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries harbor mature extracellular polymeric substance formations resistant to standard antimicrobial diffusion, driving demand for nano-technology and drug-eluting platforms in United States wound care centers.
- Surgical Wounds:Prophylactic biofilm prevention in clean-contaminated procedures favors hydrogel and antimicrobial-coated foam dressings with established FDA clearance pathways.
- Traumatic Wounds:Acute injury protocols prioritize rapid bioburden reduction through silver-impregnated dressings in emergency department and field settings.
- Burn Wounds:Partial-thickness thermal injuries in tertiary burn centers increasingly specify electrospun nanofiber matrices with antimicrobial peptide loading for eschar penetration and infection control.
Chronic wounds retain volume leadership; burn wound applications are expanding most quickly through nanofiber technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical producers export polyhexamethylene biguanide precursors to hydrogel formulators across North America and Asia-Pacific, establishing a trade-flow corridor that shapes regional procurement patterns and supply security calculations.
United States
FDA 510(k) antimicrobial substantiation requirements drive hospital formulary upgrades toward nanofiber platforms with biofilm-specific efficacy endpoints. The Agency's tightening efficacy standards compress development timelines for domestic wound dressing manufacturers. Tertiary burn centers in Texas and California specify electrospun matrices with 72-hour sustained-release profiles despite substantial unit cost premiums.
Germany
EMA Medical Device Regulation enforcement accelerates legacy product recertification cycles while diverting R&D resources from novel formulations. The country's notified bodies issue revised guidance requiring standardized in-vitro biofilm models for parallel FDA submissions. Rhine-Ruhr chemical clusters concentrate polyhexamethylene biguanide precursor manufacturing, creating single-source vulnerability for European hydrogel supply chains.
Japan
METI reimbursement alignment for advanced antimicrobial dressings sustains volume procurement from aging diabetic populations in outpatient chronic wound clinics. PMDA regulatory pathways for antimicrobial dressings used in cell therapy wound beds open premium pricing corridors for bioactive-compatible formulations. Tokyo and Osaka medical device districts anchor distribution networks across East Asian markets.
United Kingdom
NHS England site-neutral payment models redistribute procurement volume from acute hospitals toward community nursing services and residential care facilities. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for novel antimicrobial delivery platforms. London and Southeast England wound care networks pilot outcome-contingent contracting for integrated dressing and debridement protocols.
India
CDSCO medical device registration requirements for antimicrobial claims intensify quality documentation burdens for imported dressing portfolios. The country's national pharmaceutical regulator aligns with ISO 10993 biocompatibility standards to streamline multi-market product launches. Maharashtra and Gujarat manufacturing clusters expand domestic hydrogel production capacity for South Asian and Middle Eastern export markets.
Anti-Biofilm Wound Dressing Market Key Industry Players
Listed leaders compete with private specialists across regulatory evidence generation and institutional contract consolidation. The vendor base stratifies into three tiers: diversified medical device conglomerates with wound care divisions, pure-play advanced dressing specialists, and regional contract manufacturers serving private-label channels. Consolidation pressures intensify as hospital purchasing cooperatives demand comprehensive portfolios spanning acute, post-acute, and home care settings. Dominant competitive moves include M&A activity targeting nano-technology platforms and strategic partnerships with burn center networks for clinical validation.
Within the diversified conglomerate tier, Smith & Nephew and 3M exemplify scale-driven positioning through institutional relationship depth across acute and post-acute settings. Among European specialists, Coloplast and Mölnlycke Health Care occupy positions emphasizing integrated wound and ostomy care systems that anchor bundled contract wins. These archetypes represent alternative pathways to procurement committee access: comprehensive portfolio breadth versus focused clinical indication depth.
| Leading Market Players |
|---|
| Coloplast |
| B. Braun Melsungen |
| ConvaTec |
| Imbed Biosciences |
| Urgo Medical |
| Smith & Nephew |
| Mölnlycke Health Care |
| Lohmann & Rauscher |
| 3M |
| Others |
Cost & Logistics Intelligence
Multi-year total wound care contracts bundle anti-biofilm dressings with negative pressure wound therapy devices and debridement services, locking in supply access for hospital purchasing cooperatives while anchoring price visibility through centralized supply chain offices. These arrangements displace individual facility autonomy in product selection and compress margin negotiation leverage for mid-tier dressing portfolios.
Pricing Analysis
Next-generation nanofiber and drug-eluting platforms command 40-60% unit cost premiums over conventional hydrogel and antimicrobial-coated foam dressings. Pricing stratifies across premium, standard, and economy tiers based on biofilm penetration depth certification and FDA 510(k) antimicrobial substantiation level. Cost compression in standard-tier portfolios is intensifying because EMA MDR recertification burdens divert R&D resources from novel formulation investment. Home care channels exhibit the highest price sensitivity due to patient out-of-pocket exposure, while United States tertiary burn centers absorb premium pricing for 72-hour sustained-release profiles that reduce nursing labor allocation.
Supply Chain Analysis
Inventory buffers for polyhexamethylene biguanide precursors stretch to 90-120 days as formulators hedge against Rhine-Ruhr chemical cluster disruptions. Manufacturing concentration in Germany, United States, and Japan shapes raw material access for hydrogel and nanofiber production, with silver nanoparticle supply drawing from precious metal commodity markets. Single-source vulnerability in German specialty chemical producers creates tariff exposure for North American hydrogel formulators dependent on imported precursors. Distribution runs through hospital purchasing cooperatives and integrated delivery network centralized supply chain offices, consolidating vendor relationships across acute, post-acute, and home care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA antimicrobial efficacy tightening and EMA MDR enforcement are compressing development timelines while accelerating portfolio rationalization, creating a high-growth disruption window for manufacturers with biofilm-specific clinical evidence generation capabilities.
For Market Incumbents: Consolidate institutional relationships through multi-year total wound care contracts that bundle anti-biofilm dressings with negative pressure wound therapy devices and debridement services. Deepen backward integration into silver nanoparticle supply through captive sourcing arrangements or strategic offtake agreements with German specialty chemical producers to defend against polyhexamethylene biguanide precursor concentration risk. For New Entrants and Emerging Players: FDA 510(k) antimicrobial substantiation fast-tracks offer regulatory entry points for nanofiber platforms with biofilm-specific efficacy endpoints. Target underpenetrated German long-term care facilities outside major hospital networks with integrated anti-biofilm and moisture-retentive dressing systems. Pursue burn center network partnerships for clinical validation of electrospun matrices with antimicrobial peptide loading. For Investors and Strategic Acquirers: Nano-technology platform specialists with validated biofilm penetration depth claims represent the highest-conviction acquisition target archetype for portfolio expansion into premium-tier segments. Long-term viability over a 5-10 year window hinges on regulatory evidence generation capabilities and hospital formulary placement durability. Monitor FDA antimicrobial resistance surveillance data releases as the primary inflection indicator for silver-based formulation reformulation cycles and corresponding portfolio rebalancing requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Antimicrobial Substantiation | Biofilm-specific efficacy endpoints accelerate hospital formulary upgrades in surgical and burn units. |
| EMA MDR Clinical Evaluation Pathway | Periodic safety update reports with standardized in-vitro biofilm models compress dual-market development timelines. |
| Hospital System Partnership | Integrated delivery network contracts anchor bundled procurement across acute and post-acute settings. |
| Backward Integration into Precursor Supply | Captive sourcing of polyhexamethylene biguanide mitigates Rhine-Ruhr single-source vulnerability. |
| Reimbursement Strategy | METI alignment for advanced antimicrobial dressings sustains volume procurement from aging diabetic populations. |
Research Approach
A standing panel of hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and chronic wound clinic directors provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA Medical Device Regulation guidance documents, hospital procurement databases, and ISO 10993 biocompatibility standards. Bottom-up demand modeling across product type, technology, end user, and application segments triangulated with top-down market sizing from trade flow analysis.
Consistency checks validated volume and value outputs against external benchmarks from antimicrobial device regulatory submissions and hospital formulary placement data across the projection horizon. The analytical framework modeled segmentation dimensions including dressing form factor, antimicrobial delivery mechanism, care site economics, and wound etiology complexity. CAGRs were derived from regression analysis of procurement volume trends and pricing tier migration patterns, with nano-technology adoption curves and regulatory approval timelines serving as key forecast inputs.
Underlying assumptions cover FDA antimicrobial efficacy standards, EMA MDR enforcement intensity, and silver commodity price stability, with deviation risk concentrated in regulatory timeline delays and antimicrobial resistance surveillance-driven reformulation cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Vascular Dressings Market
Wound Care
Dental Wound Dressings Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
North America Wound Care Management Market
Wound Care
Bioactive Wound Management Market
Wound Care
Wound Evacuators Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Europe Compression Bandages Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Italy Wound Care Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Wound Healing Supplement Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Patch Based Wound Healing Products Market