
 Bioadhesive Wound Care Market | 2026-2036
Bioadhesive Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Bioadhesive Wound Care Market Intelligence
Cross-linked polysaccharide hydrogel chemistry is reconfiguring how bioadhesive layers bond to moist wound beds without secondary fixation. Becton Dickinson leverages its surgical closure portfolio to anchor hospital formulary positioning across North American acute care networks. Ethicon competes through Johnson & Johnson Services, Inc.'s integrated sutures-to-sealants ecosystem, while Adhezion Biomedical specializes in cyanoacrylate-based topical skin adhesives for clean wound approximations.
Bioadhesive wound care comprises medical dressings and sealants engineered from natural polymers, synthetic polymers, or composite materials that adhere to tissue via molecular bonding rather than mechanical pressure, typically achieving tack strengths of 0.5–2.0 N/cm² and maintaining moisture vapor transmission rates between 2,000–8,000 g/m²/24h to support autolytic debridement. Hydrocolloid dressings dominate ambulatory revenue due to established reimbursement codes and extended wear times, while hydrogel dressings capture expanding home care volumes where cooling hydration soothes partial-thickness burns and donor sites. Film dressings occupy a mature position in IV site protection, though composite material formulations incorporating antimicrobial biochemical agents represent the fastest-margin segment as infection prevention protocols tighten.
FDA 510(k) premarket notification requirements govern bioadhesive device classifications in the United States, while the EU Medical Device Regulation (MDR) and CE marking mandate clinical evidence for absorbable sealants entering European markets. Japan's PMDA enforces Japan Industrial Standards (JIS) biocompatibility testing that delays foreign product entry but elevates quality benchmarks domestic manufacturers must meet. Stakeholders should monitor how post-market surveillance databases in each jurisdiction reshape liability exposure and design control documentation requirements.
Market Dynamics
Cross-linked polysaccharide hydrogel chemistry is compressing development timelines for bioadhesive dressings that bond to moist wound beds without mechanical fixation, forcing manufacturers to reconfigure R&D pipelines around molecular adhesion rather than traditional tape-based securing mechanisms.
Growth Catalysts
- Hospital formulary consolidation:Acute care networks in the United States are standardizing procurement around advanced dressings that reduce nursing time for chronic wound management. This concentrates volume among suppliers with integrated surgical closure portfolios.
- FDA 510(k) pathway efficiency:The premarket notification framework for novel biomaterials compresses regulatory review timelines compared to PMA routes. Developers leverage this to accelerate commercialization of next-generation sealants.
- Aging demographic surgical volumes:Japan's expanding elderly population generates sustained demand for post-operative wound closure solutions. PMDA biocompatibility benchmarks elevate product quality while extending market access for compliant manufacturers.
Market Restraints
- Raw material concentration risk:Medical-grade cyanoacrylate monomer supply concentrates among specialty chemical producers in Germany and Switzerland. Price volatility for these feedstocks compresses margin structures for finished adhesive manufacturers.
- EU MDR clinical evidence requirements:The Medical Device Regulation mandates extensive biocompatibility documentation for absorbable sealants entering European markets. This creates capital-intensive barriers for mid-scale developers lacking established clinical data repositories.
- Mechanical closure substitution:Traditional sutures and staples retain cost advantages in emerging markets with limited reimbursement infrastructure. Price-sensitive healthcare systems delay bioadhesive adoption despite superior patient outcomes.
Strategic Opportunities
- Home care channel expansion:Hydrogel dressings with extended wear times are penetrating direct-to-patient distribution models in Germany. Cooling hydration properties address partial-thickness burn management outside institutional settings.
- Antimicrobial composite formulations:Biochemical agent integration into film dressings addresses tightening infection prevention protocols in Japanese acute care facilities. This represents the fastest-margin segment as hospitals prioritize nosocomial reduction.
- Reimbursement code development:Established hydrocolloid dressing codes in the United States create template pathways for novel bioadhesive categories. Manufacturers who secure parallel coding capture ambulatory revenue streams.
Industry Challenges
- Biocompatibility testing capacity constraints:JIS-standard cytotoxicity assays require specialized laboratory infrastructure that concentrates in Osaka and Tokyo metropolitan clusters. Testing bottlenecks delay product launches for foreign entrants.
- Moisture vapor transmission calibration:Achieving consistent 2,000–8,000 g/m²/24h performance across production batches demands precision manufacturing equipment. Capital requirements for this capability exclude smaller contract manufacturers from premium segment supply.
- Post-market surveillance documentation:FDA MAUDE database reporting and EU vigilance system requirements impose ongoing compliance burdens. Design control documentation must anticipate retrospective regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioadhesive Wound Care Market |
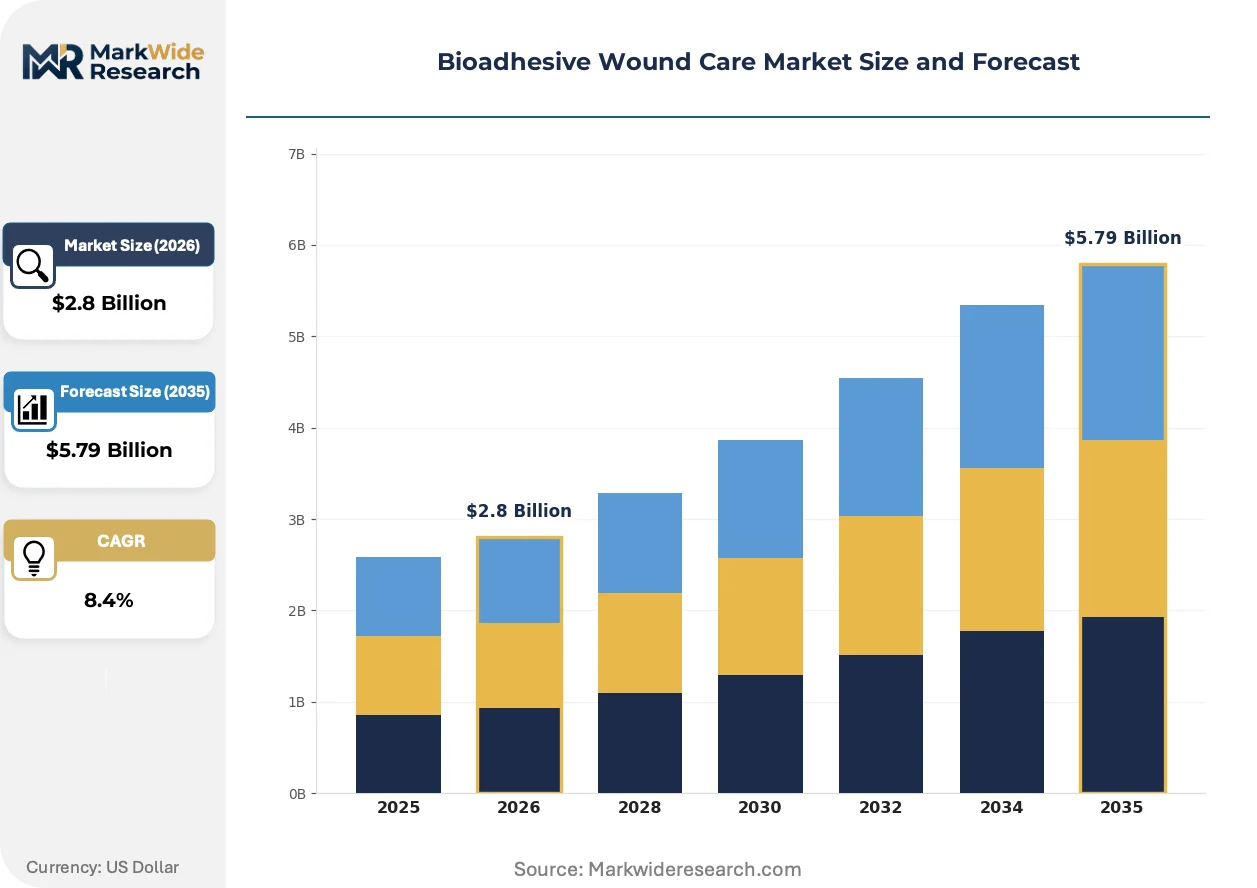
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Hydrogel Dressings, Film Dressings, Foam Dressings Application: Surgical Wounds, Chronic Wounds, Burns, Traumatic Wounds End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Material: Natural Polymers, Synthetic Polymers, Composite Materials, Biochemical Agents |
| Companies Covered | Becton Dickinson, Ethicon, Integra LifeSciences Corporation, Adhezion Biomedical, McKesson Corporation, Johnson & Johnson Services, Inc., Vivostat A/S, Henkel AG & Co. KGaA, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioadhesive Wound Care Market Strategic Shifts & Innovations
Active chemistry migration toward bioadhesive platforms is reconfiguring competitive positioning around molecular bonding performance rather than mechanical securing. This shift compresses differentiation timelines and elevates R&D intensity across formulation science.
Silicone-based gentle adhesion technology is migrating from infant skin applications to geriatric wound care where fragile epidermis demands atraumatic removal. Long-term care facilities in Japan are adopting these formulations at accelerated pace for pressure ulcer management. The technology is migrating from pediatric niches into mainstream chronic wound protocols, compressing the addressable market for traditional acrylic-based alternatives.
EU MDR post-market clinical follow-up requirements are reshaping evidence generation obligations for absorbable sealant manufacturers. The regulation mandates systematic collection of real-world performance data that extends beyond premarket trial endpoints. Hydrogel and hydrocolloid categories with established safety profiles face lighter surveillance burdens, while novel synthetic polymer entrants absorb disproportionate compliance costs.
Home health agencies are consolidating purchasing authority through group purchasing organizations that displace individual facility contracting. This concentration extracts volume discounts from adhesive dressing suppliers while demanding extended wear-time guarantees. The behavioral shift is most visible in United States Medicare-funded home care networks where reimbursement compression forces operational efficiency gains through standardized product formularies.
Bioadhesive Wound Care Market Segmentation
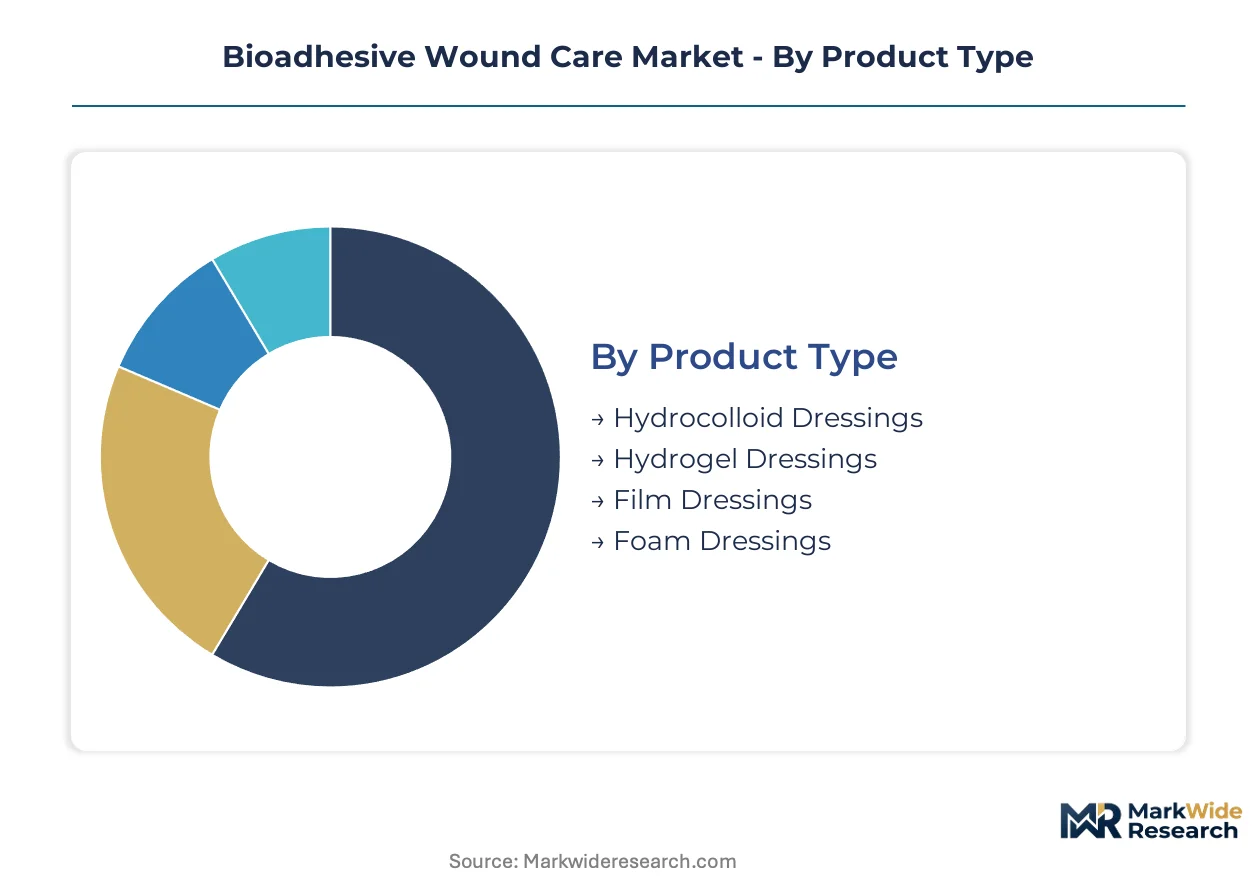
Bioadhesive wound care segmentation reveals how formulation chemistry, clinical setting, and patient acuity reshape procurement priorities across acute and ambulatory channels. Manufacturers calibrate R&D investment against reimbursement codes that favor extended-wear hydrocolloids in institutional settings while hydrogels penetrate direct-to-patient distribution.
Product Type:
Mature hydrocolloid technology anchors ambulatory revenue through established reimbursement infrastructure, while hydrogel chemistry represents the emerging growth vector as home care channels expand.
- Hydrocolloid Dressings:Gelatin, pectin, and carboxymethylcellulose formulations create occlusive environments that absorb exudate and form protective gels. Hospital procurement in the United States concentrates volume among suppliers with integrated surgical closure portfolios due to formulary consolidation pressures.
- Hydrogel Dressings:Cross-linked polyacrylamide or polyethylene oxide matrices deliver cooling hydration to partial-thickness burns and donor sites. German home health agencies are consolidating purchasing authority through group purchasing organizations that extract extended wear-time guarantees for direct-to-patient distribution.
- Film Dressings:Polyurethane semi-permeable membranes maintain moisture vapor transmission for IV site protection and superficial wounds.
- Foam Dressings:Hydrophilic polyurethane structures manage moderate-to-heavy exudate in pressure ulcer protocols.
Hydrocolloid Dressings retain volume leadership; Hydrogel Dressings hold the steepest expansion curve.
Application:
Surgical wound protocols generate the highest per-procedure value capture, while chronic wound management delivers recurring revenue streams through extended treatment durations.
- Surgical Wounds:Post-operative closure demands bioadhesive sealants with precise tack strength and biocompatibility profiles. Japan's PMDA enforces JIS biocompatibility testing that elevates quality benchmarks for compliant manufacturers serving aging surgical populations.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers require dressings that support autolytic debridement over months of therapy. United States Medicare-funded networks are standardizing procurement around advanced dressings that reduce nursing time.
- Burns:Partial-thickness thermal injuries favor hydrogel cooling properties and pain management characteristics.
- Traumatic Wounds:Emergency department applications prioritize rapid application and hemostatic performance.
Surgical Wounds command premium pricing; Chronic Wounds deliver the most predictable recurring revenue base.
End User:
Institutional procurement concentrates volume through formulary standardization, while home care fragmentation demands simplified application and patient self-management capabilities.
- Hospitals:Acute care networks leverage integrated surgical closure portfolios to anchor formulary positioning. FDA 510(k) pathway efficiency accelerates commercialization of next-generation sealants for operating room and wound care unit deployment.
- Home Care:Direct-to-patient distribution models require extended wear times and intuitive application. German hydrogel penetration is accelerating as cooling hydration properties address partial-thickness burn management outside institutional settings.
- Clinics:Outpatient wound centers balance cost constraints with clinical outcomes for moderate-complexity cases.
- Long-term Care Facilities:Pressure ulcer protocols in Japan are adopting silicone-based gentle adhesion technology for fragile geriatric epidermis.
Hospitals dominate absolute spending; Home Care channels are expanding most quickly as reimbursement shifts toward ambulatory settings.
Material:
Natural polymer supply chains face agricultural sourcing variability, while synthetic chemistry enables precise molecular engineering of adhesion and absorption properties.
- Natural Polymers:Chitosan, alginate, and hyaluronic acid derivatives offer inherent biocompatibility and biodegradability. EU MDR clinical evidence requirements create capital-intensive barriers for mid-scale developers lacking established safety data repositories.
- Synthetic Polymers:Cyanoacrylate and polyurethane formulations deliver tunable mechanical properties and manufacturing consistency. Medical-grade cyanoacrylate monomer supply concentrates among specialty chemical producers in Germany and Switzerland, compressing margin structures for finished adhesive manufacturers.
- Composite Materials:Hybrid formulations combine natural and synthetic phases for optimized performance profiles.
- Biochemical Agents:Antimicrobial integration addresses tightening infection prevention protocols in Japanese acute care facilities, representing the fastest-margin segment.
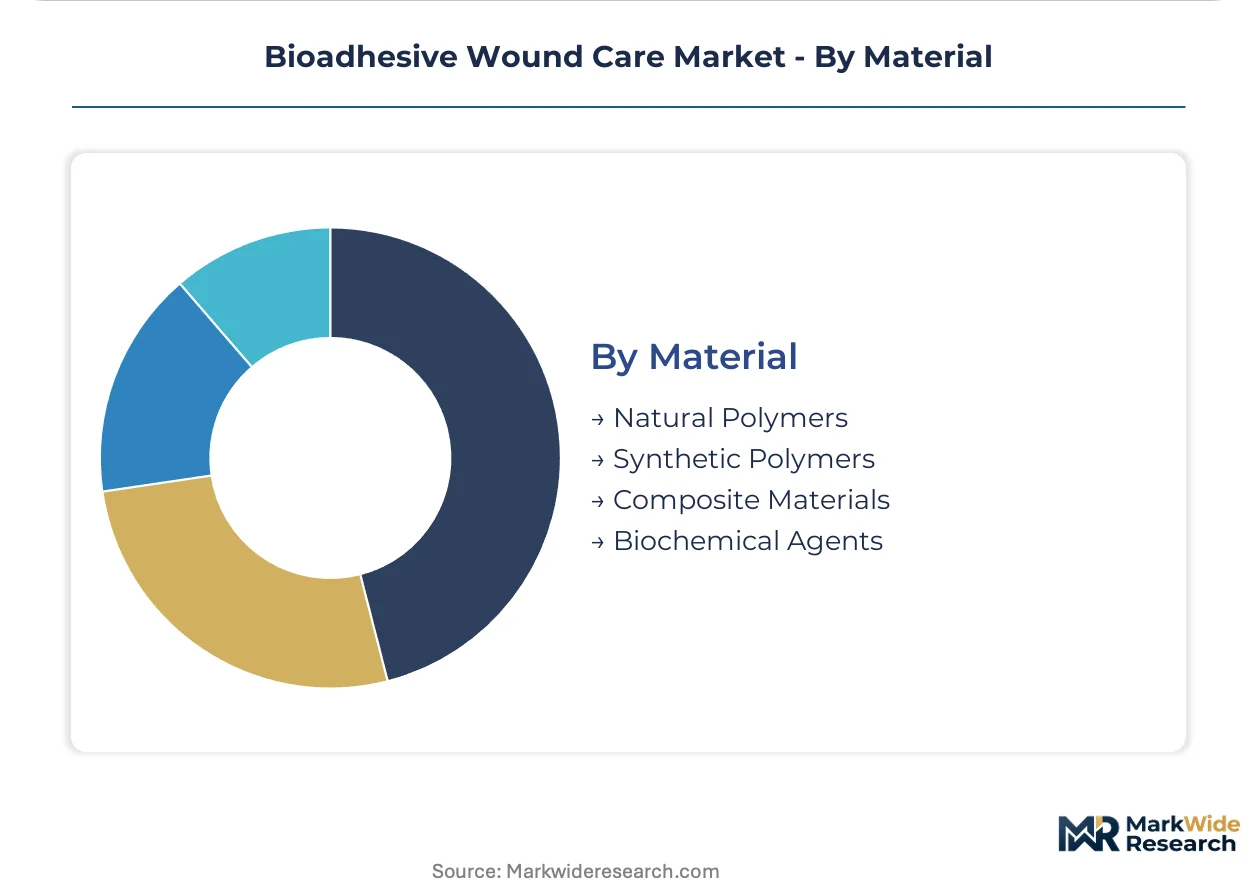
Synthetic Polymers anchor production scale; Biochemical Agents are climbing the fastest as hospitals prioritize nosocomial reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement networks and home health agencies concentrate purchasing authority across mature healthcare systems, with regulatory pathways and reimbursement infrastructure determining market access velocity in each geography.
United States
Acute care networks standardize formulary procurement around advanced dressings that reduce nursing labor for chronic wound management. FDA 510(k) premarket notification requirements compress review timelines for novel biomaterials compared to PMA routes. Greater Boston and Minneapolis-St. Paul metropolitan clusters host specialized biocompatibility testing laboratories that accelerate product validation for domestic manufacturers.
Germany
Home health agencies consolidate purchasing through group purchasing organizations that extract volume discounts and extended wear-time guarantees for hydrogel distribution. EU MDR clinical evidence requirements mandate extensive biocompatibility documentation for absorbable sealants entering European markets. Specialty chemical producers in Ludwigshafen and Basel-adjacent Swiss border zones concentrate medical-grade cyanoacrylate monomer supply for regional finished adhesive manufacturers.
Japan
Aging demographic expansion generates sustained surgical and diabetic wound patient volumes requiring post-operative closure solutions. PMDA enforces JIS biocompatibility testing standards that elevate quality benchmarks while delaying foreign product entry. Osaka and Tokyo metropolitan clusters concentrate specialized cytotoxicity assay infrastructure that creates testing bottlenecks for international entrants.
United Kingdom
NHS procurement frameworks prioritize cost-effective wound care solutions that balance clinical outcomes with budget constraints in community and acute settings. MHRA operates post-Brexit regulatory pathways that maintain alignment with EU MDR standards while introducing separate UKCA marking requirements. London and Southeast England host contract research organizations that support clinical evidence generation for novel dressing categories.
Switzerland
Precision chemical manufacturing capabilities support medical-grade adhesive feedstock production for European and Asian finished goods producers. Swissmedic maintains stringent quality benchmarks that domestic manufacturers leverage as competitive differentiation in export markets. Basel and Zurich industrial corridors concentrate specialty polymer chemistry expertise that feeds downstream bioadhesive formulation pipelines.
Bioadhesive Wound Care Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers, with acute care formulary consolidation favoring integrated surgical closure portfolios while home care fragmentation rewards simplified application designs. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with cross-category leverage, pure-play adhesive specialists with formulation depth, and distribution intermediaries with logistics scale. Dominant competitive moves include backward integration into medical-grade polymer supply and technology licensing arrangements that accelerate regulatory clearance timelines.
Among diversified medical technology conglomerates, Becton Dickinson and Johnson & Johnson Services, Inc. exemplify the channel-control archetype through integrated surgical closure portfolios that anchor hospital formulary positioning. Adhezion Biomedical occupies a specialist position within the cyanoacrylate-based topical adhesive segment, representing the pure-play formulation depth model that competes on molecular bonding performance rather than cross-category procurement leverage.
| Leading Market Players |
|---|
| Becton Dickinson |
| Ethicon |
| Integra LifeSciences Corporation |
| Adhezion Biomedical |
| McKesson Corporation |
| Johnson & Johnson Services, Inc. |
| Vivostat A/S |
| Henkel AG & Co. KGaA |
| Baxter International |
| Others |
Cost & Logistics Intelligence
Medical-grade cyanoacrylate monomer production concentrates among specialty chemical producers in Germany and Switzerland, anchoring margin capture upstream while finished adhesive manufacturers in the United States and Japan absorb feedstock volatility through formula adjustments and contract renegotiations.
Pricing Analysis
Cost-plus contracts with quarterly indexation to petrochemical feedstock benchmarks dominate procurement between monomer suppliers and finished goods manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared antimicrobial composites from basic hydrocolloid equivalents. Price erosion runs through the standard tier as Chinese contract manufacturers expand medical-grade polymer compounding capacity. Home health agencies exhibit highest price sensitivity due to Medicare reimbursement compression, while Japanese acute care networks prioritize JIS-compliant quality tiers with lower elasticity.
Supply Chain Analysis
Tariff exposure between Germany and Switzerland dominates supply chain risk planning for European finished goods producers dependent on Basel-adjacent monomer supply. Raw material sourcing draws from German cyanoacrylate specialists, Swiss precision polymer chemists, and Japanese biocompatibility testing laboratories. Single-source vulnerability concentrates in Osaka and Tokyo metropolitan cytotoxicity assay infrastructure. Distribution runs through hospital group purchasing organizations in the United States, German home health agency consortia, and Japanese medical device trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across home care channel configurations creates niche formation opportunities as direct-to-patient distribution displaces institutional procurement concentration.
For Market Incumbents: Build regulatory data moats through systematic EU MDR post-market clinical follow-up documentation that mid-scale competitors cannot replicate. Anchor hospital formulary positioning by integrating surgical closure portfolios with antimicrobial composite dressings. Capture backward integration into medical-grade chitosan supply from agricultural processors to defend margin structures against natural polymer price volatility. For New Entrants and Emerging Players: Establish a beachhead in German hydrogel home care distribution where group purchasing organization consolidation has not yet eliminated regional agency autonomy. Target silicone-based gentle adhesion technology for Japanese long-term care facility penetration. Pursue reimbursement code development alongside clinical evidence generation to secure ambulatory revenue streams before formulary standardization hardens. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play adhesive specialists lacking the capital depth for EU MDR compliance cost absorption. Five-to-ten year viability hinges on regulatory data repository depth rather than manufacturing scale alone. Monitor FDA MAUDE database reporting frequency for novel synthetic polymer entrants as an inflection indicator for liability exposure accumulation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Clinical Follow-Up Investment | Systematic real-world data collection satisfies vigilance requirements for absorbable sealant categories. |
| Antimicrobial Biochemical Agent Integration | FDA 510(k) pathway efficiency accelerates clearance for infection-prevention composite formulations. |
| Silicone-Based Gentle Adhesion Technology Licensing | Pediatric formulation expertise transfers to geriatric wound care applications in Japanese long-term care. |
| Home Care Channel Direct Distribution Partnership | Medicare-funded network consolidation demands extended wear-time guarantees from hydrogel suppliers. |
| JIS Biocompatibility Testing Infrastructure Expansion | Osaka and Tokyo laboratory capacity constraints delay foreign product entry for non-compliant manufacturers. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, EU MDR clinical evidence repositories, and Japanese PMDA approval records preceded structured interviews with hospital procurement managers, wound care clinicians, biomedical engineers, and group purchasing organization contract specialists. Secondary validation drew from hospital procurement databases, GPO contract filings, CMS Medicare reimbursement data, and customs trade records for medical-grade polymer feedstocks. Bottom-up demand modeling across product type, application, end user, and material segments triangulated against top-down healthcare expenditure allocation analysis.
Assumptions regarding FDA 510(k) pathway efficiency, EU MDR post-market surveillance burden evolution, and Japanese PMDA biocompatibility testing capacity constraints remained fixed across the projection horizon while raw material price volatility and reimbursement code expansion scenarios were stress-tested. Segmentation dimensions modeled included dressing chemistry, clinical setting acuity, patient self-management capability, and regional regulatory cluster. CAGRs derived from procedure volume forecasting combined with per-procedure product utilization intensity curves.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement compression rates, petrochemical feedstock pricing, or cross-border medical device tariff regimes would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Measurement Devices Market
Wound Care
US Wound Care Centers Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Wound Care Centers Market
Wound Care
US Wound Irrigation System Market
Wound Care
Liquid Bandages Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Wound Care Market
Wound Care
Bioactive Wound Care Market
Wound Care
France Wound Care Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Animal Wound Care Market
Wound Care
Wound Healing Market