
 Wood Chipper Machines Market | 2026-2036
Wood Chipper Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Chipper Machines Market Intelligence
Midwestern U.S. fabrication capacity is recalibrating around heavier-duty chassis and Tier 4 Final powertrains to serve municipal biomass contractors. Vermeer sustains dominance in horizontal-feed drum chippers through its dealer network density across Great Plains states. Morbark anchors the Great Lakes region with specialized whole-tree chipper lines engineered for pulpwood and fuel-chip specifications. Bandit Industries competes on customization depth, offering application-specific cutter configurations that extend machine versatility across forestry and waste streams.
Wood chipper machines are mechanical reduction systems employing high-torque drums or disc cutters to shred woody biomass into uniform chips ranging from coarse fuel-grade to fine landscaping mulch. These machines operate at feed rates between 50 and 1,000+ cubic meters per hour depending on rotor diameter and engine rating, serving primary functions in land clearing, arborist operations, and renewable fuel preprocessing. Gas-powered and PTO product types occupy the largest installed base due to their power-to-weight efficiency and compatibility with existing agricultural and forestry vehicle fleets. Compact and medium size classes are gaining traction fastest among landscaping contractors and municipal parks departments seeking maneuverability in urban and suburban job sites.
EPA Tier 4 Final and EU Stage V emissions frameworks are forcing engine recertification cycles that elevate product development costs and compress margin pools for smaller assemblers. OSHA machine guarding standards and CE marking requirements under the EU Machinery Directive shape export eligibility and aftermarket parts compatibility across North American and European channels. Stakeholders must monitor regulatory divergence between U.S. state-level renewable portfolio standards and EU biomass sustainability certification schemes to anticipate demand shifts in public-sector procurement.
Market Dynamics
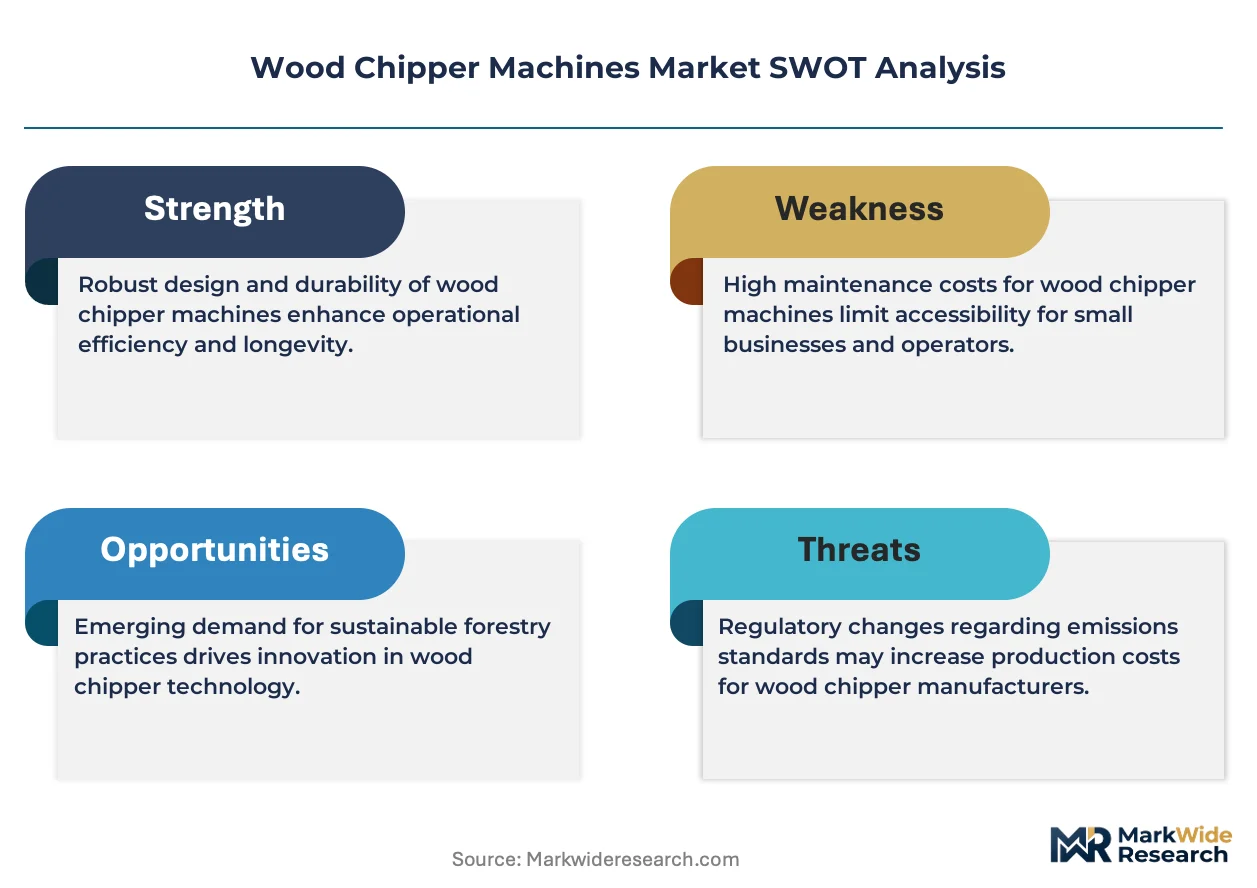
EPA Tier 4 Final and EU Stage V emissions mandates are compressing margin pools for smaller assemblers while forcing engine recertification cycles that elevate product development costs across the wood chipper machines market.
Growth Catalysts
- Municipal biomass collection mandates:Germany's renewable energy framework requires cities to divert green waste from landfills toward fuel-chip preprocessing, driving fleet purchases of PTO-compatible drum chippers by municipal contractors.
- Forestry mechanization:Rising labor costs and safety requirements across Scandinavian logging operations are accelerating replacement cycles for whole-tree disc chippers with higher feed-rate specifications.
- Urban green waste programs:North American metropolitan sustainability offices are expanding curbside collection services, creating sustained demand for compact gas-powered units maneuverable in suburban job sites.
Market Restraints
- Diesel engine cost inflation:Tier 4 Final aftertreatment systems and DEF infrastructure requirements have elevated powertrain costs, squeezing profitability for mid-size chassis manufacturers.
- Steel price volatility:Drum and disc cutter fabrication depends on high-grade alloy steel supplies concentrated in Chinese and Turkish mill networks, exposing assemblers to input cost swings.
- Electrification timeline uncertainty:Battery energy density limitations and charging infrastructure gaps constrain electric chipper viability for remote forestry applications, delaying product line transitions.
Strategic Opportunities
- India biomass power sector:State-level renewable purchase obligations and agricultural residue availability create openings for PTO tractor-mounted chippers serving rice husk and cotton stalk preprocessing.
- Rental channel expansion:Equipment-as-a-service platforms are penetrating landscaping contractor segments previously reliant on capital purchases, enabling fleet flexibility without ownership burden.
- EU sustainability certification convergence:ENplus and SBP pellet standards are harmonizing fuel-chip quality specifications, creating demand for precision screening systems integrated with chipper discharge conveyors.
Industry Challenges
- Certification timeline compression:CE marking under the EU Machinery Directive and OSHA guarding standard updates require concurrent engineering validation, straining smaller R&D teams.
- Service technician scarcity:Hydraulic system diagnostics and Tier 4 aftertreatment troubleshooting demand specialized training that vocational programs have not scaled to match fleet expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Chipper Machines Market |
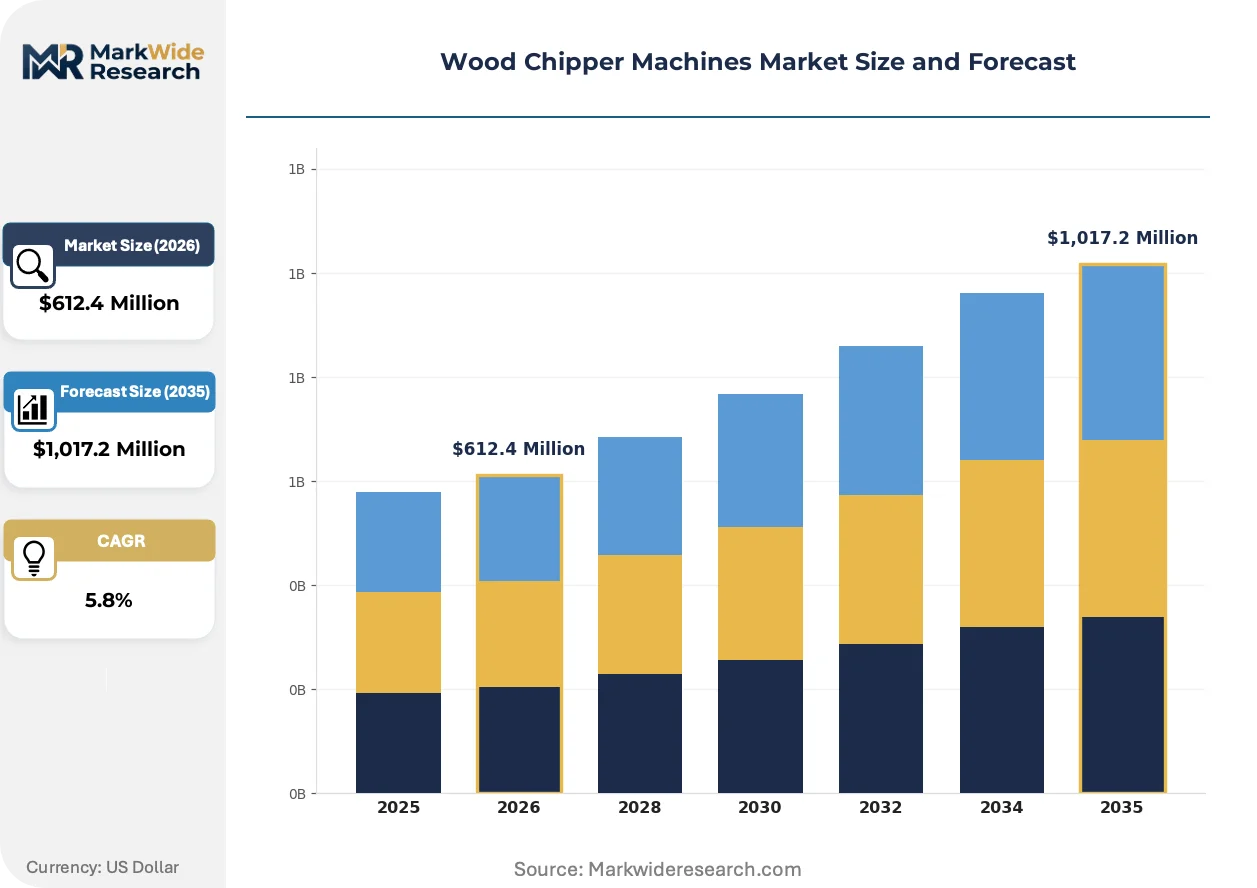
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas-Powered, Hydraulic, PTO Application: Forestry, Landscaping, Construction, Waste Management End User: Commercial, Residential, Government, Industrial Size: Compact, Medium, Large, Portable |
| Companies Covered | Terex, Vermeer, Morbark, Bandit Industries, Timberwolf, J.P. Carlton, Peterson, GreenMech, ALBACH Maschinenbau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Chipper Machines Market Strategic Shifts & Innovations
Electrification, emissions compliance architectures, and procurement model evolution are converging to reshape competitive positioning across wood chipper product lines and distribution channels.
Battery-electric drivetrains are electrifying compact chipper segments previously dominated by small-displacement gasoline engines. Landscaping contractors in urban California and German municipal parks departments are piloting lithium-ion units for noise-restricted job sites. This transition is electrifying dealer inventory strategies and compressing service revenue streams tied to combustion engine maintenance.
EU Stage V and EPA Tier 4 Final frameworks are forcing parallel engine recertification investments that favor larger manufacturers with dedicated compliance engineering teams. The industrial consequence is consolidation pressure on regional assemblers lacking capital for dual-certification programs. Horizontal-feed drum chippers above 200 horsepower face the steepest compliance cost escalation, pushing some European specialists toward partnership structures with Japanese engine suppliers.
Contracting officers at municipal biomass programs are consolidating vendor relationships through multi-year fleet agreements that bundle machines, preventive maintenance, and wear-part subscriptions. This pattern displaces transactional equipment purchasing through independent dealers in the Great Lakes and Pacific Northwest regions. The shift is most visible in Washington State and British Columbia, where public-sector procurement rules now favor outcome-based service contracts over capital asset ownership.
Wood Chipper Machines Market Segmentation
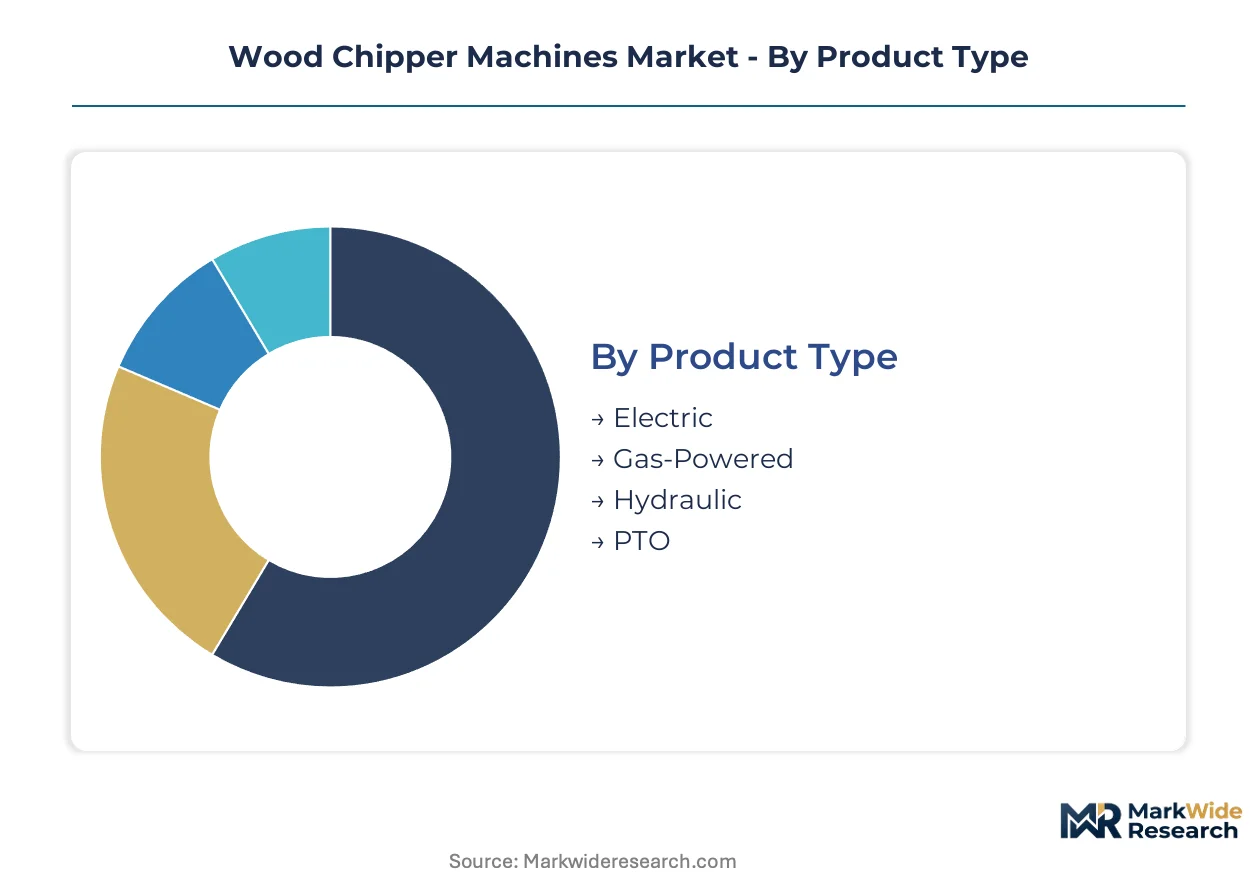
Wood chipper machines fragment across powertrain architectures, job site requirements, and operator sophistication levels. Each segmentation axis carries distinct certification burdens and margin profiles that shape vendor portfolio priorities.
Product Type:
EPA Tier 4 Final and EU Stage V compliance costs concentrate in diesel-derived architectures, while electric segments face UL and CE low-voltage directives. Gas-powered units navigate CARB certification in California and state-level emissions waivers elsewhere.
- Gas-Powered:Small-displacement gasoline engines power compact drum chippers favored by landscaping contractors for suburban tree maintenance. Demand clusters in North American metropolitan green waste programs where maneuverability outweighs throughput requirements. CARB compliance costs and ethanol fuel stability concerns constrain margin expansion.
- PTO:Tractor power-take-off configurations eliminate onboard engine certification burdens entirely, transferring compliance to agricultural OEM powertrains. German municipal biomass contractors favor PTO drum chippers under renewable energy diversion mandates. Hydraulic coupling standardization limits cross-brand compatibility.
- Electric:Battery-electric drivetrains with lithium-ion packs serve noise-restricted urban parks in California and German cities. UL 2580 and CE machinery directive compliance dominates product development spend.
- Hydraulic:Dedicated hydraulic power units deliver high-torque drum rotation for industrial preprocessing lines. Stationary installations in biomass power plants require IEEE electrical certification and pressure vessel inspection.
Leading the category by volume: Gas-Powered. Growing fastest: Electric.
Application:
Application segmentation tracks feedstock heterogeneity and chip specification stringency, with fuel-grade preprocessing commanding stricter durability standards than ornamental mulch production.
- Forestry:Whole-tree disc chippers process 50+ centimeter diameter trunks into uniform pulpwood chips. Scandinavian logging contractors specify feed rates exceeding 500 cubic meters hourly. OSHA guarding and EU Machinery Directive CE marking dominate safety engineering.
- Landscaping:Compact horizontal-feed drum chippers shred branches under 15 centimeters into decorative mulch. Urban contractors in Washington State and British Columbia prioritize noise attenuation and trailer mobility.
- Waste Management:Mixed construction debris and pallets require reinforced cutter housings and magnetic contamination removal. Material recovery facilities specify contamination tolerance below two percent by weight.
- Construction:Land clearing operations demand tracked undercarriage mobility and radiused discharge chutes for controlled chip placement. Dust suppression systems satisfy EPA NESHAP requirements.
Forestry commands the highest average machine value. Landscaping shows the steepest expansion trajectory in unit shipments.
End User:
Procurement sophistication varies sharply across end user categories, with government entities imposing prevailing wage and domestic content requirements absent in commercial channels.
- Commercial:Independent tree services and landscaping contractors purchase through dealer finance programs with seasonal payment structures. Fleet standardization on single brands reduces technician training overhead.
- Government:Municipal parks departments and state forestry agencies specify multi-year service contracts bundling machines, maintenance, and wear parts. Washington State procurement rules now favor outcome-based agreements over capital ownership.
- Industrial:Biomass power plants and pellet mills demand continuous-duty specifications with 8,000+ annual operating hours. ENplus and SBP certification requirements shape chip quality tolerances.
- Residential:Homeowner-grade electric and small gas units serve property maintenance under 50 annual operating hours. Big-box retail distribution dominates with minimal service attachment.
Commercial segment leads in absolute unit volume. Government procurement is climbing fastest as municipal biomass programs expand.
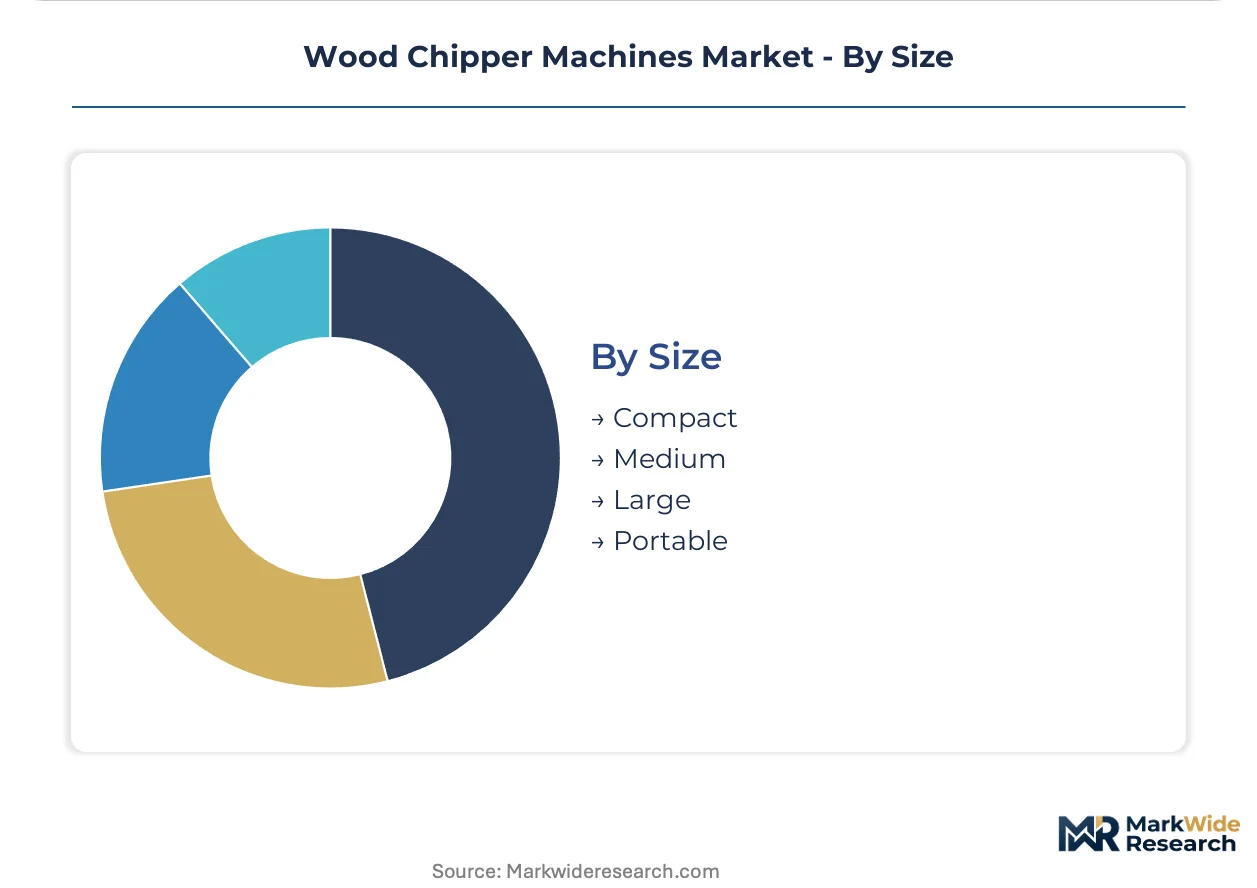
Size:
Physical envelope constraints determine transportation logistics and job site access, with compact segments optimizing for urban trailer towing and large units requiring lowboy haul permits.
- Compact:Drum diameters under 30 centimeters and gasoline powertrains enable single-axle trailer transport. Urban landscaping contractors in California cities favor electric variants for noise ordinances.
- Large:Stationary and self-propelled whole-tree systems with 75+ centimeter drum diameters serve pulpwood and fuel-chip preprocessing. Rail and barge loading dimensions constrain maximum envelope.
- Medium:Diesel-powered horizontal-feed drums balance throughput and maneuverability for municipal contractors. Tier 4 Final aftertreatment packaging challenges chassis integration.
- Portable:Track-mounted or hook-lift configurations enable rapid repositioning across logging sites. Ground pressure specifications determine soft-terrain eligibility.
Medium size dominates current revenue contribution. Compact units are gaining share fastest among urban contractor fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardwood timber belts in the Great Lakes basin and Scandinavian pine forests anchor wood chipper demand through pulpwood preprocessing and municipal biomass collection programs.
United States
Midwestern fabrication clusters around Iowa and Michigan supply Tier 4 Final drum chippers to municipal contractors. EPA emissions mandates compress margins for regional assemblers lacking dedicated compliance engineering. Chicago-Gary industrial corridor hosts service networks for whole-tree disc systems.
Germany
Baden-Württemberg and Bavaria dominate PTO-compatible drum chipper production for renewable energy diversion mandates. EU Stage V frameworks force engine recertification investments favoring larger manufacturers. Stuttgart engineering clusters specialize in precision cutter configurations for ENplus pellet specifications.
Sweden
Scandinavian logging operations accelerate replacement cycles for high-feed-rate disc chippers amid labor cost pressures. CE marking under the EU Machinery Directive shapes export eligibility for Baltic Sea shipping routes. Gothenburg port infrastructure supports fuel-chip export logistics to continental biomass plants.
Canada
British Columbia municipal procurement rules favor outcome-based service contracts over capital equipment ownership. Health Canada machinery safety standards align with OSHA guarding requirements for cross-border dealer networks. Vancouver sustainability offices expand urban green waste collection fleets.
India
Punjab and Haryana agricultural residue availability drives PTO tractor-mounted chipper demand for rice husk preprocessing. State-level renewable purchase obligations create openings for biomass power feedstock suppliers. Ludhiana manufacturing clusters adapt agricultural equipment fabrication capacity.
Wood Chipper Machines Market Key Industry Players
Global majors compete with regional champions across emissions compliance architectures and dealer network density. The market exhibits tiered consolidation with three to four dominant horizontal-feed specialists commanding premium positioning. Strategic archetypes include full-line forestry equipment conglomerates, dedicated chipper specialists, and agricultural PTO attachment fabricators. Competitive moves concentrate on Tier 4 Final engine recertification partnerships and municipal service contract bundling.
Among North American fabricators, Vermeer Corporation and Morbark, LLC occupy positions within the dedicated specialist tier, exemplifying engineering depth in horizontal-feed drum configurations. Bandit Industries, Inc. represents the customization-focused archetype, anchoring competitive positioning through application-specific cutter configurations. Terex Corporation sits within the diversified conglomerate category, leveraging cross-product service infrastructure.
| Leading Market Players |
|---|
| Terex |
| Vermeer |
| Morbark |
| Bandit Industries |
| Timberwolf |
| J.P. Carlton |
| Peterson |
| GreenMech |
| ALBACH Maschinenbau |
| Others |
Cost & Logistics Intelligence
Alloy steel drum fabrication costs flow from Chinese and Turkish mill networks through Tier 4 Final powertrain assemblers to municipal biomass contractors, with EPA and EU Stage V compliance investments stratifying final machine pricing across premium certified, standard certified, and economy non-certified tiers.
Pricing Analysis
Warranty and preventive maintenance bundling separates municipal service-contract pricing from transactional dealer sales to independent landscaping contractors. Price differentiation hinges on CE marking under the EU Machinery Directive and EPA Tier 4 Final certification status, with government procurement showing lowest price sensitivity due to outcome-based contract structures. Cost compression in mid-size diesel segments is intensifying because aftertreatment system packaging elevates chassis engineering spend. Commercial landscaping contractors exhibit highest price sensitivity, prioritizing maneuverability and seasonal financing flexibility over throughput specifications.
Supply Chain Analysis
Freight cost exposure from Great Lakes fabrication clusters to Pacific Northwest municipal buyers elevates landed costs for whole-tree disc systems relative to Midwest-sourced compact units. Supply concentrates in the United States, Germany, and Sweden for precision cutter engineering, with high-grade alloy steel for drums and discs drawing from East Asian mill networks. Single-source vulnerability in hydraulic coupling standardization limits cross-brand PTO compatibility. Distribution runs through dealer finance programs for commercial buyers and direct municipal procurement channels for government fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and EU Stage V recertification cycles have erected a cost-of-compliance barrier that favors capitalized manufacturers with dedicated emissions engineering teams, compressing margin pools for smaller assemblers unable to absorb dual-certification investments.
For Market Incumbents: To counter consolidation pressure from Japanese engine supplier partnerships, deepen captive supply of precision cutter configurations and expand municipal service-contract bundling across Great Lakes and Pacific Northwest procurement offices. Prioritize backward integration into hydraulic system diagnostics training to address technician scarcity constraining fleet expansion rates. For New Entrants and Emerging Players: Begin with PTO tractor-mounted configurations for Indian agricultural residue preprocessing, where state-level renewable purchase obligations create white-space demand absent Tier 4 Final certification burdens. Target Punjab and Haryana contractor segments through agricultural equipment dealer networks adapted from existing tractor distribution relationships. For Investors and Strategic Acquirers: Multi-year municipal fleet agreements bundling machines with wear-part subscriptions is the leading indicator that outcome-based procurement is displacing transactional equipment ownership. Position acquisition screening toward horizontal-feed drum specialists with CE marking validation and established German municipal biomass program relationships. Monitor Washington State and British Columbia procurement rule evolution as signal for North American contract-structure adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Tier 4 Final Engine Recertification Partnership | Dual EPA and EU Stage V validation accelerates market access for horizontal-feed drum configurations. |
| Municipal Service Contract Bundling | Outcome-based agreements in Washington State and British Columbia displace independent dealer transactional sales. |
| Precision Cutter Configuration Specialization | Application-specific engineering for ENplus pellet specifications captures German renewable energy diversion demand. |
| PTO Hydraulic Coupling Standardization | Cross-brand compatibility investment unlocks German municipal biomass contractor fleet standardization opportunities. |
| Technician Training Program Scaling | OSHA guarding and Tier 4 aftertreatment diagnostics capacity addresses service scarcity constraining fleet expansion. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews involving municipal procurement officers, forestry equipment dealership principals, biomass power plant maintenance directors, and Tier 4 Final engine supplier regulatory affairs leads. EPA certification databases, EU Machinery Directive CE marking registries, and German renewable energy framework documentation supplied validation benchmarks. Bottom-up unit shipment modeling across powertrain architectures converged with top-down value estimates derived from municipal budget appropriations and commercial fleet financing disclosures.
Segment-level granularity modeled product type, application, end user, and size class dimensions across the projection horizon, with powertrain certification tier and geographic procurement rule clusters treated as cross-cutting analytical layers. CAGR derivation integrated replacement cycle analysis for Scandinavian logging equipment, urban green waste program expansion trajectories in North American metropolitan sustainability offices, and Indian agricultural residue availability indices. Biomass power plant operating hour specifications and ENplus pellet quality tolerance standards informed industrial end-user demand elasticity assumptions.
Underlying measurement precision varies by segment; electric and hydraulic product types carry tighter precision than gas-powered categories given earlier-stage adoption curves. Forecasts reflect assumptions regarding emissions regulatory stability, alloy steel price volatility, and municipal procurement rule convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Power Rental Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Earthmover Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Crane Rail Market