
 Enclosed Belt Conveyors Market | 2026-2036
Enclosed Belt Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Enclosed Belt Conveyors Market Foresight
North American conveyor fabricators is expanding production footprints to serve rising grain export infrastructure investments. Ag Growth International leverages its integrated manufacturing platform across prairie provinces to anchor regional supply chains for enclosed belt systems. Buhler competes through technology leadership in dust-tight sealing architectures for food-grade applications. Continental AG sustains R&D intensity in polymer belt compounds engineered for abrasive mineral loads.
Enclosed belt conveyors are continuous bulk material handling systems featuring fully covered troughed or tubular belt paths that prevent spillage, contain dust emissions, and protect conveyed product from contamination; typical specifications include belt widths from 18 to 72 inches, operating speeds of 200-500 feet per minute, and enclosed housings fabricated from galvanized steel or aluminum. The equipment serves primarily in agriculture, mining, and food processing where environmental containment and product integrity carry operational and regulatory weight. Modular designs lead the product type landscape due to their field-adaptable configurations and reduced installation downtime at multi-site grain cooperatives. Heavy-duty trough configurations dominate margin pools in mining applications where abrasive ore streams demand reinforced carcass constructions and specialized wear liners. Electric drive technology anchors the installed base, though pneumatic actuation is gaining traction in food processing cleanrooms where oil-free operation and precise speed modulation matter.
The EPA enforces particulate emission limits under NESHAP Subpart DD that effectively mandate enclosed conveying at grain elevators above threshold capacities, while OSHA's grain handling facility standard imposes housekeeping and ignition source controls that enclosed architectures directly address. The EU Green Deal's industrial emissions directive is tightening belt conveyor dust containment requirements for cross-border bulk terminals. Stakeholders must monitor how evolving MSHA ventilation standards for underground mineral transport reshape specification priorities for flame-resistant belt compounds and sealed drive enclosures.
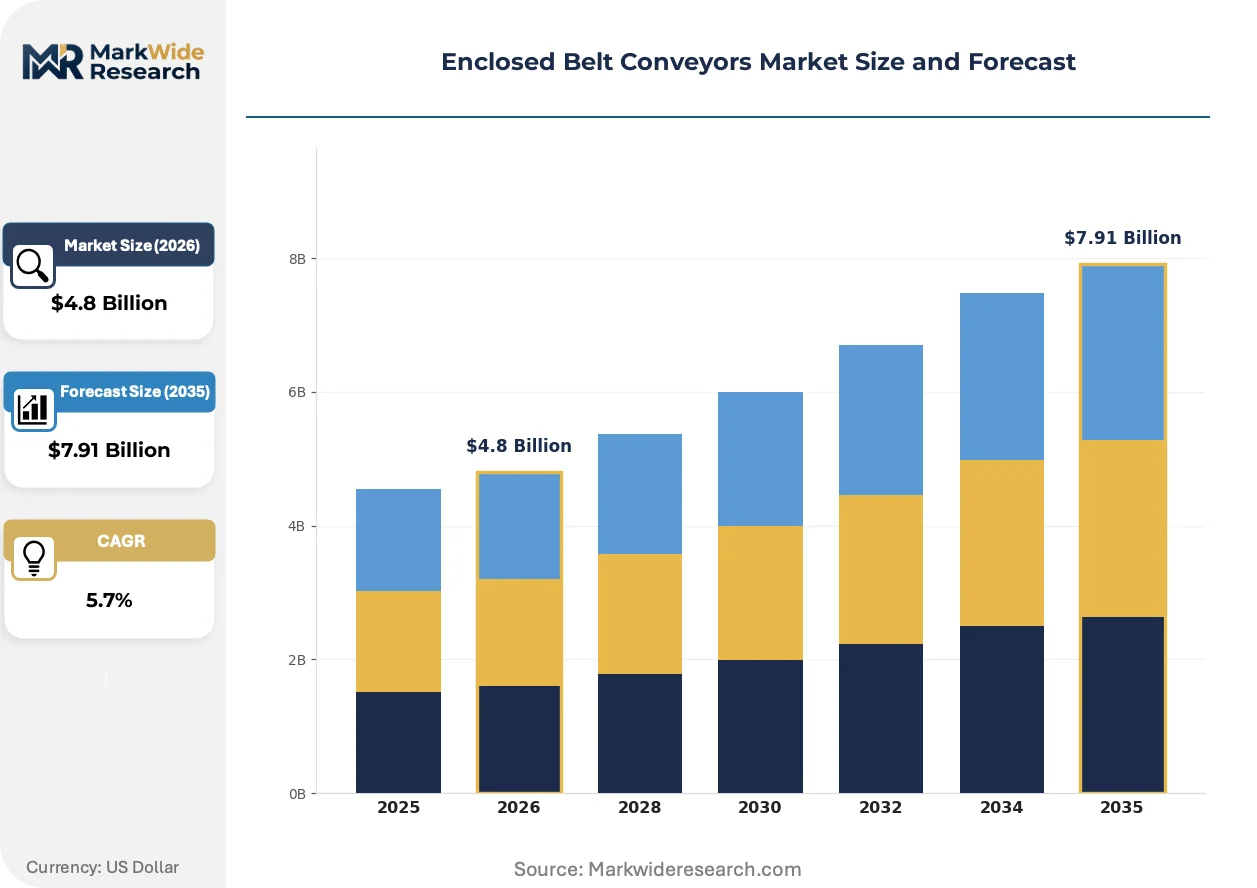
Market Dynamics
The EPA's NESHAP Subpart DD particulate emission mandates are forcing grain elevators above threshold capacities to replace open transfer points with fully sealed conveyor architectures, compressing procurement timelines and favoring suppliers with integrated fabrication platforms.
Growth Catalysts
- EPA NESHAP Subpart DD:The EPA enforces particulate emission limits that effectively mandate enclosed conveying at grain elevators above threshold capacities, creating immediate replacement demand across the US Midwest agricultural corridor.
- Modular field-adaptable designs:Multi-site grain cooperatives are specifying modular enclosed belt systems that reduce installation downtime and enable rapid reconfiguration across seasonal inbound and outbound material flows.
- EU Green Deal industrial emissions directive:Cross-border bulk terminals in Europe face tightening dust containment requirements, accelerating specification of sealed troughed architectures for mineral and agricultural exports.
Market Restraints
- Steel input cost volatility:Galvanized steel housing fabrication accounts for substantial equipment cost, and mills serving conveyor fabricators face pricing pressure from construction and automotive sector competition.
- Polymer compound supply concentration:Specialized abrasion-resistant belt carcass polymers rely on a limited supplier base concentrated in German and Japanese chemical producers, creating vulnerability to force majeure disruptions.
- Pneumatic conveying substitution:Food processing cleanrooms are evaluating pneumatic transfer for oil-free operation, though enclosed belt systems retain total cost advantages at longer transport distances.
Strategic Opportunities
- Underpenetrated Brazilian port infrastructure:Grain export terminal expansion along the Amazon corridor lacks mature enclosed conveyor supply chains, creating first-mover positioning for fabricators establishing regional assembly partnerships.
- MSHA ventilation standard evolution:Underground mineral transport regulation is reshaping specification priorities for flame-resistant belt compounds and sealed drive enclosures in Appalachian coal and western metal operations.
- Digital twin and predictive maintenance convergence:Sensor-integrated enclosed housings enable vibration monitoring and belt wear prediction, opening recurring revenue streams through condition-based service contracts.
Industry Challenges
- Welding and fabrication skill scarcity:Galvanized steel housing production requires certified pressure vessel welders, and rural manufacturing locations near agricultural demand centers face recruitment competition from oilfield and construction sectors.
- Legacy mechanical system integration:Brownfield grain elevator retrofits demand custom transition chutes and drive alignment engineering, extending project timelines and requiring site-specific design capabilities that strain standardized product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enclosed Belt Conveyors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Trough, Adjustable, Heavy-Duty Application: Mining, Agriculture, Food Processing, Waste Management Technology: Electric Drive, Pneumatic, Hydraulic, Manual End User: Manufacturers, Distributors, Contractors, Suppliers |
| Companies Covered | Ag Growth International, ContiTech AG, Kase Custom Conveyors, Buhler, Sweet Manufacturing, Continental AG, Bridgestone Corp., Goodyear Rubber Co., Fenner Dunlop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enclosed Belt Conveyors Market Shifts & Advancements
Sealed conveyor architectures are absorbing digital sensing layers and advanced polymer formulations that redefine performance benchmarks for dust containment and abrasive load durability across agricultural and mineral handling.
Advanced polymer belt compounds engineered with aramid fiber reinforcement are absorbing extreme abrasion from copper ore and phosphate rock streams. Mining operators in Arizona and Chile are specifying these formulations to extend belt life beyond 50,000 operating hours. The technology is absorbing margin pressure from competing wear liner strategies by eliminating secondary maintenance interventions.
REACH chemical registration requirements are restricting certain plasticizer chemistries in belt compounds sold into EU food-grade applications. Compounders serving enclosed conveyor manufacturers are reformulating migration-resistant alternatives that maintain flexibility at sub-zero temperatures. The regulatory shift is compressing certification timelines for suppliers lacking in-house polymer synthesis capabilities.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts. Large grain cooperatives in Iowa and Nebraska are separating predictive monitoring subscriptions from physical spare parts procurement, pressuring OEMs to demonstrate sensor data value independently. This purchasing pattern shift is most visible among multi-facility operators with centralized engineering staff capable of direct component sourcing.
Enclosed Belt Conveyors Market Segmentation
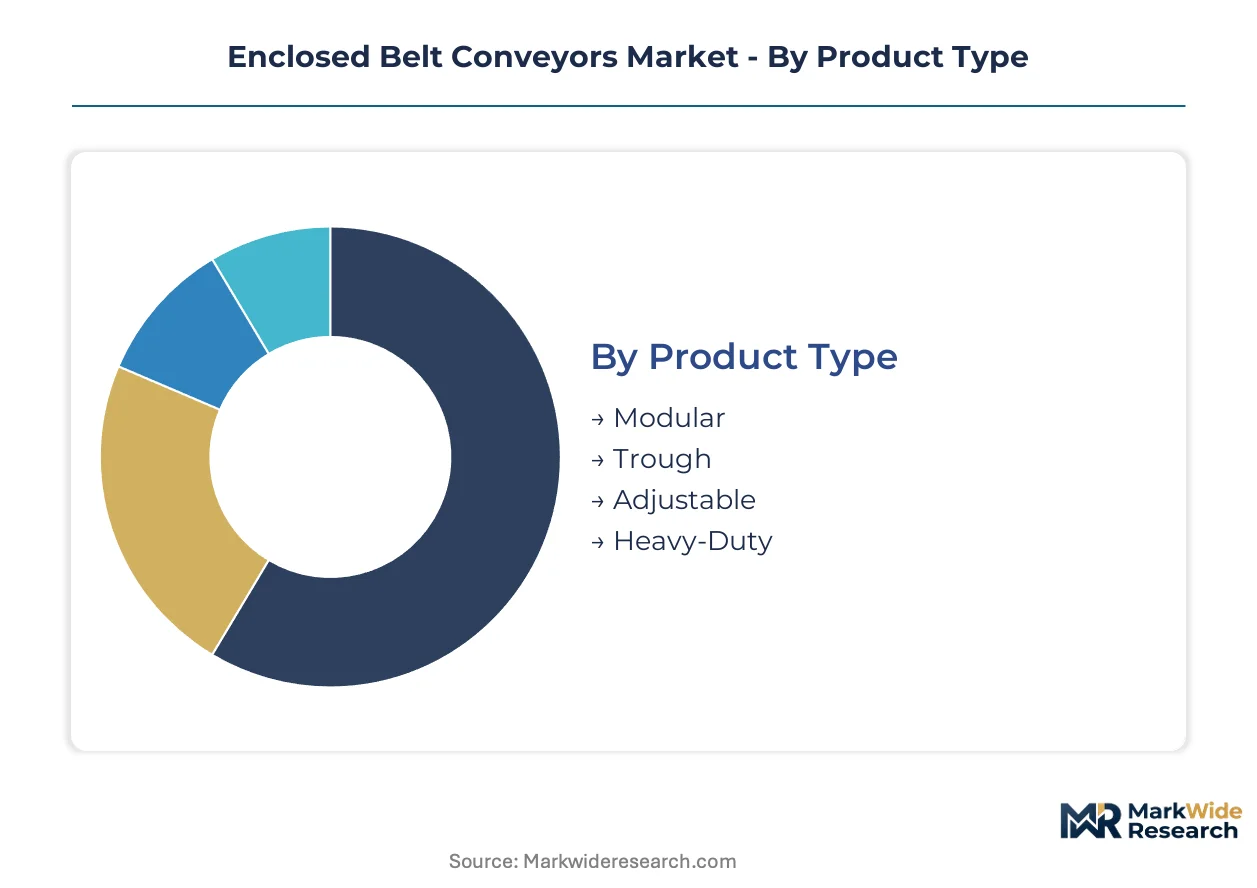
Segmentation in enclosed belt conveyors reveals how procurement priorities diverge across regulatory environments, material abrasiveness, and operational scale. Buyers select architectures based on dust containment mandates, belt durability requirements, and field reconfiguration needs rather than upfront equipment cost alone.
Product Type:
Capital allocation patterns separate grain cooperatives seeking installation flexibility from mining operators prioritizing structural endurance under abrasive loads.
- Modular:Field-adaptable configurations with bolted galvanized steel housings enable rapid reassembly across seasonal inbound and outbound material flows at multi-site grain cooperatives. Iowa and Nebraska cooperatives specify these systems to compress installation windows during narrow harvest-to-export intervals.
- Trough:Sealed troughed architectures with reinforced belt edges dominate food-grade applications where dust-tight sealing prevents cross-contamination between bulk commodity batches. EPA NESHAP Subpart DD compliance at US Midwest grain elevators drives specification of fully enclosed troughed paths above threshold capacities.
- Adjustable:Variable-angle housing designs accommodate elevation changes in brownfield retrofit projects without custom transition engineering.
- Heavy-Duty:Reinforced carcass constructions with specialized wear liners absorb copper ore and phosphate rock abrasion in Arizona and Chilean mineral operations.
Volume sits with Trough configurations serving agricultural compliance mandates; growth tilts toward Modular designs as cooperative networks expand multi-site standardization.
Application:
Material characteristics and regulatory exposure determine whether buyers prioritize polymer compound specifications or housing fabrication tolerances.
- Mining:Abrasive ore streams in Appalachian coal and western metal operations demand flame-resistant belt compounds and sealed drive enclosures as MSHA ventilation standards evolve. Aramid fiber reinforcement extends belt life beyond 50,000 operating hours in Arizona copper and Chilean phosphate handling.
- Agriculture:Bulk grain handling at commercial elevators and port terminals absorbs the majority of fully sealed conveyor deployments. The US Midwest agricultural corridor concentrates demand where EPA particulate emission limits mandate enclosed transfer architectures above threshold capacities.
- Food Processing:Cleanroom environments specify oil-free pneumatic actuation for precise speed modulation, though enclosed belt systems retain cost advantages at longer transport distances.
- Waste Management:Contaminated soil and construction debris handling requires corrosion-resistant housing materials and specialized belt cleaning mechanisms.
Revenue concentrates in Agriculture where regulatory deadlines compress procurement timelines; steepest expansion trajectory appears in Mining as mineral export infrastructure absorbs abrasion-resistant polymer innovations.
Technology:
Power transmission selection hinges on contamination sensitivity, speed control precision, and maintenance access constraints in enclosed housings.
- Electric Drive:Standard AC and DC motor configurations anchor the installed base across grain elevators and mineral processing plants. Variable frequency drives enable energy recovery during downhill conveying operations in mountainous terrain.
- Pneumatic:Oil-free compressed air systems gain specification in food processing cleanrooms where lubricant contamination risks override efficiency considerations. Precise speed modulation supports batch weighing integration in pharmaceutical ingredient handling.
- Hydraulic:High-torque hydraulic motors serve heavy-duty trough configurations in mining applications with frequent start-stop cycles under loaded conditions.
- Manual:Hand-cranked tensioning and tracking adjustments persist in small-scale agricultural installations with intermittent operation schedules.
Installed base dominance belongs to Electric Drive; specification momentum shifts toward Pneumatic systems in contamination-sensitive processing environments.
End User:
Purchasing authority and technical capability determine whether buyers source through OEM direct channels or intermediate distribution networks.
- Manufacturers:Integrated conveyor fabricators with in-house polymer compounding and galvanized steel fabrication control specification influence for large-scale grain export terminal projects. Prairie province production platforms anchor regional supply chains for North American agricultural demand.
- Distributors:Independent equipment dealers with field service capabilities capture aftermarket parts and retrofit project flows from mid-size grain cooperatives lacking centralized engineering staff.
- Contractors:Construction firms executing brownfield elevator retrofits demand custom transition chutes and drive alignment engineering that strains standardized product platforms.
- Suppliers:Component vendors of specialized wear liners and sensor-integrated monitoring systems unbundle from traditional bundled maintenance contracts.
Specification authority concentrates with Manufacturers; procurement fragmentation accelerates among Distributors as cooperatives separate predictive monitoring subscriptions from physical spare parts sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Galvanized steel mills in the US Midwest anchor regional conveyor fabrication clusters, with Iowa and Nebraska grain cooperatives driving specification demand for modular enclosed systems.
United States
EPA NESHAP Subpart DD particulate mandates compress procurement timelines at commercial elevators above threshold capacities. The regulation forces replacement of open transfer points with fully sealed architectures across the agricultural corridor. Omaha and Des Moines manufacturing clusters expand fabrication capacity to serve cooperative storage network expansions.
Germany
REACH chemical registration restricts plasticizer chemistries in belt compounds for EU food-grade applications. Compounders reformulate migration-resistant alternatives maintaining flexibility at sub-zero temperatures. The Ruhr industrial region concentrates polymer synthesis capabilities serving conveyor manufacturers.
Brazil
Grain export terminal expansion along the Amazon corridor lacks mature enclosed conveyor supply chains. ANVISA food safety protocols tighten contamination controls for agricultural commodity handling. Pará state port infrastructure investments create first-mover positioning opportunities for regional assembly partnerships.
China
Mineral processing capacity expansion in Inner Mongolia and Shanxi provinces absorbs heavy-duty trough configurations for abrasive coal and ore streams. MEE industrial emission standards tighten dust containment requirements at bulk material terminals. Yangtze River Delta fabricators scale production for domestic mining infrastructure.
Australia
Iron ore export operations in Western Australia's Pilbara region specify aramid-reinforced belt compounds exceeding 50,000 operating hour lifespans. State environmental protection authorities mandate enclosed transfer systems at port loading facilities. Perth-based engineering firms integrate predictive monitoring into sealed housing designs.
Enclosed Belt Conveyors Market Competitive Landscape
Global majors compete with regional champions across fabrication capacity and polymer compounding capabilities. The vendor base separates into tiered positions based on integrated manufacturing depth and geographic proximity to agricultural demand centers. Three archetypes dominate: prairie-based fabricators with captive steel supply, European technology specialists with proprietary sealing architectures, and diversified industrial conglomerates with polymer R&D platforms. Competitive moves concentrate on backward integration into belt compound production and regional assembly partnerships in underpenetrated export corridors.
Within the integrated manufacturing tier, Ag Growth International and Continental AG exemplify contrasting scale strategies. Ag Growth International anchors North American agricultural supply chains through prairie province production platforms. Continental AG occupies a position emphasizing polymer compound development for abrasive mineral applications. Buhler represents the European technology specialist archetype, with Swiss-based operations reflecting food-grade application priorities. These three fabricators demonstrate how geographic origin and corporate structure correlate with specification influence across regulatory environments.
| Leading Market Players |
|---|
| Ag Growth International |
| ContiTech AG |
| Kase Custom Conveyors |
| Buhler |
| Sweet Manufacturing |
| Continental AG |
| Bridgestone Corp. |
| Goodyear Rubber Co. |
| Fenner Dunlop |
| Others |
Supply & Pricing Matrix
EPA NESHAP Subpart DD compliance deadlines at US Midwest grain elevators are compressing procurement timelines and forcing supply chains to prioritize rapid fabrication turnaround over cost optimization, elevating pricing power for regional fabricators with integrated steel processing.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium-tier suppliers from commodity competitors in enclosed belt conveyor procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by polymer compound grade and EPA certification tier. Cost compression in economy-tier modular systems is intensifying because galvanized steel input volatility squeezes fabricator margins. Multi-site grain cooperatives with centralized engineering staff exhibit highest price sensitivity through unbundled spare parts sourcing, while mining operators prioritize abrasion-resistant polymer specifications over upfront equipment cost.
Supply Chain Analysis
ISO 9001 and ASME pressure vessel certification requirements gate entry for galvanized steel housing fabricators serving grain elevator retrofits. Supply concentrates in the United States, Germany, and China, with Ruhr Valley polymer compounders and Yangtze River Delta steel mills anchoring regional production clusters. Raw material dependencies rest on aramid fiber reinforcement, specialized abrasion-resistant polymers, and galvanized steel coil. Single-source vulnerability in German and Japanese polymer suppliers creates force majeure exposure. Distribution runs through OEM direct channels for large terminal projects and independent dealer networks for cooperative aftermarket procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer compounding and sensor-integrated monitoring systems defines competitive positioning in enclosed belt conveyors, as fabricators race to capture margin pools upstream from commoditized steel fabrication.
For Market Incumbents: Anchor specification authority through captive polymer synthesis capabilities and EPA certification pre-approval at commercial elevator projects. Pneumatic conveying substitution in food processing cleanrooms threatens belt system volume in short transport applications. Capacity addition in Brazilian regional assembly partnerships defends against first-mover entrants in Amazon corridor grain terminal expansion. For New Entrants and Emerging Players: Capture underpenetrated Brazilian port infrastructure through ANVISA-compliant regional assembly partnerships rather than direct export from established manufacturing bases. Modular field-adaptable designs offer the most penetrable entry point among grain cooperatives seeking installation flexibility. Go-to-market execution should leverage distributor field service capabilities to overcome incumbent OEM direct channel relationships. For Investors and Strategic Acquirers: Re-rating potential sits with integrated fabricators possessing in-house polymer compounding given REACH registration barriers and EPA compliance acceleration. Long-term viability favors upstream control over specialized belt carcass formulations and predictive maintenance data platforms. The signal to watch is MSHA ventilation standard finalization timing for underground mineral transport specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH and EPA certification timelines favor in-house formulation capabilities over external sourcing. |
| Regional Assembly Partnership in Brazil | ANVISA food safety protocols and Amazon corridor terminal expansion create first-mover positioning. |
| Predictive Maintenance Platform Launch | Sensor-integrated housings enable vibration monitoring subscriptions unbundled from spare parts procurement. |
| Flame-Resistant Belt Compound Development | MSHA ventilation standard evolution reshapes specification priorities for Appalachian coal operations. |
| Modular Design Standardization | Field-adaptable configurations reduce installation downtime at Iowa and Nebraska cooperative networks. |
Research Methodology
Multi-period observation of EPA enforcement patterns, grain elevator capacity expansions, and polymer compound price indices anchored the trend analysis, supplemented by interviews with maintenance directors at Midwest cooperatives, plant engineers at Arizona copper operations, OEM procurement teams, and aftermarket service heads. Secondary validation drew from EPA NESHAP Subpart DD regulatory filings, MSHA ventilation standard drafts, SEC 10-K disclosures by listed fabricators, and customs trade data for galvanized steel and aramid fiber imports. Bottom-up equipment shipment tracking and top-down agricultural infrastructure investment flows were triangulated to verify volume estimates.
Segment-weighting across product type, application, technology, and end-user dimensions structured the analytical framework across the projection horizon. CAGRs were derived from installed base replacement cycles, regulatory compliance deadlines, and export infrastructure investment pipelines. Modeled inputs included EPA threshold capacity classifications for grain elevators, MSHA flame-resistance certification timelines, and Brazilian port terminal expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel input cost volatility, REACH chemical registration amendments, and MSHA standard finalization timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cooperative storage network consolidation patterns. A model refresh is warranted upon material change in EPA NESHAP Subpart DD threshold definitions or MSHA ventilation standard adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Vibratory Feeder Machine Market