
 Concrete Chain Saw Market | 2026-2036
Concrete Chain Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Chain Saw Market Analysis
Skilled demolition technician shortages across North America and Western Europe is unwinding project timelines and pushing contractors toward higher-output equipment. Husqvarna AB leverages its diamond blade integration to sustain premium positioning in road cutting. Andreas Stihl AG & Co. KG anchors gasoline-powered portability for remote job sites without compressed air or three-phase power. Hilti Corporation competes through fleet management services that reduce downtime for municipal maintenance crews.
A concrete chain saw is a handheld or rig-mounted cutting machine utilizing diamond-impregnated segments or carbide-tipped chains to slice through reinforced concrete, masonry, and asphalt, typically operating at chain speeds between 1,200 and 1,800 meters per minute. The tool serves primary industrial purposes in controlled demolition, utility trenching, and structural modification where precision cuts limit collateral damage to surrounding substrate. Gasoline chain saws still dominate rental fleet deployments due to site power independence, though hydraulic variants command the margin pool in continuous heavy-duty applications like bridge deck removal. Diamond blade technology leads technology segmentation by installed base, while advanced cooling systems represent the fastest-expanding upgrade category as thermal degradation of cutting segments drives replacement costs higher.
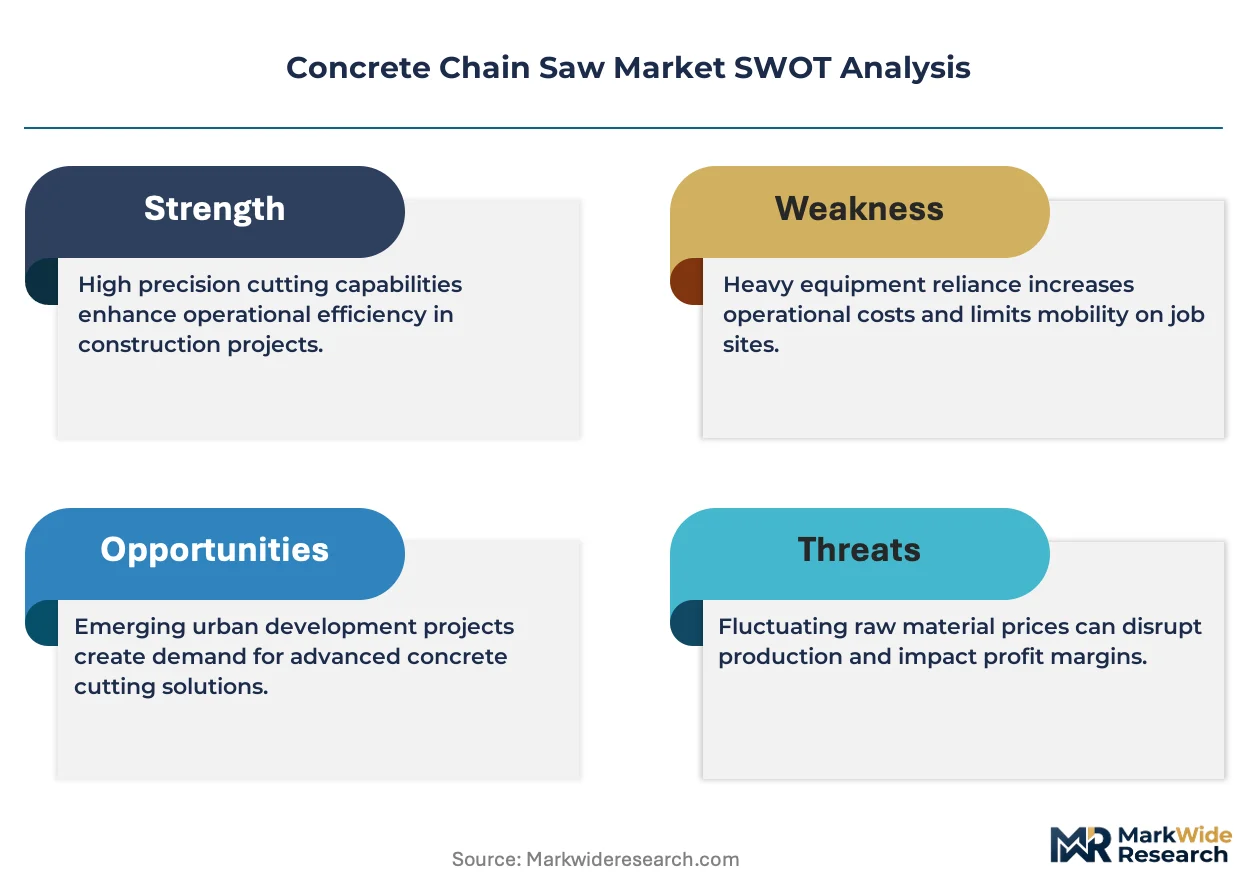
OSHA silica standards and EPA Tier 4 emissions rules shape equipment design mandates in the United States, forcing manufacturers to integrate water suppression systems and cleaner-burning engines. The EU Green Deal and REACH chemical restrictions influence lubricant formulations and chain lubrication protocols across European markets. Stakeholders must monitor how regulatory tightening on particulate emissions intersects with contractor demands for uninterrupted cutting performance in enclosed demolition environments.
Market Dynamics
OSHA silica exposure limits and EPA Tier 4 emissions mandates are compressing equipment design cycles, forcing manufacturers to integrate water suppression and cleaner combustion architectures without sacrificing cutting throughput in continuous demolition environments.
Growth Catalysts
- Urban renewal acceleration:Building demolition contractors in Germany and Austria are scaling hydraulic chain saw fleets for heavy infrastructure decommissioning, driven by municipal brownfield redevelopment timelines.
- REACH chemical restrictions:EU lubricant formulation standards are pushing chain lubrication protocol upgrades, creating replacement demand for compliant cutting systems across European rental fleets.
- Diamond blade integration:Road cutting contractors are specifying diamond-impregnated segment chains for precision trenching that limits collateral damage to surrounding substrate in utility corridor work.
Market Restraints
- Skilled technician scarcity:North American demolition labor shortages are unwinding project timelines and constraining equipment utilization rates across contractor fleets.
- Three-phase power dependency:Hydraulic system deployment requires compressed air infrastructure or electrical supply that remote job sites often lack, limiting adoption outside urban cores.
- Carbide tip substitution:Lower-cost carbide-tipped chains compete for asphalt and soft masonry applications, pressuring diamond segment pricing in entry-tier equipment categories.
Strategic Opportunities
- EU Green Deal alignment:Equipment financing incentives for low-emission demolition machinery are opening public procurement channels for compliant hydraulic and battery-electric variants.
- Fleet management services:Municipal maintenance crews are unbundling equipment ownership from uptime guarantees, creating recurring revenue streams for service-integrated vendors.
- Cooling system upgrades:Thermal degradation of cutting segments is accelerating demand for advanced cooling architectures as a retrofit and factory-installed option category.
Industry Challenges
- Certification timeline compression:OSHA and EPA compliance testing protocols are extending product launch cycles, delaying revenue recognition for new equipment introductions.
- Supply chain reconfiguration friction:REACH-compliant lubricant sourcing is forcing reformulation partnerships and qualification delays across European distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Chain Saw Market |
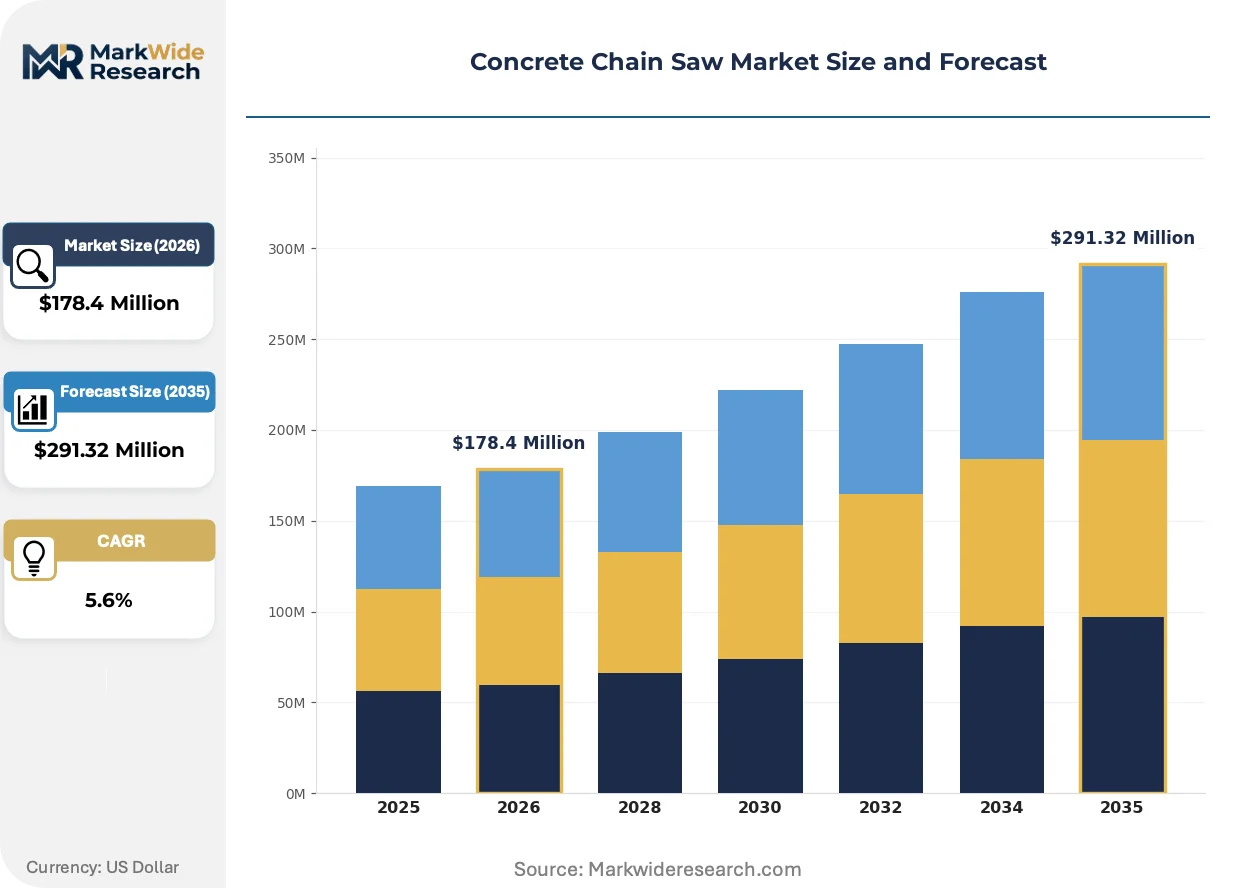
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $291.32 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Chain Saws, Gasoline Chain Saws, Hydraulic Chain Saws, Pneumatic Chain Saws Technology: Diamond Blade Technology, Carbide Tipped Technology, Standard Blade Technology, Advanced Cooling Technology Application: Building Demolition, Road Construction, Pipe Cutting, Trenching End User: Contractors, Construction Companies, Municipalities, Maintenance Providers |
| Companies Covered | Wacker Neuson SE, Tyrolit Schleifmittelwerke Swarovski KG, Husqvarna AB, Andreas Stihl AG & Co. KG, CS Unitec Maschinenbau GmbH, ICS Diamond Tool Company, LLC, Diamond Products Inc., Reimann and Georger Corp., Hilti Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Chain Saw Market Emerging Trajectories
Equipment architecture is pivoting toward thermal management and emission containment as regulatory thresholds tighten, while service models decouple hardware ownership from performance guarantees.
Advanced cooling systems are miniaturizing. These architectures circulate conditioned fluid through cutting head assemblies to maintain diamond segment integrity under sustained load. Bridge deck removal contractors in continuous-duty applications are specifying factory-integrated cooling as standard, compressing replacement part revenue cycles while extending chain life.
EPA Tier 4 Final emissions standards are mandating diesel particulate filters and selective catalytic reduction on gasoline-powered units above threshold displacement. Equipment manufacturers are redesigning engine compartments to accommodate after-treatment hardware without compromising portability. Rental fleet operators in the United States are absorbing capital cost premiums and extending lease terms to recover compliance investments.
Service unbundling is restructuring municipal procurement. Maintenance crews are shifting from capital purchase to performance-based contracts that guarantee cutting availability per operating hour. Husqvarna and Hilti service networks in Germany and Austria are capturing this transition through depot-based rapid exchange programs that eliminate field repair downtime.
Concrete Chain Saw Market Segmentation
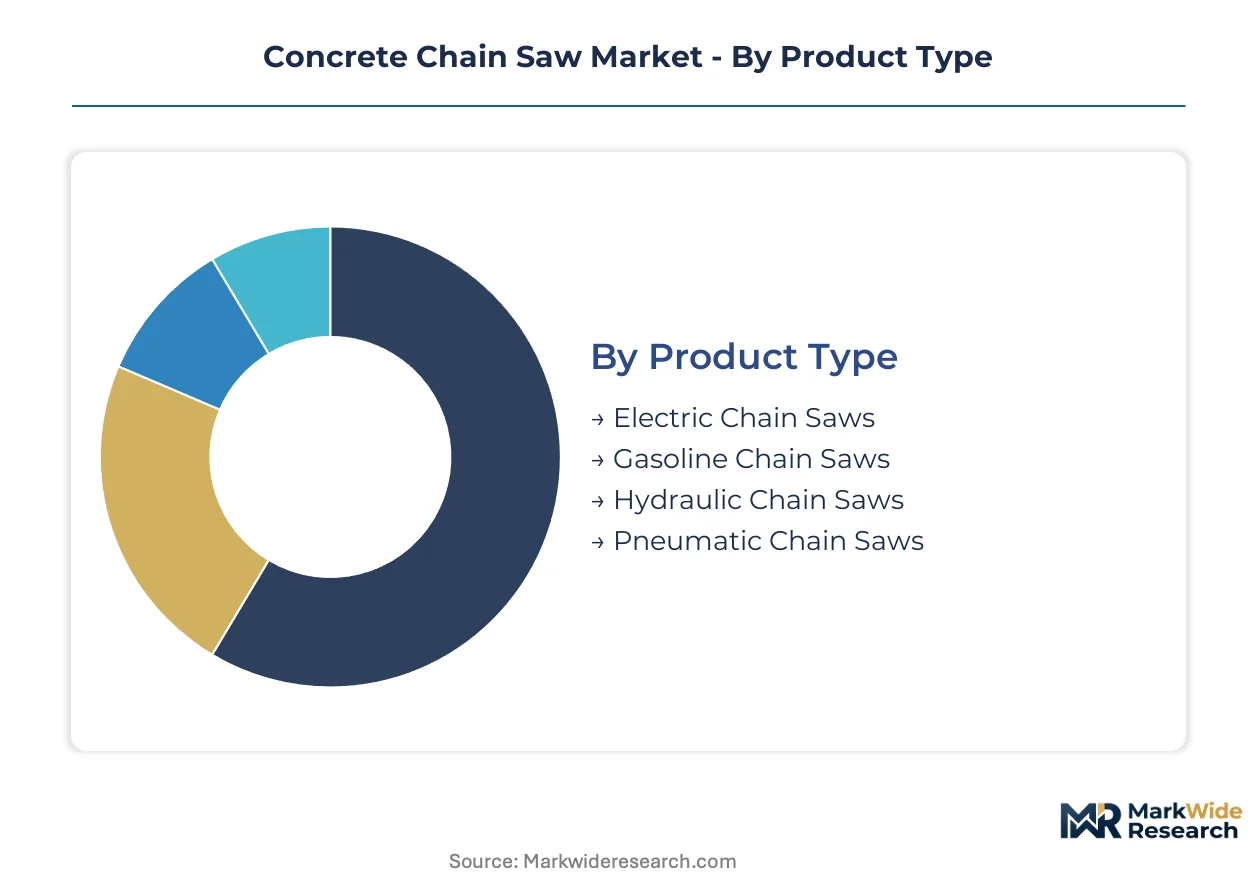
Concrete chain saw segmentation reveals how power source preferences, cutting technology sophistication, and end-use specialization create distinct commercial battlegrounds. Equipment manufacturers configure product portfolios across these dimensions to capture specific contractor workflows and compliance environments.
Product Type:
Gasoline-powered units dominate export flows to developing markets lacking fixed infrastructure, while hydraulic variants concentrate in German and Austrian domestic procurement for heavy decommissioning work.
- Electric Chain Saws:Battery and corded architectures deliver zero-emission cutting for enclosed demolition sites where OSHA silica containment is mandatory. Demand clusters in California and New York municipalities enforcing strict indoor air quality protocols.
- Gasoline Chain Saws:Two-stroke and four-stroke engines provide site-independent mobility for remote utility trenching and emergency response. Rental fleets across Texas and Florida deploy these units where three-phase power is unavailable.
- Hydraulic Chain Saws:Continuous-duty systems integrate with carrier equipment for bridge deck removal and structural dismantling.
- Pneumatic Chain Saws:Compressed-air operation eliminates ignition risk in petrochemical and mining environments.
Gasoline chain saws hold the largest share; momentum sits with hydraulic systems in European infrastructure decommissioning.
Technology:
Technology tiers separate precision cutting applications from cost-sensitive asphalt work, with cooling architectures commanding premium positioning in continuous-duty contracts.
- Diamond Blade Technology:Synthetic diamond segments bonded to steel cores slice through reinforced concrete with minimal kerf loss. Road contractors in Germany specify these chains for utility corridor work where substrate preservation reduces backfill costs.
- Advanced Cooling Technology:Closed-loop fluid circulation through cutting heads maintains segment integrity under sustained thermal load. Bridge demolition specialists in Austria now require factory-integrated cooling as standard specification.
- Carbide Tipped Technology:Tungsten carbide cutters penetrate soft masonry and asphalt at lower capital cost.
- Standard Blade Technology:Conventional steel chains serve intermittent light-duty applications.
Diamond blade technology holds the largest share; advanced cooling systems are climbing the fastest as thermal management becomes a contract differentiator.
Application:
Application segmentation tracks urban renewal intensity and utility infrastructure investment cycles across municipal and private contractor budgets.
- Building Demolition:Controlled dismantling of reinforced concrete structures demands precision cutting to limit collateral damage. Brownfield redevelopment timelines in German cities are accelerating hydraulic saw deployment for selective demolition.
- Trenching:Narrow excavation for water, gas, and fiber optic lines requires clean sidewall cuts that minimize bedding material requirements. Municipal maintenance crews in Texas favor diamond-chain trenchers for clay-heavy soils.
- Road Construction:Pavement removal and expansion joint cutting operate on compressed highway maintenance windows.
- Pipe Cutting:Severing concrete-encased utilities and large-diameter drainage lines.
Building demolition holds the largest share; trenching applications are gaining share fastest as fiber optic rollout intensifies.
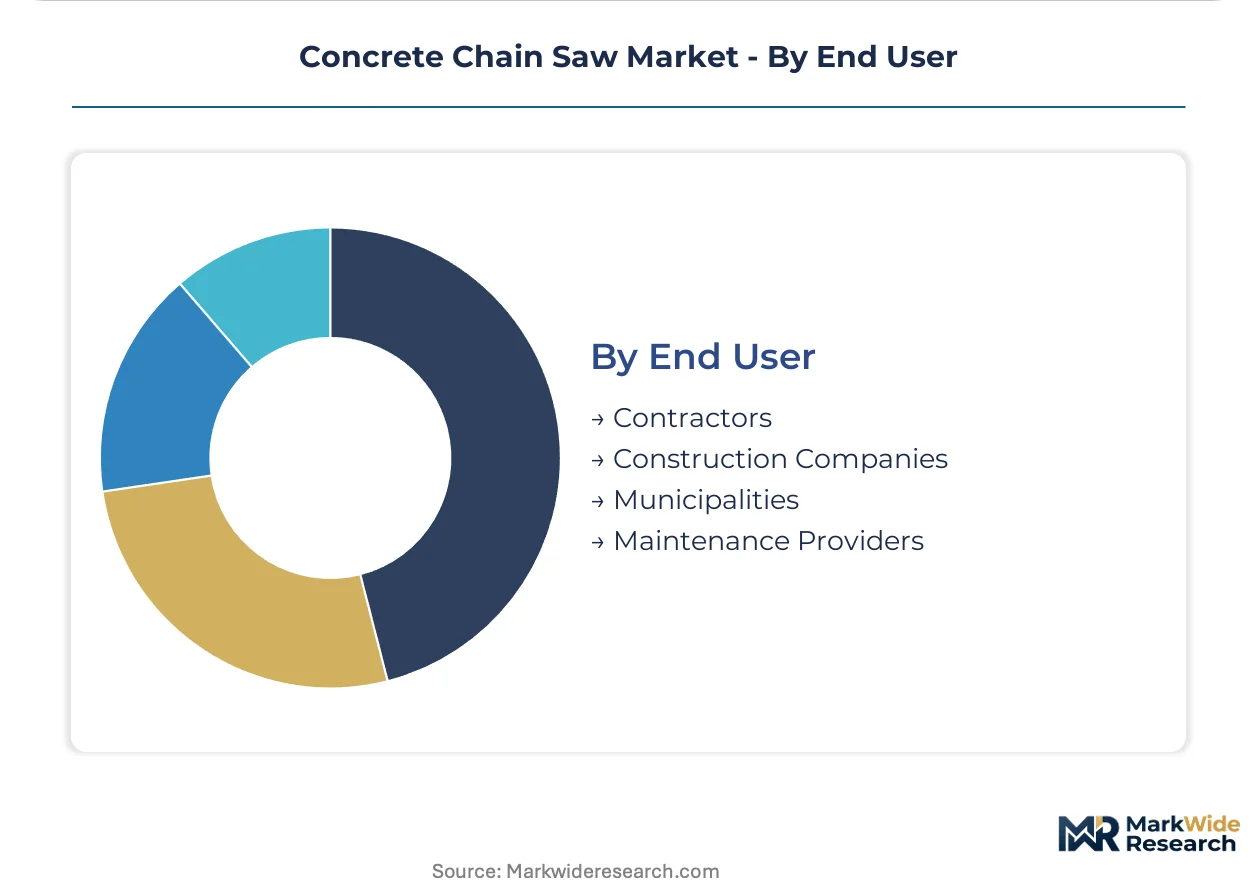
End User:
End-user categories reflect divergent procurement logic: capital ownership versus performance contracting, and compliance-driven specification versus cost minimization.
- Contractors:Independent demolition and concrete cutting specialists prioritize equipment uptime and rapid chain exchange to maintain crew productivity. Skilled technician shortages across North America are pushing this segment toward higher-output hydraulic units.
- Municipalities:City maintenance departments are unbundling equipment ownership from availability guarantees, shifting toward service-integrated procurement models. Public procurement channels in Germany and Austria now favor EU Green Deal-compliant hydraulic variants.
- Construction Companies:General contractors deploy chain saws for structural modification and site preparation phases.
- Maintenance Providers:Third-party infrastructure service firms operate on performance-based contracts.
Contractors hold the largest share; municipalities are expanding most quickly as service unbundling restructures public procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA silica exposure limits and EPA Tier 4 emissions mandates in the United States are forcing equipment redesign cycles that ripple through supplier networks worldwide. Municipal brownfield programs and utility infrastructure renewal are concentrating demand in specific industrial corridors.
United States
Building demolition contractors in Texas and Florida favor gasoline-powered units for site independence where three-phase power is unavailable. OSHA silica containment rules drive water suppression system integration in California and New York municipal fleets. Houston's petrochemical corridor sustains pneumatic chain saw demand for explosion-risk environments.
Germany
Hydraulic chain saw procurement concentrates in heavy infrastructure decommissioning projects across the Ruhr Valley brownfield zones. EU Green Deal equipment financing incentives open public procurement channels for low-emission variants. Munich and Stuttgart municipal maintenance crews are shifting toward service-integrated contracts with availability guarantees.
Austria
Bridge deck removal specialists in Vienna and Linz now require factory-integrated advanced cooling systems as standard specification. REACH-compliant lubricant sourcing forces reformulation partnerships across Austrian distribution networks. Alpine tunnel maintenance programs sustain demand for precision cutting equipment with thermal management architectures.
China
Urban renewal acceleration in the Yangtze River Delta and Pearl River Delta drives demand for diamond-impregnated segment chains in controlled demolition. The country's national construction equipment regulator enforces emissions standards that push cleaner combustion architectures. Shenzhen and Shanghai infrastructure investment cycles concentrate procurement in municipal maintenance fleets.
Canada
Remote utility trenching in Alberta and British Columbia favors gasoline-powered portability for job sites lacking compressed air infrastructure. Health Canada workplace safety guidelines align with silica exposure protocols affecting equipment specification. Toronto's transit expansion projects drive diamond-chain trenching demand for clay-heavy soil conditions.
Concrete Chain Saw Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier commands premium positioning through diamond blade integration and fleet management services, while mid-tier players compete on equipment output and rental fleet penetration. Strategic archetypes separate portable gasoline specialists from continuous-duty hydraulic fabricators and from service-integrated solution providers. Competitive moves concentrate on portfolio diversification toward cooling system upgrades and on geographic expansion through depot-based rapid exchange networks.
Among European-integrated manufacturers, Husqvarna AB and Andreas Stihl AG & Co. KG occupy positions on opposite ends of the power source spectrum, with the former representing diamond-technology premium positioning and the latter exemplifying gasoline-powered portability archetypes. Hilti Corporation anchors the service-integrated tier through fleet management offerings that decouple equipment ownership from uptime guarantees. These three entities collectively illustrate how competitive positioning separates by procurement model rather than hardware specification alone.
| Leading Market Players |
|---|
| Wacker Neuson SE |
| Tyrolit Schleifmittelwerke Swarovski KG |
| Husqvarna AB |
| Andreas Stihl AG & Co. KG |
| CS Unitec Maschinenbau GmbH |
| ICS Diamond Tool Company, LLC |
| Diamond Products Inc. |
| Reimann and Georger Corp. |
| Hilti Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at hydraulic system fabricators in Germany and Austria anchors price floors for premium cutting equipment, compressing margins at mid-tier gasoline-powered manufacturers while elevating bargaining power for diamond-segment suppliers. This scale asymmetry stratifies procurement costs across contractor archetypes and municipal fleets.
Pricing Analysis
North American rental fleets absorb 15-25% capital cost premiums over European procurement for EPA Tier 4-compliant gasoline units. Pricing stratifies across premium, standard, and economy tiers based on cooling system integration and diamond segment bonding quality. Cost compression in carbide-tipped entry equipment is intensifying because Chinese manufacturers are expanding export volumes. Municipal maintenance crews exhibit highest price sensitivity due to budget approval cycles, while bridge demolition specialists prioritize thermal management specifications over unit economics.
Supply Chain Analysis
Inventory cycles for diamond-impregnated segments extend 8-12 weeks due to synthetic grit synthesis bottlenecks in Ireland and Japan. Manufacturing concentration clusters in Germany, Austria, and China, with hydraulic power unit assembly tethered to Ruhr Valley industrial corridors. Synthetic diamond supply draws from Element Six facilities in Ireland and Sumitomo Electric operations in Japan, creating single-source vulnerability for specialized segment geometries. Distribution runs through depot-based rapid exchange networks operated by OEM service divisions and independent rental fleet aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete chain saw market sits in early-cycle expansion as EU Green Deal equipment financing accelerates municipal procurement of low-emission hydraulic variants. Service unbundling is converting capital sales into recurring revenue streams.
For Market Incumbents: Shield premium positioning by backward integration into diamond segment manufacturing and captive supply of REACH-compliant lubricant formulations. Certification investment in OSHA silica containment systems preserves access to California and New York municipal channels. Capacity addition in Austrian alpine tunnel maintenance corridors captures Alpine infrastructure renewal timelines.
For New Entrants and Emerging Players: Differentiate on battery-electric zero-emission architectures for enclosed demolition sites where OSHA mandates water suppression. The most penetrable white space sits in Texas and Florida rental fleet replacement cycles where gasoline portability requirements exclude hydraulic competition. Target municipal maintenance crews through performance-based availability contracts rather than equipment ownership models.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated vendors with depot-based rapid exchange networks. Long-term viability over the next decade hinges on thermal management IP and EU regulatory compliance certification. Acquisition targets should demonstrate installed base density in German brownfield corridors. The signal to watch is municipal procurement rule changes embedding EU Green Deal alignment into bid scoring criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diamond Segment Manufacturing | Captive supply of synthetic grit reduces exposure to Element Six and Sumitomo Electric pricing power. |
| REACH-Compliant Lubricant Formulation Partnership | Qualification delays across European distribution networks create first-mover advantage in rental fleet retrofits. |
| Depot-Based Rapid Exchange Network Expansion | Husqvarna and Hilti service architectures in Germany and Austria eliminate field repair downtime for municipalities. |
| Battery-Electric Zero-Emission Product Line Launch | California and New York indoor air quality protocols mandate emission containment in enclosed demolition. |
| Performance-Based Availability Contract Structuring | Municipal maintenance crews in Munich and Stuttgart unbundle ownership from uptime guarantees. |
Methodological Framework
Initial hypotheses were tested against primary input from demolition contractors, municipal maintenance directors, rental fleet operators, and aftermarket service managers and refined through secondary validation against SEC filings, customs trade data, EPA enforcement records, and EU procurement registries. Bottom-up equipment shipment data triangulated against top-down construction spending forecasts anchored the market sizing framework.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeled across power source architecture, cutting technology tier, cooling system integration, application intensity, and end-user procurement model. CAGRs were derived from fitted growth curves calibrated to historical replacement cycles and forward infrastructure investment pipelines, incorporating OSHA silica rule phase-in schedules and EU Green Deal equipment financing trajectories as scenario inputs.
Forecasts assume regulatory continuity in OSHA silica exposure limits and EPA Tier 4 emissions mandates; material policy shifts would require re-modeling. Supply chain reconfiguration friction from REACH-compliant lubricant sourcing and skilled technician scarcity represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
Backhoes Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
Road Roller Market