
 Electrofusion Welding Machines Market | 2026-2036
Electrofusion Welding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Electrofusion Welding Machines Market Insights
Chinese electrofusion machine producers is rebalancing capacity toward microcontroller-based systems for export markets. Georg Fischer leverages its Swiss engineering heritage to dominate premium stationary equipment for gas distribution utilities. McElroy Manufacturing anchors North American demand through extensive field-service networks and rental channel partnerships. RITMO S.p.A. competes aggressively across Southern Europe with specialized portable units for tight-access pipeline repairs.
An electrofusion welding machine electrically heats a resistive wire coil embedded within a polyethylene fitting, generating localized molten zones that fuse pipe and fitting into a monolithic joint under controlled voltage and cooling cycles; these systems achieve joint strengths matching or exceeding parent material tensile properties, which explains their dominance in pressurized gas and potable water infrastructure. Automatic equipment leads value generation due to embedded data-logging and barcode traceability that utility inspectors require, while portable units represent the fastest-growing configuration as fiber-optic and telecom cabling deployments multiply in urban corridors. Microprocessor-controlled technology now occupies the margin-rich center of the market, displacing older relay-type architectures that lack real-time temperature feedback.
FDA and NSF standards govern potable water contact surfaces and calibration protocols, while EPA pipeline safety regulations mandate traceable weld documentation for gas distribution networks. The EU F-Gas Regulation and associated CE marking requirements shape product design for European export eligibility, forcing manufacturers to certify electromagnetic compatibility and operator safety interlocks. Stakeholders must monitor how impending updates to ISO 21307 welding procedure standards affect equipment validation cycles and aftermarket service obligations.
Market Dynamics
Microprocessor-controlled architectures are displacing relay-based systems across the electrofusion welding machine market, compressing validation cycles while forcing manufacturers to recalibrate service networks around data-logging capabilities and barcode traceability requirements.
Growth Catalysts
- EPA Pipeline Safety Regulations:Mandates for documented weld traceability in gas distribution networks are compelling utility operators to upgrade from manual to automatic electrofusion systems with embedded data-logging.
- Polyethylene Infrastructure Renewal:Municipal water authorities across Germany are deploying precision-controlled welding systems for district heating expansions and aging pipeline replacement programs.
- Leak-Free Joint Standards:EU F-Gas framework requirements for hermetic integrity in pressurized systems are accelerating equipment replacement cycles among European gas utility operators.
Market Restraints
- Copper and Semiconductor Input Volatility:Resistive heating coils and microcontroller components face price instability from concentrated East Asian foundry capacity, squeezing margin structures for equipment assemblers.
- Swiss-German Engineering Concentration:Premium stationary equipment production clusters in Central Europe, creating supply vulnerability and extended lead times for North American utility procurement.
- Butt Fusion Substitution:Large-diameter pipeline contractors in cost-sensitive markets favor mechanical butt fusion for trunk lines above 315mm, limiting electrofusion addressable volume.
Strategic Opportunities
- Fiber-Optic Trenching Corridors:Telecom infrastructure deployments in urban corridors are generating demand for portable electrofusion units sized for tight-access conduit repairs.
- ISO 21307 Standard Updates:Pending revisions to welding procedure validation protocols will create aftermarket service and recertification revenue streams for equipment vendors with field technical capabilities.
- India Water Infrastructure:Central government Jal Jeevan Mission allocations for rural piped water networks represent an underpenetrated geography requiring compact, voltage-adaptive welding systems.
Industry Challenges
- Certified Welding Technician Scarcity:Utility operators face 12-18 month training pipelines for electrofusion procedure qualification under evolving ISO standards, constraining deployment velocity.
- Legacy System Integration Friction:Municipal gas distribution networks with decades-old polyethylene installations require retrofitted data-logging adapters to meet EPA documentation mandates, complicating upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrofusion Welding Machines Market |
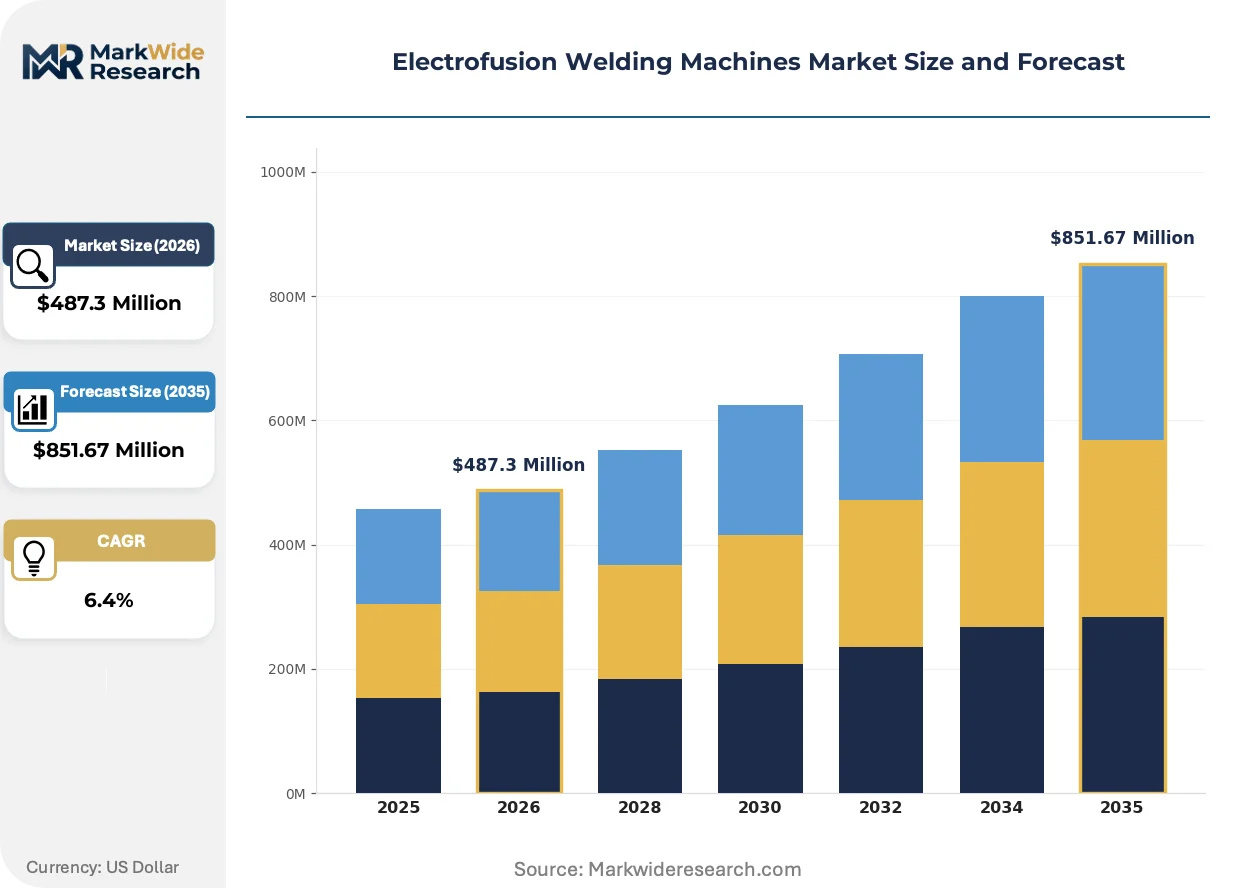
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $851.67 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, Portable, Stationary Technology: Microcontroller-Based, Relay-Type, Microprocessor-Controlled, Touch Screen, Sensor Integrated Application: Gas Piping, Water Supply, Chemical Industry, Telecom Cabling, Underground Utilities End User: Pipeline Fabricators, Equipment Rental Firms, Construction Companies, Utility Service Providers |
| Companies Covered | McElroy Manufacturing, RITMO S.p.A., GEofusion, Georg Fischer, Aliaxis Group, Wuxi Shunda Plastic Pipes Welding Machine Co., Ltd, Plastal S.A., Frialit S.A., Elektro-Weld GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrofusion Welding Machines Market Trends and Innovations
Electrofusion welding equipment is converging with industrial IoT architectures, embedding real-time temperature feedback and cloud-connected quality assurance that reshape how utilities validate joint integrity across distributed infrastructure networks.
Bluetooth-enabled data-logging modules are automating weld documentation workflows, transmitting voltage curves and cooling cycle parameters directly to utility asset management systems. North American gas distribution operators are adopting these systems fastest, driven by EPA audit requirements. The technology is automating inspector site visits while compressing the window between joint completion and regulatory filing.
EU F-Gas Regulation amendments are tightening electromagnetic compatibility certification requirements for equipment sold into European markets. Manufacturers must now validate operator safety interlocks through notified body assessment before CE marking. German gas network operators are most affected, requiring equipment fleets to undergo recertification against updated EN standards.
Rental channel partnerships are displacing direct equipment sales for intermittent-use contractors in municipal maintenance segments. McElroy Manufacturing's field-service network model is being replicated by competitors seeking to capture utility capex constraints. This pattern is most visible across Texas and California, where water authority budgets favor operational expenditure structures over capital ownership.
Electrofusion Welding Machines Market Segmentation
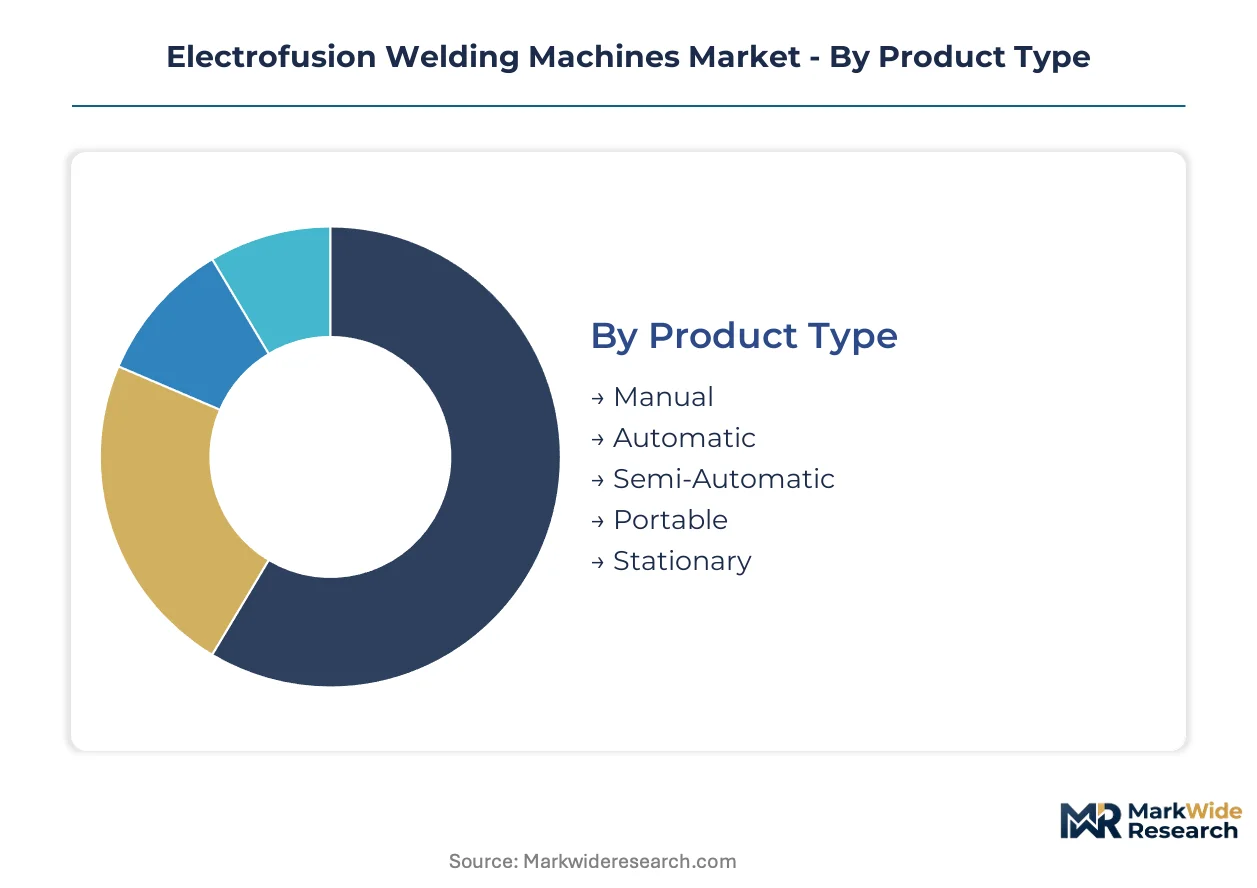
Electrofusion welding machine segmentation reflects divergent supply chain configurations across precision-controlled stationary systems and portable field units. Manufacturers configure production lines around distinct certification tiers, with automatic data-logging equipment commanding premium foundry partnerships while portable configurations source from distributed electronics assemblers.
Product Type:
Supply concentration for electrofusion equipment clusters around automatic stationary systems with embedded microcontroller architectures, while portable unit production disperses across contract manufacturers serving intermittent-use segments.
- Automatic:Embedded data-logging and barcode traceability satisfy EPA pipeline safety mandates for documented weld integrity across US gas distribution networks. German district heating authorities specify these systems for precision-controlled joint formation in pressurized polyethylene infrastructure.
- Portable:Compact voltage-adaptive designs address tight-access repairs in urban telecom conduit corridors. Fiber-optic trenching contractors across Texas and California favor rental-channel procurement of these units for intermittent deployment cycles.
- Manual:Relay-based architectures persist in cost-sensitive emerging markets with limited regulatory documentation requirements.
- Semi-Automatic:Hybrid designs bridge price-performance gaps for mid-tier municipal water authorities upgrading from manual systems.
- Stationary:Fixed-installation systems dominate large-diameter pipeline fabrication yards with dedicated power infrastructure.
Today's leader: Automatic. Tomorrow's challenger: Portable.
Technology:
Cost tier stratification separates premium microprocessor-controlled architectures from legacy relay-type systems, with validation complexity and aftermarket service obligations widening margin dispersion across technology tiers.
- Microprocessor-Controlled:Real-time temperature feedback and closed-loop voltage regulation enable ISO 21307-compliant weld procedures. Swiss and German engineering clusters dominate this margin-rich center of the market.
- Microcontroller-Based:Chinese producers are rebalancing capacity toward these systems for export markets, leveraging East Asian semiconductor supply chains.
- Relay-Type:Older architectures lack data-logging capabilities, facing displacement as EPA and EU F-Gas documentation mandates tighten.
- Touch Screen:Intuitive operator interfaces reduce training pipelines for certified welding technician qualification.
- Sensor Integrated:Multi-parameter monitoring enables predictive maintenance alerts for rental fleet operators.
Volume concentrates with microprocessor-controlled systems; steepest expansion trajectory belongs to microcontroller-based configurations.
Application:
Customer type differentiation separates utility operators with stringent traceability requirements from construction contractors prioritizing equipment mobility and operational expenditure structures.
- Gas Piping:Pressurized distribution networks demand automatic electrofusion systems with embedded data-logging to satisfy EPA audit requirements. North American utility operators represent the most regulated demand concentration.
- Water Supply:Municipal authorities across Germany deploy precision-controlled welding for aging pipeline replacement and district heating expansion programs.
- Chemical Industry:Hermetic joint integrity specifications align with EU F-Gas framework compliance for process piping systems.
- Telecom Cabling:Urban fiber-optic deployments generate demand for portable units sized for tight-access conduit repairs.
- Underground Utilities:Multi-service corridor construction favors versatile equipment configurations adaptable across piping and cabling applications.
Regulatory intensity peaks in gas piping; infrastructure renewal momentum concentrates in water supply.
End User:
Geographic procurement patterns concentrate automatic system demand among integrated utility service providers, while equipment rental firms capture intermittent-use segments across municipal maintenance markets.
- Utility Service Providers:Integrated gas and water operators mandate automatic systems with cloud-connected quality assurance for distributed infrastructure validation. German network operators lead European adoption of Bluetooth-enabled documentation workflows.
- Equipment Rental Firms:McElroy Manufacturing's field-service network model anchors North American rental channel partnerships, displacing direct sales for intermittent-use contractors.
- Pipeline Fabricators:Dedicated fabrication yards specify stationary automatic systems for high-throughput production environments.
- Construction Companies:General contractors favor portable configurations with flexible procurement terms for project-based deployment cycles.
Procurement authority consolidates with utility service providers; rental penetration is climbing fastest among construction companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting electrofusion equipment sourcing patterns as manufacturers migrate production toward jurisdictions with streamlined CE marking pathways and lower electromagnetic compliance validation costs.
United States
EPA pipeline safety mandates for documented weld traceability drive automatic system upgrades across gas distribution networks. Utility operators in Texas and California favor rental-channel procurement models to convert capital expenditure into operational spend. Houston anchors the largest concentration of field-service networks serving intermittent-use contractors.
Germany
District heating expansions and municipal water infrastructure renewals concentrate demand for precision-controlled welding systems. EU F-Gas Regulation amendments tighten electromagnetic compatibility certification requirements, forcing equipment fleet recertification. Bavarian engineering clusters dominate premium stationary equipment production for pressurized polyethylene infrastructure.
China
Microcontroller-based system capacity is rebalancing toward export markets as domestic producers leverage East Asian semiconductor supply chains. The MIIT oversees industrial equipment standardization affecting welding machine electromagnetic compatibility protocols. Wuxi and surrounding Yangtze River Delta manufacturing zones supply compact voltage-adaptive units for emerging market water infrastructure programs.
India
Central government Jal Jeevan Mission allocations for rural piped water networks generate demand for portable, voltage-adaptive welding configurations. BIS certification requirements shape product design for domestic market eligibility. Maharashtra and Gujarat industrial corridors concentrate equipment assembly operations serving South Asian infrastructure deployment.
Switzerland
Swiss engineering heritage anchors premium stationary equipment production for gas distribution utilities requiring closed-loop voltage regulation. Swissmedic and associated notified bodies validate operator safety interlocks for CE marking eligibility. Zurich-region precision manufacturing clusters supply microprocessor-controlled architectures with real-time temperature feedback capabilities.
Electrofusion Welding Machines Market Competitive Landscape
Swiss and German engineering clusters anchor the premium equipment tier; Chinese fabricators occupy volume-oriented microcontroller-based production. Market structure consolidates around three strategic archetypes: precision-engineered stationary system specialists, portable unit contract manufacturers, and field-service network operators. Competitive intensity centers on M&A activity targeting data-logging technology assets and strategic partnerships with rental channel distributors.
Among Swiss-German precision engineering groups, Georg Fischer and Elektro-Weld GmbH exemplify the premium stationary equipment archetype with heritage positioning in closed-loop voltage regulation systems. McElroy Manufacturing represents the field-service network model that rental channel partnerships replicate. RITMO S.p.A. occupies a specialization position in portable configurations for tight-access pipeline repairs across Southern European markets.
| Leading Market Players |
|---|
| McElroy Manufacturing |
| RITMO S.p.A. |
| GEofusion |
| Georg Fischer |
| Aliaxis Group |
| Wuxi Shunda Plastic Pipes Welding Machine Co., Ltd |
| Plastal S.A. |
| Frialit S.A. |
| Elektro-Weld GmbH |
| Others |
Pricing and Supply Chain Analysis
Microprocessor-controlled certification tiers diverge sharply from relay-based commodity equipment, creating a dual-track market where German and Swiss engineering clusters capture premium pricing through closed-loop voltage regulation while Chinese contract manufacturers compete on microcontroller-based unit economics. This bifurcation feeds directly into supply chain geography: precision components for automatic data-logging systems flow through Zurich-region foundries, whereas portable configurations source from dispersed Yangtze River Delta assemblers serving price-sensitive rental channels.
Pricing Analysis
Distributor margins for automatic electrofusion systems compress the final price by 15-25 points before reaching utility procurement teams, while rental channel partnerships absorb this markup through operational expenditure structures favored by Texas and California water authorities. Pricing stratifies across ISO 21307-certified automatic tiers, CE-marked mid-range configurations, and uncertified manual units for emerging markets. Cost compression in microcontroller-based portable segments is intensifying because East Asian foundry capacity expansion for resistive heating coils outpaces demand growth. Municipal gas distribution operators exhibit the lowest price sensitivity due to EPA-mandated traceability requirements, whereas intermittent-use telecom contractors driving portable demand prioritize rental flexibility over acquisition cost.
Supply Chain Analysis
Precision welding technician scarcity across Bavarian manufacturing zones constrains output expansion for premium stationary equipment despite strong order backlogs from German district heating authorities. Supply concentration centers on Switzerland and Germany for microprocessor architectures, China for microcontroller-based portable units, and Italy for specialized tight-access configurations. Component sourcing draws from East Asian semiconductor foundries for control systems, German copper processors for resistive heating coils, and Swiss precision mechanics for voltage regulation modules. Single-source vulnerability in microcontroller chip supply creates exposure to export control fluctuations. Distribution runs through field-service networks for automatic systems, rental firm partnerships for portable units, and direct OEM relationships for large fabrication yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in electrofusion welding equipment hinges on microcontroller cost curves flattening faster than premium-tier pricing erodes, allowing vendors to capture spread improvement as automatic systems retain EPA-mandated valuation power.
For Market Incumbents: Extend data-logging software subscription attach rates beyond hardware sale closure, converting one-time equipment revenue into recurring utility expenditure streams. Deepen backward integration into resistive heating coil production to buffer copper price volatility squeezing assembler margins. Defend against butt fusion substitution above 315mm trunk line applications by embedding cloud-connected quality assurance that mechanical joining cannot replicate. For New Entrants and Emerging Players: Equipment rental firms represent the most penetrable channel partner type for volume entry without direct competition against entrenched field-service networks. Target India's Jal Jeevan Mission rural water infrastructure with voltage-adaptive portable configurations priced below German automatic systems. Pursue white-label manufacturing partnerships with Yangtze River Delta assemblers to bypass Swiss-German engineering concentration and serve Southeast Asian emerging demand. For Investors and Strategic Acquirers: Consolidation pressure builds where microcontroller-based portable specialists lack the service infrastructure to capture ISO 21307 recertification revenue streams from installed automatic equipment bases. Long-term viability favors vendors with dual capability across premium stationary engineering and scalable portable production. Acquisition targets should display field technical capabilities for aftermarket service rather than pure manufacturing scale. Watch EPA enforcement intensity around weld documentation audits as the inflection indicator for automatic system upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Coil Production | Captive copper coil supply insulates margin structures from commodity volatility affecting East Asian foundry pricing. |
| Bluetooth-Enabled Data-Logging Platform Launch | Cloud-connected weld documentation satisfies EPA audit mandates while generating recurring software subscription revenue. |
| Rental Channel Partnership Expansion | Operational expenditure conversion captures municipal budget constraints favoring McElroy-style field-service network access. |
| CE Marking Recertification Service Buildout | EU F-Gas Regulation amendments create aftermarket revenue from German gas operator fleet compliance requirements. |
| Voltage-Adaptive Portable Unit Development | Compact designs address India's Jal Jeevan Mission rural infrastructure with BIS-certified configurations for unstable grid conditions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gas utility engineering directors, municipal water authority procurement managers, electrofusion equipment rental firm operators, and certified welding technician training program administrators with secondary validation against EPA pipeline safety filings, EU F-Gas Regulation amendment texts, ISO 21307 draft standard revisions, and German district heating infrastructure investment disclosures. Bottom-up equipment shipment aggregation across automatic, portable, and manual configurations triangulated against top-down utility capex and opex survey responses.
Historical reference periods anchored the projection horizon through verified installation base counts and replacement cycle analysis across pressurized gas distribution networks, municipal water infrastructure renewal programs, and telecom fiber-optic conduit deployments. Segmentation modeling incorporated product type, control technology architecture, application vertical, and end-user procurement structure dimensions. CAGRs were derived from weighted average replacement demand, new infrastructure deployment pipelines, and regulatory mandate acceleration effects. Forecast inputs included copper and semiconductor component cost trajectories, certified technician training pipeline throughput, and rental channel penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement intensity around weld traceability mandates, EU electromagnetic compatibility certification pathway changes, and East Asian foundry capacity allocation shifts affecting microcontroller availability. Forecasts reflect documented assumptions regarding infrastructure investment continuity and regulatory implementation timelines. Material deviation in copper price volatility, ISO standard finalization schedules, or Indian rural water mission funding allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Backhoes Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Jackhammer Market
Construction Equipment
Stud Welding Guns Market