
 Construction Wearable Technology Market | 2026-2036
Construction Wearable Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Wearable Technology Market Insights
Multi-source procurement for sensor hardware is broadening as general contractors diversify supplier risk across wearable platforms. German Bionic Systems GmbH anchors European exoskeleton engineering with biomechanical load-assistance patents. Trimble competes through GNSS-integrated hardhat systems that merge spatial positioning with safety telemetry. Honeywell International dominates industrial-grade environmental sensing, leveraging gas-detection modules that retrofit into connected vest architectures.
Construction wearable technology encompasses sensor-embedded personal equipment designed to monitor physiological states, environmental hazards, and spatial positioning across active jobsites, typically integrating accelerometers, gyroscopes, and wireless transceivers within IP-rated enclosures. These systems serve to prevent struck-by incidents, heat-related illness, and falls through real-time alert generation and cloud-based incident logging. Smart helmets lead product-type revenue pools due to integrated audio-visual communication and crash-detection maturity, while exoskeletons represent the fastest-expanding category as masonry and rebar crews adopt powered lift-assistance to reduce musculoskeletal claims. GPS and motion-sensor technologies command the largest technology share through proven reliability in open-air positioning, though augmented reality is gaining fastest among specialty contractors performing complex MEP overlay work.
OSHA workplace safety standards and FCC wireless device certifications shape hardware design requirements and market access timelines for domestic vendors. The EU Machinery Directive and CE marking obligations create parallel compliance burdens for equipment sold to European contractors operating across multinational project portfolios. Stakeholders must monitor evolving silica-exposure thresholds and biomechanical load-limit regulations that will determine which wearable form factors achieve mandatory-deployment status on federally funded construction sites.
Market Dynamics
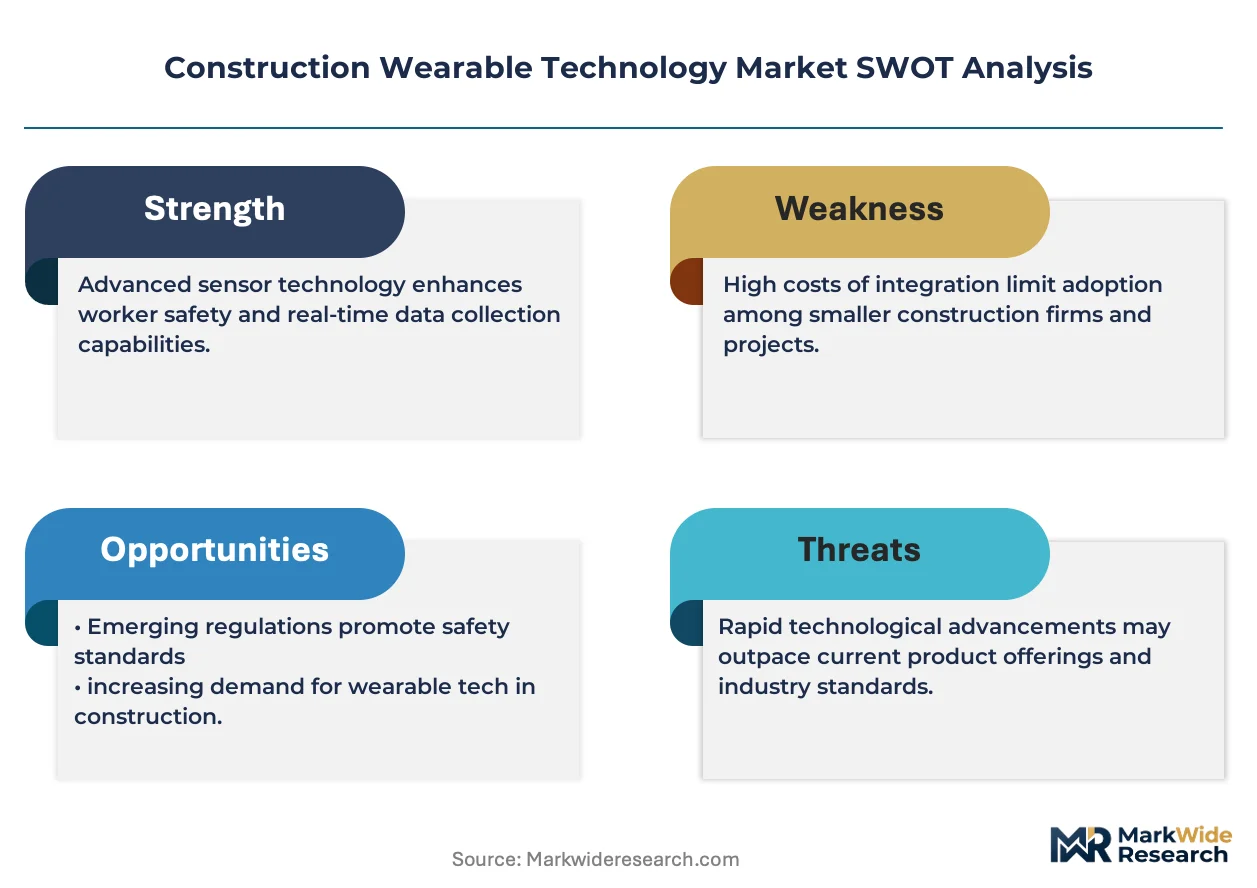
Federal infrastructure spending and OSHA's tightening stance on real-time hazard detection are compressing procurement cycles for connected safety equipment across megaproject sites.
Growth Catalysts
- OSHA silica-exposure mandates:Contractors deploy continuous particulate-monitoring vests to comply with permissible exposure limits on federally funded jobsites.
- Exoskeleton biomechanics:Powered lift-assistance systems reduce musculoskeletal injury claims among masonry and rebar crews facing repetitive load stress.
- Union labor agreements:Collective bargaining provisions in the United States now specify smart helmet and environmental sensor provisioning as standard PPE.
Market Restraints
- Lithium-ion battery volatility:Thermal runaway risks in sensor-embedded wearables complicate site storage protocols and insurance underwriting.
- IP-rated enclosure costs:Ingress protection certification for dust and moisture resistance adds 15-25% to hardware BOM versus consumer-grade alternatives.
- FCC certification timelines:Wireless transceiver approvals for multi-band operation delay product launches by 8-14 months for domestic vendors.
Strategic Opportunities
- Augmented reality convergence:AR-enabled smart glasses overlay MEP schematics for specialty contractors performing complex mechanical-electrical-plumbing coordination.
- Equipment-as-a-service models:Rental channels for exoskeletons reduce upfront capex barriers for mid-tier commercial builders.
- EU Green Deal procurement criteria:CE-marked wearables with carbon footprint disclosure gain preference in European public infrastructure tenders.
Industry Challenges
- Interoperability fragmentation:Proprietary data protocols between Trimble, Honeywell, and German Bionic platforms prevent unified site-wide safety dashboards.
- Field technician training gaps:Biomechanical calibration of powered exoskeletons requires certified fitters scarce in secondary construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Wearable Technology Market |
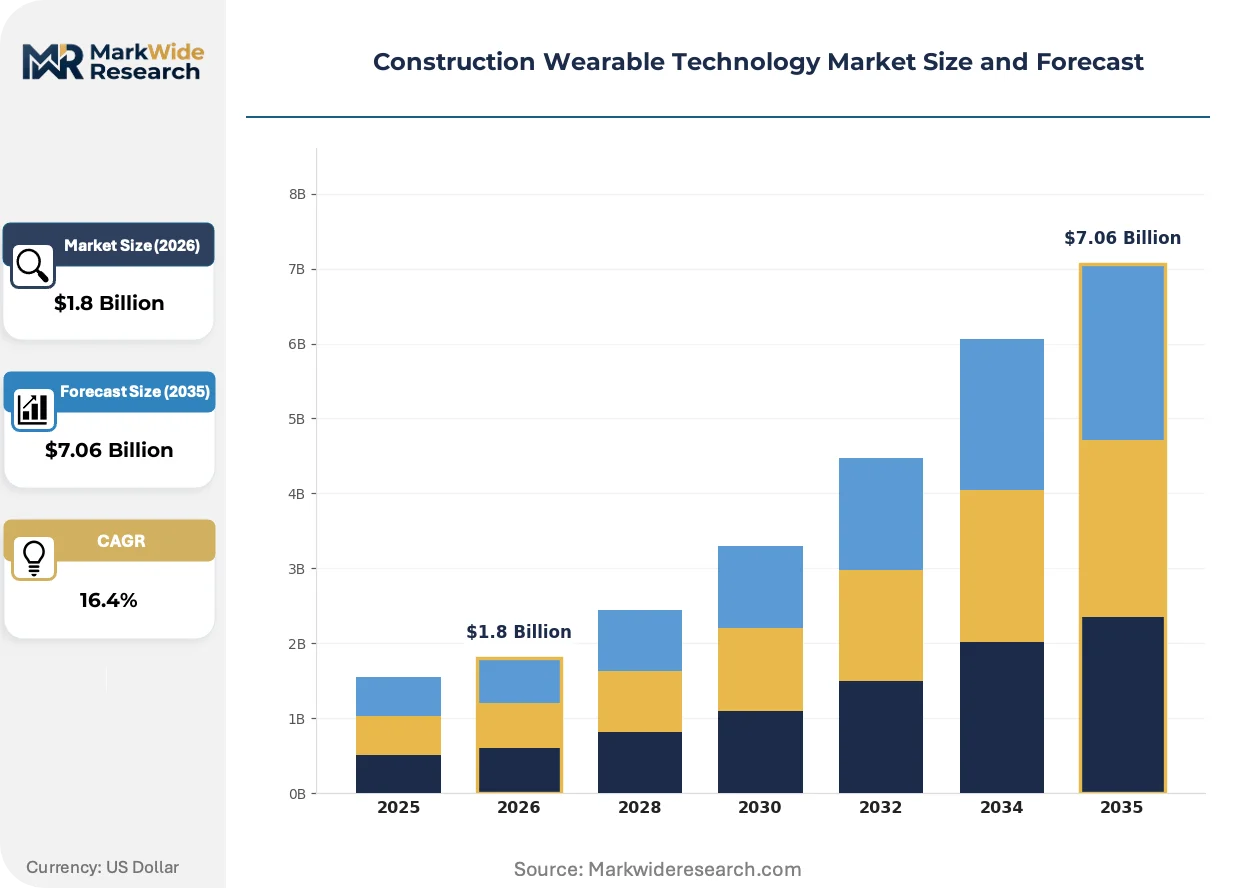
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, Safety Vests, Smart Glasses, GPS Trackers, Exoskeletons Technology: GPS, RFID, Bluetooth, Augmented Reality, Motion Sensors Application: Worker Safety Monitoring, Asset Tracking, Equipment Management, Workforce Productivity, Site Supervision End User: General Contractors, Equipment Operators, Safety Inspectors, Site Engineers, Project Managers |
| Companies Covered | 3M Company, Apple Inc., Garmin, German Bionic Systems GmbH, Honeywell International, RealWear, Siemens, Trimble, XREAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Wearable Technology Market Trends and Innovations
Sensor fusion architectures and edge-computing migration are redefining how physiological and environmental data get processed on active jobsites.
Computer vision embedded in smart helmets is overtaking standalone proximity beacons for struck-by hazard detection. Rebar and concrete crews in Texas and California deploy hardhat-mounted cameras with on-device inference to identify swinging loads without infrastructure-dependent beacon networks. The shift compresses site commissioning from weeks to days while eliminating mesh-network maintenance overhead.
OSHA's pending heat-illness prevention standard is forcing deployment of continuous core-temperature monitoring. General contractors in Arizona and Florida pilot ingestible sensors and wearable sweat-analysis patches to demonstrate compliance during summer concrete pours. The rulemaking accelerates procurement of connected cooling vests with automated ventilation triggers.
Buying committees now dominate wearable procurement decisions, displacing sole sourcing by site safety managers. Large commercial builders in the United States convene cross-functional teams spanning risk, IT, and procurement to evaluate total cost of ownership across hardware, connectivity, and cloud analytics subscriptions. This pattern concentrates contract awards with vendors offering vertically integrated platform stacks rather than point-solution specialists.
Construction Wearable Technology Market Segmentation
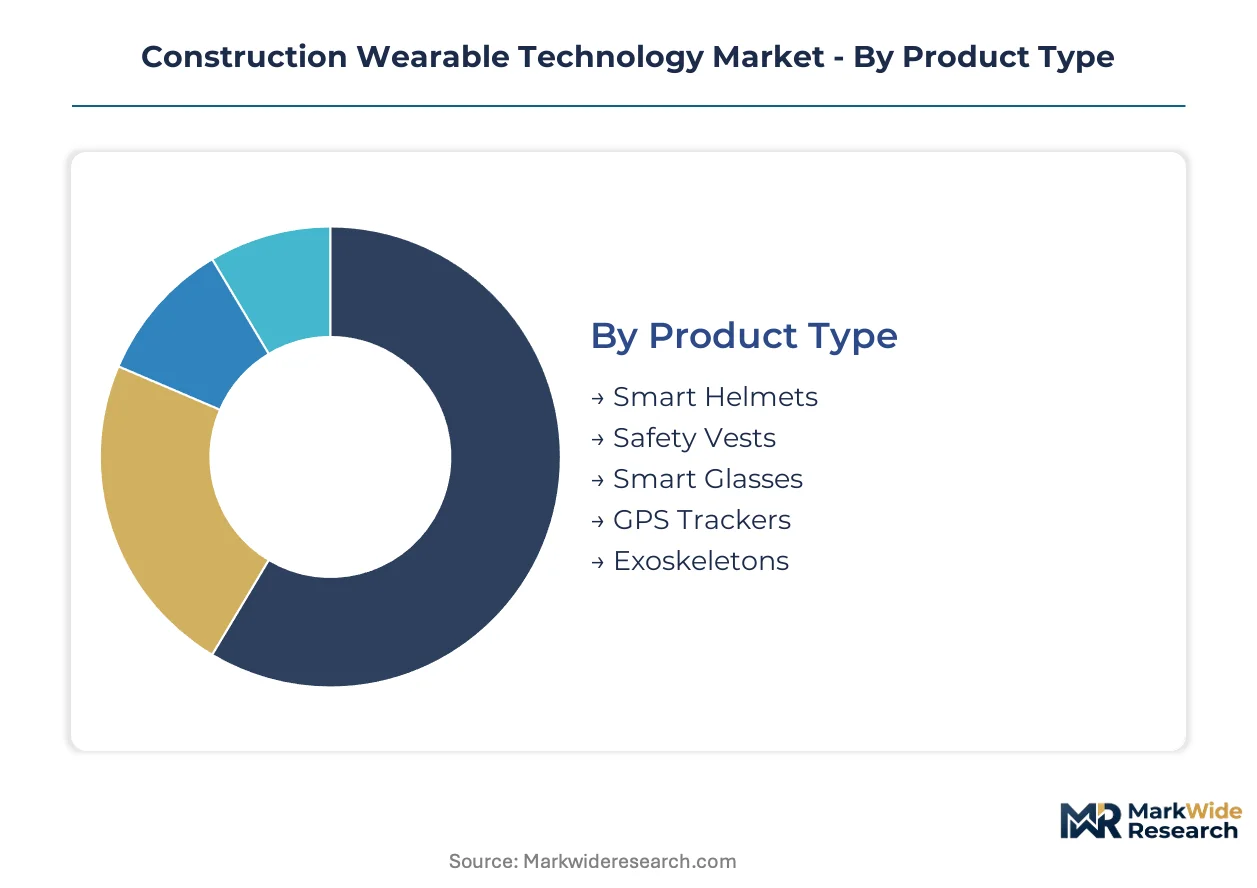
Construction wearable technology segments by product type, technology, application, and end user reveal distinct integration patterns. Standalone devices dominate procurement today, while embedded sensor architectures are displacing bolt-on configurations in large commercial builds.
Product Type:
Standalone hardhat systems command the largest procurement volumes, though vest-embedded sensor arrays are accelerating fastest in unionized megaprojects.
- Smart Helmets:Integrated audio-visual communication modules with crash-detection accelerometers and GNSS positioning. Demand concentrates among general contractors in Texas and California facing OSHA struck-by enforcement, driven by mesh-network elimination through on-device computer vision.
- Exoskeletons:Powered lift-assistance frames with biomechanical load sensors and lithium-ion power packs. Adoption clusters among masonry and rebar crews in Arizona and Florida, propelled by musculoskeletal injury claim reduction mandates in collective bargaining agreements.
- Safety Vests:Sensor-embedded fabric with particulate-monitoring and core-temperature tracking capabilities.
- Smart Glasses:AR-enabled optical systems overlaying MEP schematics for mechanical-electrical-plumbing coordination tasks.
- GPS Trackers:Standalone positioning beacons for asset and personnel location in open-air site environments.
Smart helmets lead volumes today; exoskeletons are gaining share fastest.
Technology:
Positioning and short-range protocols split procurement budgets, with spatial tracking absorbing larger shares in infrastructure-heavy deployments.
- GPS:Multi-constellation satellite positioning with RTK correction for centimeter-grade accuracy in earthmoving and grading operations. Deployment concentrates among equipment operators on federal highway projects, driven by FCC-certified module availability and proven open-air reliability.
- Augmented Reality:Optical waveguide displays with spatial anchoring for MEP overlay visualization. Demand clusters with specialty contractors in complex commercial builds, propelled by BIM-to-field workflow integration requirements.
- RFID:Passive and active tag systems for proximity-based access control and equipment authentication.
- Bluetooth:Low-energy mesh protocols for short-range personnel proximity alerting in dense structural environments.
- Motion Sensors:Accelerometer-gyroscope fusion for fall detection and ergonomic posture monitoring.
GPS dominates procurement spend; augmented reality exhibits the steepest expansion trajectory.
Application:
Safety-centric use cases absorb the majority of wearable deployments, while productivity optimization applications are climbing fastest in cost-competitive commercial segments.
- Worker Safety Monitoring:Continuous physiological and environmental hazard detection with real-time cloud logging. Concentration among general contractors on federally funded sites, driven by OSHA silica-exposure and pending heat-illness rulemaking compliance requirements.
- Workforce Productivity:Motion-pattern analysis and task-time optimization for crew efficiency benchmarking. Demand clusters with mid-tier commercial builders in secondary markets, propelled by equipment-as-a-service rental models reducing upfront sensor capex.
- Asset Tracking:Real-time location systems for high-value equipment and material inventory management.
- Equipment Management:Operator biometric verification and machinery utilization telemetry.
- Site Supervision:Remote audio-visual communication and progress documentation for off-site project management.
Worker safety monitoring leads deployment scale; workforce productivity is climbing the fastest.
End User:
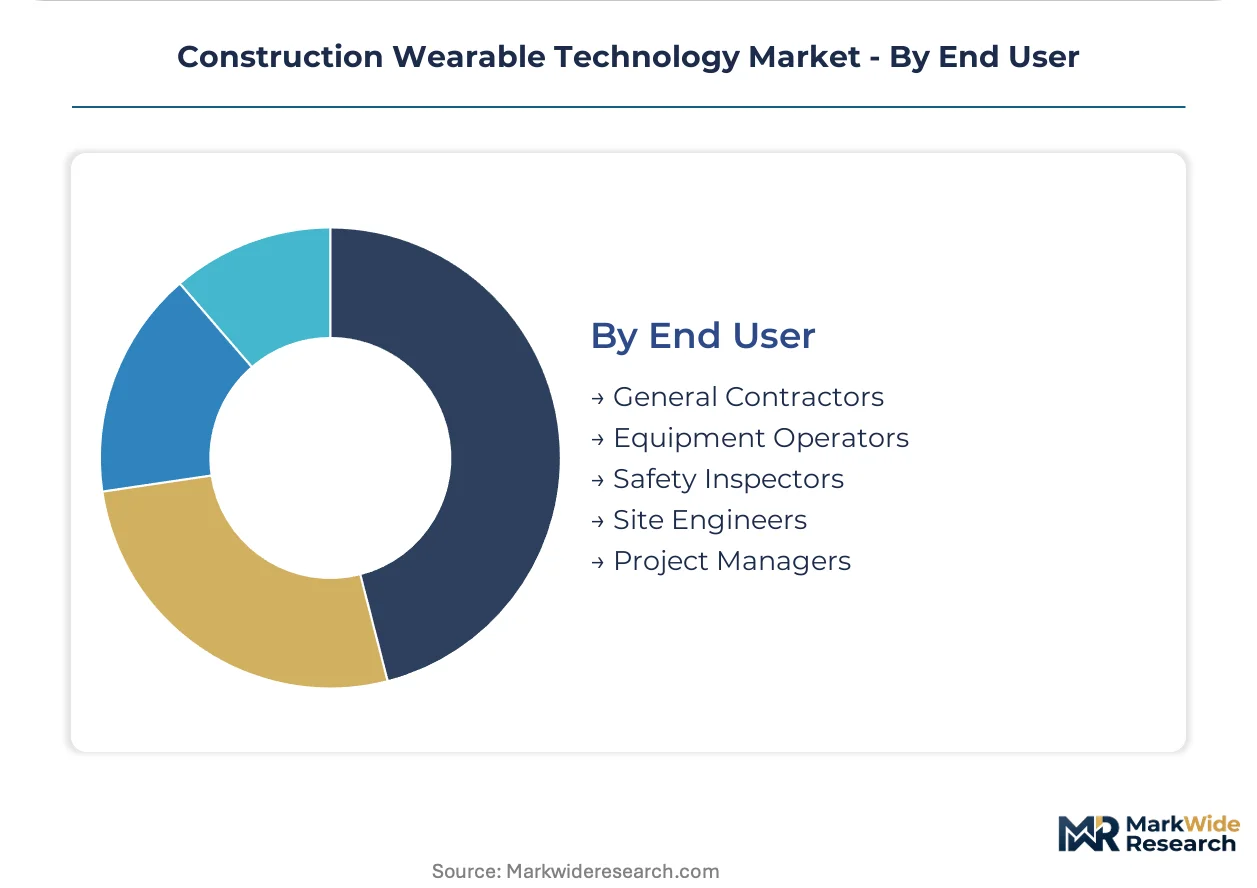
Procurement authority is shifting from site safety managers toward cross-functional buying committees spanning risk, IT, and operations functions.
- General Contractors:Enterprise-scale wearable platform procurement for multi-site safety standardization. Concentration among top-20 commercial builders in the United States, driven by total cost of ownership evaluations favoring vertically integrated vendor stacks over point solutions.
- Safety Inspectors:Mobile audit and compliance documentation tools with automated incident logging. Demand clusters in unionized jurisdictions with real-time hazard disclosure requirements, propelled by OSHA enforcement pattern documentation needs.
- Equipment Operators:Biometric-enabled machinery access and fatigue-monitoring systems.
- Site Engineers:AR-assisted layout verification and as-built documentation capture.
- Project Managers:Remote visibility dashboards integrating wearable telemetry with schedule and budget systems.
General contractors dominate procurement volume; safety inspectors are expanding their budget share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas megaproject corridors anchor construction wearable procurement volumes, where federal infrastructure spending and union labor density concentrate demand for connected safety equipment.
United States
Federal highway and transit appropriations compress procurement cycles for exoskeleton and smart helmet deployments across unionized sites. OSHA silica-exposure enforcement and pending heat-illness rulemaking mandate continuous particulate and core-temperature monitoring. The Arizona-Florida corridor pilots ingestible sensors and connected cooling vests during summer concrete operations.
Germany
Industrial exoskeleton engineering clusters around Bavarian and Baden-Württemberg manufacturing belts, driven by automotive plant construction and precision assembly applications. The EU Machinery Directive and CE marking obligations shape hardware design requirements for cross-border project portfolios. Munich-based engineering groups patent biomechanical load-assistance systems for masonry and rebar applications.
China
State-backed infrastructure stimulus accelerates smart helmet adoption across high-speed rail and urban transit megaprojects. GB standards and MIIT wireless device certifications govern domestic market access timelines for sensor-embedded PPE. Yangtze River Delta contractors integrate GNSS-integrated hardhat systems for centimeter-grade spatial positioning in earthmoving operations.
Japan
Aging workforce demographics propel powered lift-assistance procurement for construction and demolition segments. METI industrial safety guidelines and JIS standards certification requirements filter hardware vendor participation. Kanto region general contractors deploy AR-enabled optical systems for complex MEP overlay coordination in dense urban rebuilds.
United Arab Emirates
NEOM and Red Sea gigaproject timelines compress safety technology deployment schedules across Saudi-adjacent contractor networks. MOHAP workplace safety protocols and Gulf Cooperation Council harmonization efforts influence equipment specification standards. Dubai-based procurement committees evaluate total cost of ownership across vertically integrated wearable platform stacks.
Construction Wearable Technology Market Competitive Landscape
Global majors compete with regional champions across certification and integration capabilities, producing a tiered structure where scale-driven platform vendors face specialized exoskeleton engineers. The vendor base splits between vertically integrated safety conglomerates, biomechanical hardware specialists, and optical display technology firms. Dominant competitive moves include strategic partnerships for sensor fusion architectures and geographic expansion through CE-marked product lines.
Among Germany-based engineering specialists, German Bionic Systems GmbH exemplifies the powered exoskeleton archetype, while Honeywell International and Trimble occupy positions spanning industrial-grade environmental sensing and GNSS-integrated spatial positioning systems respectively.
| Leading Market Players |
|---|
| 3M Company |
| Apple Inc. |
| Garmin |
| German Bionic Systems GmbH |
| Honeywell International |
| RealWear |
| Siemens |
| Trimble |
| XREAL |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between FCC-compliant smart helmets and uncertified consumer alternatives splits procurement budgets and supplier networks simultaneously across the construction wearable technology market. Premium-tier vendors absorb 15-25% hardware cost premiums for IP-rated enclosures and multi-band wireless approvals, while commodity suppliers compete on stripped-down sensor arrays lacking OSHA-mandated environmental monitoring capabilities.
Pricing Analysis
Input-cost pass-through from lithium-ion power packs and MEMS sensor modules shapes hardware pricing across tiered product architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FCC and CE marking tiers commanding substantial premiums over uncertified alternatives. Cost compression in standard-tier exoskeletons intensifies because Chinese sensor suppliers are scaling MEMS production for industrial applications. Mid-tier commercial builders exhibit highest price sensitivity, while unionized megaproject contractors prioritize compliance-grade equipment regardless of unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from top-20 general contractors, while rental-as-a-service distributors serve price-sensitive mid-tier builders. Component manufacturing concentrates in China, South Korea, and Germany, with Shenzhen supplying MEMS accelerometers, Seoul providing lithium-ion cells, and Bavaria specializing in precision exoskeleton frames. Hardware BOMs draw from rare earth magnet dependencies for motor assemblies and semiconductor shortages for edge-computing modules. Single-source vulnerability in FCC-certified wireless module supply creates procurement bottlenecks for domestic vendors. Distribution runs through construction equipment lessors and safety distributor networks with certified fitter capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA's pending heat-illness prevention standard functions as a regulatory compounder, mandating continuous physiological monitoring that expands addressable hardware demand across federally funded sites.
For Market Incumbents: Cement platform stickiness through backward integration into cloud analytics subscriptions that lock general contractors into vertically integrated vendor stacks. Deepen certification moats by accelerating CE marking for European infrastructure tenders before EU Green Deal procurement criteria harden. Sensor fusion patent portfolios defend against modular point-solution entrants threatening unified dashboard architectures. For New Entrants and Emerging Players: Launch via equipment-as-a-service rental channels to bypass upfront capex barriers among mid-tier commercial builders in secondary U.S. markets. Target exoskeleton biomechanical calibration services where certified fitter scarcity constrains incumbent deployment velocity. Specialty contractor AR glasses for MEP coordination represent the most penetrable white-space segment. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary data protocols prevent interoperability between Trimble, Honeywell, and German Bionic platform ecosystems. Long-term viability favors vendors with captive sensor hardware production and FCC certification expertise rather than software-only overlays. Acquisition target archetypes include CE-marked exoskeleton engineers with automotive plant construction relationships. Watch for OSHA silica-exposure enforcement patterns as inflection indicator for particulate-monitoring vest procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Unified physiological and environmental data streams enable site-wide safety dashboards for general contractors. |
| CE Marking Pathway Acceleration | EU Machinery Directive compliance unlocks European public infrastructure tenders with carbon disclosure preferences. |
| Equipment-as-a-Service Launch | Rental models reduce upfront capex barriers for mid-tier commercial builders in secondary U.S. markets. |
| Biomechanical Calibration Certification | Certified fitter networks address scarcity constraints limiting exoskeleton deployment in unionized jurisdictions. |
| AR-Enabled Smart Glasses Integration | BIM-to-field workflow integration captures specialty contractor demand for complex MEP coordination tasks. |
Research Methodology
Bottom-up general contractor procurement modeling reconciled against top-down sensor hardware production tracking forms the analytical core of this study. Primary interviews with site safety managers, construction equipment lessors, union bargaining representatives, and FCC certification consultants combined with secondary validation from OSHA enforcement databases, SEC equipment supplier filings, and construction industry trade association reports. Triangulation between demand-side procurement patterns and supply-side manufacturing capacity ensures cross-verified market sizing.
Input-output matrices map exoskeleton unit volumes against lithium-ion cell supply, smart helmet shipments against MEMS sensor foundry capacity, and AR glasses adoption against optical waveguide production yields across the analysis window. Segmentation dimensions include product type, technology protocol, application use case, end-user archetype, and regional regulatory cluster. CAGRs derive from regression analysis of historical procurement cycles against OSHA rulemaking timelines and federal infrastructure appropriation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated OSHA enforcement scenarios or lithium-ion thermal runaway incidents triggering site storage bans. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Industrial Nailers Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Global Welding Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Press Brakes Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Autonomous Construction Equipment Market