
 Cold Heading Machine Market | 2026-2036
Cold Heading Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Heading Machine Market Intelligence
Germany's precision engineering corridor is fragmenting as multiple equipment builders expand cold heading capacity simultaneously. Hatebur Umformmaschinen AG anchors its position through deep specialization in high-speed multi-station architectures for automotive tier-one suppliers. SACMA Limbiate S.p.A. competes aggressively from its Italian manufacturing base, leveraging integrated servo-electric technology development. Nakashimada Engineering Works Ltd differentiates through precision small-diameter machines serving electronics and medical component markets across East Asia.
A cold heading machine forms metal wire or rod into complex shapes through successive die strikes without material loss, typically processing diameters from 0.5 mm to 40 mm at stroke rates exceeding 300 per minute for high-volume fastener and component production. Multi-station machines dominate volume shipments to automotive suppliers where transfer sequences produce finished bolts and screws in single cycles, while programmable machines capture expanding margin pools in aerospace lot-size-one manufacturing. Electric technology architectures displace legacy hydraulic systems in European and Japanese installations where energy efficiency standards tighten operational cost structures.
EU REACH and RoHS frameworks restrict lubricant chemistries and surface treatment substances used in cold forming processes, compelling machine builders to certify dry-process compatibility. Japan's METI energy efficiency benchmarks shape electric and hybrid technology roadmaps for equipment sold into domestic automotive supply chains. China's GB standards and MIIT industrial upgrading directives mandate localized control system architectures for imported metalworking equipment. Stakeholders must monitor how dual carbon compliance timelines in Beijing and Brussels reshape capital equipment specification criteria across export markets.
Market Dynamics
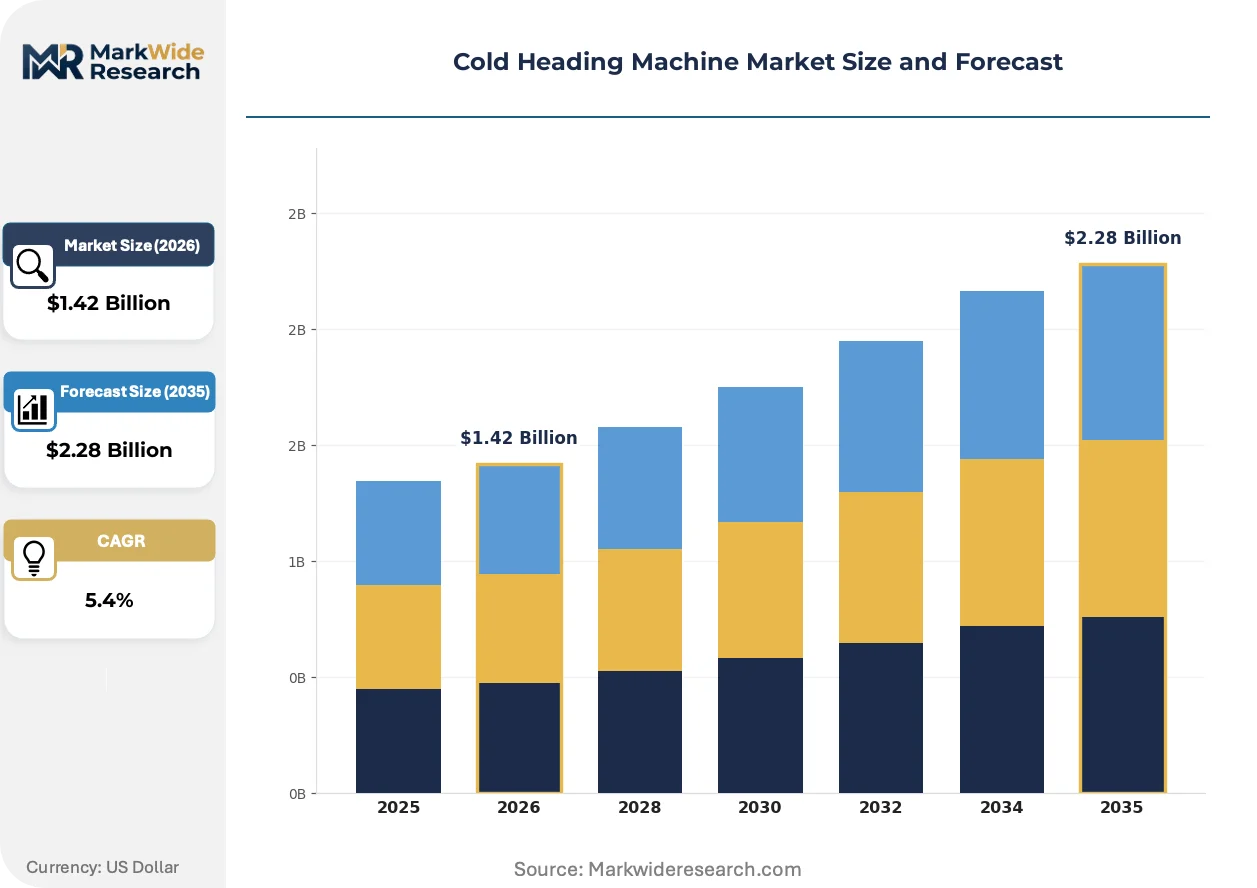
Electric servo architectures are compressing operating cost structures and compelling equipment replacement cycles across automotive fastener supply chains, while REACH compliance mandates force dry-forming process redesigns.
Growth Catalysts
- EU REACH lubricant restrictions:Dry-forming machine architectures open new specification windows for European OEMs seeking exemption from metalworking fluid compliance costs. Equipment builders certify process compatibility to capture replacement demand.
- EV fastener programs:Automotive suppliers in Germany and Japan expand cold heading capacity to serve electric vehicle platform bolt and screw specifications requiring higher strength-to-weight ratios.
- MIIT industrial upgrading directives:China's mandates for localized control systems on imported metalworking equipment create captive demand for joint-venture machine architectures in the Yangtze River Delta.
Market Restraints
- Specialized alloy input volatility:Cold heading-grade wire rod supply concentrates among a limited base of European and East Asian metallurgical suppliers, exposing machine operators to nickel and chromium price swings.
- Multi-station machine footprint constraints:Physical installation requirements for high-volume automotive lines exceed available floor space at tier-two supplier facilities in dense industrial zones.
- Hydraulic system obsolescence risk:Legacy installed base depreciation accelerates as METI energy efficiency benchmarks render older architectures uneconomical for Japanese domestic buyers.
Strategic Opportunities
- Aerospace lot-size-one manufacturing:Programmable cold heading machines capture margin pools in titanium and Inconel fastener applications where batch sizes below 500 units previously excluded mechanical forming.
- India's Pune-Aurangabad corridor:Precision component clusters in Maharashtra state lack indigenous high-speed multi-station capacity, creating white space for equipment localization partnerships.
- Dual carbon compliance timelines:Beijing's 2060 net-zero targets and Brussels' 2050 climate neutrality reshape capital equipment specification criteria, favoring electric and hybrid technology roadmaps in export markets.
Industry Challenges
- Servo-electric technician scarcity:Machine tool maintenance functions require skill sets spanning mechanical alignment, PLC programming, and power electronics diagnostics that outpace vocational training pipeline output.
- GB standards certification timelines:China's mandatory control system localization reviews extend equipment approval cycles by 8-14 months for European and Japanese builders.
- Legacy hydraulic integration friction:Brownfield installations face control architecture mismatches when retrofitting electric feed systems to existing die stations and transfer mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Heading Machine Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Station Machines, Single-Station Machines, Programmable Machines, Automated Machines End User: Aerospace, Automotive Suppliers, Electronics Manufacturers, Construction Material: Steel, Aluminum, Copper, Titanium Technology: Hydraulic, Pneumatic, Electric, Hybrid |
| Companies Covered | National Machinery LLC, Hatebur Umformmaschinen AG, Chun Zu Machinery Industry Co. Ltd, GFM GmbH Steyr, Nakashimada Engineering Works Ltd, SACMA Limbiate S.p.A., Asahi Sunac Corporation, Sakamura Machine Co. Ltd, Nedschroef Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Heading Machine Market Strategic Shifts & Innovations
Active innovation fronts concentrate on energy architecture substitution, regulatory chemistry compliance, and buyer procurement model compression across precision component supply chains.
Servo-electric drive systems eliminate hydraulic power units and cooling infrastructure from cold heading machine footprints. Automotive tier-one suppliers in Germany and Japan specify all-electric architectures for new capacity installations. This transition is rendering obsolete the aftermarket service revenue streams tied to hydraulic fluid maintenance and seal replacement.
REACH Annex XVII restrictions on chlorinated paraffins and boron-based lubricants force formulation changes in metalworking fluids. Machine builders now certify dry-process compatibility and minimal-lubrication architectures to maintain European market access. Automotive fastener producers bear the highest compliance burden, accelerating capital equipment replacement to avoid process chemistry penalties.
After-sales service unbundling separates maintenance contracts from initial equipment sales. Tier-two fastener manufacturers in China's Yangtze River Delta increasingly procure machine-hours or output-guarantee arrangements rather than traditional parts-and-labor service agreements. This compression is most visible among mid-volume producers seeking to convert fixed maintenance costs to variable operating expenses.
Cold Heading Machine Market Segmentation
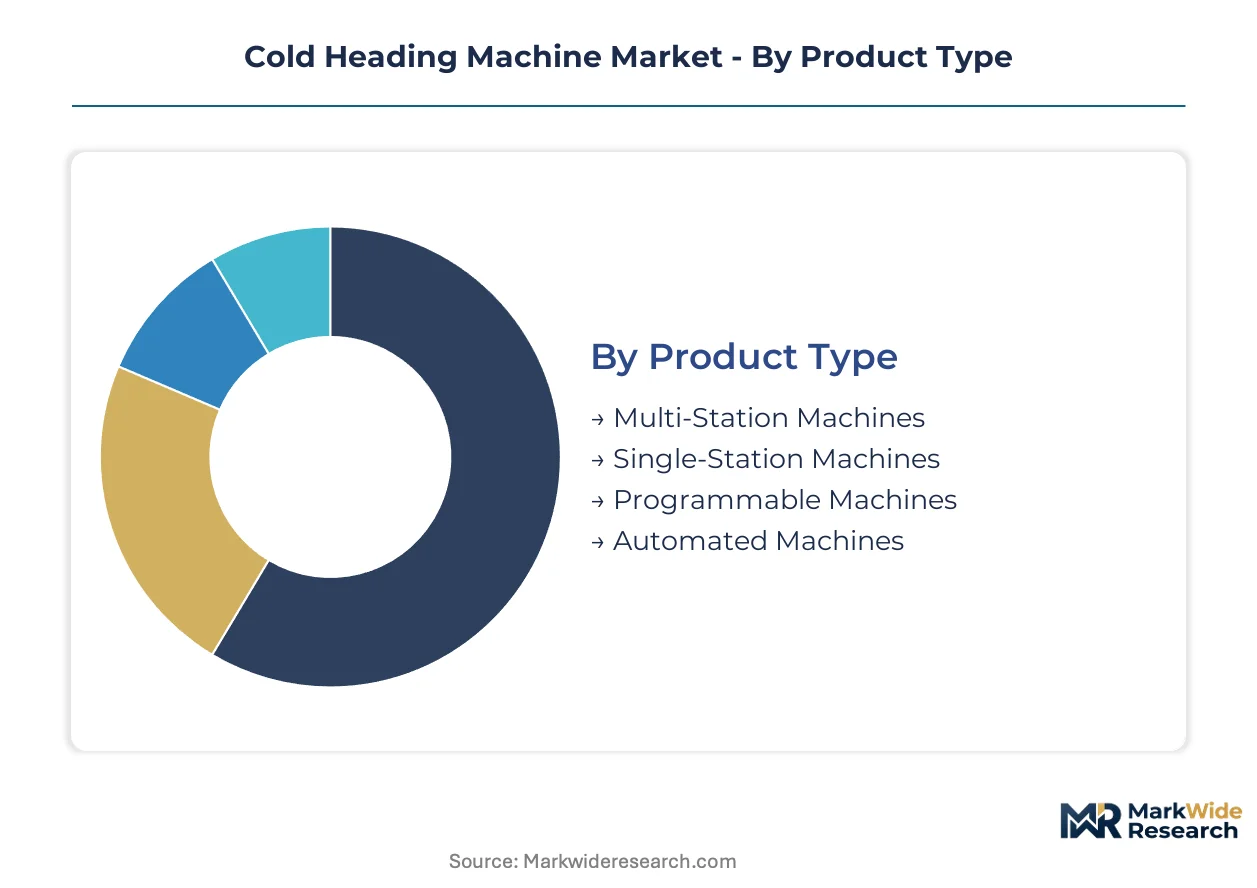
Cold heading machine procurement patterns diverge sharply across product architectures and end-use requirements. After-sales service intensity varies dramatically by segment, with multi-station automotive lines demanding continuous uptime contracts while programmable aerospace units require specialized technician deployment.
Product Type:
After-sales service intensity peaks with multi-station architectures where die wear and transfer mechanism alignment demand continuous technical presence.
- Multi-Station Machines:These architectures sequence 4-6 die strikes in single cycles, producing finished bolts and screws without material transfer between machines. Automotive tier-one suppliers in Germany specify these for EV fastener programs requiring 300+ strokes per minute. Service contracts typically bundle predictive maintenance with die refurbishment schedules.
- Programmable Machines:CNC-controlled stroke parameters and die positioning enable rapid changeover between part numbers. Aerospace manufacturers in Japan leverage these for titanium fastener batches below 500 units. The programming complexity elevates service technician skill requirements and extends commissioning timelines.
- Single-Station Machines:Basic two-die configurations serve low-volume construction fastener producers with minimal automation requirements.
- Automated Machines:Integrated feeding and ejection systems reduce labor content for high-volume electronics component manufacturing.
Multi-Station Machines hold the largest share; momentum sits with Programmable Machines.
End User:
Cost tier differentiation separates capital equipment specifications across buyer categories, with aerospace procurement budgets exceeding automotive tier-two allocations by substantial margins.
- Automotive Suppliers:Tier-one fastener manufacturers in Germany and Japan dominate volume demand, specifying electric architectures to meet METI efficiency benchmarks and EU REACH dry-forming requirements. EV platform transitions are accelerating replacement cycles for hydraulic legacy equipment.
- Aerospace:Precision requirements for titanium and Inconel fasteners drive specification toward programmable machines with closed-loop force monitoring. Lot-size-one manufacturing patterns favor output-guarantee procurement models over traditional equipment purchase.
- Electronics Manufacturers:Miniature component production in China's Yangtze River Delta concentrates demand for small-diameter precision machines.
- Construction:Standardized bolt specifications permit lower-cost single-station equipment with reduced automation content.
Automotive Suppliers command the largest installed base; Aerospace is expanding most quickly.
Material:
Application requirements determine feedstock compatibility specifications, with specialized alloys demanding customized die materials and lubrication architectures.
- Steel:Cold heading-grade wire rod constitutes the majority of processed volume across automotive fastener applications. Nickel and chromium price volatility exposes operators to margin compression when alloy surcharges escalate.
- Titanium:Aerospace fastener specifications require specialized die coatings and reduced stroke speeds to prevent work hardening. The material's reactivity with standard lubricants necessitates dry-forming process certification.
- Aluminum:Electronics and lightweight automotive applications favor aluminum for its formability at lower tonnage requirements.
- Copper:Electrical connector manufacturers specify copper for conductivity-critical applications with moderate strength requirements.
Steel dominates current processing volumes; Titanium is gaining share fastest.
Technology:
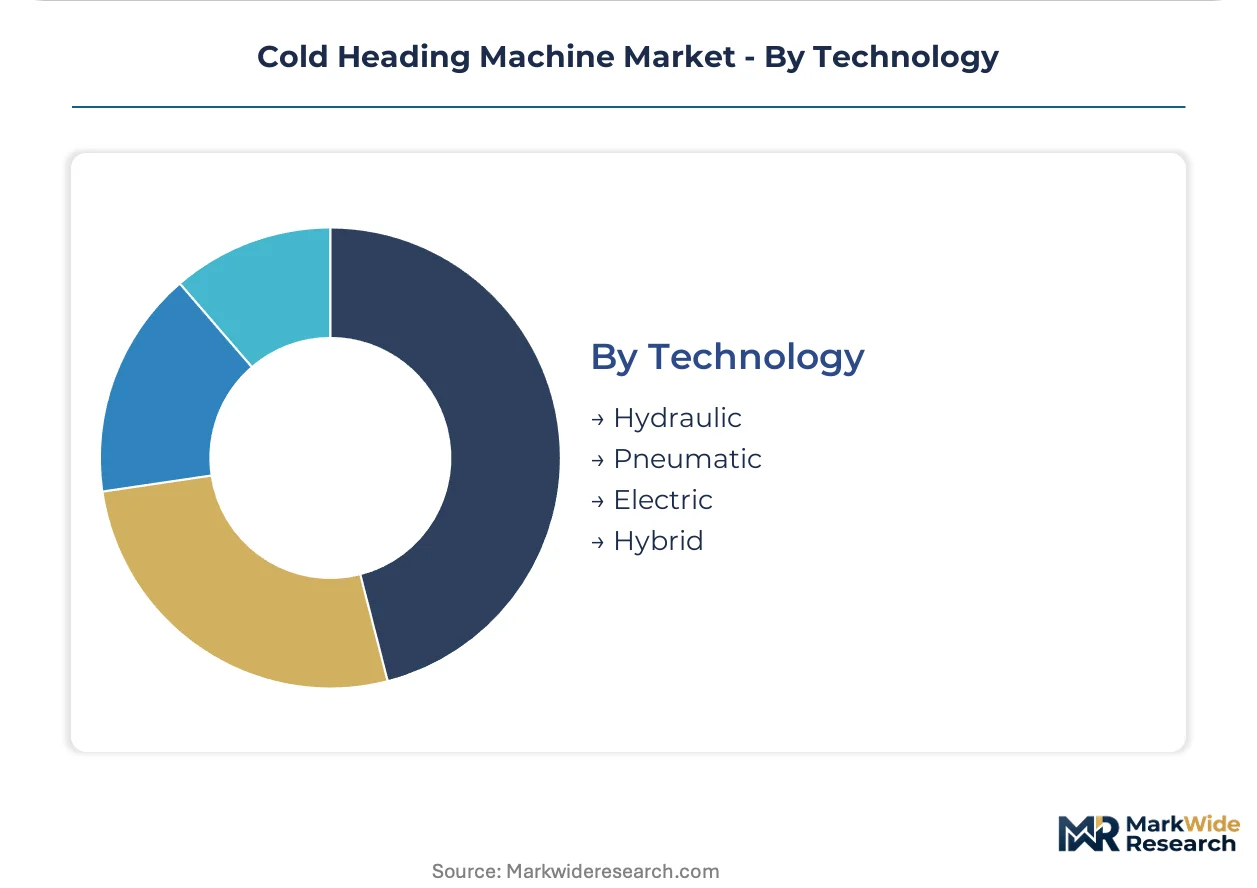
Customer type stratification separates buyers pursuing energy efficiency compliance from those prioritizing lowest first-cost acquisition.
- Electric:Servo-driven architectures eliminate hydraulic power units and cooling infrastructure, compressing factory footprints. METI benchmarks and EU energy efficiency standards are rendering electric specification mandatory for new installations in Japan and Europe.
- Hybrid:Combined electric feed systems with hydraulic main drives offer transitional architectures for brownfield upgrades where full electric replacement is capital-constrained.
- Hydraulic:Legacy installed base depreciation accelerates as regulatory standards tighten, though residual demand persists in cost-sensitive construction fastener segments.
- Pneumatic:Limited to specialized small-diameter applications where stroke force requirements remain below electric actuator thresholds.
Hydraulic retains the largest installed base; Electric is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in precision machinery exports, while the Yangtze River Delta's manufacturing density anchors Asia-Pacific demand for cold heading capacity.
Germany
Automotive tier-one suppliers in Baden-Württemberg and Bavaria drive multi-station machine procurement for EV fastener programs. REACH Annex XVII restrictions on chlorinated paraffins compel dry-forming process adoption across the precision engineering corridor. Stuttgart's industrial cluster hosts simultaneous capacity expansions by multiple equipment builders serving continental OEMs.
China
MIIT industrial upgrading directives mandate localized control architectures for imported metalworking equipment. GB standards certification extends approval timelines for European and Japanese builders. The Yangtze River Delta's electronics manufacturers concentrate demand for small-diameter precision machines with integrated automation.
Japan
METI energy efficiency benchmarks render hydraulic legacy architectures uneconomical for domestic buyers. Automotive supply chains in Aichi Prefecture specify all-electric servo systems for new capacity installations. Tokyo-based precision component producers leverage programmable machines for titanium fastener batches below 500 units.
United States
The US Midwest's automotive fastener clusters face floor space constraints for high-volume multi-station lines. EPA industrial emissions frameworks influence lubricant chemistry specifications at tier-two supplier facilities. Michigan and Ohio precision component manufacturers prioritize brownfield electric retrofits over greenfield hydraulic installations.
India
Maharashtra's Pune-Aurangabad corridor lacks indigenous high-speed multi-station capacity for precision fastener production. BIS certification requirements shape equipment specification criteria for imported metalworking machinery. Gujarat's emerging automotive component clusters attract joint-venture proposals from European and East Asian machine builders.
Cold Heading Machine Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in die and tooling supply. The vendor base concentrates among German, Japanese, and Italian machinery builders with deep automotive supply chain relationships. Three archetypes dominate: high-speed multi-station specialists, precision small-diameter engineers, and servo-electric technology pioneers. Capacity expansion and technology licensing represent the dominant competitive moves as electric architectures displace legacy hydraulic systems.
Among German-based fabricators, Hatebur Umformmaschinen AG and GFM GmbH Steyr exemplify the high-volume automotive tier-one supply archetype. SACMA Limbiate S.p.A. represents Italian engineering integration with servo-electric development capabilities. Nakashimada Engineering Works Ltd anchors the precision small-diameter segment serving East Asian electronics and medical component markets.
| Leading Market Players |
|---|
| National Machinery LLC |
| Hatebur Umformmaschinen AG |
| Chun Zu Machinery Industry Co. Ltd |
| GFM GmbH Steyr |
| Nakashimada Engineering Works Ltd |
| SACMA Limbiate S.p.A. |
| Asahi Sunac Corporation |
| Sakamura Machine Co. Ltd |
| Nedschroef Machinery |
| Others |
Cost & Logistics Intelligence
Cold heading-grade wire rod supply concentrates among European and East Asian metallurgical suppliers, anchoring margin pools at machine builders who certify dry-forming process compatibility for REACH-compliant European OEMs. This upstream concentration forces tier-one automotive fastener producers to absorb alloy surcharge volatility while competing for allocation during nickel and chromium price spikes.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure across the cold heading machine market, separating premium electric servo architectures from legacy hydraulic systems. Three-tier pricing stratifies across premium certified-electric, standard hybrid-transition, and economy hydraulic-residual levels. Price differentiation hinges on energy efficiency certification grade and after-sales service bundling intensity. Cost compression in the standard tier is intensifying because METI benchmarks render older architectures uneconomical for Japanese domestic buyers. Tier-two fastener manufacturers in China's Yangtze River Delta exhibit highest price sensitivity, while aerospace lot-size-one producers prioritize output-guarantee procurement over first-cost minimization.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk assessment for cold heading machine builders serving dual-market OEMs. Manufacturing concentration centers on Germany, Japan, and Italy for complete machine fabrication, with control system components sourced from Taiwan and South Korea. Raw material dependencies rest on cold heading-grade wire rod, specialized die coatings, and servo-electric drive modules. Single-source vulnerability persists in high-precision linear actuator supply from Japanese specialty manufacturers. Distribution runs through automotive tier-one supplier procurement channels with long-term framework agreements, supplemented by regional equipment distributors serving tier-two construction fastener producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold heading machine market sits in early-cycle expansion as electric servo architectures displace legacy hydraulic systems across automotive fastener supply chains. EV platform transitions and REACH dry-forming mandates create simultaneous replacement demand across European and East Asian installed bases.
For Market Incumbents: Build captive aftermarket service networks as the primary moat against unbundling pressure from tier-two buyers seeking machine-hour arrangements. Deepen die refurbishment capabilities in the Yangtze River Delta to capture MIIT-mandated localization demand. Defend against SACMA's servo-electric aggression by accelerating joint-venture control system architectures for Chinese GB certification timelines.
For New Entrants and Emerging Players: Establish a beachhead in India's Pune-Aurangabad precision component corridor where indigenous high-speed multi-station capacity remains absent. Target programmable machine segments for titanium fastener applications where incumbent service technician scarcity extends commissioning timelines. Pursue technology licensing arrangements with European builders seeking BIS certification pathways for Maharashtra state procurement.
For Investors and Strategic Acquirers: Capital is best deployed toward servo-electric technology pioneers with established METI efficiency certification and REACH dry-forming process validation. Long-term viability favors builders who control both machine architecture and die coating IP for specialized alloy applications. Watch for inflection when China's dual carbon compliance timelines accelerate electric specification mandates beyond current MIIT directives.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Architecture Transition | METI benchmarks and EU REACH compliance render hydraulic systems obsolete for tier-one automotive procurement. |
| Joint Venture Localization | MIIT mandates for GB-certified control systems require captive manufacturing presence in the Yangtze River Delta. |
| Aftermarket Service Unbundling | Machine-hour procurement models convert fixed maintenance costs to variable operating expenses for tier-two buyers. |
| Die Coating Technology Licensing | Titanium fastener applications demand specialized surface treatments that prevent work hardening during cold forming. |
| India Manufacturing Footprint | BIS certification requirements and precision component cluster growth in Maharashtra create first-mover advantages. |
Research Approach
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with tier-one automotive fastener producers in Germany and Japan, precision component manufacturers in China's Yangtze River Delta, and emerging buyers in India's Pune-Aurangabad corridor. Secondary validation drew from MIIT industrial upgrading directives, METI energy efficiency benchmark disclosures, EU REACH Annex XVII restriction schedules, and customs data on cold heading machine trade flows. Bottom-up equipment shipment analysis and top-down automotive fastener demand modeling were triangulated against control system localization requirements.
Scenario-bracketing around alloy price volatility, regulatory acceleration timelines, and electric technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include machine architecture type, end-use industry vertical, technology generation, material processed, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and EV platform penetration assumptions. Industry-specific forecast inputs incorporated die wear rates by material type and servo-electric technician training pipeline output.
Stress conditions across nickel and chromium price bands, REACH enforcement intensity, and GB certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EV fastener program ramp schedules and METI benchmark phase-in compliance deadlines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Demolition Vessels Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Welding Equipment Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Mill Pulverizer Market