
 Industrial Wood Chipper Market | 2026-2036
Industrial Wood Chipper Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wood Chipper Market Analytics
Electrification of mobile material processing is narrowing the performance gap between diesel and battery-driven industrial wood chippers in medium-duty applications. Vermeer leverages its horizontal grinder architecture to compete in biomass preprocessing. Bandit Industries anchors its position through specialized drum-chipper configurations for forestry contractors. Morbark dominates the heavy-duty stationary segment with in-house production of high-torque feed systems.
An industrial wood chipper is a mechanized size-reduction machine that employs a drum, disc, or screw mechanism to fracture wood material into uniform chips ranging from 10 mm to 50 mm, serving biomass fuel production, pulp feedstock, and land-clearing operations. Portable chippers lead volume sales due to contractor fleet flexibility requirements, while stationary units command higher margin pools from pulp mill and pellet plant installations. Electric models represent the fastest-expanding product category as municipal noise ordinances and emissions zones tighten across European cities.
The EPA Nonroad Compression-Ignition standards in the United States and the EU Stage V emissions framework jointly compel engine retooling and aftertreatment investments, directly raising equipment cost structures and reshaping manufacturer R&D priorities. OSHA machine-guarding mandates and ISO 21873 mobile crusher safety specifications further constrain design freedom while creating compliance barriers for new entrants. Stakeholders must monitor battery energy density trajectories and charging infrastructure buildouts to time capital commitments between diesel residual value erosion and electric total-cost-of-ownership crossover.
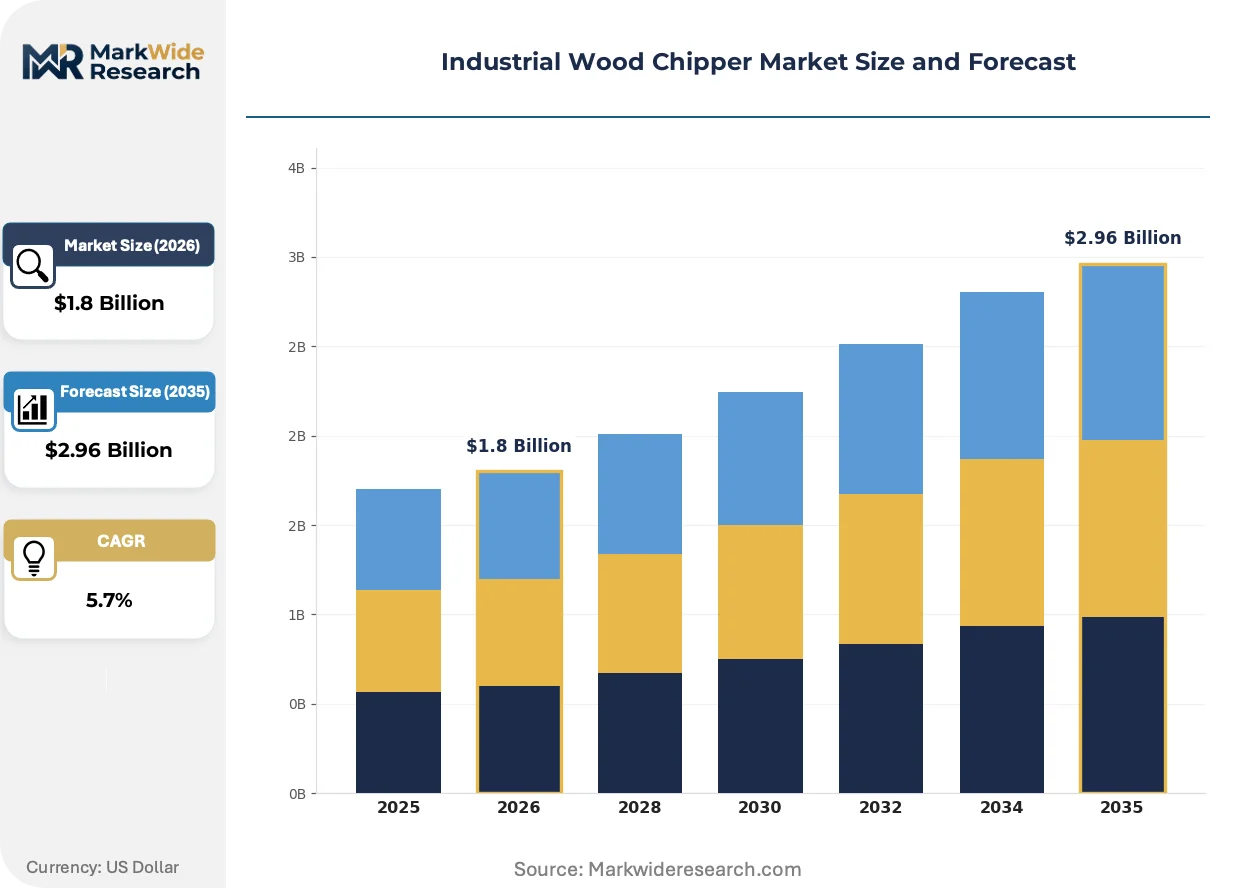
Market Dynamics
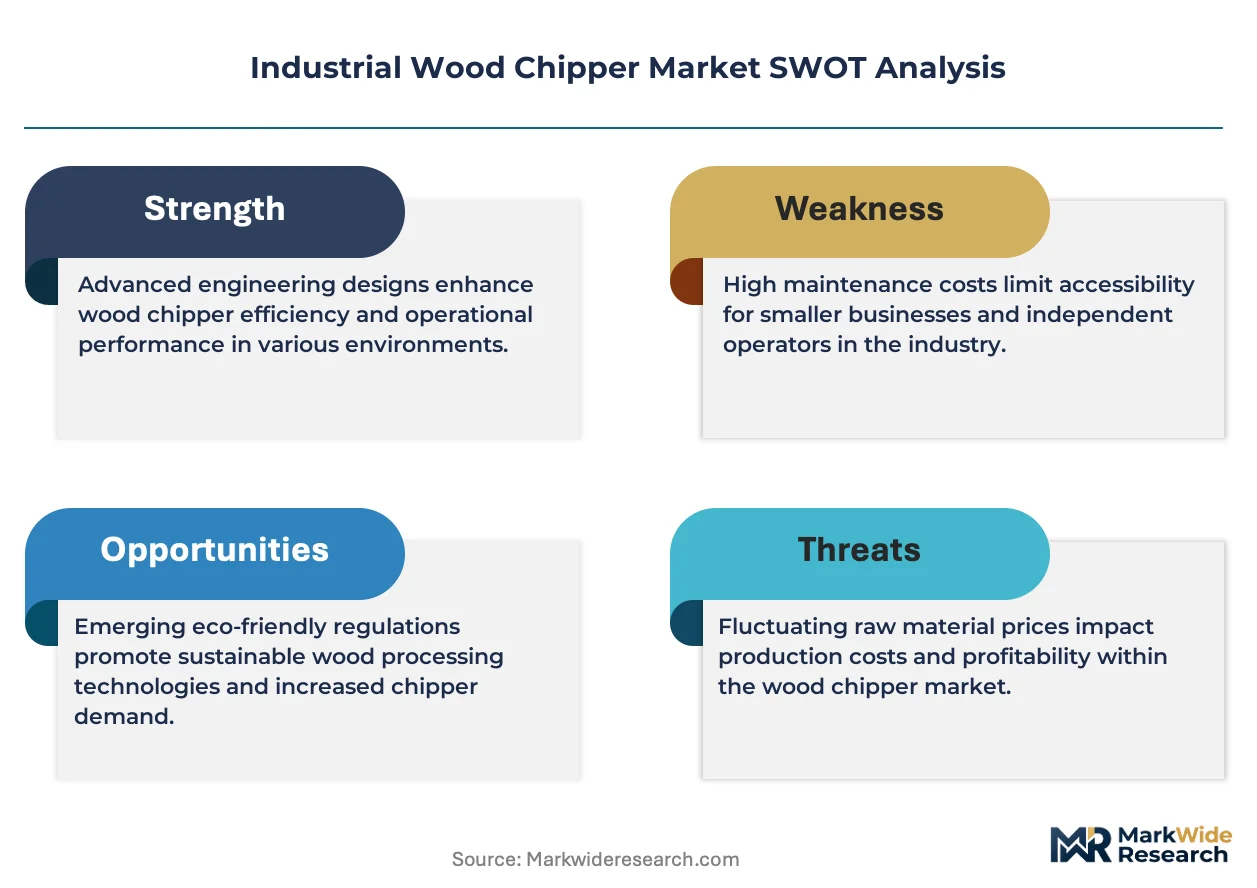
Diesel-to-electric powertrain conversion is compressing replacement cycles across European contractor fleets as EU Stage V emissions mandates and municipal noise ordinances converge to reshape equipment procurement criteria.
Growth Catalysts
- EU Green Deal biomass targets:Municipal waste management programs in Germany are expanding chipper procurement to meet renewable energy quotas, creating sustained demand for high-throughput preprocessing equipment.
- Drum-chipper mechanization:Forestry contractors across Scandinavia are replacing manual processing with automated feed systems to reduce labor exposure and increase chip uniformity for pellet plant specifications.
- Battery energy density gains:Lithium-ion pack improvements are extending electric chipper runtime to match half-day diesel duty cycles, enabling deployment in urban land-clearing operations previously reserved for combustion units.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for high-grade alloys and precision pumps compress manufacturer margins and complicate long-term contract pricing with pulp mill buyers.
- Engine supplier concentration:Tier-1 diesel powertrain sourcing clusters among a handful of European and Japanese suppliers, exposing fleet operators to allocation constraints during emissions transition periods.
- Electric charging infrastructure gaps:Rural forestry sites in Finland and Sweden lack high-capacity grid connections, limiting electric chipper deployment to municipal yards and peri-urban corridors.
Strategic Opportunities
- Austrian pellet plant integration:Biomass fuel producers in Styria and Upper Austria are seeking captive preprocessing capacity, creating demand for stationary high-torque installations with direct conveyor feed.
- Rental channel expansion:Equipment-as-a-service models are penetrating the German forestry contractor segment, reducing upfront capital barriers and accelerating electric model trial adoption.
- EU Stage V retrofit incentives:National scrappage programs in France and Italy are subsidizing diesel-to-electric fleet transitions, opening replacement windows for municipal procurement departments.
Industry Challenges
- Mechatronics technician scarcity:Electric powertrain diagnostics and battery management system repair skills lag fleet electrification timelines, extending downtime for early-adopter contractors.
- ISO 21873 compliance complexity:Mobile crusher safety certification timelines stretch 14-18 months for new drum-chipper configurations, delaying product launches and freezing R&D roadmaps.
- Legacy hydraulic system integration:Hybrid architectures combining electric motors with existing feed mechanisms require proprietary control software, fragmenting supplier ecosystems and complicating aftermarket service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wood Chipper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Towable, Electric Application: Landscaping, Waste Management, Forestry, Biomass Production Feed Type: Chips, Logs, Brush, Yard Waste End User: Commercial, Industrial, Municipal, Agricultural |
| Companies Covered | Vermeer, Bandit Industries, Morbark, Terex, Peterson, J.P. Carlton, Timberwolf, GreenMech, Bruks Siwertell Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wood Chipper Market Evolving Landscape
Telematics-enabled predictive maintenance is rewiring service relationships between manufacturers and fleet operators, shifting value capture from equipment sales to uptime guarantees and performance-based contracts.
Advanced battery management systems with cell-level thermal monitoring are virtualizing the traditional diesel engine service interval model. Forestry contractors in Sweden are piloting subscription-based powertrain coverage that replaces scheduled maintenance with real-time degradation alerts. This architecture is compressing total-cost-of-ownership calculations by eliminating unplanned downtime penalties from contractor bidding processes.
EU Stage V emissions frameworks are forcing engine retooling investments that raise equipment cost structures by fifteen to twenty-five percent across combustion product lines. German and Austrian manufacturers are responding by accelerating electric platform development and discontinuing marginal diesel SKUs. The regulatory friction concentrates most severely on portable chipper categories where weight constraints complicate aftertreatment packaging.
Contractor procurement departments are consolidating vendor relationships around full-lifecycle cost transparency rather than upfront capital expenditure. Municipal buyers in Finland now require ten-year total-cost projections including energy, maintenance, and residual value assumptions. This behavioral shift favors manufacturers with established electric platforms and penalizes pure-play diesel suppliers lacking secondary market infrastructure.
Industrial Wood Chipper Market Segmentation
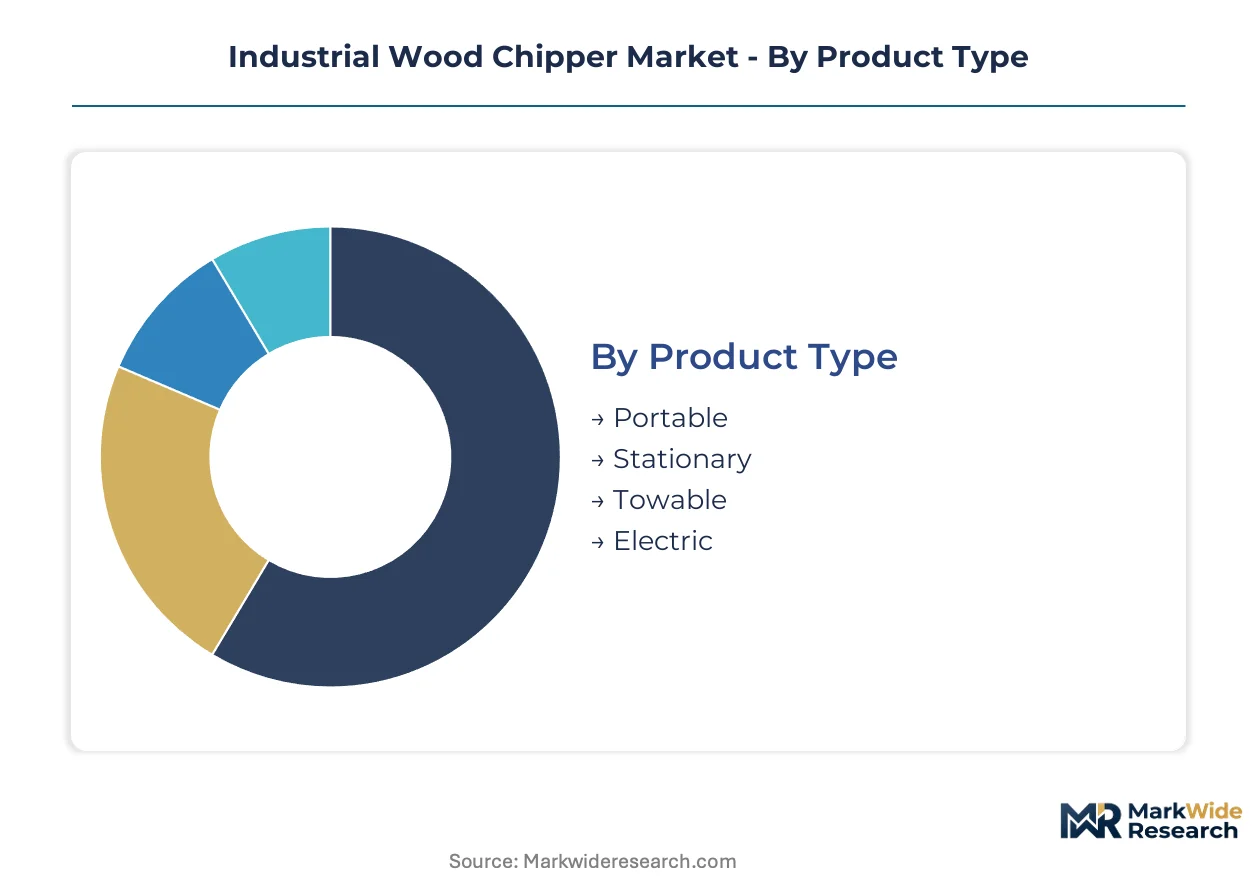
Industrial wood chipper segmentation reveals distinct equipment procurement patterns across mobility requirements, material feedstock characteristics, and operator scale. Each dimension carries specific total-cost-of-ownership implications that reshape vendor positioning and aftermarket service architectures.
Product Type:
Contractor fleet flexibility demands span from urban noise-restricted zones to remote forestry corridors without grid access.
- Portable:Self-propelled or track-mounted units deploy directly to felling sites without road transport dependency. Demand concentrates among Swedish and Finnish forestry contractors requiring rapid repositioning between harvest blocks under tight biomass delivery windows.
- Stationary:Fixed installations with direct conveyor feed into pellet mill or pulp processing lines. Austrian biomass producers in Styria favor these configurations for captive preprocessing capacity with minimal labor exposure.
- Towable:Highway-legal chassis mounting enables contractor fleet rotation across municipal maintenance contracts. German landscaping services leverage these for seasonal equipment pooling between urban parks departments.
- Electric:Battery-driven systems eliminate diesel aftertreatment complexity and comply with tightening municipal noise ordinances. Runtime limitations restrict deployment to peri-urban corridors with established charging infrastructure.
Established volume favors Portable; emerging adoption favors Electric.
Application:
Material throughput requirements and chip uniformity specifications diverge sharply across end-use destinations.
- Forestry:Whole-tree processing at harvest sites demands high-torque feed systems capable of handling irregular stem diameters. Drum-chipper mechanization is displacing manual delimbing across Scandinavian contractor operations.
- Biomass Production:Pellet plant feedstock specifications require precise particle size distribution for combustion efficiency. Preprocessing investments are climbing fastest among Austrian and German district heating supply chains.
- Waste Management:Municipal green waste streams contain contaminated material requiring reinforced cutting components. German cities under EU Green Deal targets are expanding procurement for renewable energy quota compliance.
- Landscaping:Lower-duty cycles prioritize maneuverability and transport convenience over maximum throughput. Urban noise restrictions are accelerating electric model trials in German municipal fleets.
Forestry commands the installed base; Biomass Production is climbing the fastest.
Feed Type:
Input material characteristics determine cutting mechanism selection and maintenance interval economics.
- Logs:Clean stem wood enables consistent chip geometry prized by pulp mill buyers. Scandinavian contractors processing softwood harvest residues dominate this segment's equipment specifications.
- Brush:Irregular limb material with high bark content accelerates knife wear and requires robust feed roller torque. Land-clearing contractors in peri-urban zones handle this feedstock for development site preparation.
- Chips:Reprocessing oversize fractions or contaminated batches demands specialized secondary sizing equipment. Pellet plant quality control protocols drive this niche application.
- Yard Waste:Mixed organic streams with soil and debris inclusion require hardened cutting surfaces and frequent maintenance. German municipal composting facilities process this material under separate collection mandates.
Logs dominate capital deployment; Brush is gaining share fastest in land-clearing applications.
End User:
Procurement sophistication and lifecycle cost visibility vary dramatically across operator categories.
- Commercial:Independent forestry contractors operate on thin margins and prioritize equipment reliability for bidding competitiveness. Fleet electrification timelines here signal broader market transition points.
- Municipal:Public procurement departments under EU emissions frameworks now require decade-long total-cost projections. Finnish cities are pioneering this transparency mandate in tender specifications.
- Industrial:Pulp mill and pellet plant operators seek captive preprocessing capacity with direct conveyor integration. Austrian biomass fuel producers exemplify this vertical control strategy.
- Agricultural:Farm-scale operations combine seasonal wood processing with diversified equipment utilization patterns. Lower utilization rates extend replacement cycles versus commercial counterparts.
Commercial users anchor replacement demand; Municipal procurement is restructuring vendor selection criteria fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forestry contractors and municipal buyers concentrate procurement authority across distinct European and North American clusters, with electrification mandates and biomass targets reshaping geographic equipment flows.
Germany
Municipal waste management programs under EU Green Deal biomass procurement quotas drive sustained chipper demand from district heating supply chains. KBA vehicle certification requirements and municipal noise ordinances accelerate diesel-to-electric fleet transitions. Equipment procurement concentrates in Bavaria and Baden-Württemberg, where forestry contractors serve pellet plant preprocessing contracts.
Sweden
Drum-chipper mechanization displaces manual delimbing across Scandinavian harvest operations as contractors face compressed biomass delivery windows. EU Stage V emissions frameworks narrow replacement cycles for combustion-powered units. Forestry equipment clusters center on Västerbotten and Dalarna counties, where whole-tree processing feeds district heating networks.
United States
EPA Nonroad Compression-Ignition standards compel engine retooling investments that raise equipment cost structures across portable chipper categories. OSHA machine-guarding mandates constrain design freedom for new drum-chipper configurations. Demand concentrates in the Pacific Northwest and Southeast, where land-clearing contractors serve urban development and wildfire fuel reduction programs.
Austria
Pellet plant operators in Styria and Upper Austria seek captive preprocessing capacity with direct conveyor feed integration. National scrappage programs subsidize diesel-to-electric transitions for municipal procurement departments. Biomass fuel producers anchor equipment demand in the Alpine corridor, where district heating supply chains require precise chip uniformity specifications.
Finland
Forestry contractors pilot subscription-based powertrain coverage models that replace scheduled maintenance with real-time degradation alerts. Rural charging infrastructure gaps limit electric chipper deployment to municipal yards and peri-urban corridors. Equipment procurement clusters in North Karelia and Central Finland, where pulp mill feedstock specifications drive high-torque feed system requirements.
Industrial Wood Chipper Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels, with forestry contractors and municipal buyers exercising divergent vendor selection criteria. The vendor base organizes around three strategic archetypes: horizontal grinder specialists leveraging biomass preprocessing architectures, drum-chipper fabricators serving contractor fleet requirements, and stationary system builders targeting pulp mill integration. Consolidation pressure concentrates most severely on portable categories where weight constraints complicate emissions aftertreatment packaging. Dominant competitive moves include geographic expansion into Austrian pellet plant supply chains and portfolio diversification toward electric platform development.
Among North American equipment fabricators, Vermeer Corporation, Bandit Industries, and Morbark occupy positions spanning the mobility and duty-cycle spectrum. Vermeer exemplifies the horizontal grinder architecture approach to biomass preprocessing. Bandit Industries anchors the drum-chipper specialist archetype for forestry contractor applications. Morbark represents the heavy-duty stationary segment with in-house production of high-torque feed systems. These three entities collectively illustrate the competitive positioning vectors—grinder-based, drum-based, and stationary-system—that define procurement alternatives for biomass producers and municipal buyers.
| Leading Market Players |
|---|
| Vermeer |
| Bandit Industries |
| Morbark |
| Terex |
| Peterson |
| J.P. Carlton |
| Timberwolf |
| GreenMech |
| Bruks Siwertell Group |
| Others |
Value Network & Pricing Analysis
EU Stage V emissions compliance costs determine both pricing tier spreads and supply chain shape across industrial wood chipper manufacturing. Diesel aftertreatment investments compress margins on combustion units while accelerating electric platform premiums, forcing procurement departments to weight total-cost-of-ownership against upfront capital expenditure.
Pricing Analysis
Cost-plus contracts with steel and hydraulic component indexation dominate pulp mill and pellet plant procurement agreements. Three-tier pricing structure across premium, standard, and economy levels separates high-torque stationary systems with direct conveyor integration from portable contractor units and entry-grade towable models. Price differentiation hinges on ISO 21873 certification status and feed mechanism automation depth. Cost compression in mid-duty portable categories is intensifying because EU Stage V aftertreatment packaging conflicts with weight constraints. Municipal buyers exhibit lowest price sensitivity due to decade-long total-cost projection mandates, while independent forestry contractors face acute bidding pressure.
Supply Chain Analysis
High-grade alloy feedstock draws from German, Swedish, and Japanese specialty steel producers with limited secondary sourcing alternatives. Precision hydraulic pumps and high-torque feed rollers rest on Italian and German component suppliers with extended lead time profiles. Single-source vulnerability concentrates in Tier-1 diesel powertrain sourcing from a handful of European and Japanese engine manufacturers. Distribution runs through forestry equipment dealerships with regional service capabilities and direct municipal procurement channels for stationary installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial wood chipper market is emerging from a cyclical trough driven by EU Green Deal biomass procurement quotas accelerating fleet replacement timelines. Municipal waste management programs and pellet plant integration investments are restoring equipment demand visibility after emissions transition uncertainty.
For Market Incumbents: Entrench drum-chipper mechanization advantages through proprietary feed system R&D and captive Austrian pellet plant supply chain partnerships. Deepen backward integration into high-torque hydraulic components to offset Tier-1 supplier allocation constraints during electric transition periods. Prioritize ISO 21873 certification maintenance as compliance timelines stretch product launch windows. For New Entrants and Emerging Players: Rural Finnish and Swedish forestry corridors with inadequate charging infrastructure represent the most penetrable white-space for diesel-hybrid interim solutions. Target German municipal rental channel partnerships as equipment-as-a-service models reduce upfront capital barriers for electric model trials. Pursue telematics-enabled predictive maintenance differentiation to capture subscription-based powertrain coverage revenue streams. For Investors and Strategic Acquirers: EU Stage V retrofit incentive programs reshape the acquisition landscape toward electric platform developers with established secondary market infrastructure. Five-to-ten year viability favors manufacturers with in-house battery management system capabilities and municipal procurement relationships. Monitor battery energy density trajectories as the inflection signal for diesel residual value erosion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Development | Battery-driven systems capture municipal procurement under tightening EU noise ordinances. |
| Pellet Plant Integration | Direct conveyor feed installations anchor Austrian biomass fuel supply chains. |
| Telematics Subscription Launch | Real-time degradation alerts compress contractor total-cost-of-ownership calculations. |
| Drum-Chipper Certification | ISO 21873 compliance timelines stretch 14-18 months, freezing competitor R&D roadmaps. |
| Rental Channel Partnership | Equipment-as-a-service models accelerate electric model trial adoption in Germany. |
Research Methodology
Cross-validation between forestry contractor maintenance records and municipal procurement databases anchors the qualitative findings in operational reality. Primary interviews with fleet managers, pellet plant operations directors, municipal procurement officers, and aftermarket service technicians combined with secondary validation from EU emissions framework documentation, KBA vehicle certification filings, and customs trade data. Bottom-up equipment shipment tallies and top-down biomass processing capacity estimates triangulate market sizing.
Calibration against historical replacement cycle patterns and regulatory compliance cost trajectories shapes the projection framework. Segmentation across mobility configuration, feed mechanism type, end-use application, and operator category structures the modeling approach. CAGRs derive from equipment procurement elasticity to EU Green Deal targets and diesel-to-electric transition pacing. Battery energy density improvement curves and charging infrastructure buildout schedules feed electric adoption scenario modeling.
Practitioners should monitor steel alloy price volatility, Tier-1 engine supplier allocation announcements, and municipal noise ordinance expansion for early signals requiring forecast reassessment. Cross-checking against pulp mill and pellet plant capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
ASEAN Conveyor System Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Hook Loader Market