
 Crane Rail Market | 2026-2036
Crane Rail Market Size, Share, and Industry Trends Forecast 2026-2036
Crane Rail Market Outlook
Specialized distributor networks serving port authorities and heavy industrial contractors is rewriting procurement pathways for crane rail systems across major steel-consuming economies. ArcelorMittal leverages its integrated European production footprint to sustain long-term supply agreements with North Sea port clusters. Ansteel anchors domestic demand through captive relationships with China's state-backed logistics infrastructure developers. Jindal Steel & Power competes aggressively on specialty alloy grades for high-wear crane rail applications in Indian steel plants.
Crane rail refers to hardened steel track sections engineered to precise head profiles and tensile specifications, typically manufactured through controlled rolling and heat-treatment processes to withstand concentrated wheel loads exceeding several hundred metric tons. These rails guide overhead cranes, gantry systems, and container-handling equipment across industrial facilities, warehousing complexes, manufacturing plants, and construction sites. Head type and flat bottom configurations dominate mature replacement cycles, while grooved rails capture emerging demand from automated warehouse systems requiring precision alignment. Steel material grades command the deepest margin pools due to alloy customization and certification complexity, whereas aluminum and composite alternatives occupy niche applications where weight reduction or corrosion resistance justifies premium positioning.
China's SAMR enforces GB standards governing rail steel chemistry and dimensional tolerances, while India's BIS mandates IS certification for structural steel deployed in critical load-bearing infrastructure. The EU's CE marking framework under the Construction Products Regulation shapes market access for European crane rail installations. Stakeholders must monitor divergence between national metallurgical standards and emerging harmonization pressures from ISO and IEC technical committees as cross-border port infrastructure investments accelerate.
Market Dynamics
Port operators in China's coastal manufacturing belts are consolidating crane rail procurement into multi-year framework agreements, compressing supplier margins while demanding integrated installation and maintenance services. This buyer concentration is restructuring competitive positioning across the hardened steel track supply chain.
Growth Catalysts
- GB Standards Modernization:China's SAMR enforcement of updated rail steel chemistry protocols is forcing domestic mills to upgrade heat-treatment capacity, filtering subscale producers from certification pools.
- Automated Warehouse Expansion:Precision grooved rail configurations are capturing demand from e-commerce fulfillment centers requiring sub-millimeter alignment tolerances for robotic crane systems.
- Heavy-Lift Logistics Infrastructure:Integrated steel-to-port investments in China's Yangtze River Delta are generating captive demand for high-wear crane rail grades rated above 900 MPa tensile strength.
Market Restraints
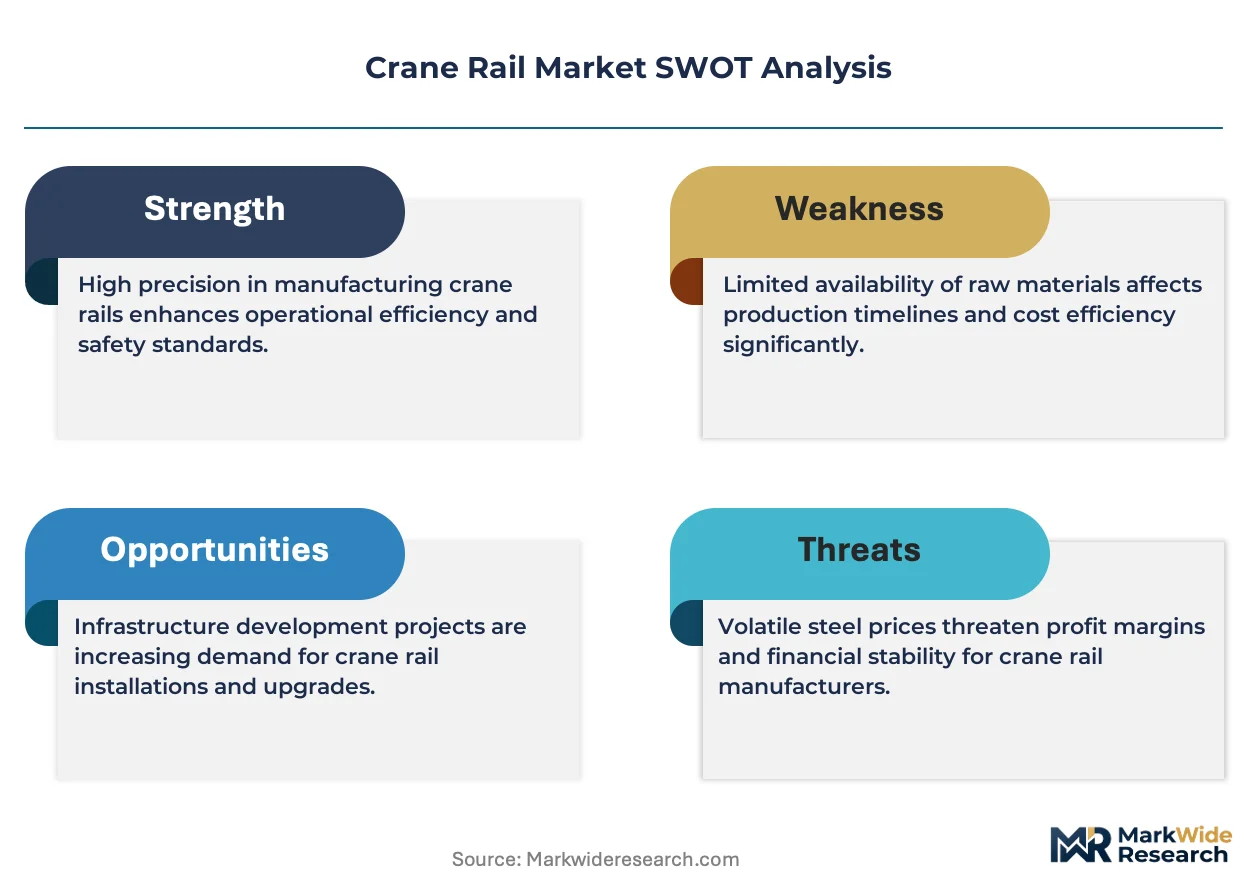
- Scrap Steel Price Volatility:Electric arc furnace operators face margin compression when ferrous scrap inventories fluctuate, destabilizing crane rail alloy cost structures.
- European Supply Concentration:ArcelorMittal's integrated production footprint dominates North Sea port cluster supply, creating single-source vulnerability for specialized head profile specifications.
- Aluminum Substitution Ceiling:Lightweight aluminum crane rails cannot achieve the wheel load ratings required for container-handling equipment above 50 metric ton capacity, capping addressable market share.
Strategic Opportunities
- Indian Specialty Alloy Gap:Domestic steel plants operating high-wear gantry systems present unmet demand for custom manganese-carbon grades outside standard IS certification catalogs.
- CE Marking Harmonization:The EU Construction Products Regulation's expanding scope creates first-mover advantage for mills pre-certifying to EN 13674-4 crane rail standards ahead of mandatory implementation.
- Digital Twin Integration:Convergence of rail wear sensors with predictive maintenance platforms is enabling outcome-based service contracts for port authority fleet operators.
Industry Challenges
- Metallurgical Certification Timelines:BIS and SAMR parallel testing requirements for cross-border projects extend qualification cycles by 8-14 months, delaying revenue recognition.
- Legacy Gantry Retrofit Complexity:Head type crane rail replacements in 1970s-era steel plants require custom fabrication to match obsolete fastening patterns, inflating project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crane Rail Market |
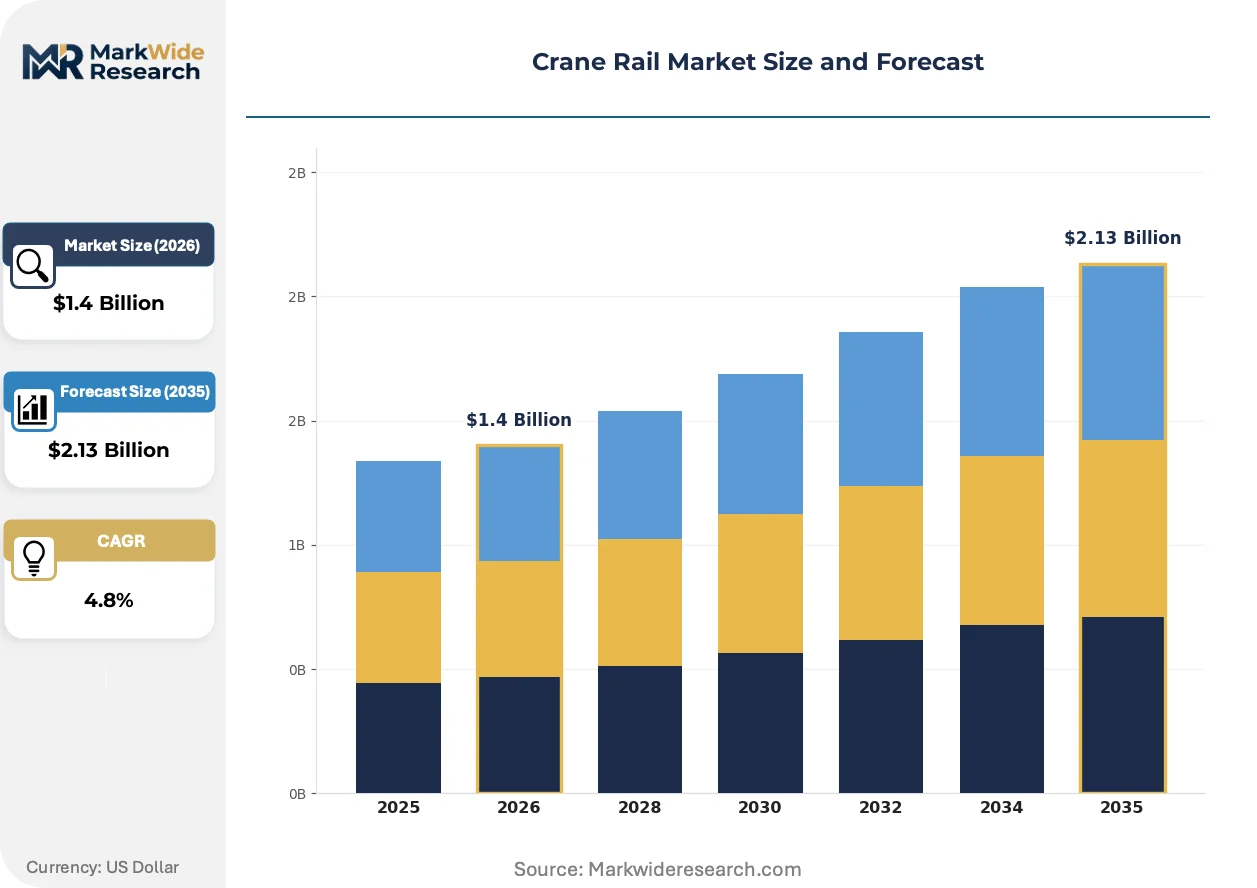
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Type, Flat Bottom, U Rails, Grooved Rails Material: Steel, Aluminum, Composite, Iron Application: Industrial Facilities, Warehousing, Manufacturing Plants, Construction Sites Installation Type: Permanent, Temporary, Mobile, Fixed |
| Companies Covered | ArcelorMittal, Nippon Steel & Sumitomo Metal Corporation, Ansteel, British Steel, Wuhan Iron and Steel, BaoTou Steel, Steel Authority of India Limited, Jindal Steel & Power, EVRAZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crane Rail Market Strategic Shifts
Heat-treatment process control and alloy formulation are converging to extend crane rail service intervals in high-cycle port environments. Material science advances are compressing the replacement cycle economics that have governed procurement decisions for decades.
Induction-hardened rail heads with differential carbon gradients are hybridizing traditional rolling mill output with surface engineering techniques. Port authorities in Rotterdam and Hamburg are specifying these dual-hardness profiles for container crane applications exceeding 500,000 annual wheel passes. This metallurgical approach is hybridizing the cost structure of premium rail grades against standard carbon steel replacement schedules.
The EU's F-Gas Regulation and associated industrial emissions frameworks are tightening energy intensity benchmarks for steel production inputs. Crane rail mills operating electric arc furnaces face compliance cost escalation unless renewable power purchase agreements offset Scope 2 emissions. European port clusters are responding by embedding carbon intensity clauses into multi-year supply tenders, favoring mills with verified low-emission metallurgical routes.
Buyer consortiums among North Sea and Yangtze Delta port operators are consolidating specification-setting authority previously dispersed across engineering consultants. These procurement collectives are displacing fragmented tender processes with standardized technical requirements and pooled volume commitments. The model is most visible in Rotterdam's Maasvlakte expansion and Shanghai's Yangshan deep-water port phases, where framework agreements now span 10-15 year horizons with embedded price adjustment mechanisms.
Crane Rail Market Segmentation
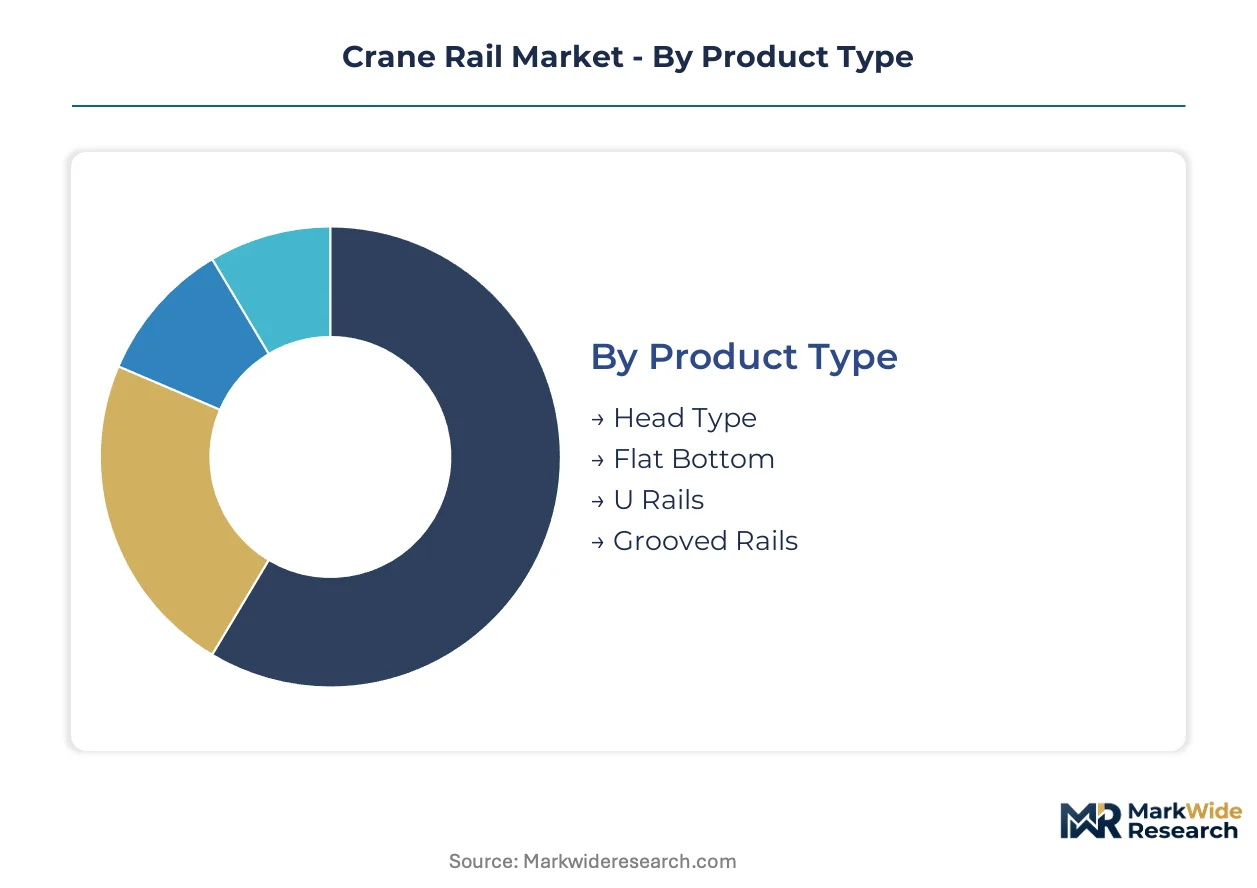
Crane rail procurement splits across four distinct dimensions that shape engineering specifications, metallurgical requirements, and lifecycle economics. Product geometry and material grade dominate technical selection criteria, while application context and installation permanence determine commercial contracting structures.
Product Type:
Head profile geometry spans a use-case spectrum from heavy-lift industrial gantries to precision-guided automated systems.
- Head Type:Hardened convex head profiles withstand concentrated wheel loads exceeding several hundred metric tons in steel mill and port crane applications. Rotterdam and Hamburg port authorities specify these configurations for container-handling equipment exceeding 500,000 annual wheel passes.
- Flat Bottom:Symmetrical base geometry enables direct fastening to concrete or steel substructures without specialized rail chairs. Mature replacement cycles in 1970s-era industrial plants sustain steady demand despite longer installation lead times for custom fabrication.
- U Rails:Channel-shaped cross-sections provide lateral guidance for lighter-capacity crane systems in warehousing environments. European automated warehouse expansions favor these profiles for sub-50 metric ton lifting applications.
- Grooved Rails:Precision-machined vertical channels accommodate robotic crane alignment systems requiring sub-millimeter tolerances. E-commerce fulfillment centers in China's Yangtze River Delta are specifying grooved configurations for high-density storage retrieval.
Established volume favors head type configurations; emerging adoption favors grooved rails.
Material:
Cost tier stratification separates commodity carbon grades from premium alloy formulations certified to national metallurgical standards.
- Steel:Controlled rolling and heat-treatment processes yield tensile ratings above 900 MPa for high-wear port environments. China's SAMR enforces GB standards governing chemistry protocols that filter subscale producers from certification pools.
- Aluminum:Extruded lightweight sections serve niche applications where corrosion resistance or reduced structural loading outweighs wheel load limitations. Weight reduction benefits cannot overcome the 50 metric ton capacity ceiling for container-handling equipment.
- Composite:Fiber-reinforced polymer matrices deliver electrical isolation and chemical resistance in specialized process environments. Food processing and pharmaceutical facilities specify these for washdown compliance.
- Iron:Cast or ductile iron alternatives occupy cost-sensitive temporary installations where service intervals remain short. Construction site mobility requirements favor these for rapid deployment and salvage.
Steel commands margin concentration through certification complexity; aluminum and composites gain share fastest in weight-critical segments.
Application:
Customer type concentration distinguishes captive industrial consumers from fragmented construction contractors.
- Industrial Facilities:Integrated steel-to-port infrastructure investments generate framework agreements spanning 10-15 year horizons. State-backed logistics developers in China's coastal manufacturing belts anchor procurement volume.
- Warehousing:Automated storage and retrieval systems drive specification convergence toward precision grooved rail standards. E-commerce fulfillment network expansion is reshaping demand concentration.
- Manufacturing Plants:High-wear gantry systems in Indian steel plants present unmet demand for custom manganese-carbon grades outside standard IS certification catalogs.
- Construction Sites:Temporary installation requirements favor mobile and modular rail configurations with rapid deployment characteristics. Project-based contracting compresses supplier margins.
Industrial facilities dominate contract value; warehousing applications show the steepest expansion trajectory.
Installation Type:
Permanence spectrum governs engineering cost allocation between initial capital deployment and lifecycle maintenance obligations.
- Permanent:Embedded fastening systems with welded or chemically bonded connections serve multi-decade infrastructure investments. Rotterdam's Maasvlakte expansion exemplifies long-horizon specification locking.
- Temporary:Bolted or clamped configurations enable rapid redeployment across construction phases. Modular design tolerates higher wear rates given abbreviated service expectations.
- Mobile:Self-propelled crane systems on rail-mounted bogies require reinforced substructures and dynamic load distribution engineering. Port intermodal yards specify these for flexible cargo handling.
- Fixed:Stationary crane foundations with dedicated rail alignments maximize load capacity and positioning precision. Heavy-lift manufacturing applications favor this configuration for repetitive high-cycle operations.
Permanent installations concentrate revenue predictability; mobile systems expand addressable use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European port operators command premium pricing leverage against Asian suppliers due to stringent CE marking protocols and carbon intensity clauses. Chinese mills absorb compressed margins from GB standards compliance costs and state-backed volume aggregation. Indian specialty alloy demand escapes domestic certification catalogs entirely.
China
Yangtze River Delta port clusters drive captive procurement for high-wear grades above 900 MPa tensile strength. SAMR enforces updated GB standards on rail steel chemistry that filter subscale producers from certification pools. Shanghai's Yangshan deep-water port phases now lock 10-15 year framework agreements with embedded price adjustment mechanisms.
Germany
North Sea port infrastructure generates long-horizon specification locking for container-handling equipment exceeding 500,000 annual wheel passes. The EU's F-Gas Regulation tightens energy intensity benchmarks for electric arc furnace inputs. Hamburg and Rotterdam procurement collectives displace fragmented tenders with standardized technical requirements and pooled volume commitments.
India
Domestic steel plants operating high-wear gantry systems present unmet demand for custom manganese-carbon grades. BIS mandates IS certification for structural steel deployed in critical load-bearing infrastructure. Maharashtra and Gujarat industrial corridors anchor procurement volume for specialty alloy formulations outside standard catalogs.
United States
Heavy-lift logistics hubs concentrate procurement into multi-year framework agreements demanding integrated installation services. OSHA and FERC guidelines shape material handling infrastructure safety protocols. Gulf Coast petrochemical complexes and Great Lakes steel terminals sustain replacement cycles for 1970s-era head type configurations.
Crane Rail Market Competitive Environment
Vertically integrated steel majors and specialty alloy specialists split the market along certification complexity lines. European producers leverage CE marking pre-certification to capture North Sea port cluster tenders. Chinese state-backed mills anchor domestic volume through captive relationships with logistics infrastructure developers. Competitive moves concentrate on heat-treatment capacity upgrades and renewable power purchase agreements to offset Scope 2 emissions compliance costs.
Within the integrated steel major tier, ArcelorMittal and Ansteel exemplify divergent geographic anchoring strategies. ArcelorMittal's European production footprint sustains long-term supply agreements with Rotterdam and Hamburg port authorities. Ansteel occupies a parallel position in China's coastal manufacturing belts through relationships with state-backed logistics developers. Jindal Steel & Power represents the specialty alloy specialist archetype competing on custom grades for high-wear applications outside standard IS certification catalogs.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel & Sumitomo Metal Corporation |
| Ansteel |
| British Steel |
| Wuhan Iron and Steel |
| BaoTou Steel |
| Steel Authority of India Limited |
| Jindal Steel & Power |
| EVRAZ |
| Others |
Value Chain & Pricing Dynamics
Yangshan deep-water port phases in Shanghai compress freight corridors into multi-year framework agreements, binding supply concentration in China's coastal manufacturing belts to downstream price differentiation across certification tiers. GB standards compliance costs filter subscale mills from tender pools while Rotterdam's Maasvlakte expansion embeds carbon intensity clauses that widen spreads between low-emission and conventional metallurgical routes.
Pricing Analysis
The customization-premium spread separates configured-to-order manganese-carbon grades from standard carbon steel catalog offerings. Project-based long-term contracting dominates procurement structures, with price differentiation resting on GB/CE certification tier and volume scale within framework agreements. Cost compression in standard grades intensifies as Chinese state-backed logistics developers aggregate demand into captive supply relationships. Construction contractors operating temporary installations exhibit highest price sensitivity; port authorities with 10-15 year horizon agreements demonstrate lowest sensitivity due to lifecycle cost optimization.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor working capital structures for electric arc furnace operators facing ferrous scrap price volatility. Production concentrates in China, Germany, and India, with raw material draws from high-grade iron ore, ferroalloy, and scrap steel inputs. Single-source vulnerability for specialized head profile specifications in North Sea port clusters creates structural risk. Distribution runs through specialized distributor networks serving port authorities and heavy industrial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among port operator consortiums in Rotterdam and Shanghai, displacing fragmented tender processes with pooled volume commitments and standardized technical requirements.
For Market Incumbents: Entrench heat-treatment capacity upgrades to maintain certification tier positioning as GB standards modernization filters competitors. Secure renewable power purchase agreements to offset Scope 2 emissions compliance costs under EU F-Gas Regulation. Anchor long-horizon framework agreements with state-backed logistics developers before procurement collectives consolidate further. For New Entrants and Emerging Players: Build out specialty alloy formulation capabilities targeting Indian steel plants with custom manganese-carbon grades outside standard IS certification catalogs. Focus initial penetration on warehousing applications for automated storage and retrieval systems requiring precision grooved rail configurations. Pursue outcome-based service contracts bundling installation and predictive maintenance to differentiate from commodity suppliers. For Investors and Strategic Acquirers: Specialty alloy specialists with pre-certified EN 13674-4 crane rail standards represent the most defensible acquisition targets ahead of mandatory CE marking harmonization. Long-term viability over the projection horizon hinges on backward integration into heat-treatment capacity and captive renewable energy supply. Monitor divergence between SAMR and BIS parallel testing timelines as an inflection indicator for cross-border project qualification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | GB standards enforcement by SAMR mandates upgraded metallurgical infrastructure for certification retention. |
| Renewable Power Purchase Agreement | EU F-Gas Regulation carbon intensity clauses favor mills with verified low-emission metallurgical routes. |
| EN 13674-4 Pre-Certification | CE marking harmonization creates first-mover advantage for Rotterdam and Hamburg port cluster tenders. |
| Digital Twin Integration | Rail wear sensors with predictive maintenance platforms enable outcome-based contracts for port authorities. |
| Specialty Alloy Formulation | Custom manganese-carbon grades address unmet demand from Indian steel plants outside standard IS catalogs. |
Study Parameters
The analysis maps head type, flat bottom, U rail, and grooved rail configurations, each validated through primary interviews with port authority procurement directors, steel mill technical R&D heads, heavy industrial contractor project managers, and distributor network principals. Secondary validation draws from SAMR GB standards documentation, EU Construction Products Regulation filings, BIS IS certification records, and electric arc furnace operator SEC disclosures. Bottom-up volume triangulation against top-down metallurgical capacity assessments ensures cross-verified demand estimates.
Forecast assumptions hold scrap steel price volatility within observed historical bands while varying renewable energy cost trajectories and regulatory implementation timelines across the analysis window. Segmentation dimensions model product geometry, material grade tier, application context, and installation permanence. CAGRs derive from installed base replacement cycles, port infrastructure investment pipelines, and automated warehouse expansion trajectories. Industry-specific inputs include annual wheel pass thresholds for container-handling equipment and heat-treatment process yield rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed mills or accelerated CE marking enforcement by EU regulators would shift outcomes. Macroeconomic deviation in steel-intensive sectors, regulatory divergence between SAMR and BIS testing protocols, or breakthroughs in aluminum alloy wheel load ratings would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Extrusion Machinery Market