
 TBR Hydraulic Curing Press Market | 2026-2036
TBR Hydraulic Curing Press Market Size, Share, and Industry Trends Forecast 2026-2036
TBR Hydraulic Curing Press Market Insights
Consolidation among commercial fleet operators is recalibrating procurement patterns for TBR hydraulic curing presses. HF TireTech Group leverages its engineering depth in double-acting press configurations to serve integrated tire plants. Himile Mechanical Science and Technology anchors its position through cost-competitive four-column designs targeting emerging Asian markets. Mitsubishi Heavy Industries Machinery Systems differentiates via servo-hybrid technology leadership that reduces cycle times for high-volume manufacturers.
A TBR hydraulic curing press applies controlled heat and pressure to vulcanize truck and bus radial tires, typically operating at clamping forces exceeding 2,500 tons and curing temperatures near 180°C to achieve optimal cross-link density in rubber compounds. Double-acting presses command the largest installed base due to their balanced force distribution and compatibility with diverse tire sizes, while servo-hybrid technology represents the fastest-expanding segment as energy efficiency mandates intensify. Electro-hydraulic systems concentrate margin pools where OEMs demand programmable force curves and reduced hydraulic oil consumption.
China's SAMR enforces GB standards that elevate press energy efficiency benchmarks, while India's BIS certification requirements for imported machinery shape equipment sourcing decisions for domestic tire makers. The EU F-Gas Regulation indirectly pressures press cooling system designs as manufacturers phase down fluorinated refrigerants. Stakeholders must monitor how regional decarbonization timelines reshape capital equipment replacement cycles and supplier qualification criteria.
Market Dynamics
Energy efficiency mandates from China's SAMR and India's BIS are forcing simultaneous retooling of installed press bases while fleet operators consolidate procurement around integrated tire plants.
Growth Catalysts
- India's commercial vehicle production surge:Domestic tire makers are expanding curing capacity to serve OEM supply contracts for heavy trucks and buses.
- EU F-Gas Regulation:Phase-down of fluorinated refrigerants is accelerating replacement of legacy cooling systems in European press installations.
- Servo-hybrid technology maturation:Programmable force curves and reduced hydraulic oil consumption are attracting high-volume manufacturers seeking operational savings.
Market Restraints
- Specialized steel forging concentration:Heavy press frame production depends on a limited supplier base in Germany and Japan, creating input bottlenecks.
- Technical limitation in heat recovery:Current curing press designs capture less than 40 percent of exhaust thermal energy, capping efficiency gains.
- China's GB standard compliance costs:SAMR energy efficiency benchmarks require control system upgrades that extend qualification timelines for imported equipment.
Strategic Opportunities
- Southeast Asian tire manufacturing clusters:Vietnam and Thailand offer greenfield plant opportunities as tire makers diversify from China-centric production.
- Remanufactured tire segment growth:Retreading operations require smaller-capacity curing presses with rapid mold change capabilities.
- Digital twin integration:Convergence of IoT sensors and predictive maintenance software creates aftermarket service revenue streams for press OEMs.
Industry Challenges
- Control systems engineering talent scarcity:Servo-hybrid and electro-hydraulic architectures require software-integrated mechanical expertise that outpaces vocational training output.
- Legacy hydraulic infrastructure integration:Brownfield tire plants face extended downtime when retrofitting older presses with energy-efficient actuation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TBR Hydraulic Curing Press Market |
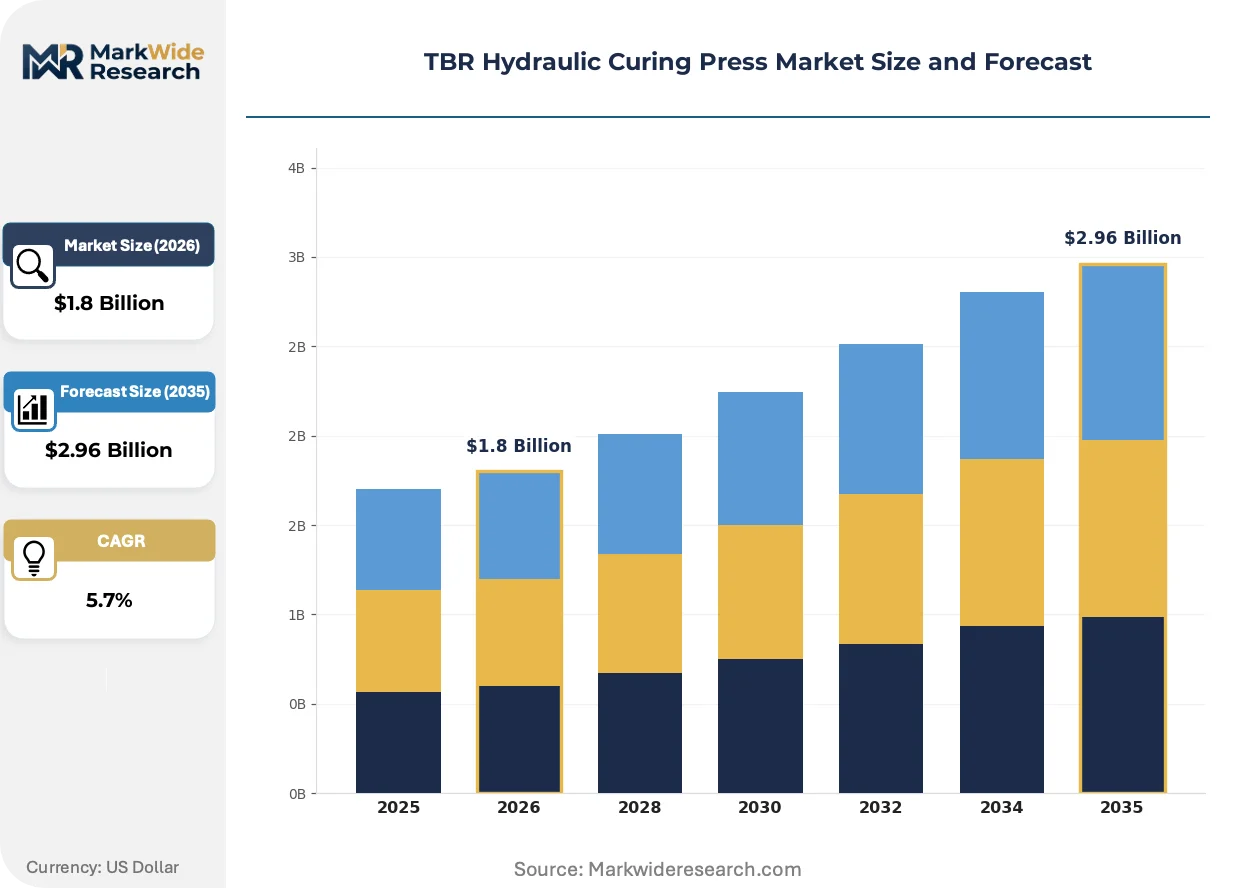
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Acting, Double-Acting, Pendulum, Four-Column Technology: Hydraulic, Pneumatic, Mechanical, Electro-Hydraulic, Servo Application: Tire Manufacturing, Rubber Molding, Composite Forming, Pharmaceutical Molding End User Industry: Automotive OEMs, Aerospace Suppliers, Medical Device Producers, Consumer Goods Manufacturers |
| Companies Covered | Larsen & Toubro, HF TireTech Group, Mitsubishi Heavy Industries Machinery Systems, McNeil & NRM, Harburg-Freudenberger Maschinenbau, Himile Mechanical Science and Technology, Guilin Rubber Machinery, Specific Engineering Corporation, Cima Impianti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TBR Hydraulic Curing Press Market Trends and Innovations
Digitalization of curing process control and material handling automation are compressing cycle times while regulatory pressure on energy intensity accelerates hardware replacement decisions across mature manufacturing bases.
Electro-hydraulic actuation systems are expanding into high-volume TBR production lines where programmable clamping profiles enable precise control over complex multi-compound tire constructions. Tier-one tire OEMs in Germany and Japan are retrofitting existing press halls with these systems to meet corporate carbon reduction targets. The technology is expanding into mid-tier Asian manufacturers as local system integrators develop cost-optimized control packages.
China's SAMR enforcement of updated GB standards on industrial equipment energy labeling is pressuring both domestic and foreign press suppliers to submit verified efficiency test data. Tire makers in Shandong and Jiangsu provinces now require documented kWh-per-cure metrics in capital equipment tenders. European press OEMs are responding by pre-certifying servo-hybrid configurations to SAMR-recognized testing protocols.
Fleet operator procurement consolidation is compressing supplier qualification cycles as integrated logistics companies centralize tire purchasing decisions. Long-haul trucking fleets in the United States and Germany now specify curing press technology tiers in their indirect sourcing requirements. This concentration is most visible in North American replacement tire programs where national fleet contracts bypass traditional distributor networks.
TBR Hydraulic Curing Press Market Segmentation
TBR hydraulic curing press segmentation reveals how force distribution architecture and actuation technology determine equipment suitability across tire construction complexity and production scale. Procurement patterns diverge sharply between high-volume integrated plants seeking cycle time compression and specialized manufacturers prioritizing mold flexibility.
Type:
Volume manufacturers favor double-acting configurations for balanced force distribution, while premium-tier producers invest in specialized architectures for complex tire geometries.
- Double-Acting:Balanced clamping force from opposing cylinders ensures uniform pressure distribution across large tire molds. Fleet operator consolidation in Germany and the United States is concentrating procurement around these presses for long-haul truck tire production.
- Four-Column:Rigid frame construction with four guide pillars delivers precise platen parallelism for high-precision curing. India's BIS certification requirements for imported machinery are accelerating adoption among domestic tire makers scaling commercial vehicle supply contracts.
- Single-Acting:Simpler unidirectional force application suits smaller retreading operations with limited capital budgets.
- Pendulum:Articulated frame design enables rapid mold access for specialty tire producers requiring frequent changeovers.
Mature deployment sits with double-acting presses. Newer deployment is concentrated in four-column configurations.
Technology:
Cost tier stratification separates legacy hydraulic systems from servo-hybrid architectures commanding premium pricing for energy recovery capabilities.
- Servo:Closed-loop motor control enables programmable force curves with kinetic energy recovery during deceleration. China's SAMR enforcement of updated GB standards on industrial equipment energy labeling is mandating documented kWh-per-cure metrics that favor these systems.
- Electro-Hydraulic:Electric servo motors driving hydraulic pumps combine precision positioning with high force density. Tier-one tire OEMs in Japan are retrofitting press halls with these systems to meet corporate carbon reduction targets.
- Hydraulic:Conventional valve-controlled systems retain installed base dominance in emerging Asian markets.
- Pneumatic:Compressed air actuation serves niche applications requiring rapid cycling at lower force levels.
- Mechanical:Crank and toggle mechanisms persist in legacy installations with limited upgrade capital.
Established capacity relies on conventional hydraulic technology. Capacity expansion is tilting toward servo and electro-hybrid architectures.
Application:
Application scope extends beyond tire curing into adjacent polymer processing, with margin concentration varying by material handling complexity and regulatory stringency.
- Tire Manufacturing:Vulcanization of truck and bus radial tires at clamping forces exceeding 2,500 tons and curing temperatures near 180°C. India's commercial vehicle production surge is driving capacity additions among domestic tire makers securing OEM supply contracts.
- Rubber Molding:Industrial component production including seals, gaskets, and vibration isolation elements. Southeast Asian manufacturing clusters in Vietnam and Thailand are attracting greenfield investments as tire makers diversify from China-centric production.
- Composite Forming:High-pressure consolidation of fiber-reinforced polymers for structural applications.
- Pharmaceutical Molding:Precision compression of elastomeric medical components requiring validated process control.
Installed base concentration favors tire manufacturing. Fastest application expansion is occurring in rubber molding for industrial components.
End User Industry:
Customer type determines specification intensity, with automotive OEMs demanding integrated production lines and medical device producers requiring validated batch documentation.
- Automotive OEMs:Integrated tire plants serving vehicle manufacturers require presses with automated mold handling and statistical process control. Fleet operator procurement consolidation in North America is centralizing sourcing decisions around national replacement tire contracts.
- Aerospace Suppliers:Aircraft tire producers need specialized presses for high-performance bias-ply and radial constructions with stringent uniformity requirements.
- Medical Device Producers:Elastomeric component manufacturers demand validated equipment with electronic batch records and FDA-compliant software.
- Consumer Goods Manufacturers:Durable goods producers utilize smaller-capacity presses for non-tire rubber and polymer applications.
Volume leadership belongs to automotive OEM supply chains. Emerging demand is building in aerospace and medical device segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand growth as domestic tire makers scale commercial vehicle supply contracts. China's regulatory tightening on energy efficiency is forcing equipment upgrades across Shandong and Jiangsu provinces. Germany and the United States anchor mature replacement tire demand from consolidated fleet operators.
China
Shandong and Jiangsu province tire makers are expanding curing capacity to serve domestic truck OEMs. SAMR enforcement of updated GB standards on industrial equipment energy labeling mandates documented kWh-per-cure metrics in capital tenders. Qingdao's rubber machinery cluster is attracting servo-hybrid press retrofits as manufacturers phase out conventional hydraulic systems.
India
Maharashtra and Gujarat-based tire producers are adding TBR curing lines to fulfill heavy truck and bus OEM contracts. BIS certification requirements for imported machinery are extending qualification timelines for European and Japanese press suppliers. Chennai's automotive manufacturing corridor is emerging as a secondary hub for commercial tire production capacity.
Germany
Integrated tire plants serving long-haul trucking fleets are retrofitting press halls with electro-hydraulic actuation systems. The EU F-Gas Regulation is accelerating replacement of legacy cooling systems in curing press installations. Hanover's industrial machinery ecosystem supports aftermarket service networks for press OEMs targeting carbon reduction targets.
United States
National fleet operator consolidation is centralizing procurement decisions around integrated tire plants for replacement programs. EPA industrial emissions guidelines indirectly shape press cooling system specifications in brownfield facilities. Ohio's rubber belt manufacturing corridor maintains demand for mid-capacity curing equipment serving adjacent polymer processing.
Japan
Tier-one tire OEMs in Kansai and Chubu regions are retrofitting existing press installations with servo-hybrid architectures. METI energy efficiency guidelines for industrial machinery are pressuring manufacturers to document carbon reduction metrics. Nagoya's automotive supplier cluster demands high-precision curing equipment for aircraft tire constructions.
TBR Hydraulic Curing Press Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cost-optimized configurations for developing Asian markets. The vendor base stratifies across three tiers: European and Japanese specialists commanding premium positioning for servo-hybrid technology, Chinese state-affiliated and private manufacturers dominating volume shipments, and Indian engineering conglomerates leveraging domestic project execution capabilities. Competitive moves center on pre-certification to SAMR-recognized testing protocols and strategic partnerships with tire OEMs for integrated plant contracts.
Within the premium technology tier, Mitsubishi Heavy Industries Machinery Systems and Harburg-Freudenberger Maschinenbau exemplify servo-hybrid engineering depth. HF TireTech Group occupies a position among double-acting press specialists serving integrated tire plants. Himile Mechanical Science and Technology anchors the cost-competitive segment with four-column designs targeting emerging Asian markets. These three company archetypes represent the dominant competitive positioning vectors across energy efficiency mandates and fleet operator procurement consolidation.
| Leading Market Players |
|---|
| Larsen & Toubro |
| HF TireTech Group |
| Mitsubishi Heavy Industries Machinery Systems |
| McNeil & NRM |
| Harburg-Freudenberger Maschinenbau |
| Himile Mechanical Science and Technology |
| Guilin Rubber Machinery |
| Specific Engineering Corporation |
| Cima Impianti |
| Others |
Pricing and Supply Chain Analysis
Fleet operator consolidation around integrated tire plants is forcing press suppliers to absorb certification and retrofit costs while specialized steel forging capacity concentrates pricing power among German and Japanese frame producers. China's SAMR energy efficiency mandates add compliance expenditure layers that tier-one OEMs pass through to mid-tier buyers, compressing margins across the standard equipment segment.
Pricing Analysis
Volume manufacturers compete on per-unit equipment cost while servo-hybrid specialists capture margin through energy-recovery value propositions and documented kWh-per-cure metrics. Price differentiation hinges on SAMR pre-certification status and after-sales service bundling for predictive maintenance software. Cost compression in the hydraulic tier is intensifying because Indian and Vietnamese tire makers prioritize capital expenditure minimization over lifecycle efficiency. Retreading operations and smaller domestic manufacturers exhibit highest price sensitivity; tier-one tire OEMs in Germany and Japan demonstrate lowest sensitivity when carbon reduction targets justify premium outlays.
Supply Chain Analysis
Heavy press frame production rests on specialized steel forging capacity concentrated in Germany, Japan, and select Chinese state-affiliated producers. Control systems engineering talent feeds from Japanese and German automation clusters, while hydraulic component sourcing draws from established Italian and Chinese supplier networks. Single-source vulnerability sits with precision-forged frame suppliers capable of meeting 2,500-ton clamping force specifications. Distribution runs through tire OEM procurement consortiums and regional rubber machinery integrators serving brownfield retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TBR hydraulic curing press market is executing a technology-transition phase as servo-hybrid architectures displace conventional hydraulic systems under regulatory pressure from China's SAMR and Japan's METI.
For Market Incumbents: Deepen vertical integration into control systems engineering to offset talent scarcity constraining servo-hybrid deployment timelines. Secure pre-certification to SAMR-recognized testing protocols before qualification windows tighten for imported equipment. Anchor aftermarket service revenue through digital twin integration and predictive maintenance software bundling. For New Entrants and Emerging Players: Retreading operations and Southeast Asian greenfield tire plants represent underserved buyer archetypes with rapid mold change requirements and capital expenditure constraints. Vietnam and Thailand manufacturing clusters offer penetrable entry points as tire makers diversify from China-centric production. Pursue cost-optimized four-column designs with local system integrator partnerships to bypass extended BIS qualification timelines. For Investors and Strategic Acquirers: The window for entry favors servo-hybrid technology specialists with documented energy efficiency metrics and established tire OEM relationships. Mid-cap engineering firms with backward integration into precision forging capabilities present viable acquisition targets. Watch for inflection when India's commercial vehicle production surge triggers accelerated curing capacity additions among domestic tire makers.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Hybrid Retrofit Programs | Enables tire OEMs to meet METI carbon reduction targets without greenfield capital deployment. |
| SAMR Pre-Certification Investment | Compresses qualification timelines for imported equipment tenders in Shandong and Jiangsu provinces. |
| Digital Twin Platform Development | Creates recurring aftermarket revenue through IoT-enabled predictive maintenance for fleet operators. |
| Southeast Asian Manufacturing Partnership | Positions suppliers for Vietnam and Thailand greenfield tire plant investments diversifying from China. |
| Control Systems Engineering Acquisition | Addresses talent scarcity constraining servo-hybrid and electro-hydraulic architecture deployment. |
Research Methodology
Trade association publications, customs and import-export databases, and tire OEM capital expenditure disclosures formed the secondary backbone for this analysis. Primary fieldwork incorporated structured interviews with plant engineers at integrated tire facilities, procurement leads at commercial fleet operators, aftermarket service heads at press OEMs, and regulatory affairs specialists familiar with SAMR certification protocols. Bottom-up and top-down triangulation validated equipment shipment volumes against tire production capacity expansion announcements across India, China, and Southeast Asia.
Bottom-up modeling aggregated segment-level equipment demand by press type, actuation technology, and end-user industry; top-down cross-checks applied macroeconomic filters for commercial vehicle production and replacement tire market sizing. Segmentation dimensions included force distribution architecture, actuation technology tier, application scope, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and capacity expansion pipeline tracking, with sensitivity testing against energy efficiency mandate acceleration scenarios and fleet operator procurement consolidation patterns.
Revisions become necessary when SAMR enforcement timelines accelerate, India's BIS certification requirements expand to additional machinery categories, or EU F-Gas Regulation phase-down schedules compress cooling system replacement demand. A small set of named triggers warrants ongoing watch: commercial vehicle production volatility in India, servo-hybrid technology cost parity achievement, and tire OEM vertical integration into captive curing capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
Rotary Blasthole Drilling Rig Market