
 Construction Power Rental Market | 2026-2036
Construction Power Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Power Rental Market Insights
Natural-gas engine technology is recalibrating diesel-centric fleet economics across the construction power rental sector. Aggreko leverages its hybrid energy expertise to anchor premium positioning in remote infrastructure sites. Caterpillar sustains manufacturing scale advantages through captive engine production and integrated control systems. Cummins competes on modular power architecture that reduces transport and commissioning timelines for rental operators.
Construction power rental encompasses the short-term lease of mobile energy systems—typically reciprocating engine generators rated from 20 kW to 2,500 kW, plus ancillary distribution equipment—to energize job sites lacking grid connection or requiring redundant capacity. These systems deliver three-phase power at 480V for heavy machinery, welding operations, and tower crane loads across civil engineering and building construction phases. Diesel generators still dominate installed rental fleets, though hybrid and solar-diesel configurations represent the fastest-expanding technology segment as fuel volatility and carbon reporting intensify. Within application categories, infrastructure projects and mining operations command the deepest rental durations and highest per-unit pricing, while residential complexes generate volume through shorter, more standardized contracts.
EPA Tier 4 Final and EU Stage V emissions frameworks compel fleet operators to retire older diesel units or retrofit aftertreatment systems, directly elevating capital intensity and rental rate structures. OSHA electrical safety standards and IEC 60364 wiring regulations shape temporary power installation protocols, influencing insurer requirements and contractor liability exposure. Stakeholders must weigh fuel-flexible engine platforms against site-specific grid interconnection timelines when sizing fleet commitments for multi-year project pipelines.
Market Dynamics
EPA Tier 4 Final emissions mandates are forcing fleet operators to retire legacy diesel generators and absorb premium capital costs for aftertreatment-equipped or alternative-fuel units, fundamentally restructuring rental rate economics and competitive positioning across the sector.
Growth Catalysts
- Gigaproject timelines in Saudi Arabia:NEOM, Red Sea Project, and Qiddiya developments require sustained multi-year temporary power capacity, anchoring regional fleet deployment commitments.
- EU Stage V emissions framework:Urban construction zones in Germany, France, and the Netherlands now mandate ultra-low emission temporary power, accelerating hybrid and natural-gas generator adoption.
- Grid interconnection delays:Utility approval timelines stretching 18-36 months in remote infrastructure sites extend rental contract durations and deepen per-project revenue capture.
Market Restraints
- Aftertreatment capital intensity:Selective catalytic reduction and diesel particulate filter retrofits add 15-25% to unit acquisition costs, compressing rental operator margins before rate adjustments pass through.
- Engine supply concentration:Cylinder block and fuel injection system production clusters in Germany, Japan, and the United States create vulnerability to localized supply disruptions.
- Battery energy density limitations:Lithium-ion packs for hybrid configurations remain insufficient for 500+ kW continuous loads without diesel backup, constraining full electrification.
Strategic Opportunities
- Underpenetrated African markets:Mining and infrastructure development in the Democratic Republic of Congo, Zambia, and Mozambique lack established rental infrastructure, favoring first-mover fleet positioning.
- Solar-diesel hybrid convergence:Photovoltaic arrays paired with reciprocating engines reduce fuel consumption 30-50% in remote sites with high solar irradiance, opening premium pricing tiers.
- India's PLI scheme for manufacturing:Production-linked incentives for domestic capital goods assembly reduce import duties on generator components, enabling cost-competitive local fleet builds.
Industry Challenges
- Certified technician scarcity:EPA Tier 4 Final and EU Stage V aftertreatment diagnostics require specialized training that rental operators struggle to source at scale.
- Fleet utilization volatility:Project delays and cancellations in oil and gas sectors force rapid redeployment of heavy units across continents, elevating logistics costs and downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Power Rental Market |
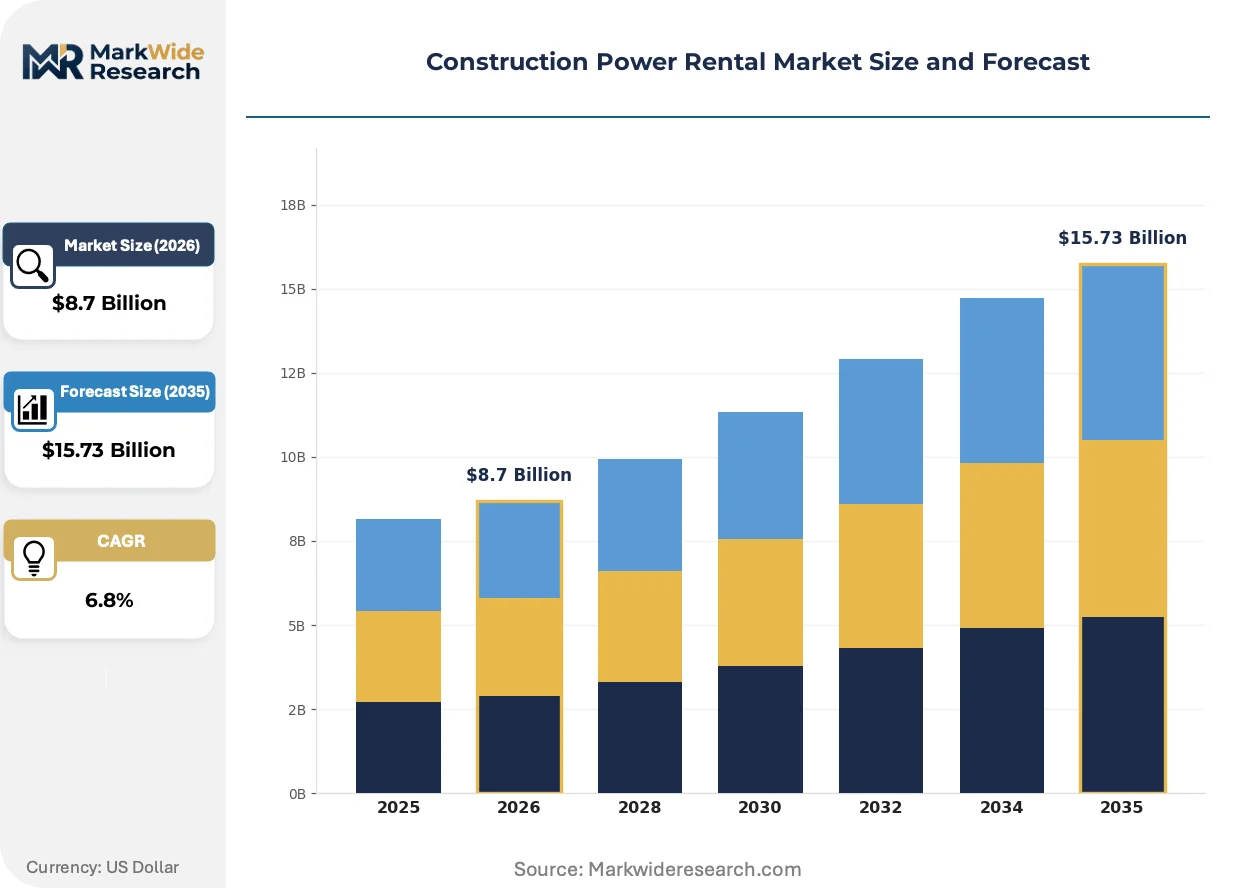
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Welders, Compressors, Lighting Towers, Pumps, Cranes Technology: Diesel, Gasoline, Electric, Solar, Hybrid, Hydrogen Application: Infrastructure Projects, Commercial Buildings, Residential Complexes, Industrial Facilities, Road Construction, Mining End User: General Contractors, Equipment Rental Companies, Specialty Contractors, Government Agencies, Utility Providers |
| Companies Covered | United Rentals, Aggreko, Ashtead Group, Herc Rentals, Atlas Copco, Caterpillar, Cummins, Generac Power Systems, Himoinsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Power Rental Market Trends and Innovations
Natural-gas engine technology and intelligent load management systems are absorbing capital allocation once reserved for conventional diesel fleets, while regulatory pressure and buyer sophistication accelerate service model reinvention.
Hybrid energy systems combining battery storage with downsized diesel prime movers are absorbing demand from mining and pipeline construction operators seeking fuel cost predictability. Remote infrastructure projects in Western Australia and the Permian Basin deploy these configurations to hedge diesel price volatility while maintaining 24/7 uptime. The technology is absorbing market share from traditional 1,000+ kW diesel-only rentals by enabling 40-60% runtime on stored energy.
EPA Tier 4 Final compliance deadlines in the United States compel rental fleets to adopt exhaust aftertreatment or alternative fuels by specified phase-in dates. Operators face retrofit costs or accelerated depreciation on non-compliant assets, with California Air Resources Board rules extending requirements to older units in non-attainment zones. Infrastructure contractors in Texas and Louisiana now specify Tier 4 Final-certified equipment in bid documents to preempt liability exposure.
Power-as-a-service contracting is replacing traditional dry-hire rental arrangements for multi-year infrastructure engagements. EPC contractors in the Middle East and Southeast Asia bundle fuel management, maintenance, and carbon reporting into single-source agreements, transferring operational risk to rental providers. This model concentrates in Saudi Arabia's gigaproject ecosystem where owners demand guaranteed availability and transparent emissions accounting without direct fleet oversight.
Construction Power Rental Market Segmentation
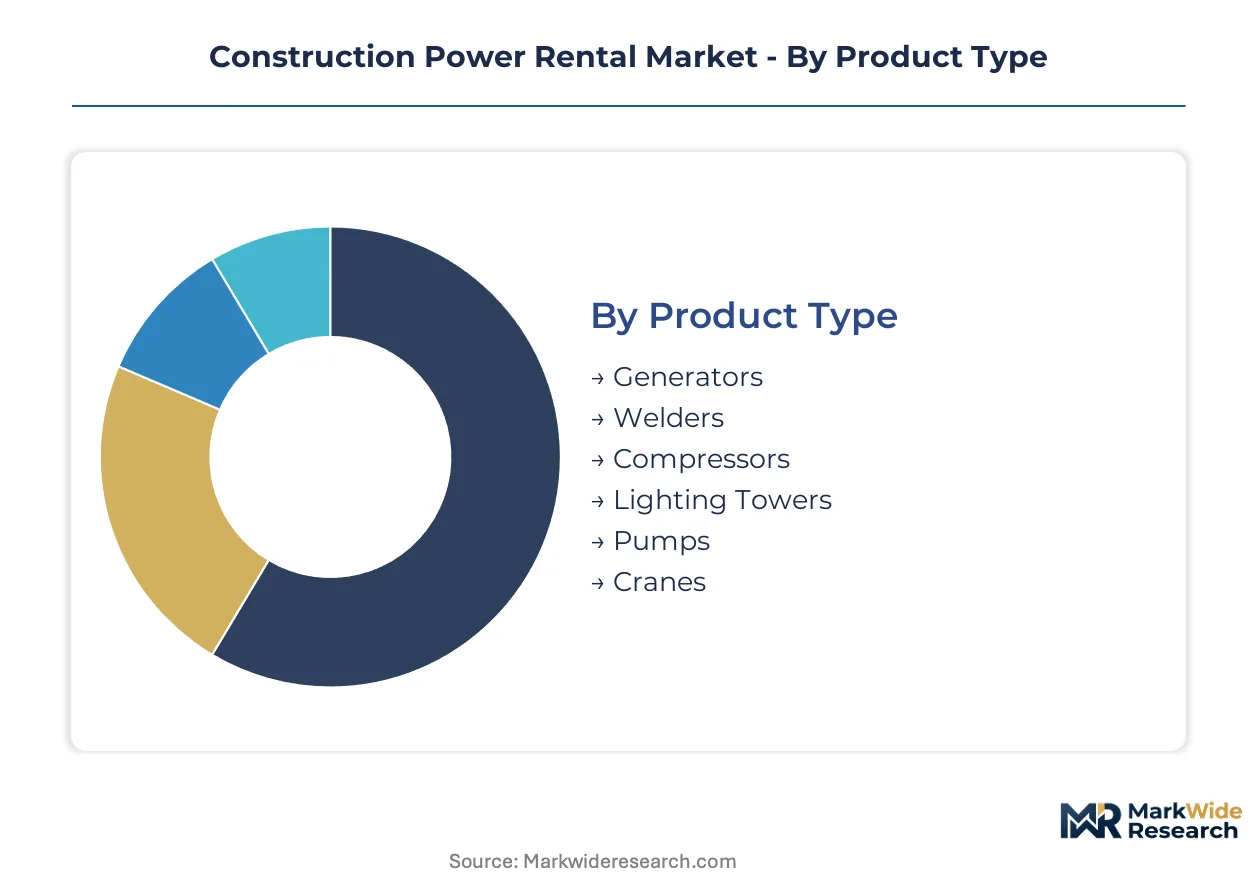
Segmentation in construction power rental reveals how fleet operators allocate capital across equipment categories, fuel technologies, and contract types. Rental providers size inventory positions by matching generator specifications to project phase requirements and emissions compliance timelines.
Product Type:
Supply concentration clusters around mobile prime movers that deliver three-phase power at construction voltage standards, with ancillary equipment filling operational gaps.
- Generators:Reciprocating engine units rated 20 kW to 2,500 kW form the revenue core of every rental fleet, powering tower cranes, concrete batch plants, and welding operations across civil engineering phases. Infrastructure projects in Saudi Arabia's gigaproject corridor command the longest deployment cycles and highest per-unit pricing for 500+ kW continuous-duty models.
- Welders:Engine-driven welding generators combine auxiliary power generation with arc welding capability, reducing equipment count on pipeline and structural steel sites. Demand concentrates in oil and gas infrastructure buildouts across the Middle East where multi-process welding requirements extend rental durations.
- Compressors:Portable air compression systems support pneumatic tools, shotcrete application, and dewatering operations in tunneling and foundation work.
- Lighting Towers:Mast-mounted LED arrays on mobile trailers extend workable hours in earthmoving and paving operations with lower fuel consumption than metal-halide predecessors.
- Pumps:Engine-driven centrifugal and diaphragm pumps handle groundwater control, slurry transfer, and concrete pumping in below-grade construction phases.
- Cranes:Mobile crane power packs and auxiliary generators support lattice boom and telescopic crane operations where grid connection is unavailable.
Generators absorb the bulk of installed capacity; lighting towers are expanding most quickly as LED efficiency and solar-hybrid configurations displace diesel-only models.
Technology:
Capital allocation across fuel platforms reflects regulatory phase-in schedules and site-specific emissions constraints rather than pure cost optimization.
- Diesel:Compression-ignition engines dominate existing rental fleets for their power density, fuel availability, and technician familiarity, though EPA Tier 4 Final aftertreatment requirements elevate acquisition costs and maintenance complexity.
- Gasoline:Spark-ignition units fill the sub-50 kW portable segment for light construction and residential applications where transport weight and noise restrictions matter more than fuel efficiency.
- Electric:Grid-tied or battery-stored power eliminates local emissions and noise, suiting urban construction zones in Germany and the Netherlands with strict EU Stage V implementation.
- Solar:Photovoltaic arrays paired with battery storage reduce diesel runtime 30-50% in remote sites with high irradiance, opening premium pricing tiers in Western Australia and the Permian Basin.
- Hybrid:Battery-diesel configurations combining downsized prime movers with lithium-ion storage are climbing the fastest as mining and pipeline operators seek fuel cost predictability.
- Hydrogen:Fuel cell prototypes are entering demonstration fleets for zero-emission mandates in California and European urban cores, though supply infrastructure limits deployment scale.
Diesel retains the largest installed base; hybrid configurations are climbing the fastest as fuel volatility and carbon reporting intensify.
Application:
Project duration and power density requirements segment rental demand into distinct contract economics and equipment specifications.
- Infrastructure Projects:Bridges, tunnels, and water treatment facilities require sustained multi-year temporary power with 24/7 uptime guarantees, generating the deepest rental durations and highest service attachment rates.
- Commercial Buildings:High-rise construction and mixed-use developments demand 480V three-phase capacity for tower cranes and concrete pumps, with grid interconnection delays extending rental timelines.
- Residential Complexes:Subdivision and multi-family construction generates volume through shorter, more standardized contracts with faster equipment turnover and lower per-unit pricing.
- Industrial Facilities:Manufacturing plant construction and refinery turnarounds require redundant power capacity and specialized hazardous location certifications.
- Road Construction:Highway and airport paving operations utilize mobile power for asphalt plants, milling machines, and lighting across linear project corridors.
- Mining:Open-pit and underground extraction sites command the largest unit sizes and harshest operating conditions, with remote locations necessitating comprehensive fuel and maintenance service bundles.
Infrastructure projects generate the longest contract tenors; mining applications are gaining share fastest as commodity prices sustain capital deployment in underpenetrated African markets.
End User:
Procurement sophistication and risk transfer preferences divide the customer base between self-operated fleets and full-service rental arrangements.
- General Contractors:Prime construction firms balance owned fleet utilization against rental flexibility, with large EPCs in the Middle East increasingly favoring power-as-a-service contracting for gigaproject portfolios.
- Equipment Rental Companies:Specialized rental providers aggregate demand across multiple job sites, achieving scale economies in maintenance and logistics that single-project owners cannot replicate.
- Specialty Contractors:Piling, foundation, and mechanical trade contractors rent application-specific equipment for discrete construction phases with irregular scheduling.
- Government Agencies:Public works departments and defense construction commands specify emissions-compliant equipment in bid documents, with procurement cycles extending 12-18 months.
- Utility Providers:Grid operators rent temporary generation for emergency response, planned maintenance, and interconnection support during infrastructure upgrades.
Equipment rental companies command the largest aggregate demand; utility providers are expanding their rental engagement fastest as grid modernization accelerates temporary power requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Saudi Arabia's gigaproject corridor concentrate fleet deployment commitments as NEOM, Red Sea Project, and Qiddiya developments sustain multi-year temporary power demand.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya gigaprojects anchor sustained multi-year temporary power contracts. SFDA and Saudi Building Code compliance shape equipment specifications for international contractors. Riyadh and the Eastern Province concentrate rental fleet staging yards serving linear infrastructure corridors.
United States
Permian Basin oilfield infrastructure and Texas-Louisiana industrial construction extend rental durations for 500+ kW units. EPA Tier 4 Final and California Air Resources Board rules accelerate hybrid and natural-gas generator adoption. Houston and Midland-Odessa form the dominant equipment staging clusters for shale patch deployment.
Germany
Tunneling and water treatment projects in urban construction zones drive demand for EU Stage V-compliant temporary power. REACH and national emissions regulations mandate ultra-low emission equipment in non-attainment zones. The Ruhr industrial corridor and Bavarian construction belt concentrate rental operator logistics networks.
Australia
Mining operations in Western Australia's Pilbara region command the largest unit sizes and harshest operating conditions. National Greenhouse and Energy Reporting obligations intensify carbon accounting requirements for remote site power. Perth and Port Hedland serve as the primary equipment marshaling points for fly-in-fly-out project support.
India
Highway construction under the National Infrastructure Pipeline and metro rail expansion generate volume demand for mobile generators. The PLI scheme for domestic capital goods assembly reduces import duties on generator components. Maharashtra and Gujarat host the most developed rental infrastructure serving western industrial corridors.
Construction Power Rental Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated engine producers commanding premium positioning in long-duration infrastructure contracts while regional rental aggregators capture volume in shorter-cycle residential and commercial building phases. The market structure consolidates around three strategic archetypes: captive engine manufacturers with integrated control systems, modular power architecture specialists, and hybrid energy service providers. Competitive moves concentrate on fleet emissions compliance upgrades and power-as-a-service contracting models that transfer operational risk from EPC contractors to rental providers.
Within the integrated manufacturing tier, Caterpillar and Cummins exemplify divergent approaches to equipment supply—Caterpillar through captive engine production and Cummins through modular power architecture designed for rapid transport and commissioning. Aggreko occupies a distinct position as a hybrid energy service specialist, anchoring premium positioning in remote infrastructure sites through bundled fuel management and carbon reporting capabilities. United Rentals and Ashtead Group represent the scale-driven rental aggregator archetype, achieving logistics economies across dispersed job site portfolios that single-project owners cannot replicate internally.
| Leading Market Players |
|---|
| United Rentals |
| Aggreko |
| Ashtead Group |
| Herc Rentals |
| Atlas Copco |
| Caterpillar |
| Cummins |
| Generac Power Systems |
| Himoinsa |
| Others |
Pricing and Supply Chain Analysis
EPA Tier 4 Final compliance mandates in the United States are forcing rental fleet operators to absorb premium capital costs for aftertreatment-equipped generators, compelling supply chain restructuring toward certified engine suppliers and compressing margins until rate adjustments pass through to infrastructure contractors.
Pricing Analysis
Short lead-time premiums dominate rental rate structures, with contractors paying markups of 20-35% for equipment delivered within 72 hours versus standard 14-day scheduling windows. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier 4 Final certification status, equipment age, and bundled service attachment rates. Cost compression in the diesel-only tier is intensifying because older non-compliant units face accelerated depreciation and limited resale markets. Residential complex developers exhibit highest price sensitivity due to standardized contract terms, while mining operators in remote locations demonstrate lowest sensitivity given fuel cost predictability priorities.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese cylinder block foundries and American fuel injection system manufacturers, creating concentration risk for rental fleet operators dependent on just-in-time engine deliveries. Raw material dependencies include high-grade steel castings, copper windings for alternators, and platinum-group metals for catalytic aftertreatment systems. Tariff exposure on Chinese-sourced battery components for hybrid configurations elevates landed costs for lithium-ion storage modules. Distribution runs through regional equipment staging yards in Houston, Riyadh, and Perth that marshal inventory for fly-in-fly-out project deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA Tier 4 Final and EU Stage V emissions frameworks erect substantial capital barriers that protect incumbent fleet operators with compliant inventory while marginalizing undercapitalized regional competitors.
For Market Incumbents: Deepen captive maintenance capabilities and certified technician training programs to defend against Aggreko's power-as-a-service bundling. Expand hybrid energy inventory positions in Western Australia and the Permian Basin to capture fuel cost predictability demand from mining operators. Prioritize backward integration into aftertreatment system refurbishment to control lifecycle costs on Tier 4 Final fleets. For New Entrants and Emerging Players: Capture first-mover positioning in underpenetrated African mining corridors—specifically the Democratic Republic of Congo and Zambia—where established rental infrastructure remains absent and commodity prices sustain capital deployment. Deploy solar-diesel hybrid configurations as the go-to-market wedge, leveraging 30-50% fuel consumption reductions to win multi-year infrastructure contracts against diesel-only incumbents. For Investors and Strategic Acquirers: The window for entry favors regional rental aggregators with established logistics networks in Saudi Arabia's gigaproject corridor or India's PLI-subsidized manufacturing zones. Long-term viability hinges on fleet emissions compliance positioning rather than pure scale. Watch for California Air Resources Board rule extensions to older units as the signal for accelerated capital deployment requirements across the United States.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Energy Fleet Conversion | Battery-diesel configurations enable 40-60% runtime on stored energy, hedging diesel price volatility for mining operators. |
| Power-as-a-Service Contracting | Bundled fuel management and carbon reporting transfers operational risk from EPC contractors to rental providers in Saudi gigaprojects. |
| Aftertreatment System Backward Integration | In-house selective catalytic reduction refurbishment controls lifecycle costs and accelerates EPA Tier 4 Final compliance timelines. |
| African Market First-Mover Positioning | Underpenetrated mining corridors in DRC and Zambia lack established rental infrastructure, favoring early fleet deployment. |
| Certified Technician Training Scale-Up | EPA Tier 4 Final and EU Stage V diagnostics require specialized skills that rental operators struggle to source at volume. |
Research Methodology
Trade association filings, customs and import records, and equipment registration databases formed the secondary backbone for this analysis, cross-referenced against primary interviews with fleet operations directors, EPC procurement managers, and aftertreatment system engineers. Conversations with Saudi gigaproject contractors and Australian mining operators supplied demand-side validation, while SEC filings from United Rentals and Ashtead Group informed rental rate economics. Bottom-up unit deployment estimates triangulated against top-down market value reconstructions to anchor forecast confidence.
Bottom-up modeling aggregated generator unit deployments by power rating tier, fuel technology, and application vertical, then applied regional rental rate structures to derive value estimates across the projection horizon. Segmentation dimensions included product type, fuel technology platform, project application, and end-user procurement sophistication. CAGRs were computed from fitted growth curves calibrated to disclosed fleet expansion announcements and project pipeline tracking. Key inputs comprised grid interconnection delay timelines, emissions compliance phase-in schedules, and commodity price volatility assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement intensity, battery energy density improvements, and African mining investment cycles. Forecasts reflect documented assumptions about fleet replacement rates and hybrid technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
CNC Router Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Portable Welding Generators Market
Construction Equipment
Grader Blades Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Utility Locator Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
UK Heavy Construction Equipment Rental Market