
 Tile Cutter Market | 2026-2036
Tile Cutter Market Size, Share, and Industry Trends Forecast 2026-2036
Tile Cutter Market Outlook
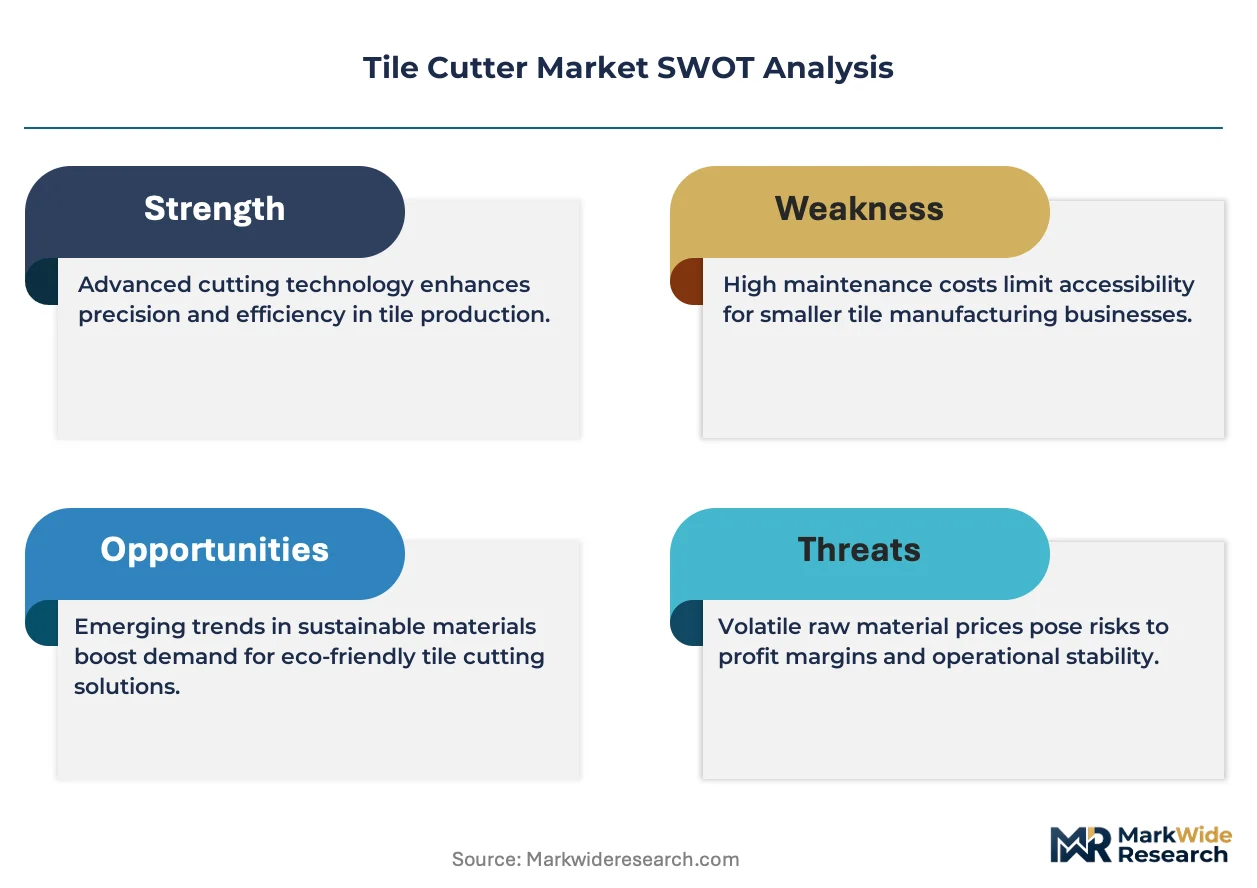
Equipment leasing and project-based rental models is rewriting capital deployment for tile cutting fleets, enabling smaller contractors to access precision machinery without ownership burdens. Robert Bosch GmbH leverages its power tool ecosystem to bundle cutters with battery platforms that lock in accessory revenue. Makita Corporation anchors its position through brushless motor technology that extends duty cycles on commercial job sites. Festool GmbH differentiates via dust extraction integration that sustains premium pricing in health-regulated environments.
A tile cutter is a mechanical or powered device engineered to score, snap, or abrade ceramic, porcelain, or stone tiles along controlled planes, typically achieving cutting tolerances within 0.5 millimeters for joint alignment in finished installations. Electric cutter models incorporating diamond wet blades dominate volume sales for porcelain, where material hardness exceeds the capacity of manual scoring wheels. The contractor end-user segment commands the largest margin pool due to replacement frequency and specification sensitivity, while robotic cutting systems represent the fastest-growing technology category as prefabrication facilities automate complex mosaic and large-format layouts.
German KBA-equivalent workplace safety frameworks and EU REACH substance restrictions on abrasive slurry disposal shape product design requirements for European manufacturers. OSHA silica exposure limits in the United States mandate integrated water suppression or vacuum systems on job site equipment, creating compliance-driven upgrade cycles. Stakeholders must monitor how evolving ISO standards for airborne particulate control in construction equipment will determine market access thresholds across export destinations.
Market Dynamics
Waterjet cutting technology is collapsing the traditional scoring-wheel paradigm in porcelain fabrication, forcing equipment manufacturers to reengineer core architectures around abrasive suspension systems rather than mechanical fracture mechanics.
Growth Catalysts
- OSHA silica exposure limits:Mandated water suppression and vacuum integration on job site equipment triggers compliance-driven replacement cycles across US residential renovation contractors.
- Porcelain hardness thresholds:Material specifications exceeding manual scoring capacity push demand toward electric wet-blade systems in German Bauhaus and Hornbach retail networks.
- Prefabrication automation:Robotic cutting systems capture momentum in mosaic and large-format layout facilities seeking micron-level repeatability.
Market Restraints
- Diamond abrasive cost volatility:Synthetic diamond supply concentration in limited manufacturing regions creates input price instability for wet-blade producers.
- EU REACH slurry disposal:Substance restrictions on abrasive wastewater handling add compliance overhead for European fabricators using waterjet systems.
- Manual cutter substitution ceiling:Ceramic tile segments retain scoring-wheel economics where material hardness permits, capping premium equipment penetration.
Strategic Opportunities
- Equipment leasing proliferation:Project-based rental models unlock precision machinery access for smaller contractors without capital ownership burdens.
- Dust extraction integration:Health-regulated environments in Germany and adjacent markets sustain premium pricing for systems bundling capture technology.
- Battery platform convergence:Cordless cutter development tied to existing power tool ecosystems creates aftermarket lock-in through accessory compatibility.
Industry Challenges
- ISO particulate standard alignment:Evolving airborne control thresholds for construction equipment create certification timeline uncertainty for export-bound manufacturers.
- Waterjet maintenance specialization:Abrasive nozzle replacement and pump calibration require technician training programs that lag equipment deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tile Cutter Market |
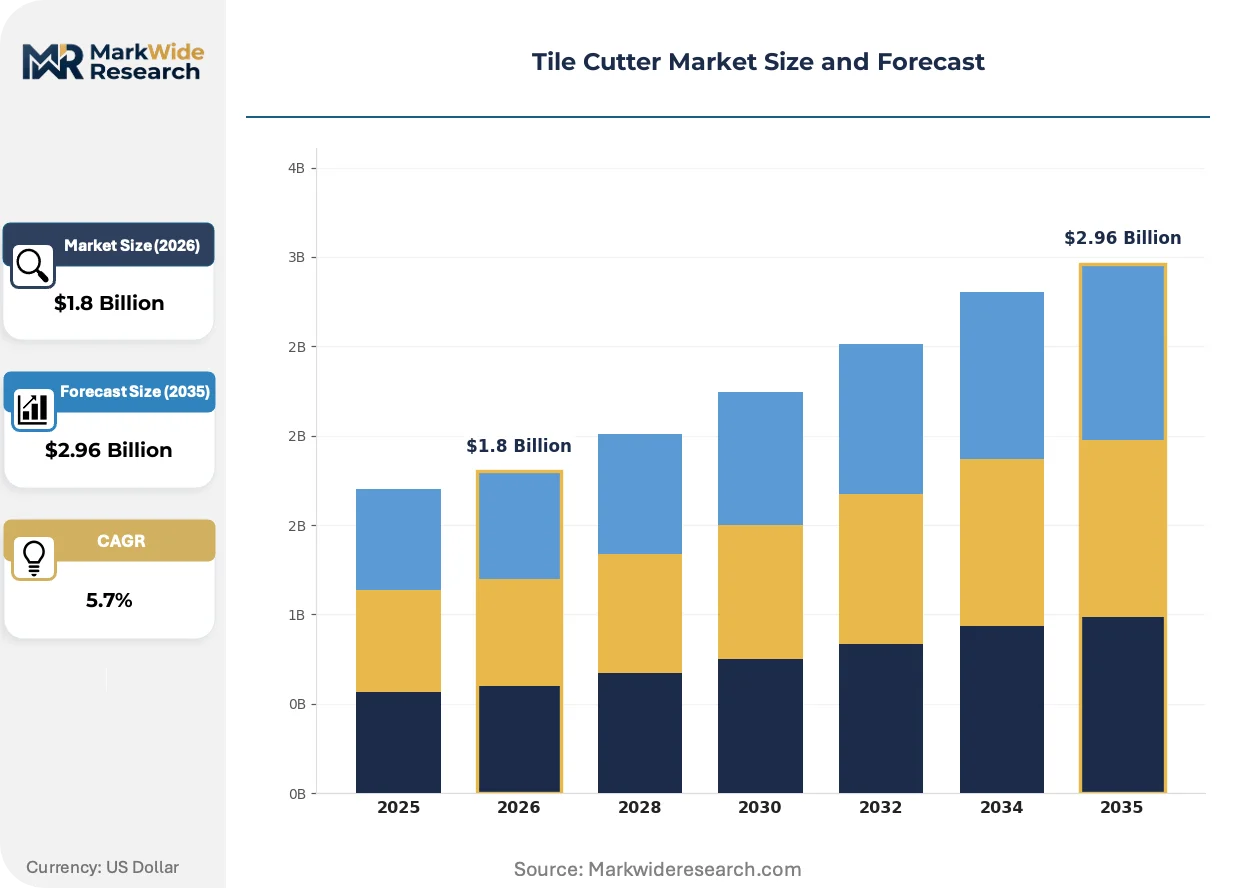
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cutter, Electric Cutter, Laser Cutter, Pneumatic Cutter End User: Contractors, DIY Enthusiasts, Retailers, Commercial Installers Material: Ceramic, Porcelain, Glass, Natural Stone Technology: Hydraulic, Mechanical, Electric, Robotic |
| Companies Covered | Hilti AG, Atlas Copco AB, Stanley Black & Decker, Inc., KYOCERA Corporation, Festool GmbH, Robert Bosch GmbH, Husqvarna AB, Brevetti Montolit Spa, Makita Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tile Cutter Market Strategic Shifts
Active transformation in tile cutting centers on three vectors: abrasive precision technology displacing mechanical methods, regulatory frameworks rewriting equipment specifications, and capital-light access models restructuring contractor procurement.
Waterjet cutting systems employing garnet abrasive suspension are collapsing the performance ceiling that constrained manual scoring wheels. Prefabrication facilities processing large-format porcelain panels adopt these systems to achieve cutting tolerances within 0.5 millimeters for joint alignment. The technology compresses traditional multi-step fabrication into single-pass operations, eliminating snap-break variance that plagued mechanical methods.
EU REACH substance restrictions on abrasive slurry disposal are reshaping product design requirements for European manufacturers. Industrial consequence manifests in closed-loop water recycling architectures and filtration subsystem integration. German KBA-equivalent workplace safety frameworks impose the strictest compliance burdens, forcing export-oriented suppliers to engineer for maximum regulatory denominator.
Contractor procurement behavior is pivoting toward fleet access without ownership. Smaller renovation specialists in aging housing stock markets lease precision cutters for project duration rather than carrying depreciation. Equipment-as-a-service penetration concentrates in Germany and developed European economies where capital efficiency pressures intersect with standardized professional-grade retail access.
Tile Cutter Market Segmentation
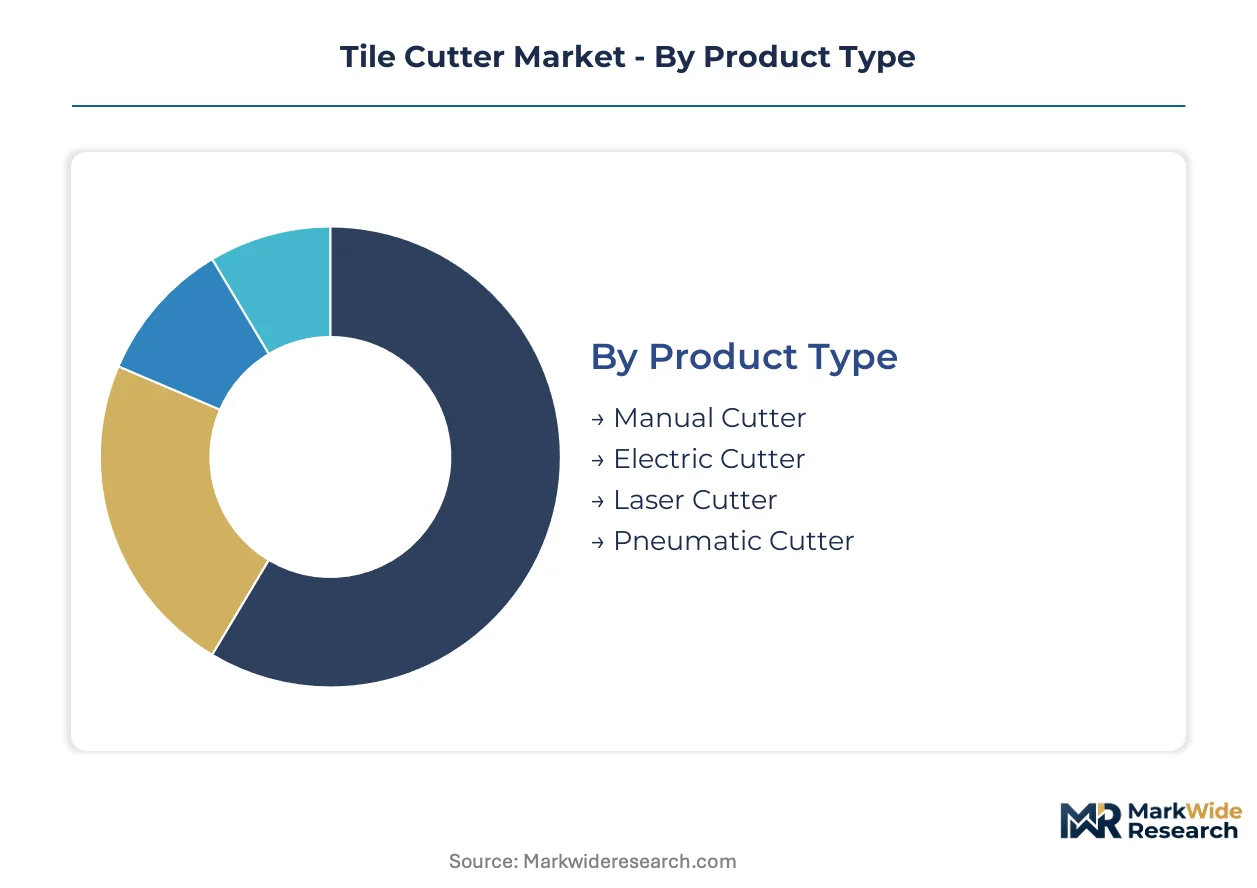
Segmentation in tile cutting equipment reveals distinct replacement rhythms and margin profiles across user types and material applications. Equipment manufacturers calibrate warranty terms and service attach rates based on these differential cycle patterns.
Product Type:
Replacement frequency varies dramatically across product categories, with job-site electric units turning over fastest due to abrasive wear and battery degradation, while manual cutters persist for years in occasional-use settings.
- Manual Cutter:Lever-action scoring devices with hardened tungsten carbide wheels dominate ceramic tile applications where material hardness permits clean snap fracture. DIY enthusiasts and small renovation crews in Germany's Bauhaus retail channels favor these units for capital efficiency on intermittent projects.
- Electric Cutter:Diamond wet-blade systems with integrated water suppression address porcelain hardness thresholds exceeding manual scoring capacity. Contractors processing large-format panels drive replacement cycles through abrasive blade consumption and motor duty-cycle limits.
- Laser Cutter:CO2 and fiber laser systems enable contact-free scoring of delicate glass mosaic substrates.
- Pneumatic Cutter:Compressed-air actuated units serve high-volume fabrication environments with centralized shop air infrastructure.
Manual cutters dominate installed base across residential renovation markets. Electric wet-blade systems are where expansion concentrates as porcelain specifications harden.
End User:
Margin capture potential separates sharply between price-sensitive occasional users and specification-driven commercial operators with fleet standardization requirements.
- Contractors:Professional renovation specialists operating across aging housing stock in developed economies generate recurring demand through equipment replacement and abrasive consumables. OSHA silica compliance mandates in the United States accelerate upgrade cycles toward integrated dust extraction models.
- Commercial Installers:Prefabrication facilities and large-scale hospitality contractors deploy robotic cutting systems for micron-level repeatability in mosaic layouts. These operators represent the steepest expansion trajectory as automation penetrates tile fabrication.
- DIY Enthusiasts:Home improvement hobbyists purchase entry-level manual and small-format electric units through retail networks.
- Retailers:Tool rental depots and equipment-as-a-service providers maintain diversified fleets for project-based contractor access.
Contractors command the largest revenue pool through replacement frequency. Commercial installers are where technology migration accelerates fastest.
Material:
Substrate hardness directly dictates cutting technology selection and blade specification, creating tiered equipment requirements across application types.
- Porcelain:Ultra-compact surfaces with Mohs hardness exceeding 7.5 demand diamond wet-blade or waterjet abrasive systems. German fabricators processing large-format porcelain panels drive specification intensity for precision tolerance equipment.
- Natural Stone:Granite and marble fabrication requires heavy-duty bridge saws and CNC waterjet systems with garnet abrasive suspension. Commercial countertop installers in stone processing clusters concentrate demand for high-horsepower cutting platforms.
- Ceramic:Traditional glazed wall and floor tiles permit manual scoring-wheel economics in residential renovation applications.
- Glass:Brittle transparent substrates require specialized scoring and thermal shock separation or laser processing.
Ceramic applications retain the broadest installed base. Porcelain fabrication is where equipment specification intensity climbs fastest.
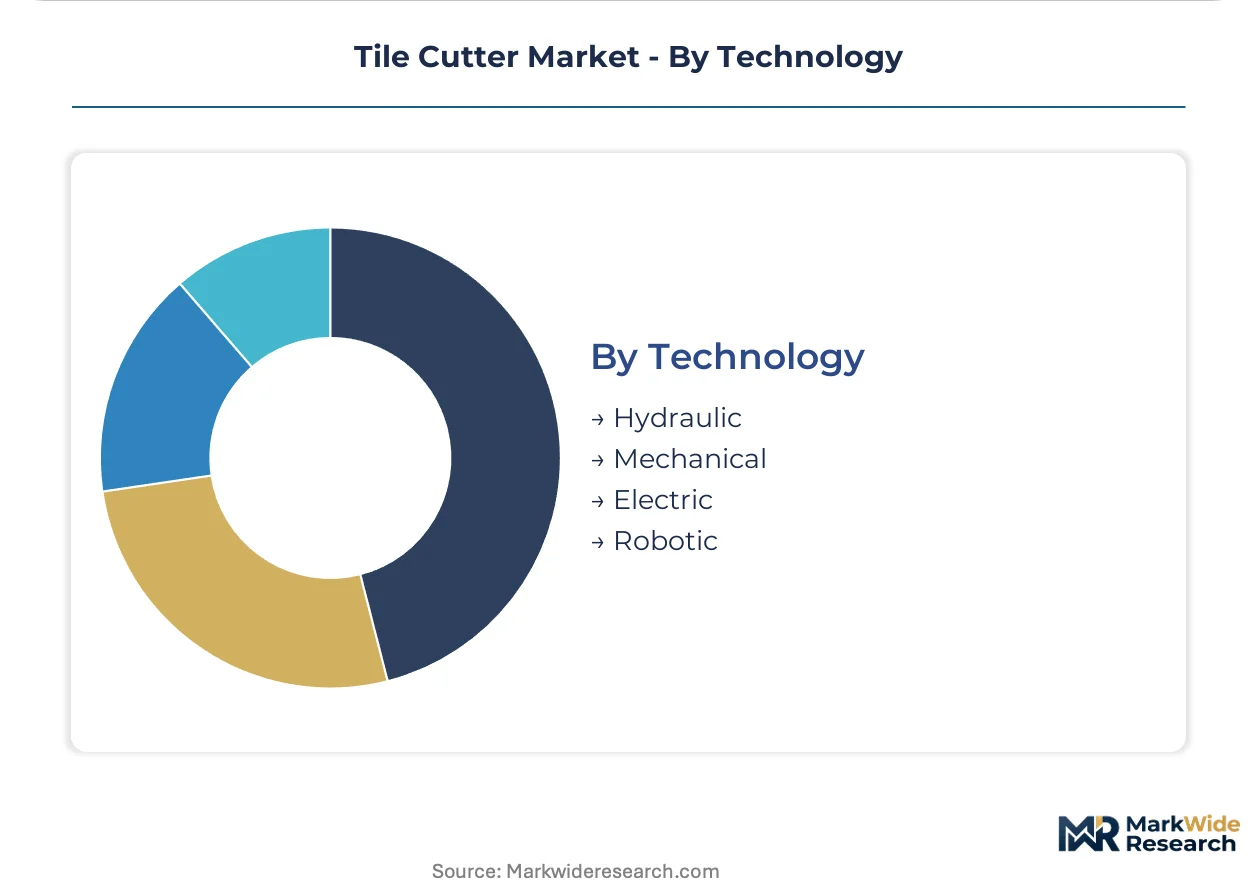
Technology:
Capital deployment and operating cost structures diverge substantially across technology categories, from low-maintenance mechanical systems to precision-calibrated robotic platforms.
- Robotic:Multi-axis CNC systems with vision-guided alignment automate complex mosaic pattern cutting and large-format panel processing. Prefabrication facilities in Germany and adjacent EU markets adopt these systems to address skilled labor constraints and micron-level repeatability requirements.
- Electric:Brushless motor platforms with battery ecosystem compatibility dominate portable job-site applications. Makita and Bosch power tool ecosystems lock in aftermarket accessory revenue through proprietary battery interfaces.
- Hydraulic:High-force actuation systems serve heavy-duty stone and thick porcelain cutting in industrial fabrication settings.
- Mechanical:Simple lever and rail scoring mechanisms persist in low-cost ceramic tile applications.
Electric systems dominate portable equipment shipments. Robotic platforms are where automation investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German KBA-equivalent workplace safety frameworks and EU REACH substance restrictions on abrasive slurry disposal are reshaping equipment specifications across developed markets. These regulatory pressures intersect with aging housing stock renovation cycles to concentrate demand in specific national markets.
United States
OSHA silica exposure limits mandate integrated water suppression or vacuum systems on job site equipment, triggering compliance-driven replacement cycles among residential renovation contractors. The EPA oversees construction waste disposal standards affecting abrasive slurry handling. Tool demand concentrates in Sun Belt metros including Phoenix, Houston, and Atlanta where housing stock turnover sustains contractor fleet expansion.
Germany
Bauhaus and Hornbach retail networks standardize professional-grade equipment access for tradespeople processing large-format porcelain panels. KBA workplace safety frameworks impose strict dust extraction requirements on portable cutting equipment. Industrial fabrication clusters in North Rhine-Westphalia and Bavaria drive specification intensity for precision tolerance machinery serving prefabrication facilities.
China
MIIT industrial upgrading initiatives accelerate automation adoption in ceramic and porcelain processing facilities. GB standards for construction equipment safety shape product certification requirements for domestic and export-bound manufacturers. Manufacturing gravity centers on Guangdong and Fujian provinces where tile production clusters concentrate demand for high-volume cutting platforms.
Japan
METI energy efficiency regulations influence brushless motor development for portable cutting equipment in commercial applications. JIS standards govern precision tolerances for finished tile installations in high-end residential construction. Tokyo-Osaka corridor contractors drive replacement frequency for battery-compatible platforms integrated with existing power tool ecosystems.
India
BIS certification requirements for construction equipment create compliance timelines for imported cutting machinery serving commercial real estate development. The PLI scheme for manufacturing incentivizes domestic assembly of precision fabrication equipment. Demand concentrates in Maharashtra and Gujarat where urban infrastructure expansion sustains contractor fleet growth.
Tile Cutter Market Competitive Environment
On the supply side, the industry is structured around three distinct strategic tiers. Power tool conglomerates leverage battery platform ecosystems to lock in aftermarket accessory revenue through proprietary interfaces. Specialized precision equipment manufacturers command premium positioning via dust extraction integration and health-regulated environment compliance. Industrial automation suppliers capture prefabrication facility demand through robotic cutting system deployment. Dominant competitive moves include strategic partnerships for distribution network expansion and portfolio diversification into adjacent surface fabrication technologies.
Within the power tool ecosystem tier, Robert Bosch GmbH and Makita Corporation exemplify archetypes competing through battery platform convergence and brushless motor durability. Festool GmbH occupies a position representing premium-tier differentiation via occupational health integration. Hilti AG anchors the commercial construction specialist segment. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning: German GmbH structures dominate precision-engineered segments while Japanese corporations and Liechtenstein-based entities concentrate on portable equipment scale.
| Leading Market Players |
|---|
| Hilti AG |
| Atlas Copco AB |
| Stanley Black & Decker, Inc. |
| KYOCERA Corporation |
| Festool GmbH |
| Robert Bosch GmbH |
| Husqvarna AB |
| Brevetti Montolit Spa |
| Makita Corporation |
| Others |
Value Chain & Pricing Dynamics
Guangdong province manufacturing clusters anchor global wet-blade production capacity, concentrating supply-side leverage among diamond abrasive processors who dictate terms to downstream cutter assemblers. This geographic density amplifies pricing power for synthetic diamond suppliers while compressing margins for finished equipment manufacturers dependent on just-in-time abrasive deliveries.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with ISO-compliant dust extraction systems commanding substantial premiums over baseline models. Three-tier pricing structure separates premium brushless motor platforms from standard brushed units and economy manual cutters. Pricing pressure stems from battery ecosystem commoditization as power tool giants cross-bundle cutters with existing cordless platforms. DIY enthusiasts exhibit highest price sensitivity, while commercial installers prioritize specification compliance over unit cost.
Supply Chain Analysis
Synthetic diamond feedstock draws from concentrated manufacturing regions in China, Ireland, and Russia, creating input dependency for wet-blade producers. Tungsten carbide scoring wheels and garnet abrasive suspensions represent secondary critical inputs with limited supplier alternatives. Single-source vulnerability in high-purity synthetic diamond supply exposes blade manufacturers to disruption risk. Distribution runs through specialized tool retailers, construction equipment depots, and direct OEM channels serving contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service and consumables attach rates expand faster than hardware unit sales, positioning aftermarket revenue streams as the primary value capture mechanism. Abrasive blade replacement cycles and maintenance contracts now exceed original equipment margins in lifetime customer value.
For Market Incumbents: Pre-empt waterjet technology displacement by acquiring abrasive suspension system capabilities before fabrication automation accelerates. Secure backward integration into synthetic diamond supply through long-term offtake agreements with Chinese and Irish producers. Channel control through exclusive Bauhaus and Hornbach retail partnerships defends against battery platform commoditization threats from power tool conglomerates. For New Entrants and Emerging Players: Pursue project-based leasing models targeting small German renovation contractors capital-constrained by aging housing stock repair cycles. Equipment-as-a-service penetration in North Rhine-Westphalia and Bavaria industrial clusters offers lowest competitive density. Partner with existing tool rental depots rather than building proprietary distribution infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision equipment manufacturers with dust extraction integration and health-regulated environment compliance. Long-term viability hinges on automation exposure as prefabrication facilities displace job-site cutting. Target acquisition archetype: robotic cutting system specialists serving mosaic and large-format panel processors. Monitor OSHA silica enforcement intensity and EU REACH slurry disposal rulemaking as inflection indicators for compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Supply | Captive abrasive feedstock secures margin stability against supply concentration in China and Ireland. |
| Dust Extraction Certification Investment | German KBA-equivalent compliance unlocks premium positioning in EU health-regulated construction environments. |
| Equipment-as-a-Service Platform Launch | Project-based leasing models capture recurring revenue from capital-constrained renovation contractors. |
| Robotic Cutting System Acquisition | Prefabrication automation exposure addresses skilled labor constraints in German industrial clusters. |
| Battery Ecosystem Partnership | Proprietary cordless platform integration locks in aftermarket accessory revenue through compatibility requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC equipment manufacturer filings, and EU regulatory disclosure archives. Contractor interviews, aftermarket service managers, diamond abrasive procurement leads, and prefabrication facility operations directors provided demand-side validation. Top-down market sizing from housing renovation expenditure data and bottom-up equipment shipment analysis were cross-referenced for convergence.
Forecast inputs include product type substitution curves, end-user replacement frequency patterns, and regional regulatory compliance timelines. Segmentation modeling spans manual, electric, and robotic technology tiers across contractor, commercial installer, and DIY user categories. CAGRs derive from equipment lifecycle analysis and abrasive consumables attach rate projections. Porcelain hardness specification trends and waterjet adoption curves in German fabrication clusters inform technology migration assumptions.
Macroeconomic conditions sit as an overlay; deviation in residential construction expenditure and synthetic diamond pricing volatility would shift the trajectory. Forecasts reflect documented assumptions about OSHA enforcement continuity and EU REACH implementation pacing. Cross-checking against construction equipment trade association shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Garden Digging Tools Market
Tools
Tool Pliers Market
Tools
Construction Anchors Market
Tools
Entrenching Tool Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Power Tool Accessories Market
Tools
Tape Measure Market
Tools
Pneumatic Tools Market
Tools
Deburring Tool Market
Tools
Allen Key Market
Tools
Surface Levelling Equipment Market
Tools
Surface Planer Market
Tools
Laser Engraving Machine Market
Tools
Crimping Tool Market
Tools
Automotive Torque Tools Market
Tools
Cordless Fillet Weld Grinder Market