
 Wood Chipper Market | 2026-2036
Wood Chipper Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Chipper Market Analytics
North American forestry equipment manufacturing is restructuring around cleaner powertrains and modular designs. Morbark LLC sustains dominance in high-torque drum chippers for professional arborists. Vermeer Corporation leverages vertical integration into engine packaging and undercarriage systems for towable units. Bandit Industries Inc. specializes in hand-fed disc chippers with specialized knife configurations for hardwood processing.
A wood chipper is a mechanical reduction machine that uses a rotating drum or disc fitted with hardened steel knives to shred branches, logs, and vegetative debris into uniform chips typically ranging from 10 mm to 50 mm in length. Drum chippers lead in industrial forestry applications where high feed rates and consistent chip geometry matter for pulp mill specifications. Electric power sources represent the fastest-expanding category among municipal and landscaping fleets seeking noise abatement and zero-emission compliance. Diesel configurations still anchor margin pools in remote logging operations where grid access remains unavailable.
EPA Tier 4 Final standards and OSHA machine guarding requirements shape product design timelines and certification costs for equipment sold in the United States. The EU Machinery Directive and CE marking obligations govern export eligibility for European landscaping contractors. Stakeholders must monitor battery energy density improvements and charging infrastructure rollouts to determine optimal timing for fleet electrification investments.
Market Dynamics
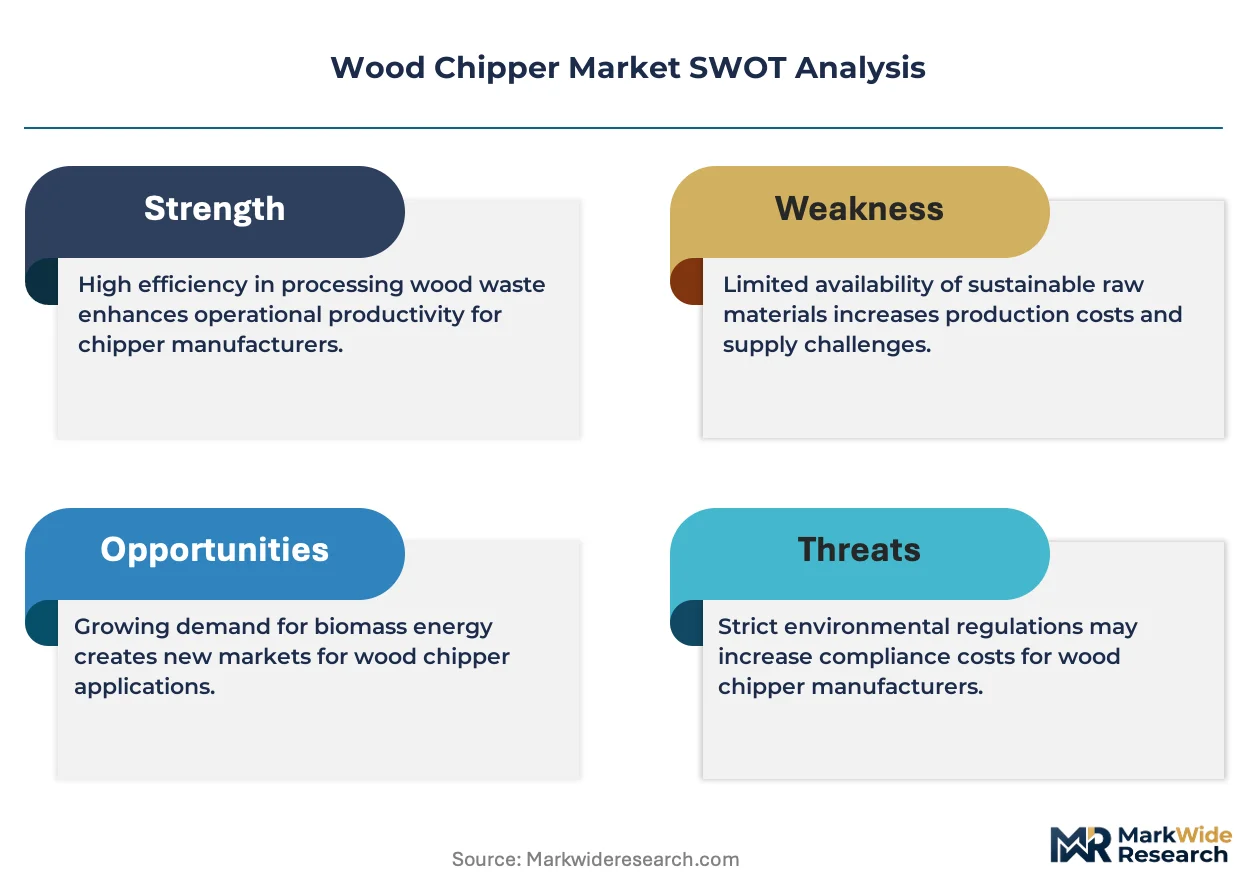
EPA Tier 4 Final emission standards are forcing diesel engine redesigns toward hybrid and electric powertrains, while drum chipper manufacturers absorb certification costs that reshape competitive economics across the North American forestry equipment sector.
Growth Catalysts
- Urban tree removal services:Municipal fleets in the United States Pacific Northwest are replacing aging equipment with zero-emission electric chippers to meet local air quality mandates.
- OSHA machine guarding requirements:Updated safety standards are accelerating replacement cycles for pre-2020 equipment among professional landscaping contractors.
- Logging residue recovery:Pulp mills in Oregon and Washington are tightening chip geometry specifications, driving demand for high-torque drum configurations with hardened steel knife systems.
Market Restraints
- Battery energy density limitations:Lithium-ion cell performance constraints restrict continuous runtime for electric chippers below the threshold required for remote logging operations without grid access.
- Steel alloy supply concentration:Hardened knife blanks depend on specialized metallurgical suppliers concentrated in the Great Lakes industrial corridor.
- CE marking friction:European export eligibility requires EU Machinery Directive compliance that adds certification timelines and testing costs for US-based manufacturers.
Strategic Opportunities
- Suburban landscaping fleet electrification:Noise abatement ordinances in California municipalities are creating first-mover advantages for battery-powered hand-fed disc chipper suppliers.
- Charging infrastructure convergence:Pairing mobile DC fast-charging trailers with electric chipper deployments is unifying equipment and energy logistics for dispersed job sites.
- Modular undercarriage platforms:Standardized towable chassis designs are enabling rapid reconfiguration between drum and disc cutting systems without full unit replacement.
Industry Challenges
- Certification timeline compression:EPA Tier 4 Final engine recertification cycles are compressing product development windows and straining engineering bandwidth.
- Skilled technician scarcity:Maintenance of precision knife alignment and hydraulic feed systems requires specialized training that outpaces vocational program output in the Pacific Northwest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Chipper Market |
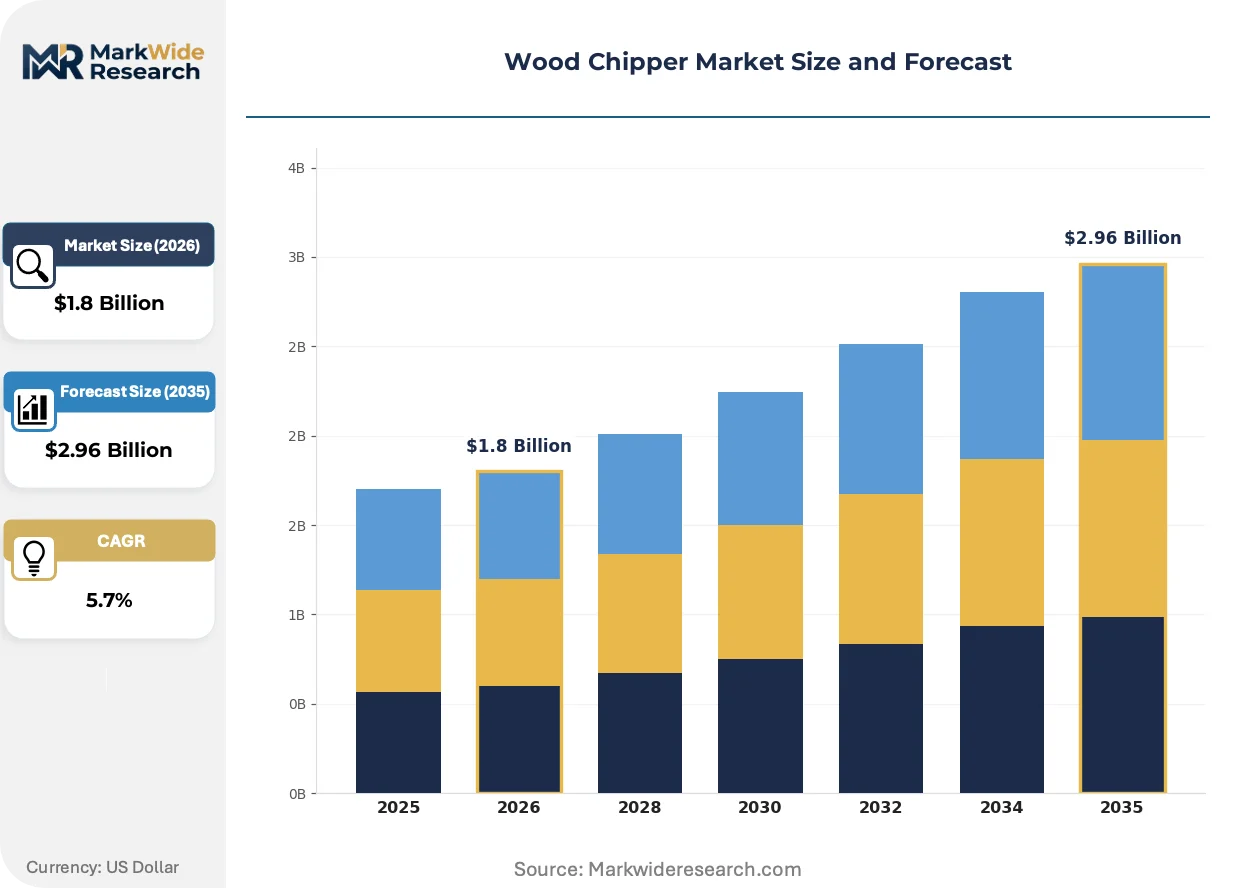
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Chippers, Disc Chippers, Multi-Function Chippers, Towable Chippers Power Source: Electric, Gasoline, Diesel, Hybrid End User: Landscaping, Forestry, Waste Management, Construction Size Category: Residential, Commercial, Industrial, Portable |
| Companies Covered | Astec Industries Inc., Morbark LLC, Vermeer Corporation, Husqvarna AB, UNTHA shredding technology GmbH, Bandit Industries Inc., Terex Corporation, Makita Corporation, Bruks Siwertell Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Chipper Market Evolving Landscape
Powertrain electrification and smart feed control systems are converging to redefine equipment lifecycle economics, while regulatory pressure on diesel emissions accelerates technology substitution timelines across municipal and commercial buyer segments.
Hybrid-electric drum drive systems are unifying high-torque cutting performance with zero-emission operation zones. Landscaping contractors in California and Washington are piloting these configurations for urban tree removal contracts with strict noise and air quality clauses. The technology is compressing the total cost of ownership gap between diesel and electric platforms by eliminating idle fuel consumption and reducing brake wear.
EPA Tier 4 Final standards are mandating selective catalytic reduction and diesel exhaust fluid systems for remaining combustion-powered units. These requirements are adding base cost and maintenance complexity that disadvantages smaller fleet operators. Professional arborist services in the United States are responding by accelerating electric procurement timelines and negotiating municipal charging partnerships.
Equipment-as-a-service contracts are displacing traditional capital purchase models among mid-sized landscaping businesses. Monthly subscription structures bundle maintenance, blade sharpening, and battery swap logistics into predictable operating expenses. This shift is most visible in the United States Pacific Northwest, where seasonal demand volatility makes fixed cost structures preferable to ownership risk.
Wood Chipper Market Segmentation
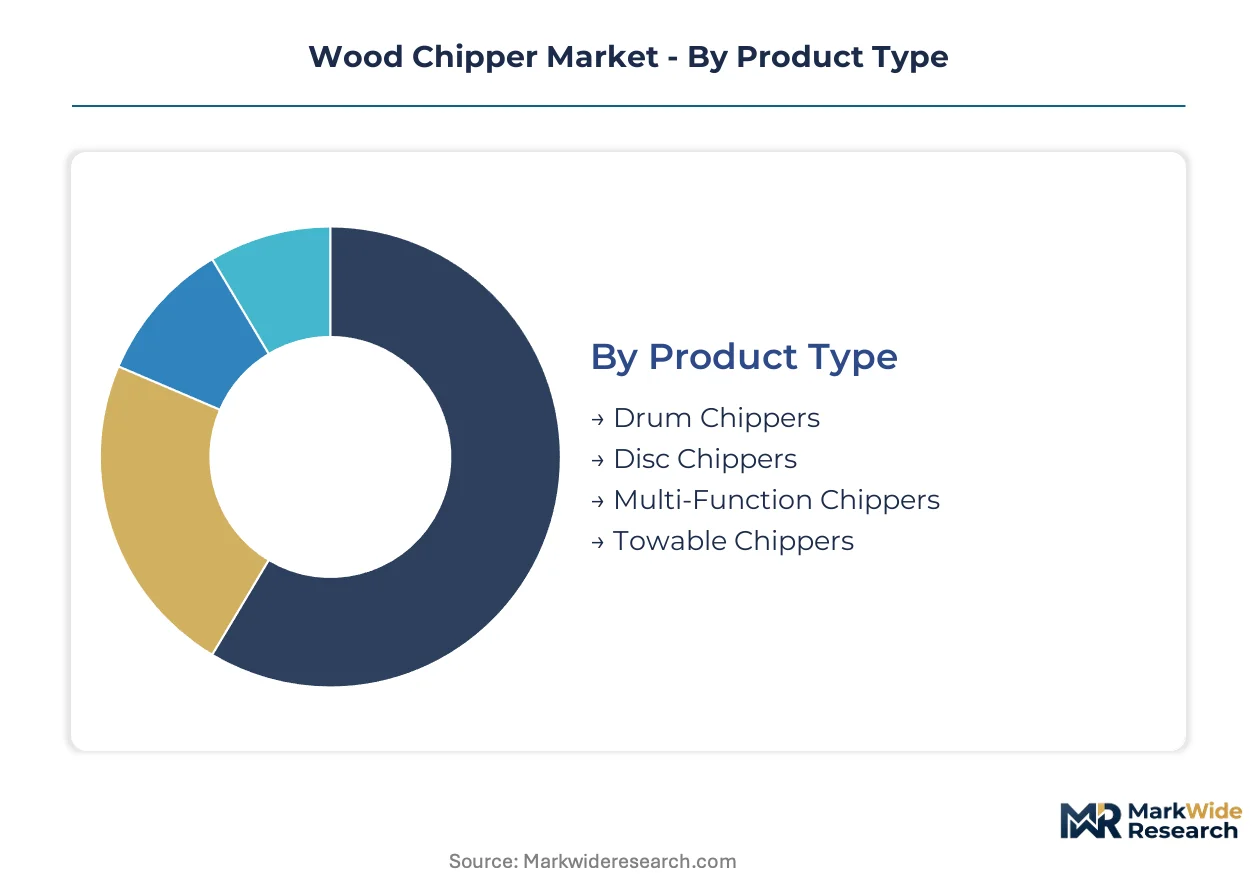
Wood chipper segmentation reveals divergent equipment economics across powertrain technologies and duty cycles. Buyers face fundamentally different capital requirements, operating constraints, and regulatory exposures depending on which configuration they deploy.
Product Type:
Drum chippers demand the heaviest upfront capital outlay due to precision-machined cutting cylinders and high-torque drive systems.
- Drum Chippers:Rotating steel drums fitted with hardened knives deliver high feed rates and consistent chip geometry for pulp mill specifications. Demand concentrates in Oregon and Washington logging residue recovery operations where chip uniformity commands premium pricing from pulp processors.
- Disc Chippers:Flywheel-mounted disc configurations excel at processing hardwoods with specialized knife geometries. Professional arborists in suburban North America favor these units for urban tree removal contracts requiring maneuverability and rapid blade changes.
- Multi-Function Chippers:Modular cutting heads switch between drum and disc modes for diversified debris streams.
- Towable Chippers:Highway-legal chassis designs enable rapid site-to-site relocation for municipal fleet operators.
Drum chippers absorb the bulk of installed capacity; multi-function configurations are expanding most quickly as fleet operators seek operational flexibility.
Power Source:
Diesel configurations still anchor margin pools for manufacturers serving remote operations beyond electrical grid access.
- Electric:Battery-powered systems eliminate idle fuel consumption and satisfy municipal noise abatement ordinances. Landscaping contractors in California municipalities are accelerating procurement timelines as charging infrastructure converges with equipment logistics.
- Diesel:Compression-ignition engines maintain dominance in Pacific Northwest logging operations where runtime demands exceed current lithium-ion energy density limits.
- Gasoline:Spark-ignition units serve residential and light commercial applications with lower duty cycles.
- Hybrid:Dual-power systems combine diesel range with electric zero-emission zones for urban contracts with strict environmental clauses.
Diesel retains the largest installed base; electric powertrains are gaining share fastest among municipal and landscaping fleet renewals.
End User:
Forestry operations require the most ruggedized equipment specifications and absorb the longest replacement cycles.
- Landscaping:Seasonal demand volatility drives preference for equipment-as-a-service contracts bundling maintenance and blade logistics.
- Forestry:Pulp mill chip geometry specifications demand hardened steel knife systems and precision feed controls.
- Waste Management:Municipal composting facilities process mixed vegetative debris with less stringent chip uniformity requirements.
- Construction:Site clearance operations value throughput speed over chip quality for biomass disposal.
Forestry applications dominate capital deployment; landscaping represents the steepest expansion trajectory as suburban fleet electrification accelerates.
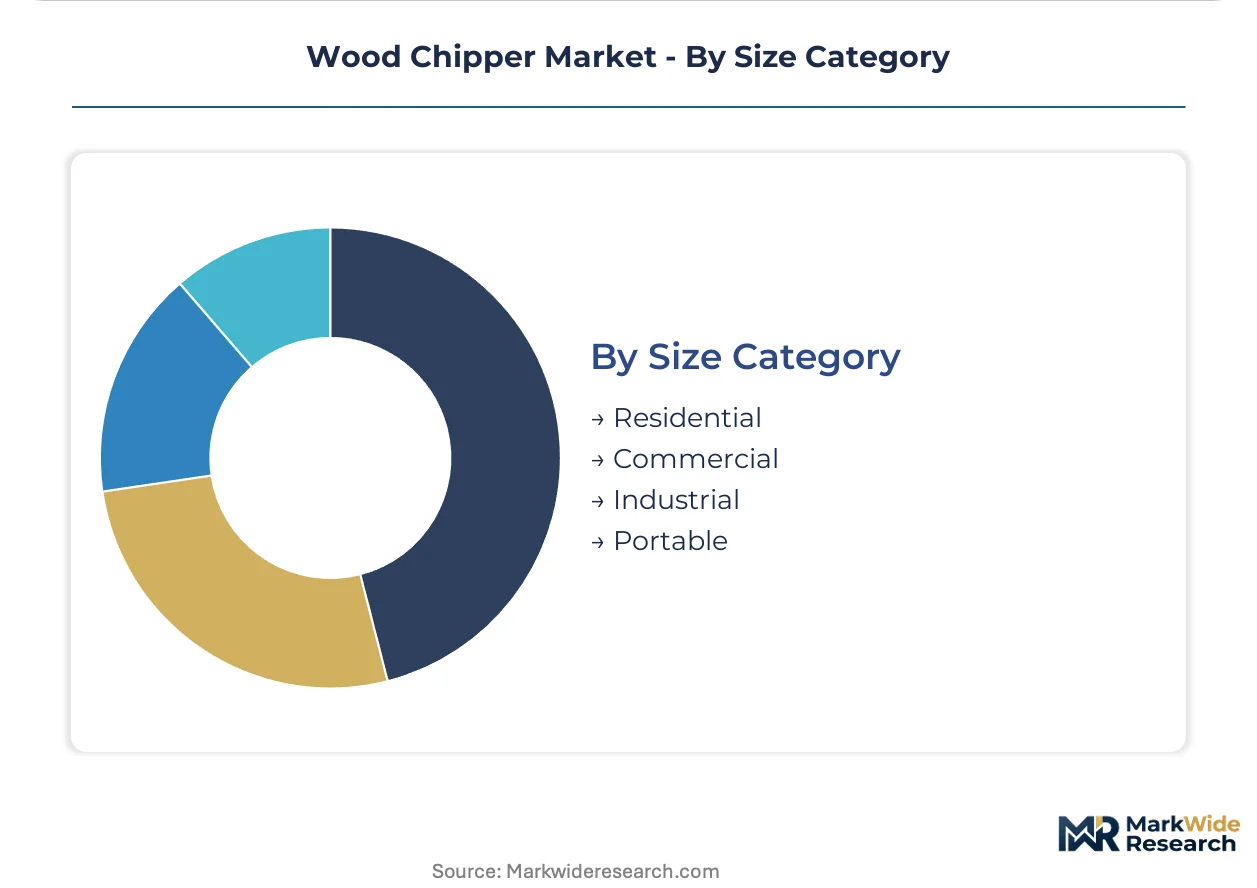
Size Category:
Industrial units carry the highest per-unit revenue and longest production lead times due to custom engineering requirements.
- Residential:Compact electric and gasoline units serve homeowner property maintenance with limited debris volumes.
- Commercial:Mid-duty configurations balance mobility with throughput for independent landscaping contractors.
- Industrial:Stationary drum systems process whole-tree logging residue at mill-yard scales with automated feed systems.
- Portable:Self-propelled or towable designs enable rapid deployment across dispersed job sites without fixed infrastructure.
Industrial equipment commands the largest revenue share; portable configurations are climbing the fastest as distributed biomass recovery expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest logging residue anchors North American wood chipper demand, while European biomass recovery and Asian urban greening programs reshape procurement patterns across distinct regulatory environments.
United States
Oregon and Washington pulp mills tighten chip geometry specifications for logging residue contracts. EPA Tier 4 Final standards force diesel engine redesigns toward hybrid configurations. Seattle municipal fleets pilot electric drum chippers for urban tree removal services with strict noise abatement clauses.
Germany
Baden-Württemberg forestry cooperatives invest in precision drum systems for hardwood processing. EU Machinery Directive CE marking governs export eligibility for equipment destined for landscaping contractors. Bavarian equipment fabricators specialize in modular undercarriage platforms enabling rapid reconfiguration.
China
Yangtze River Delta biomass power plants source uniform chips from urban green waste streams. MIIT industrial standards shape domestic equipment certification timelines for municipal fleet operators. Shandong Peninsula manufacturers concentrate on towable disc configurations for distributed job sites.
Canada
British Columbia logging operations demand hardened steel knife systems for western red cedar processing. Health Canada workplace safety regulations align with OSHA machine guarding requirements for cross-border equipment sales. Ontario landscaping contractors accelerate electric procurement as charging infrastructure converges with urban service routes.
Sweden
Stockholm district heating networks source forest residue chips with strict moisture content specifications. EU Green Deal carbon accounting drives municipal zero-emission mandates for urban vegetation management. Västerbotten equipment specialists integrate smart feed control systems for automated pulp mill integration.
Wood Chipper Market Competitive Landscape
Global majors compete with regional champions across powertrain technology and after-sales service density. The vendor base stratifies into three tiers: integrated forestry equipment conglomerates with captive engine packaging capabilities, specialized drum and disc fabricators with hardened steel metallurgy expertise, and emerging electric powertrain entrants leveraging battery swap logistics. Consolidation pressure concentrates among mid-scale towable specialists lacking vertical integration into undercarriage systems. Strategic moves center on hybrid-electric platform licensing and mobile charging infrastructure partnerships.
Among North American forestry equipment specialists, Morbark LLC and Vermeer Corporation exemplify divergent vertical integration strategies. Bandit Industries Inc. occupies a position within the specialized disc-chipper tier, representing the hardwood-focused archetype prevalent among professional arborist suppliers. European precision engineering traditions surface through UNTHA shredding technology GmbH, a German limited liability company anchoring the industrial shredding segment. Terex Corporation and Astec Industries Inc. demonstrate the conglomerate model, spanning multiple equipment categories beyond dedicated wood reduction systems.
| Leading Market Players |
|---|
| Astec Industries Inc. |
| Morbark LLC |
| Vermeer Corporation |
| Husqvarna AB |
| UNTHA shredding technology GmbH |
| Bandit Industries Inc. |
| Terex Corporation |
| Makita Corporation |
| Bruks Siwertell Group |
| Others |
Value Network & Pricing Analysis
Precision knife alignment technicians concentrated in the Pacific Northwest command wage premiums that widen spreads between premium-tier drum systems and economy disc configurations. Labor scarcity for hydraulic feed system specialists in Oregon and Washington inflates after-service costs for industrial buyers while suburban landscaping contractors absorb tighter margins on entry-level towable units.
Pricing Analysis
Warranty bundling separates premium drum chipper suppliers from unbundled economy disc vendors, with Morbark and Vermeer wrapping multi-year service contracts into capital outlays while Bandit and regional fabricators price equipment-only for price-sensitive arborists. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and knife metallurgy quality, with EPA Tier 4 Final compliance adding base cost to diesel configurations. Cost compression in the standard tier intensifies because hybrid-electric R&D absorbs engineering bandwidth without immediate volume recovery. Municipal fleet operators show least price sensitivity given equipment-as-a-service adoption, while independent landscaping contractors negotiate hardest on upfront capital.
Supply Chain Analysis
Freight cost volatility from Great Lakes metallurgical suppliers to Pacific Northwest assembly plants compresses margins on hardened steel knife blanks, with rail and flatbed trucking rates fluctuating seasonally around logging residue harvest cycles. Manufacturing concentrates in the United States, Germany, and China, with Baden-Württemberg fabricators supplying modular undercarriage platforms and Shandong Peninsula producers dominating towable disc exports. Production draws from specialized alloy suppliers in the Great Lakes corridor, hydraulic component manufacturers in Germany, and battery cell producers in South Korea. Single-source vulnerability sits with Great Lakes knife blank suppliers given limited alternative hardening capacity. Distribution runs through OEM direct sales for industrial drum systems and regional equipment dealers for landscaping towables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around powertrain electrification investments that smaller towable specialists cannot fund, with EPA Tier 4 Final recertification cycles forcing sub-scale fabricators toward acquisition or exit.
For Market Incumbents: To counter emerging electric powertrain entrants from battery logistics specialists, Morbark and Vermeer should deepen backward integration into battery pack assembly and captive charging trailer production. Incumbents must also secure exclusive municipal fleet partnerships in California and Washington before first-mover advantages harden.
For New Entrants and Emerging Players: EPA Tier 4 Final in the United States opens a window for battery-swap logistics specialists to enter through equipment-as-a-service contracts bundling maintenance and energy supply. White space concentrates in California suburban landscaping fleets seeking noise-compliant hand-fed disc configurations. New entrants should anchor go-to-market through municipal charging infrastructure partnerships rather than dealer networks.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-electric platform licensors given EPA compliance cost compression and municipal zero-emission mandates. Long-term viability favors specialists with captive metallurgy relationships and modular undercarriage IP. The signal to watch is battery energy density improvements crossing the threshold for remote logging runtime without grid access.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Platform Development | Unifies high-torque cutting with zero-emission zones for California municipal contracts. |
| Mobile Charging Infrastructure Partnership | Pairs DC fast-charging trailers with electric chipper deployments for dispersed job sites. |
| Modular Undercarriage Standardization | Enables rapid reconfiguration between drum and disc systems without full unit replacement. |
| Equipment-as-a-Service Contract Expansion | Bundles maintenance, blade sharpening, and battery swaps into predictable operating expenses. |
| Hardened Steel Metallurgy Investment | Secures captive supply of precision knife blanks from Great Lakes alloy suppliers. |
Research Methodology
Independent corroboration across primary interviews with forestry equipment procurement managers, municipal fleet operators, and aftermarket service technicians underwrites the qualitative findings in this analysis. Secondary validation draws from EPA certification filings, OSHA machine guarding guidance documents, and trade customs data for hardened steel alloy imports. Bottom-up equipment shipment tallies from drum and disc manufacturers triangulate against top-down pulp mill chip demand estimates across Oregon and Washington.
Comparable-period anchoring to historical replacement cycles and seasonal demand volatility patterns shaped the projection framework across the analysis window. Segmentation modeling spans product type, power source, end-use application, and size category, with additional granularity on municipal versus commercial buyer archetypes. CAGRs derive from regression analysis of equipment-as-a-service adoption curves and battery energy density improvement trajectories. Forecast inputs include EPA Tier 4 Final compliance timelines and charging infrastructure rollout schedules in California municipalities.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric powertrain penetration in remote logging applications. Forecasts reflect assumptions about lithium-ion cost curves and municipal procurement acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Conveyor Scales Market