
 Earthmover Market | 2026-2036
Earthmover Market Size, Share, and Industry Trends Forecast 2026-2036
Earthmover Market Analytics
Operator shortages across North America and Western Europe are unwinding traditional fleet deployment models. Caterpillar leverages its dealer network and telematics platform to sustain equipment uptime commitments for mining clients. Komatsu anchors its position through autonomous haulage systems that reduce labor dependency in Australian iron ore pits. Volvo Group differentiates via electric compact excavators targeting European urban construction where emission zones tighten.
Earthmovers comprise heavy mobile equipment designed to displace, transport, and grade soil, rock, and aggregate materials using hydraulic actuation systems typically generating breakout forces exceeding 150 kN. Their primary purpose centers on site preparation, mineral extraction, and civil engineering where material volume throughput determines project economics. Excavators dominate revenue contribution due to versatility across trenching, demolition, and material handling applications. Electric technology represents the fastest-expanding segment as battery energy density improvements enable 8-hour duty cycles in municipal construction. Diesel technology retains margin concentration in mining-scale bulldozers and extra-large loaders where power-to-weight ratios remain critical.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe mandate particulate matter and nitrogen oxide reductions, forcing engine architecture changes and after-treatment system adoption. China's MEE enforces National VI emissions benchmarks that restrict non-compliant equipment registration in Beijing, Shanghai, and Guangzhou metropolitan zones. India's CEA power-project clearance requirements and BIS construction equipment safety standards shape procurement specifications for domestic infrastructure tenders. Stakeholders must monitor battery-swapping infrastructure deployment rates and autonomous regulatory frameworks to calibrate R&D allocation between electrification and automation pathways.
Market Dynamics
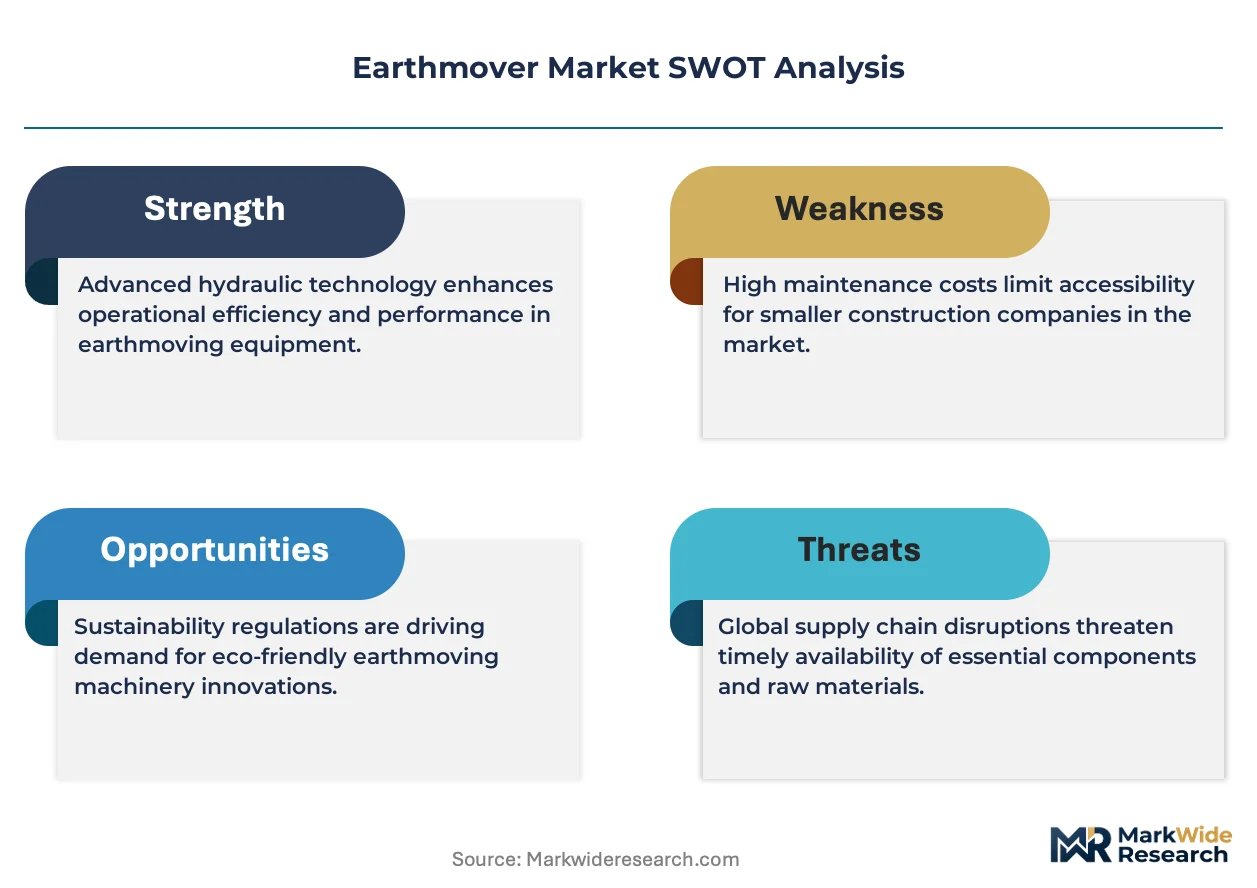
EPA Tier 4 Final and EU Stage V emissions mandates are compressing diesel engine architectures while battery-swapping infrastructure and autonomous haulage systems rewrite fleet economics across mining and construction verticals.
Growth Catalysts
- Battery energy density improvements:Lithium-ion cell chemistry advances now enable 8-hour duty cycles in municipal construction applications, displacing diesel compact excavators in European urban emission zones.
- Australian and Chilean mining expansion:Copper and lithium output targets are forcing fleet scale-ups in Western Australia and Chile's Atacama salt flats, concentrating demand for ultra-class haul trucks and hydraulic shovels.
- China's western infrastructure buildout:Energy and transportation projects across Sichuan, Xinjiang, and Yunnan provinces are absorbing crawler dozers and motor graders at volumes unmatched since the 2015 Belt and Road acceleration.
Market Restraints
- High-voltage battery supply concentration:Cathode active material refining clusters in China's Hunan and Fujian provinces create geopolitical exposure for European and North American OEMs dependent on nickel-manganese-cobalt cell supply.
- After-treatment system complexity:Diesel particulate filters and selective catalytic reduction hardware add maintenance burden and cold-start reliability issues in Siberian and Alaskan mining operations.
- Autonomous retrofit incompatibility:Legacy hydraulic architectures in 10-15 year old mining fleets lack the sensor integration points and CAN bus bandwidth required for retrofit autonomy kits.
Strategic Opportunities
- India's National Infrastructure Pipeline:CEA power-project clearances and BIS construction equipment safety standards are creating a procurement specification window for mid-size hydraulic excavators in road and rail tenders.
- Telematics-enabled uptime contracts:Sensor fusion on engine, hydraulic, and undercarriage systems allows OEMs to unbundle maintenance from capital sale, capturing recurring revenue from risk-averse mining contractors.
- Battery-swapping standardization:Interoperable pack formats across compact loader and mini-excavator segments could unlock shared infrastructure models in Japanese and South Korean urban construction clusters.
Industry Challenges
- Autonomous systems integration:Mining contractors face 18-24 month workforce retraining timelines to redeploy operators into remote supervisor roles, compressing realized productivity gains from haul truck automation.
- Emissions certification lag:EPA and EU type-approval cycles for novel diesel-electric hybrid architectures now extend 8-14 months, delaying product launches past seasonal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthmover Market |
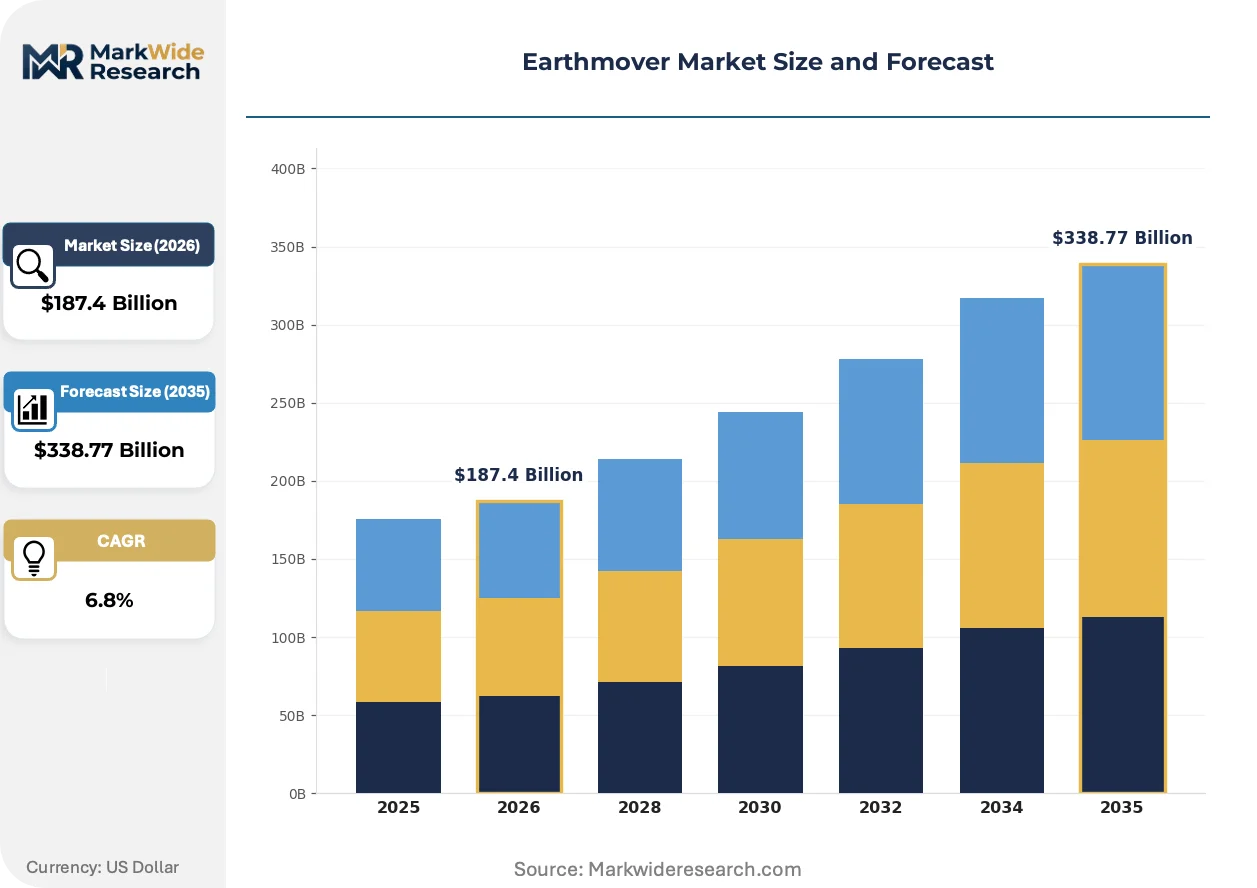
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Bulldozers, Graders Technology: Hydraulic, Electric, Diesel, Autonomous End User: Construction, Mining, Agriculture, Highway Maintenance Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Caterpillar, Komatsu, Volvo Group, Liebherr Group, Hitachi Construction Machinery, SANY Group, XCMG Group, Hyundai Heavy Industries, JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthmover Market Evolving Landscape
Electrification and automation are diverging the product roadmap: battery-electric machines capture urban construction while diesel-electric hybrids and full autonomy dominate mining scale applications.
Modular battery pack architectures are fragmenting equipment design conventions. Standardized cell modules allow OEMs to scale energy capacity across excavator weight classes without redesigning chassis structures. Municipal contractors in German and French metropolitan zones are specifying swappable-pack machines to eliminate midday charging downtime. This standardization is fragmenting traditional powertrain supplier relationships as battery system integrators capture value previously held by engine manufacturers.
EU Stage V and EPA Tier 4 Final regulations are forcing exhaust after-treatment miniaturization. Compact selective catalytic reduction units and diesel oxidation catalysts now fit within 15-tonne excavator engine compartments previously reserved for bare engines. Construction equipment distributors in California and New York are prioritizing certified machines to maintain eligibility for state infrastructure grants tied to air quality compliance.
Telematics-driven procurement is compressing traditional sales cycles. Mining contractors now specify guaranteed availability metrics rather than capital expenditure limits, shifting risk to OEMs and dealers. Komatsu's KOMTRAX and Caterpillar's VisionLink platforms enable this outcome-based contracting model. Australian iron ore operators are leading this transition, with European quarrying contractors piloting similar structures for mid-size wheel loader fleets.
Earthmover Market Segmentation
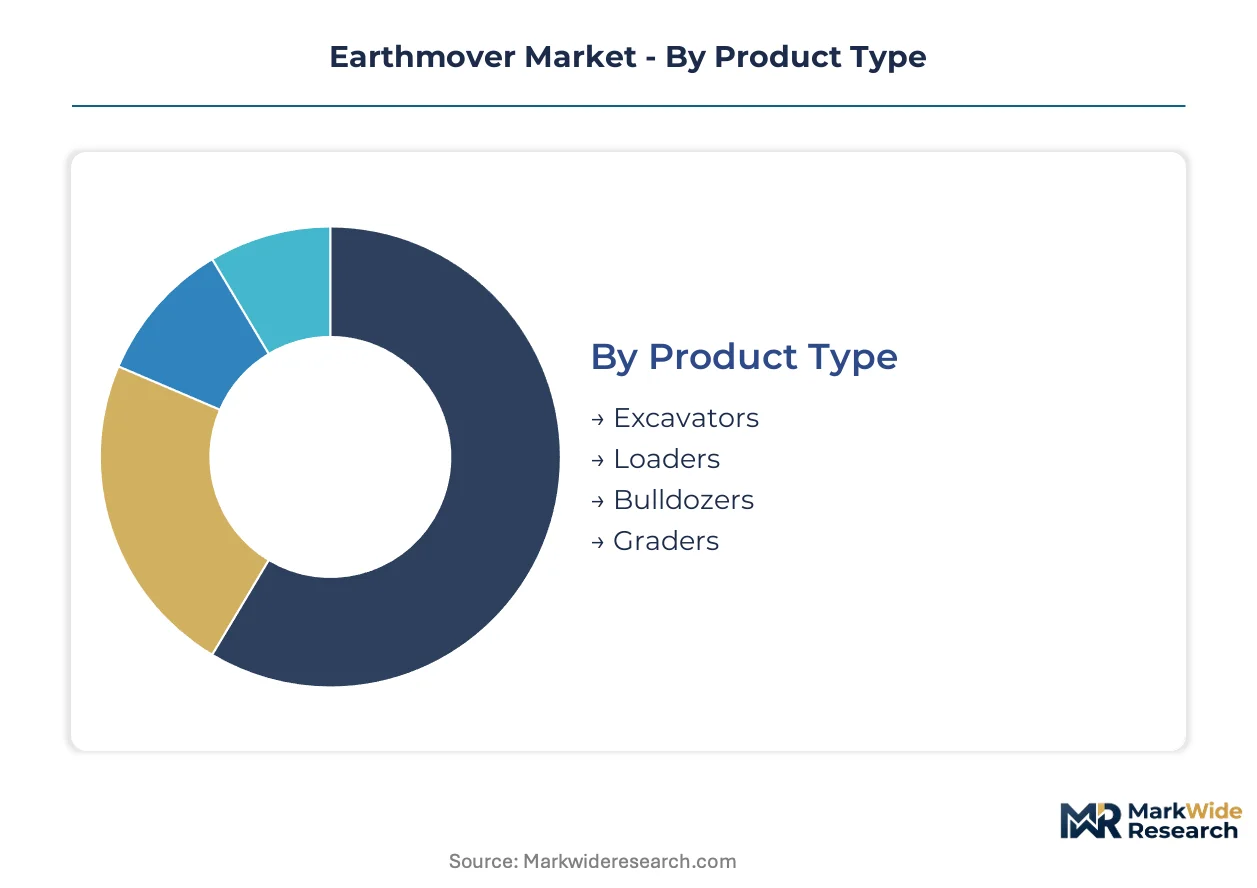
Earthmover procurement patterns diverge sharply across application contexts, with mining contractors prioritizing uptime guarantees and municipal buyers emphasizing emission compliance. Equipment specification cascades from duty cycle intensity through to powertrain architecture selection.
Product Type:
Domestic fleet replacement dominates North American and European excavator demand, while Australian and Chilean mining exports drive ultra-class loader and dozer procurement.
- Excavators:Hydraulic boom and arm configurations deliver breakout forces exceeding 150 kN for trenching, demolition, and material handling. Demand clusters in China's western provinces where infrastructure projects require versatile earthmoving capacity alongside German urban emission zones specifying electric compact variants.
- Loaders:Articulated chassis designs with bucket capacities ranging 3-20 cubic meters handle aggregate stockpiling and truck loading. Australian iron ore operators and Chilean lithium brine extractors anchor the ultra-class wheel loader segment for high-volume material movement.
- Bulldozers:Tracked undercarriage systems with blade widths exceeding 5 meters grade surfaces and displace overburden in mining strips.
- Graders:Articulated frames with moldboard precision control finish road surfaces and maintain haul road profiles in open-pit operations.
Excavators command the established base. The steepest expansion runs through electric compact variants in European municipal construction.
Technology:
Cost tier separation is pronounced: premium autonomous and electric systems capture mining and urban emission zones, while standard hydraulic and diesel architectures serve price-sensitive general construction.
- Hydraulic:Open-center and load-sensing hydraulic circuits transmit power through variable displacement pumps and piston motors. This architecture retains dominance in mid-size construction equipment across India's National Infrastructure Pipeline road tenders.
- Electric:Battery-electric powertrains with lithium-ion packs enable 8-hour duty cycles without midday charging through swappable pack designs. Municipal contractors in Paris, Berlin, and London metropolitan zones specify these machines to maintain eligibility for state infrastructure grants tied to EU Stage V compliance.
- Diesel:Compression-ignition engines with EPA Tier 4 Final after-treatment systems retain margin concentration in extra-large mining equipment where power-to-weight ratios remain critical.
- Autonomous:Sensor fusion platforms with LiDAR, radar, and GPS guidance enable haul truck operation without onboard operators. Australian iron ore pits in Western Australia's Pilbara region anchor deployment volumes for Komatsu and Caterpillar autonomous haulage systems.
Diesel technology holds the installed base. The steepest expansion trajectory belongs to autonomous systems in Australian mining.
End User:
Application intensity determines specification: mining demands 24/7 durability ratings, while agriculture accepts lower duty cycles for seasonal use.
- Construction:General building and civil engineering contractors specify mid-size hydraulic excavators and wheel loaders for site preparation and material handling. Demand concentrates in China's Sichuan and Yunnan provinces where energy and transportation projects absorb crawler dozers and motor graders.
- Mining:Surface and underground extractive operations require ultra-class haul trucks, hydraulic shovels, and dozers with million-hour frame life ratings. Western Australian iron ore and Chilean Atacama lithium operations anchor fleet expansion for copper and lithium output targets.
- Agriculture:Land clearing, drainage installation, and feedlot maintenance drive seasonal demand for compact loaders and small excavators.
- Highway Maintenance:State and provincial road agencies specify motor graders and compact loaders for snow removal, shoulder grading, and ditch maintenance.
Construction commands the established base. The steepest expansion runs through mining as Australian and Chilean operators scale fleets.
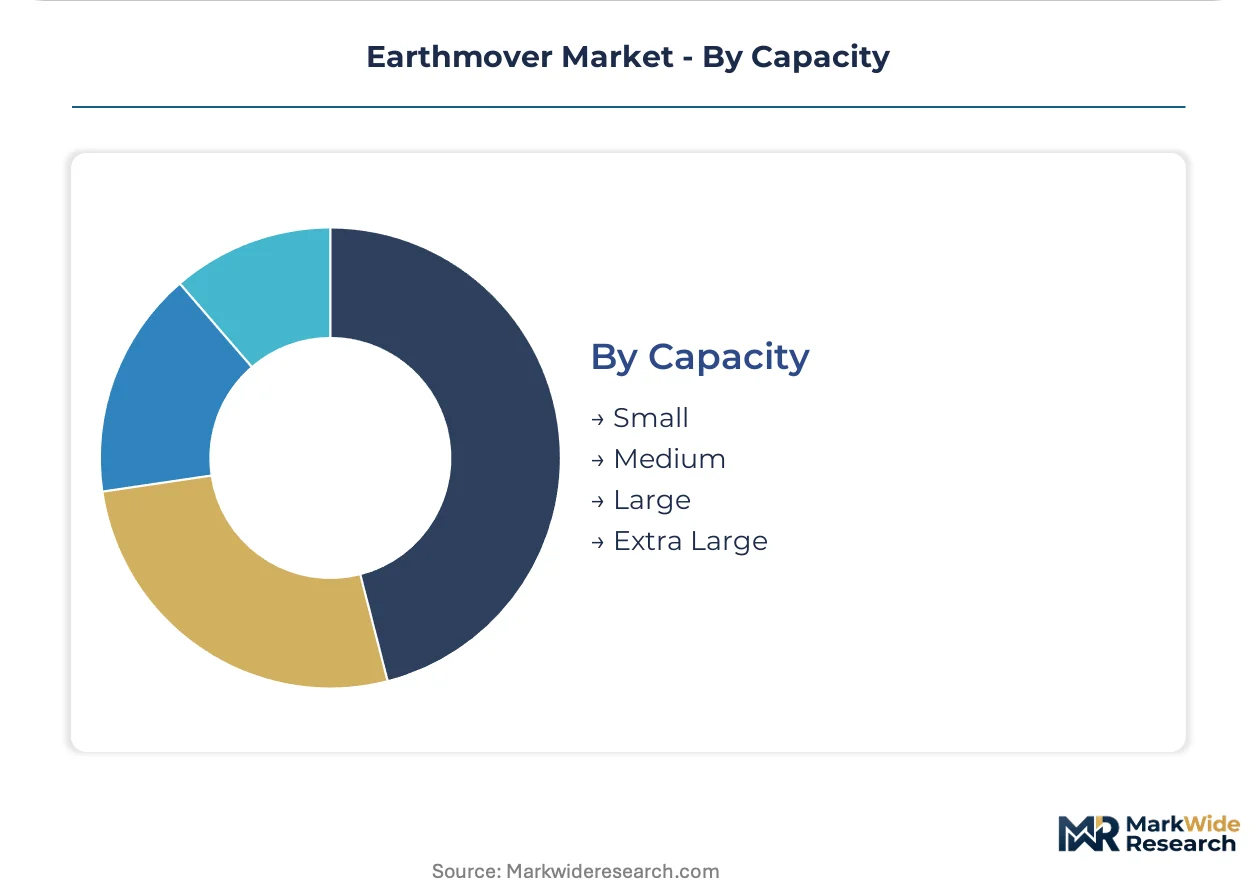
Capacity:
Volume concentration sits with large and extra-large classes in mining, while small and medium units dominate unit sales in general construction.
- Small:Operating weights below 6 tonnes serve residential construction, utility trenching, and landscaping with trailer-transportable dimensions.
- Medium:6-20 tonne operating weights balance mobility and productivity for road building, commercial construction, and quarry operations. Indian road and rail tenders through the National Infrastructure Pipeline specify this class for mid-size hydraulic excavator procurement.
- Large:20-100 tonne machines handle bulk earthmoving and mining support functions with dedicated transport requirements.
- Extra Large:Operating weights exceeding 100 tonnes include ultra-class haul trucks and hydraulic shovels purpose-built for open-pit mining. Western Australian iron ore operators and Chilean copper mines specify these units for million-tonne-per-day material movement.
Medium capacity commands the established base. The steepest expansion runs through extra-large units in Australian and Chilean mining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final standards anchor the United States as the regulatory benchmark setter, with emissions compliance costs reshaping procurement patterns across mining and construction verticals worldwide.
United States
Surface mining operations in Wyoming's Powder River Basin and Arizona's copper belt are replacing aging haul truck fleets to meet productivity targets. EPA Tier 4 Final particulate matter limits are forcing after-treatment retrofits on equipment registered in California and New York non-attainment zones. Houston and Dallas-Fort Worth construction clusters are absorbing medium excavators for petrochemical infrastructure expansion.
China
Western provincial infrastructure buildouts across Sichuan, Xinjiang, and Yunnan are driving crawler dozer and motor grader absorption at volumes unmatched since 2015. MEE National VI emissions benchmarks restrict non-compliant equipment registration in Beijing, Shanghai, and Guangzhou metropolitan zones. Hunan and Fujian province cathode refining clusters concentrate battery supply chain exposure for domestic OEMs.
Australia
Western Australia's Pilbara iron ore operators are scaling ultra-class haul truck and hydraulic shovel fleets to meet export volume commitments. State environmental clearance requirements for new mine approvals are accelerating autonomous haulage system adoption. Perth-based mining contractors are piloting telematics-enabled uptime contracts that shift maintenance risk to equipment suppliers.
Germany
Berlin, Munich, and Hamburg municipal contractors are specifying electric compact excavators to maintain eligibility for federal infrastructure grants tied to EU Stage V compliance. EU Green Deal construction sector decarbonization targets are compressing diesel equipment residual values in urban emission zones. Bavarian and Baden-Württemberg manufacturing clusters are developing modular battery pack architectures for municipal construction applications.
India
National Infrastructure Pipeline road and rail tenders are specifying mid-size hydraulic excavators for contractors seeking CEA power-project clearances. BIS construction equipment safety standards are shaping procurement specifications for domestic infrastructure awards. Maharashtra and Gujarat state highway departments are absorbing motor graders for corridor development projects.
Earthmover Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the earthmover market, with consolidated players controlling autonomous haulage and electric powertrain development while fragmented regional fabricators compete on price-sensitive construction segments. Three archetypes dominate: full-line mining specialists with autonomy platforms, urban electric equipment developers, and scale-driven emerging market suppliers. Competitive moves center on telematics-enabled service contracts and battery-swapping infrastructure partnerships.
Among integrated mining equipment developers, Caterpillar and Komatsu exemplify the full-line autonomy tier, with both occupying positions in Australian iron ore haulage system deployment. Volvo Group represents the urban electrification archetype, anchoring electric compact equipment development for European emission zones. SANY Group sits within the scale-driven emerging market tier, with Chinese manufacturing base positioning for domestic and export volume expansion.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Volvo Group |
| Liebherr Group |
| Hitachi Construction Machinery |
| SANY Group |
| XCMG Group |
| Hyundai Heavy Industries |
| JCB |
| Others |
Value Network & Pricing Analysis
Ninety-day cathode active material inventory cycles in Hunan and Fujian provinces translate directly into battery pack cost volatility for European and North American OEMs, compressing margin buffers on electric compact equipment while amplifying pricing power for domestic Chinese manufacturers with captive refining access.
Pricing Analysis
Australian iron ore operators pay 15-25% premiums over European municipal contractors for identical ultra-class haul truck platforms, reflecting uptime guarantee bundling and autonomous retrofit compatibility rather than hardware differentiation alone. Three-tier pricing structure across premium autonomous, standard diesel-electric hybrid, and economy hydraulic architectures separates mining contractors from urban emission-zone buyers. Cost compression in standard hydraulic tiers is intensifying because Indian National Infrastructure Pipeline tenders prioritize capital expenditure minimization over lifecycle operating cost. Municipal contractors in German metropolitan zones exhibit lowest price sensitivity due to federal grant eligibility requirements tied to EU Stage V compliance.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell manufacturing, with cathode active material refining clustering in Hunan's Xiangtan and Fujian's Ningde industrial corridors. Battery-electric powertrains draw from nickel-manganese-cobalt chemistries, high-voltage inverters, and thermal management systems sourced across East Asian supplier networks. Single-source vulnerability concentrates in rare earth permanent magnet supply for electric drive motors, with processing capacity tethered to Chinese state-owned refiners. Distribution runs through OEM captive dealer networks in mining verticals and independent equipment distributors serving price-sensitive construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Earthmover electrification sits at early-cycle expansion, with battery energy density improvements enabling 8-hour duty cycles that displace diesel compact equipment in European urban emission zones.
For Market Incumbents: Shield autonomous haulage system margins by accelerating sensor fusion platform standardization before Komatsu and Caterpillar patent positions harden around Australian iron ore deployment experience. Deepen backward integration into battery pack assembly through modular architecture licensing to regional fabricators, reducing exposure to cathode material cost volatility from Chinese refining clusters. For New Entrants and Emerging Players: Anchor in India's National Infrastructure Pipeline mid-size hydraulic excavator segment, where CEA clearance requirements and BIS safety standards create procurement specification windows underserved by premium autonomous specialists. Target state highway department motor grader tenders in Maharashtra and Gujarat with cost-optimized crawler dozer derivatives, leveraging local component sourcing partnerships to undercut full-line OEM landed costs. For Investors and Strategic Acquirers: Carve-out targets emerge from construction equipment distributors with captive aftermarket service revenue in Australian mining corridors, where telematics-enabled uptime contracts are compressing traditional equipment sales cycles. Long-term viability favors platforms with demonstrated autonomous retrofit kit integration or battery-swapping infrastructure partnerships. Monitor EPA and EU type-approval cycle durations for novel diesel-electric hybrid architectures as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Partnership | Interoperable pack formats unlock shared infrastructure models in Japanese and South Korean urban construction clusters. |
| Telematics-Enabled Uptime Contract | Sensor fusion on engine and hydraulic systems allows OEMs to capture recurring revenue from risk-averse Australian mining contractors. |
| Autonomous Haulage System Deployment | LiDAR and GPS guidance platforms reduce labor dependency in Western Australian iron ore pits facing operator shortages. |
| Modular Battery Pack Architecture | Standardized cell modules allow scaling energy capacity across excavator weight classes without chassis redesign. |
| After-Treatment System Miniaturization | Compact selective catalytic reduction units fit within 15-tonne excavator engine compartments for California and New York compliance. |
Research Methodology
The analysis maps hydraulic, electric, diesel, and autonomous powertrain sub-sectors, each validated through maintenance directors at mining contractors, OEM procurement teams, aftermarket service heads, and plant engineers at aggregate operations. Primary interview findings triangulate against customs and trade data, SEC 10-K equipment segment disclosures, EPA and EU type-approval registries, and mining fleet deployment announcements. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder feedback loops.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions span product type, technology architecture, end-use intensity, and capacity class. CAGRs derive from equipment replacement cycle analysis, mining capital expenditure pipeline tracking, and infrastructure tender award velocity. Battery energy density improvement curves and autonomous regulatory framework development pace inform technology transition timing assumptions.
Decision-makers should treat outputs as directional under stable emissions regulation enforcement and cathode material supply continuity assumptions; material deviation in Chinese export licensing or EPA Tier 5 advancement would warrant model refresh. Recalibration cycles align with material shifts in mining commodity price trajectories and battery-swapping infrastructure deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Global Excavators Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
GCC Crane Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Europe Crane Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Boom Cranes Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market