
 Wireless Telecommunication Services Market | 2026-2036
Wireless Telecommunication Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Telecommunication Services Market Intelligence
The accelerated deployment of 5G infrastructure in countries like South Korea and the United States is recalibrating network capacity and service potential. This shift creates new competitive arenas for major operators. Verizon Communications leads in the deployment of mmWave technology in dense urban US markets. In Europe, Deutsche Telekom leverages its extensive fiber backbone to support its 5G expansion across Germany and other key territories.
Wireless telecommunication services encompass the transmission of voice, data, and video signals between endpoints without physical cabling, utilizing radio waves across licensed spectrum. These services operate on standards defined by bodies like the 3GPP, specifying protocols for technologies from 4G LTE to 5G New Radio. While data services have become the primary revenue driver, the 5G technology segment represents the fastest-growing area of investment. Demand from enterprise end users for dedicated IoT connectivity is also expanding rapidly.
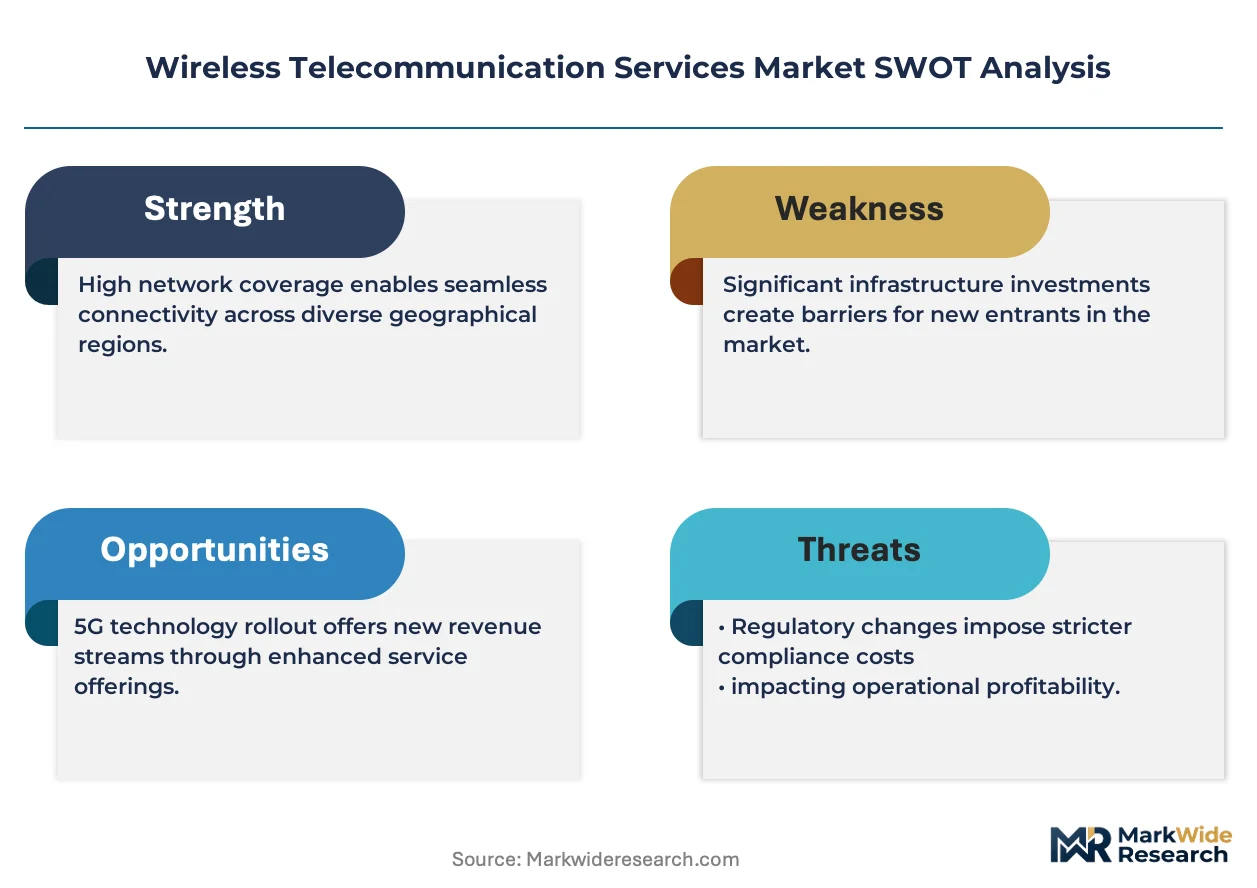
Spectrum allocation and pricing are heavily influenced by national regulators like the FCC in the United States and India's TRAI. Concurrently, data handling and privacy for value-added services fall under frameworks such as the EU's GDPR, impacting how operators manage customer information. The central strategic challenge for carriers involves monetizing massive capital expenditures on next-generation networks while managing the decline of legacy service revenues.
Market Dynamics
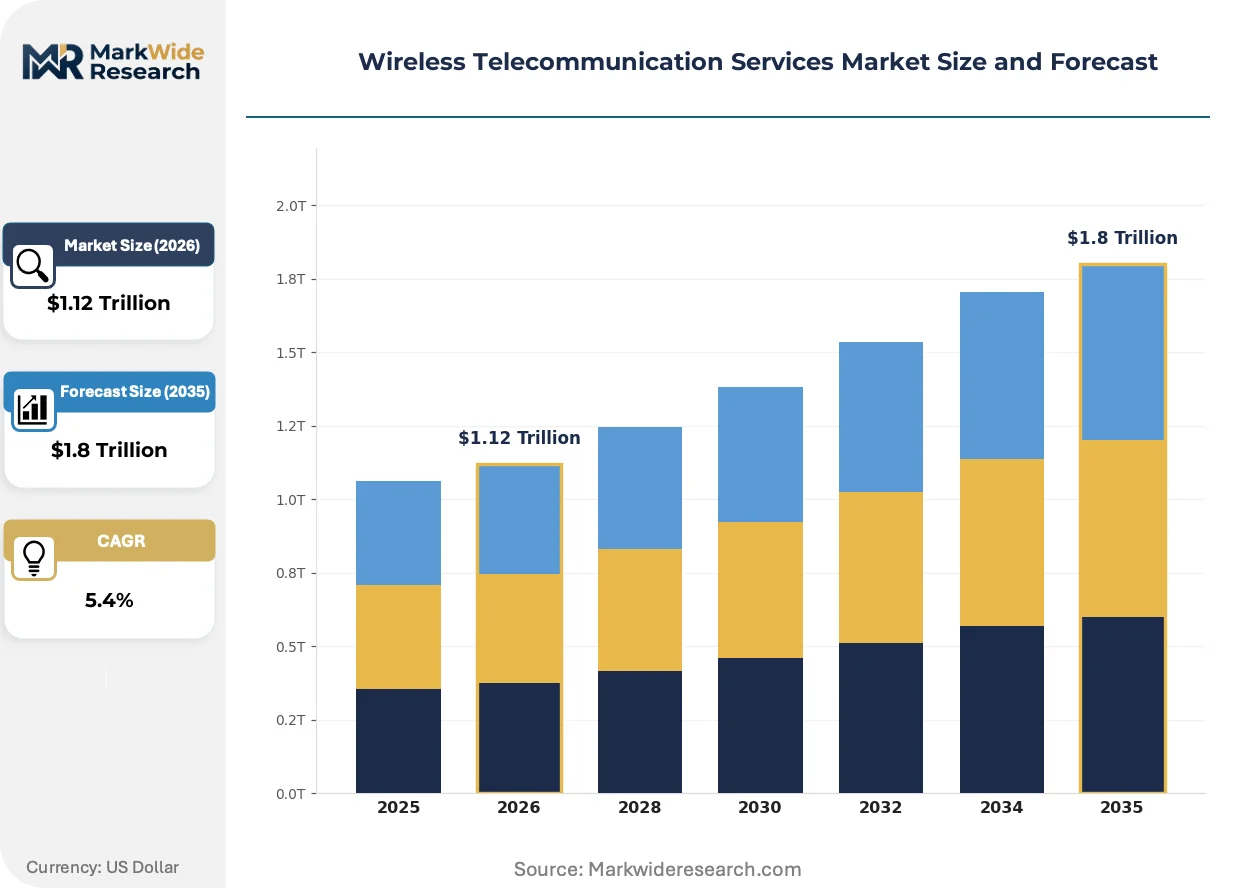
The central structural force shaping the wireless telecommunication services market is the economic tension between the immense capital expenditure required for 5G network deployment and the urgent need for carriers to monetize these investments beyond traditional consumer data plans.
Growth Catalysts
- Enterprise IoT Adoption:The expansion of Internet of Things (IoT) applications within the fleet management and logistics sectors creates significant demand for reliable, wide-area wireless connectivity for real-time asset tracking and monitoring.
- Government Digitalization Programs:National policies, such as India's Digital India initiative, are accelerating smartphone penetration and data consumption, creating a massive and expanding subscriber base for mobile network operators.
- 5G Fixed Wireless Access (FWA):The deployment of 5G technology as a viable alternative to fixed-line broadband in underserved suburban and rural areas provides a new revenue stream for carriers, competing directly with cable and fiber providers.
Market Restraints
- Spectrum Scarcity and Cost:The high cost and limited availability of suitable radio frequency spectrum, allocated through auctions by regulators like the US Federal Communications Commission (FCC), represent a significant financial barrier to entry and expansion.
- High Capital Intensity:Building out dense 5G networks, including small cells and extensive fiber backbones, requires massive, sustained capital investment with long return-on-investment timelines, pressuring operator margins.
- Network Security Threats:The increasing complexity of software-defined networks and the proliferation of connected IoT devices expand the attack surface, demanding constant investment in advanced cybersecurity measures to prevent breaches.
Strategic Opportunities
- Network Slicing for Verticals:Offering dedicated virtual network slices with guaranteed quality of service (QoS) for specific enterprise applications, such as factory automation or connected healthcare, opens up high-margin, value-added service opportunities.
- Private Wireless Networks:Designing and managing private 5G and LTE networks for large enterprises, campuses, and industrial sites provides a new B2B revenue model focused on dedicated performance, security, and control.
- Edge Computing Integration:Partnering with cloud providers to deploy multi-access edge computing (MEC) nodes within the radio access network enables ultra-low-latency applications, creating a new service tier for developers and enterprises.
Industry Challenges
- Technical Skills Gap:A persistent shortage of network engineers and software developers with expertise in cloud-native architectures, network function virtualization (NFV), and automation tools hampers the transition to 5G Standalone (SA) cores.
- Legacy System Integration:The operational complexity of integrating new 5G network functions with legacy billing support systems (BSS) and operational support systems (OSS) can delay service rollouts and increase operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Telecommunication Services Market |
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $1.8 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Data, Messaging, Roaming, Value-Added Services, IoT Connectivity Technology: 4G LTE, 5G, Wi-Fi, Satellite, Bluetooth, NFC Application: Mobile Communication, M2M Communication, Emergency Services, Fleet Management, Smart Cities, Telemetry End User: Individual Subscribers, Enterprises, Public Safety Agencies, Transportation Firms, Educational Institutions, Government Organizations |
| Companies Covered | AT&T, Verizon Communications, China Mobile, Vodafone Group, Deutsche Telekom, T-Mobile US, América Móvil, China Telecommunications Corporation, NTT DOCOMO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Telecommunication Services Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental pivot from providing ubiquitous connectivity to delivering specialized, application-aware network services. This transition leverages software-defined architectures and edge intelligence to create differentiated value for enterprise and industrial end users.
Open Radio Access Network (Open RAN) architecture provides a standardized interface between radio and baseband units. Telecom operators are steadily adopting this approach to diversify their supply chain and avoid single-vendor lock-in. This technology is modularizing the network equipment ecosystem, enabling carriers to integrate best-of-breed components from a wider range of hardware and software suppliers.
Data privacy regulations, exemplified by the EU's General Data Protection Regulation (GDPR), mandate stringent controls over the handling of personal information. This directly impacts how operators can leverage customer data for analytics, advertising, and personalized value-added services. The telecommunications sector, particularly in Europe, must now embed privacy-by-design principles into all new service offerings to ensure compliance.
A notable behavioral shift is occurring in how enterprises procure dedicated network resources, moving away from rigid, long-term contracts. The emerging model involves consumption-based pricing for network-as-a-service (NaaS) offerings, often provisioned through self-service portals and APIs. This trend is most visible within the private 5G and SD-WAN segments in North America, where enterprise IT demands greater agility.
Wireless Telecommunication Services Market Segmentation
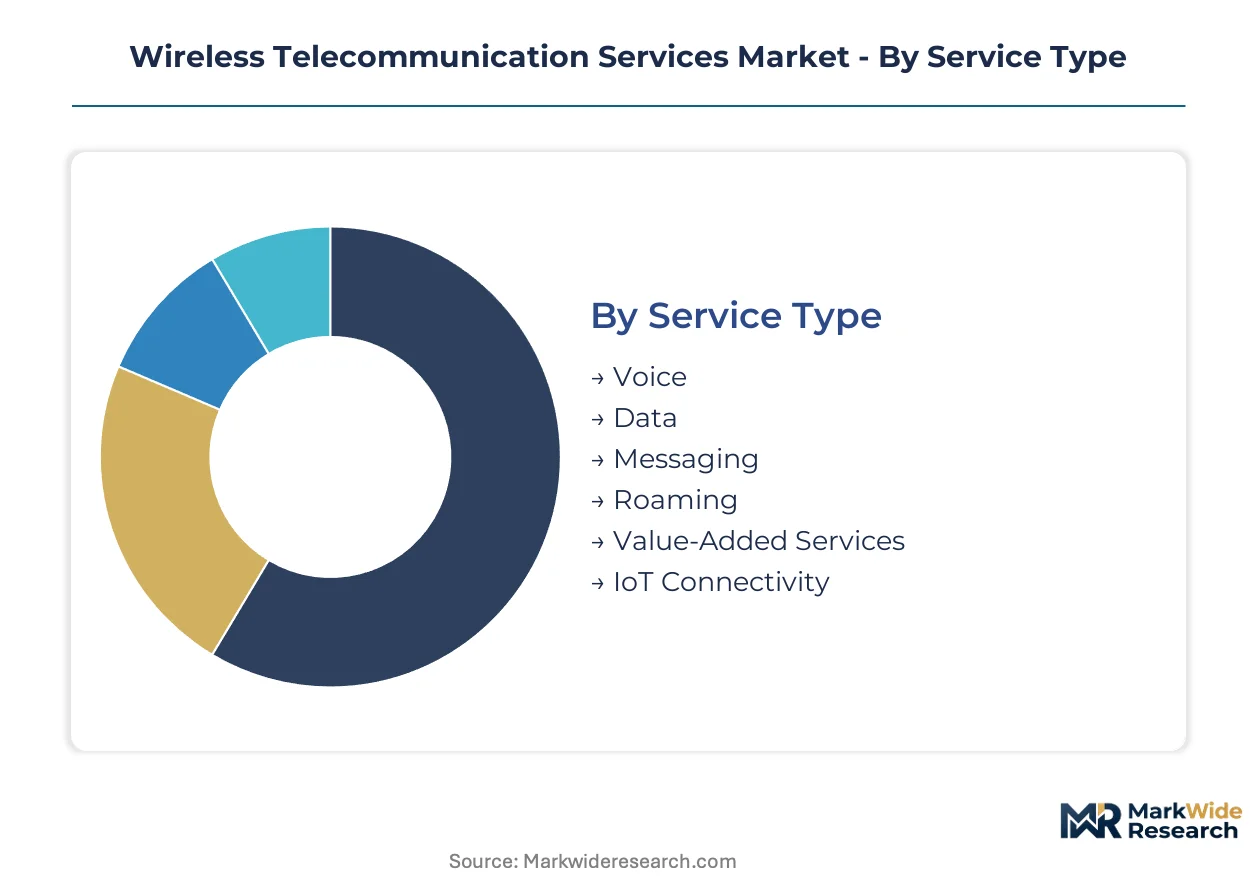
Understanding the granular components of the wireless telecommunication services market is crucial for identifying revenue streams and strategic investment areas. This segmentation highlights the diverse offerings and underlying technologies driving market evolution, from core connectivity to specialized enterprise solutions. Each category reveals distinct demand patterns and operational complexities for carriers.
Service Type:
The range of services offered spans from highly standardized basic communication to increasingly customized, application-specific solutions. This spectrum dictates both pricing flexibility and the required network intelligence for delivery.
- Data:This service type facilitates the transmission of digital information, including internet browsing, streaming media, and application usage, across wireless networks. Demand for data services is concentrating in India, driven by extensive smartphone penetration and government digital initiatives like Digital India.
- IoT Connectivity:Dedicated connectivity solutions enable real-time data exchange between connected devices, sensors, and platforms for various industrial and consumer applications. Enterprise end users, particularly in the fleet management sector, are driving significant demand for reliable, wide-area IoT connectivity.
- Voice:Traditional voice communication services allow users to make and receive calls over wireless networks.
- Messaging:This segment includes SMS and MMS services, providing text and multimedia communication capabilities to subscribers.
- Roaming:Roaming services enable subscribers to use their mobile devices on partner networks when outside their home network coverage area.
- Value-Added Services:These are supplementary services beyond basic voice and data, such as caller ID, voicemail, and content subscriptions.
Most installed capacity flows through Data. Expansion is steepest in IoT Connectivity.
Technology:
The maturity and deployment scale of wireless technologies significantly influence network capabilities and service innovation. Newer generations offer enhanced performance but require substantial capital expenditure for infrastructure upgrades.
- 5G:The fifth generation of cellular technology offers significantly higher speeds, lower latency, and greater capacity, supporting advanced applications like network slicing and edge computing. Accelerated deployment in South Korea and the United States is recalibrating network capacity.
- 4G LTE:Long-Term Evolution (LTE) is a widely adopted standard providing high-speed mobile broadband, forming the backbone for most current mobile data services globally. This technology remains a primary revenue driver for established mobile network operators.
- Wi-Fi:Wireless Fidelity (Wi-Fi) provides local area network connectivity using radio waves, commonly used for internet access in homes and public spaces.
- Satellite:Satellite communication offers wide-area coverage, particularly in remote or underserved regions, for specialized data and voice services.
- Bluetooth:This short-range wireless technology enables device-to-device communication for peripherals and personal area networks.
- NFC:Near Field Communication (NFC) facilitates short-range, high-frequency wireless communication for contactless payments and data exchange.
The 4G LTE segment maintains significant volume, while 5G technology is expanding most quickly.
Application:
Wireless services are tailored to specific functional needs, ranging from ubiquitous personal communication to highly specialized industrial deployments. Each application demands distinct network characteristics like reliability, latency, and security.
- Mobile Communication:This foundational application supports personal voice, data, and messaging services for individual subscribers using smartphones and other portable devices. Ubiquitous smartphone penetration drives consistent demand in this segment.
- Fleet Management:Wireless services enable real-time tracking, monitoring, and management of vehicle fleets, optimizing logistics and operational efficiency for transportation firms. IoT connectivity is a critical enabler for advanced fleet management solutions.
- M2M Communication:Machine-to-Machine communication facilitates direct data exchange between devices without human intervention for automation and remote monitoring.
- Emergency Services:These applications provide critical communication capabilities for public safety agencies, supporting rapid response and coordination during emergencies.
- Smart Cities:Wireless networks support various urban applications, including smart lighting, waste management, and traffic control, to enhance city infrastructure.
- Telemetry:Telemetry involves the remote measurement and transmission of data from various sources, such as utility meters and environmental sensors.
Mobile Communication holds the largest share of service usage. Fleet Management applications are climbing the fastest.
End User:
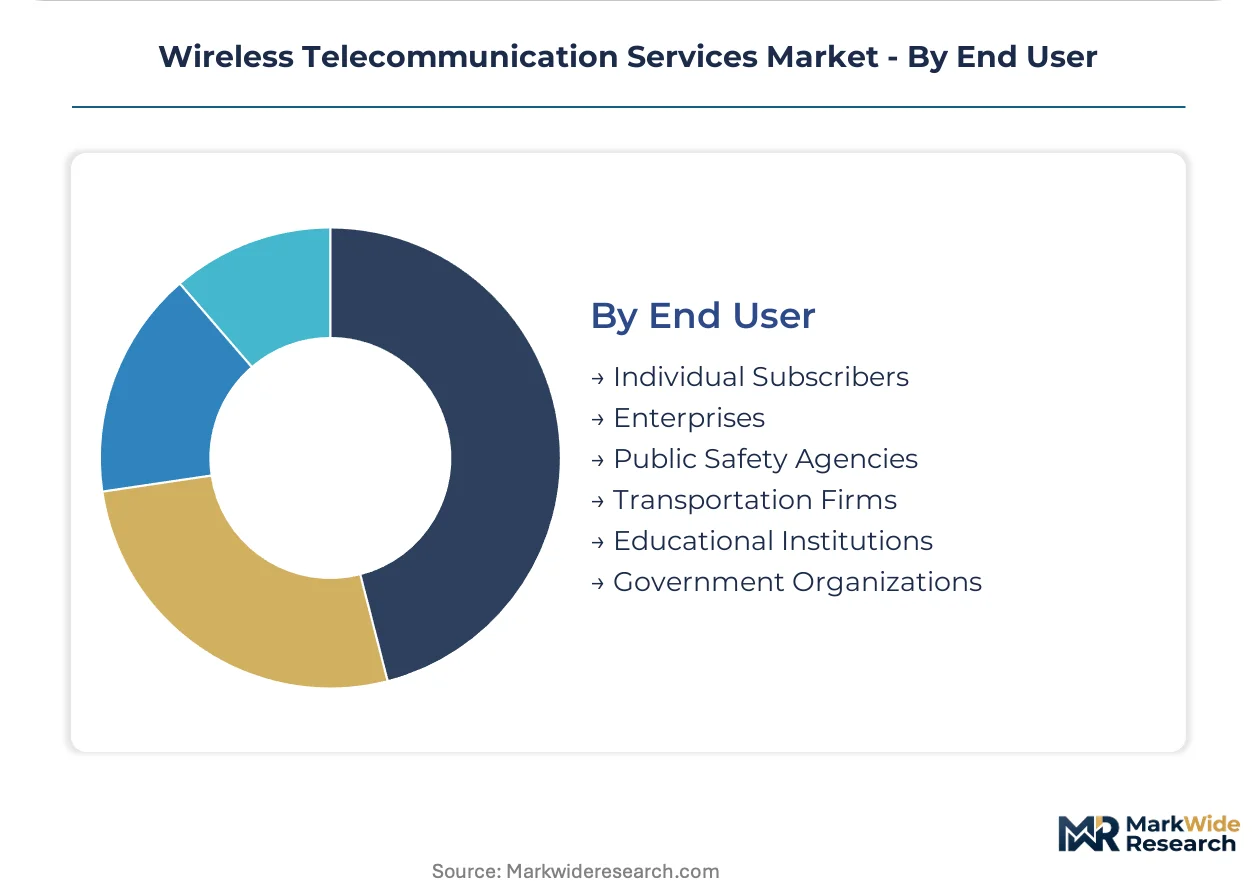
The customer base for wireless telecommunication services is diverse, encompassing individual consumers, large enterprises, and public sector entities. Each end-user group presents unique requirements for service level agreements, security, and integration.
- Individual Subscribers:This segment includes residential customers and mobile users who consume voice, data, and messaging services for personal use. Rapid smartphone penetration in India significantly expands this subscriber base.
- Enterprises:Businesses utilize wireless services for internal communication, IoT deployments, private networks, and connecting distributed workforces. Demand for dedicated IoT connectivity from enterprise end users is expanding rapidly.
- Public Safety Agencies:Government organizations responsible for law enforcement, fire, and emergency medical services rely on secure and reliable wireless communication.
- Transportation Firms:Companies involved in logistics and passenger transport leverage wireless services for fleet management, navigation, and operational efficiency.
- Educational Institutions:Schools and universities use wireless networks to provide internet access, support digital learning platforms, and manage campus operations.
- Government Organizations:Various government bodies employ wireless services for administrative functions, public services, and critical infrastructure management.
Individual Subscribers represent the largest volume of connections. The Enterprise segment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks in some regions compel carriers to invest heavily in network upgrades, while others offer more flexible spectrum policies. This divergence in regulatory environments creates a complex landscape for telecommunication service providers globally. Operators often weigh the cost of compliance against market potential when strategizing network deployment.
United States
Demand for 5G Fixed Wireless Access (FWA) is strong in suburban and rural areas. The FCC's spectrum auctions and infrastructure policies significantly influence network deployment strategies for major carriers. Dense urban markets like New York City and Los Angeles see significant mmWave technology investments.
India
Smartphone penetration and data consumption drive immense demand for mobile services. The TRAI's push for digital inclusion through initiatives like Digital India accelerates subscriber growth. Major metropolitan areas like Mumbai and Delhi are experiencing rapid 5G rollout.
South Korea
Advanced 5G infrastructure deployment supports innovative low-latency applications. The Ministry of Science and ICT (MSIT) promotes early adoption of next-generation telecommunications technologies. Seoul and Busan are centers for 5G Standalone (SA) network advancements.
Germany
Enterprise demand for dedicated IoT connectivity and private 5G networks is expanding. The Bundesnetzagentur oversees spectrum allocation, shaping the competitive landscape for 5G expansion. Major industrial hubs like Bavaria and North Rhine-Westphalia are leveraging extensive fiber backbones for network support.
China
Massive subscriber bases and government-backed digital initiatives fuel consistent growth in data services. The Ministry of Industry and Information Technology (MIIT) guides nationwide 5G infrastructure development. Urban centers such as Shanghai and Shenzhen are at the forefront of network technology innovation.
Wireless Telecommunication Services Market Key Industry Players
United States-based producers anchor one tier of the market, while European and Asian specialists hold significant positions. The market exhibits a tiered structure, with global operators competing against regional and national providers for subscriber share and enterprise contracts. Strategic archetypes include integrated network operators, infrastructure providers focused on wholesale services, and value-added service specialists targeting niche enterprise segments. Capacity expansion through 5G rollout and strategic partnerships for edge computing integration are dominant competitive moves among these players.
Within the integrated network operator archetype, Verizon Communications, a major US-based provider, exemplifies advanced mmWave technology deployment in dense urban markets. China Mobile, a state-owned enterprise with a vast subscriber base, anchors the Asian market, leveraging extensive network infrastructure for widespread connectivity. Deutsche Telekom, a prominent European operator, sits within the tier of companies expanding 5G through extensive fiber backbones across Germany and other key territories, focusing on both consumer and enterprise solutions.
| Leading Market Players |
|---|
| AT&T |
| Verizon Communications |
| China Mobile |
| Vodafone Group |
| Deutsche Telekom |
| T-Mobile US |
| América Móvil |
| China Telecommunications Corporation |
| NTT DOCOMO |
| Others |
Cost & Logistics Intelligence
Vertical integration into core network infrastructure, such as fiber backbones and tower assets, anchors both an operator's supply position and its long-term pricing power in the wireless telecommunication services market.
Pricing Analysis
Subscriber service margins are highly sensitive to competition and data commoditization, particularly for consumer-grade offerings. The dominant pricing model remains subscription-based, often tiered by data volume or speed, with additional charges for value-added services. Network quality and bundled content services serve as key price differentiation drivers. Pricing pressure stems from intense competition among operators and the increasing commoditization of basic data. Individual subscribers exhibit high price sensitivity, while enterprise clients show lower sensitivity for dedicated IoT connectivity and private network solutions.
Supply Chain Analysis
Single-source vulnerability sits with key network equipment vendors for 5G infrastructure, particularly in radio access network (RAN) components. Geographic supply concentration for these critical components centers on China, South Korea, and parts of Europe. The industry's raw material dependencies include specialized semiconductors, optical fiber, and radio frequency components. Geopolitical tensions impacting equipment availability represent a significant supply chain risk. Distribution runs through direct sales channels from equipment manufacturers to wireless network operators, often involving system integrators for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, as the lower operational costs and massive subscriber base in India offer a different revenue landscape compared to the high average revenue per user (ARPU) but capital-intensive markets like the United States.
For Market Incumbents:Extend network slicing capabilities to enable new, high-margin enterprise verticals like industrial automation and connected healthcare. Optimize legacy network infrastructure to reduce operational costs, mitigating the threat from high 5G capital expenditures. Leverage existing fiber backbones to support advanced 5G Standalone (SA) deployments. Invest in edge computing partnerships to deliver ultra-low-latency applications.
For New Entrants and Emerging Players:Open RAN initiatives in Europe open a window for new entrants to challenge established vendors by offering disaggregated network components. Target niche enterprise segments requiring dedicated IoT connectivity or private 5G networks, where specific performance guarantees are critical. Focus on underserved rural and suburban areas with 5G Fixed Wireless Access (FWA) solutions. Partner with cloud providers to offer multi-access edge computing (MEC) services as a go-to-market angle.
For Investors and Strategic Acquirers:Roll-up economics work for regional FWA providers because the demand for high-speed broadband in underserved areas is robust and growing. The long-term viability of the wireless telecommunication services market is anchored in the sustained demand for ubiquitous, high-performance connectivity. Target specialized IoT connectivity providers or regional network operators with strong local market penetration. Accelerated enterprise adoption of private 5G networks is a key signal to watch as an inflection indicator for new investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Network Slicing Development | This initiative tailors network performance and resources for specific enterprise applications. |
| Edge Computing Partnerships | These collaborations enable ultra-low-latency services for industrial users and developers. |
| Open RAN Adoption | This strategy diversifies the equipment supply chain and reduces single-vendor lock-in. |
| Private Network Offering | This provides secure, dedicated connectivity for large industrial sites and campuses. |
| FWA Expansion | This captures new revenue streams in suburban and rural broadband markets. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market landscape. The analysis combines in-depth interviews with industry stakeholders, including network architects, enterprise IT managers, regulatory officials, and telecom analysts, with extensive secondary validation. Bottom-up data triangulation across various sources provides a comprehensive market view.
Rate-of-change decomposition drives the forecast model, analyzing shifts in adoption, technology evolution, and regulatory impacts across the analysis window. Segmentation dimensions modeled include service type, technology, application, end user, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived based on historical trends and projected market dynamics, incorporating key industry-specific inputs like smartphone penetration and 5G Standalone (SA) rollout pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions like geopolitical shifts impacting equipment supply. Forecasts reflect a synthesis of assumptions regarding technological advancements and market adoption rates. Spectrum policy changes and global economic downturns represent specific risk factors that could revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Mesh Wifi System Market
Wireless Technologies
Global Wi-Fi Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
USA Li-Fi Market