
 USA Li-Fi Market | 2026-2036
USA Li-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
USA Li-Fi Market Analytics
Buyer concentration across federal defense procurement is broadening as civilian healthcare networks and educational institutions enter the addressable base. pureLiFi Ltd. leverages its Scotland-to-USA technology transfer pipeline to sustain R&D intensity in military-grade optical links. Signify Holding (Trulifi) anchors the commercial lighting integration channel through its existing LED infrastructure footprint. Qualcomm Technologies, Inc. competes by embedding Li-Fi modems directly into mobile chipset reference designs.
Li-Fi transmits data through modulated light-emitting diodes operating across the 380–780 nanometer visible spectrum and adjacent infrared bands, achieving bidirectional throughput exceeding standard Wi-Fi in controlled line-of-sight deployments. Its primary commercial purpose centers on delivering high-density wireless connectivity without radio-frequency interference in electromagnetic-sensitive environments. Visible Light Communication dominates current deployment volumes due to mature LED infrastructure, while Hybrid Systems capture expanding margin pools as enterprises demand seamless handoff between optical and radio-frequency backhaul. Healthcare Facilities represent the fastest-growing end-user category as hospitals deploy Li-Fi for patient monitoring networks where electromagnetic compatibility restrictions apply.
The FCC governs unlicensed spectrum rules for visible light transmission, while the FDA oversees electromagnetic compatibility standards for medical device environments where Li-Fi displaces conventional wireless. OSHA workplace safety guidelines influence indoor optical power limits to prevent retinal exposure hazards in commercial deployments. Stakeholders must monitor evolving IEEE 802.11bb standard ratification timelines and corresponding NIST cybersecurity frameworks for optical wireless networks.
Market Dynamics
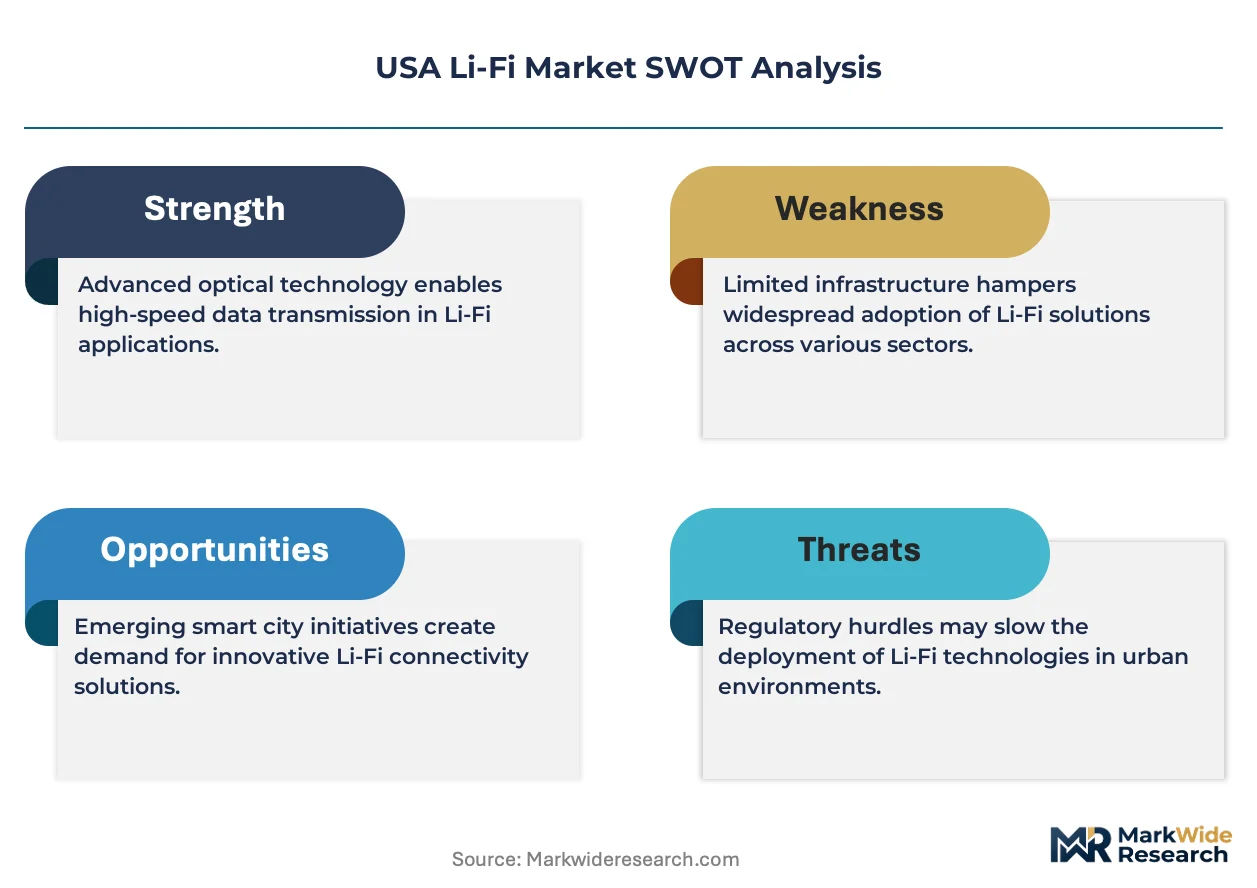
The FCC's unlicensed spectrum allocation for visible light bands is compressing deployment timelines, while electromagnetic compatibility mandates from FDA and OSHA accelerate substitution of radio-frequency infrastructure in sensitive environments.
Growth Catalysts
- FCC Spectrum Policy:Unlicensed designation for 380-780 nanometer visible light bands eliminates licensing friction for commercial deployments. Federal agencies now procure optical wireless for electromagnetic-sensitive facilities.
- Healthcare Electromagnetic Restrictions:Patient monitoring networks in hospitals face strict FDA electromagnetic compatibility standards. Li-Fi bypasses radio-frequency interference constraints entirely.
- California-Texas Corridor Demand:Technology clusters in California's innovation corridor and defense procurement centers in Texas concentrate early infrastructure investment.
Market Restraints
- Line-of-Sight Architecture:Optical wireless requires unobstructed transmitter-receiver alignment. Physical barriers degrade signal integrity in complex indoor environments.
- LED Infrastructure Replacement Cycles:Existing lighting installations must reach end-of-life before Li-Fi retrofit becomes economically viable. Commercial real estate landlords delay capital deployment.
- Radio-Frequency Incumbency:Wi-Fi 6E and Wi-Fi 7 standards deliver incremental performance gains. Enterprises hesitate to abandon mature radio-frequency ecosystems.
Strategic Opportunities
- Educational Institution Networks:K-12 schools and university campuses seek high-density connectivity for device-dense classrooms. Electromagnetic sensitivity concerns in aging buildings create entry points.
- IEEE 802.11bb Standardization:Pending ratification of optical wireless networking standards will unlock enterprise procurement budgets awaiting interoperability certification.
- Hybrid Optical-RF Convergence:Seamless handoff between visible light communication and cellular backhaul addresses mobility limitations. System integrators capture margin pools from unified deployment.
Industry Challenges
- Optical Engineering Talent Scarcity:Photonics specialists with visible light communication expertise command premium compensation. Defense contractors and commercial vendors compete for limited domestic talent pools.
- Legacy Building Integration Complexity:Retrofitting Li-Fi into existing electrical and network infrastructure requires coordination across lighting, IT, and facilities management silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Li-Fi Market |
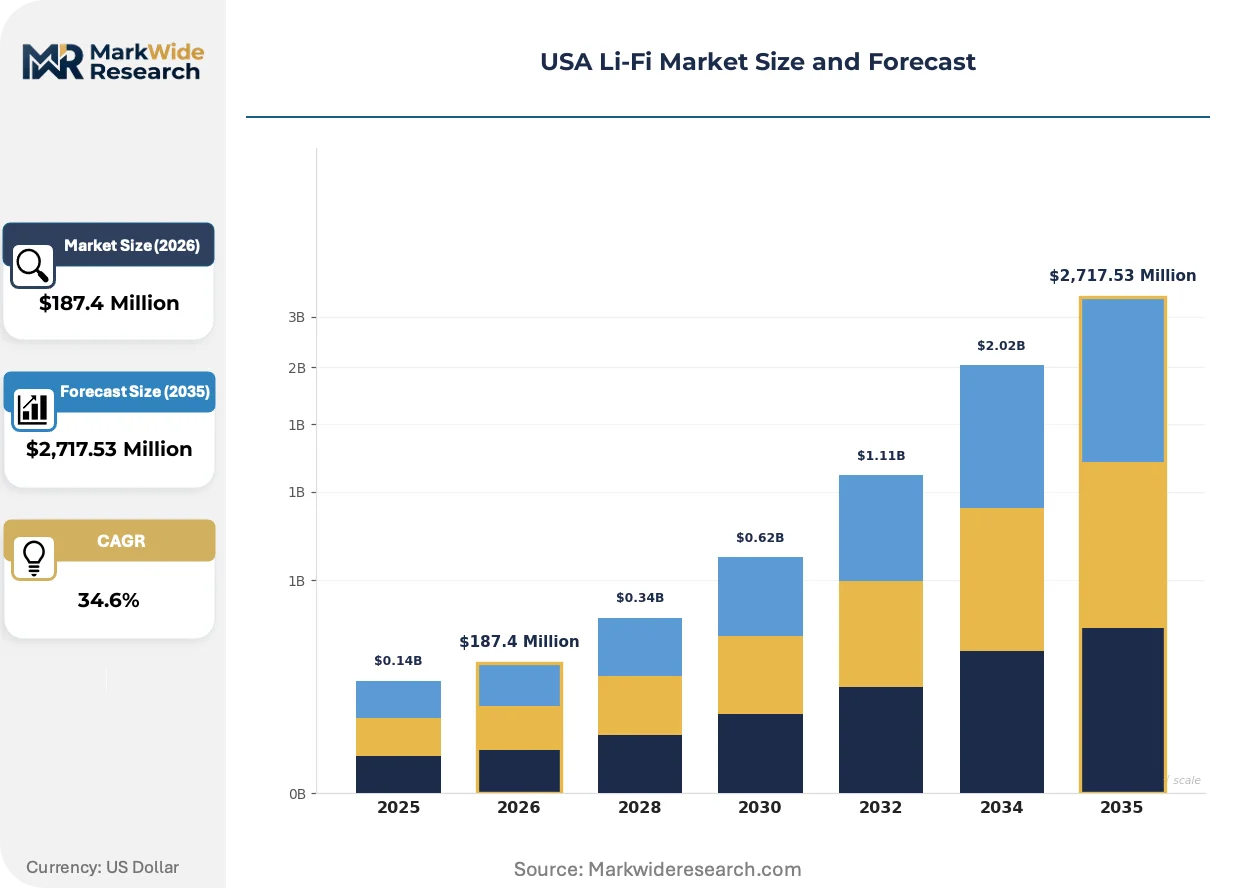
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,717.53 Million |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Visible Light Communication, Infrared Communication, Hybrid Systems, Optical Wireless Networks Application: Smart Lighting, Healthcare Monitoring, Educational Tools, Retail Services End User: Residential Users, Commercial Spaces, Educational Institutions, Healthcare Facilities Deployment: Indoor, Outdoor, Mobile, Fixed |
| Companies Covered | Panasonic Holdings Corporation, Acuity Brands, Inc. (Atrius), Signify Holding (Trulifi), LVX System Corporation, OLEDCOMM SAS, VLNComm Inc., pureLiFi Ltd., SaNoor Technologies Inc., Qualcomm Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Li-Fi Market Evolving Landscape
Visible light communication is consolidating its position as the dominant optical wireless modality, while regulatory frameworks and procurement behaviors reshape competitive positioning across federal and commercial segments.
Hybrid Li-Fi systems are consolidating market architecture by combining visible light downstream with infrared upstream channels. Defense contractors and healthcare networks adopt these configurations to maintain bidirectional throughput without radio-frequency emissions. The technology is consolidating procurement decisions around unified optical-RF infrastructure vendors rather than point solutions.
FCC Part 15 rules for unlicensed intentional radiators now explicitly encompass visible light communication devices. Equipment manufacturers accelerate certification submissions to capture first-mover advantage in enterprise channels. California-based technology vendors and Texas defense suppliers align product roadmaps with anticipated enforcement timelines.
Hospital procurement committees now require electromagnetic compatibility documentation for all wireless infrastructure purchases. Radio-frequency equipment faces extended evaluation cycles compared to optical alternatives. This behavioral shift concentrates demand in healthcare facilities across electromagnetic-sensitive zones in California, Texas, and federal medical centers.
USA Li-Fi Market Segmentation
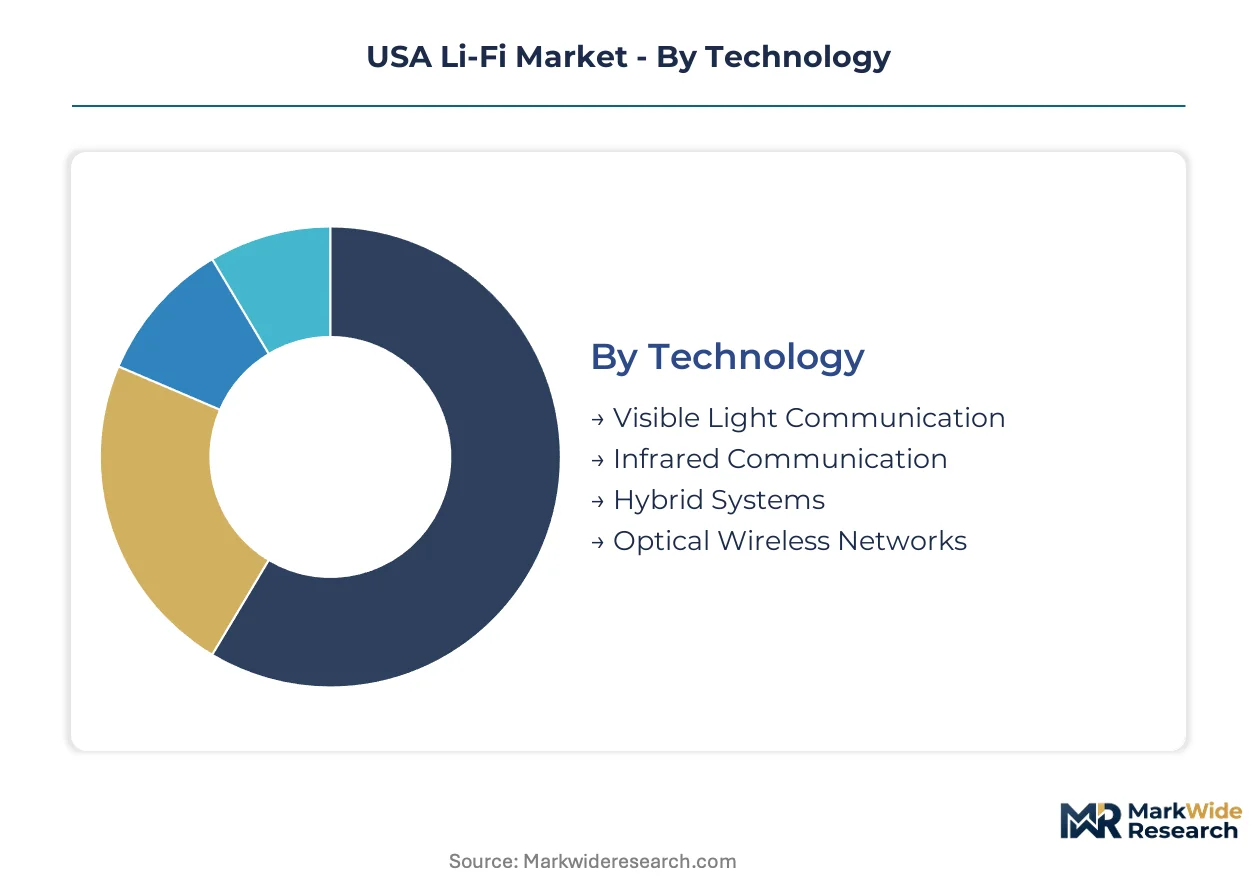
Technology selection in the USA Li-Fi Market determines regulatory pathway complexity and infrastructure investment requirements. Segment-specific certification demands from the FCC, FDA, and OSHA create divergent commercialization timelines across deployment scenarios.
Technology:
FCC Part 15 certification applies universally, yet FDA electromagnetic compatibility documentation requirements vary sharply by transmission medium and end-use environment.
- Visible Light Communication:Modulated LED transmission across 380-780 nanometer spectrum leverages mature solid-state lighting infrastructure. Demand concentrates in California commercial real estate retrofits where landlords face compressed timelines for electromagnetic-sensitive tenant requirements.
- Hybrid Systems:Bidirectional architectures combining visible light downstream with infrared upstream eliminate radio-frequency emissions entirely. Texas defense contractors procure these configurations for secure facilities requiring TEMPEST-level electromagnetic containment.
- Infrared Communication:Near-infrared bands (780-1000 nanometer) enable non-visible optical links for discrete deployments.
- Optical Wireless Networks:Mesh-capable Li-Fi architectures supporting seamless handoff between optical access points.
Leading the category by volume: Visible Light Communication. Growing fastest: Hybrid Systems.
Application:
Cost tier stratification separates capital-intensive healthcare infrastructure from high-volume commercial lighting retrofits with faster payback periods.
- Healthcare Monitoring:Continuous patient data transmission in electromagnetic-restricted zones requires FDA 510(k) clearance for adjacent medical devices. Demand clusters in Texas Medical Center and federal VA hospital networks where Wi-Fi interference risks patient safety systems.
- Smart Lighting:Integrated illumination and connectivity infrastructure targets commercial real estate with 10-15 year LED replacement cycles. California's Title 24 energy codes accelerate adoption in new construction.
- Educational Tools:High-density classroom connectivity for device-per-student initiatives.
- Retail Services:Location-based analytics and customer engagement through overhead lighting infrastructure.
Dominant by deployment value: Healthcare Monitoring. Steepest expansion trajectory: Smart Lighting.
End User:
Customer type determines procurement authority structure — federal acquisition regulations versus commercial facility management budgets versus institutional capital planning cycles.
- Healthcare Facilities:Hospital procurement committees mandate electromagnetic compatibility documentation exceeding commercial standards. Federal medical centers in Maryland and Texas drive standardization requirements.
- Commercial Spaces:Corporate campuses and multi-tenant buildings prioritize TCO optimization across 15-year infrastructure lifecycles.
- Educational Institutions:K-12 districts and university systems leverage E-rate funding eligibility for optical wireless.
- Residential Users:Early adopters in electromagnetic-sensitive housing segments.
Highest procurement authority concentration: Healthcare Facilities. Fastest budget cycle acceleration: Educational Institutions.
Deployment:
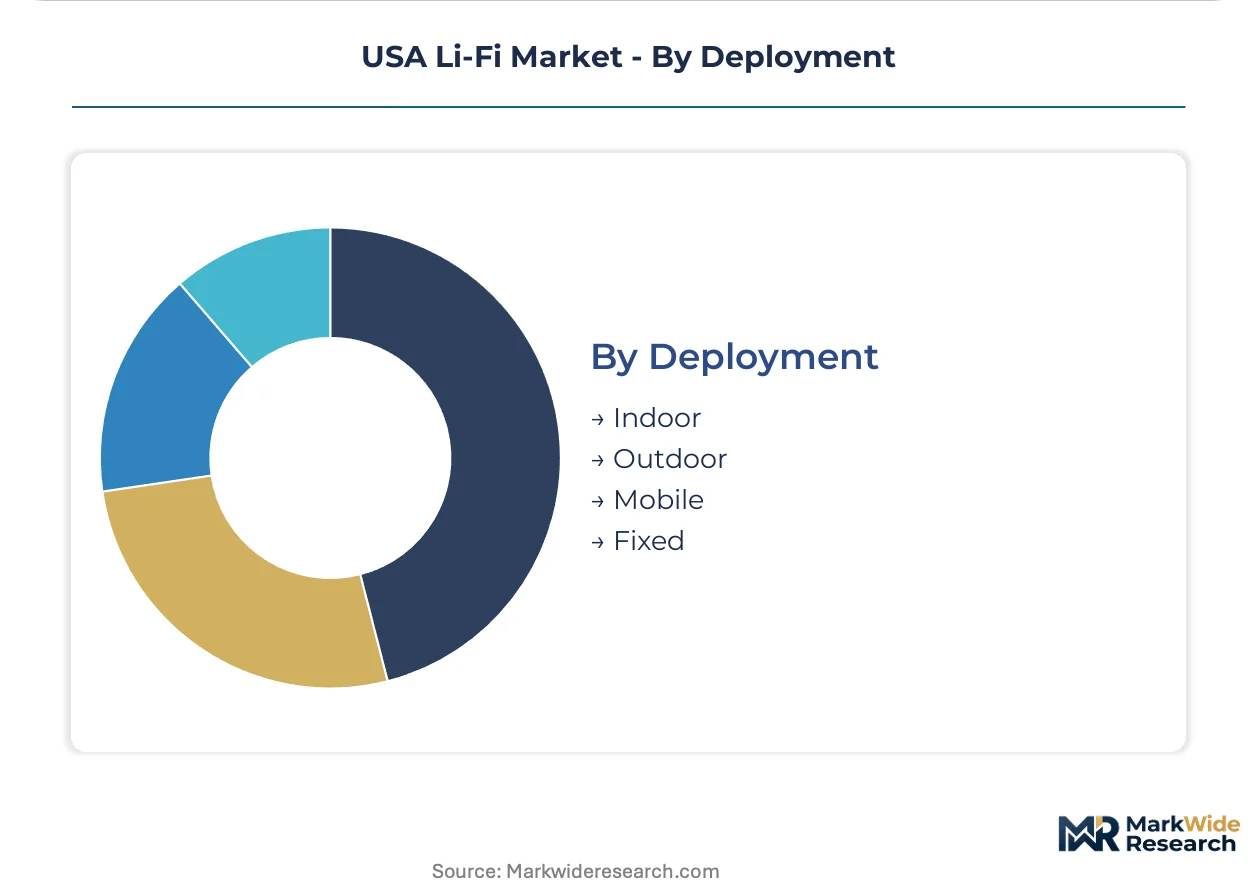
Environmental exposure dictates optical power limits under OSHA workplace safety guidelines and constrains mobility support architecture.
- Indoor:Controlled line-of-sight environments dominate current deployment volumes. Ceiling-mounted LED arrays in Texas defense facilities and California healthcare networks establish performance baselines.
- Mobile:Handoff protocols between optical cells and cellular backhaul address pedestrian mobility in enterprise campuses.
- Outdoor:Weather-hardened optical transceivers for campus perimeter and parking structure coverage.
- Fixed:Static workstation links in electromagnetic-sensitive manufacturing cells.
Volume leadership: Indoor deployments. Mobility capability expansion: Mobile architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement clusters and healthcare networks concentrate optical wireless demand in specific sub-regional corridors, with state-level energy codes and federal facility mandates accelerating deployment timelines unevenly across the country.
California
Commercial real estate developers in San Francisco and Los Angeles integrate Li-Fi into Title 24-compliant new construction to attract electromagnetic-sensitive tenants. The California Energy Commission's building efficiency standards compress LED replacement cycles. Silicon Valley technology campuses pilot hybrid optical-RF networks for high-density device environments.
Texas
Defense contractors in the Dallas-Fort Worth corridor and Houston's Texas Medical Center procure TEMPEST-level optical systems for secure federal facilities. Veterans Affairs hospital networks mandate electromagnetic compatibility documentation that favors Li-Fi over conventional wireless. Austin's technology corridor attracts Li-Fi infrastructure vendors establishing regional headquarters.
Maryland
Federal medical centers in Bethesda and Baltimore drive standardization requirements for optical wireless procurement. The FDA's electromagnetic compatibility oversight for adjacent medical devices creates evaluation advantages for Li-Fi in hospital networks. Fort Meade defense installations require optical communications for sensitive compartmented information facilities.
Illinois
Chicago's commercial real estate market faces tenant pressure for interference-free connectivity in aging Class B buildings. The state's educational institutions explore E-rate funding eligibility for optical wireless classroom deployments. Manufacturing corridors near Rockford evaluate fixed optical links for electromagnetic-sensitive production cells.
Massachusetts
Greater Boston's healthcare research complexes deploy Li-Fi for patient monitoring networks where radio-frequency restrictions apply. MIT and Harvard research partnerships advance visible light communication protocols. Defense subcontractors in the Route 128 technology belt integrate optical wireless into federal procurement supply chains.
USA Li-Fi Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized defense and healthcare certification pathways. The vendor base stratifies across lighting infrastructure incumbents, semiconductor specialists, and optical communication pure-plays. Three archetypes dominate: LED-integrated platform vendors, chipset-embedded modem suppliers, and electromagnetic-hardened system integrators. Capacity expansion and strategic technology licensing represent the primary competitive moves as firms secure FCC Part 15 certification ahead of rivals.
Within the lighting-integrated tier, Signify Holding exemplifies the commercial infrastructure archetype through its Trulifi product line, while Acuity Brands occupies a parallel position serving North American building automation channels. pureLiFi Ltd. represents the optical communication pure-play model with its Scotland-to-USA technology transfer focus. These three entities anchor the competitive structure across commercial, federal, and specialized healthcare deployment scenarios.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Acuity Brands, Inc. (Atrius) |
| Signify Holding (Trulifi) |
| LVX System Corporation |
| OLEDCOMM SAS |
| VLNComm Inc. |
| pureLiFi Ltd. |
| SaNoor Technologies Inc. |
| Qualcomm Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Federal defense procurement programs and healthcare facility capital committees anchor pricing power toward project-based contracting with extended certification timelines. This buyer concentration elevates FCC Part 15 certification premiums while compressing margins on commercial lighting retrofits awaiting LED replacement cycles.
Pricing Analysis
Volume concentrates in visible light communication retrofits where commoditized LED infrastructure drives transactional per-fixture pricing, while hybrid systems command project-based premiums for TEMPEST-level electromagnetic containment. Price differentiation hinges on FDA electromagnetic compatibility documentation grade and defense contractor security clearance tier. Pricing pressure stems from Wi-Fi 6E and Wi-Fi 7 incumbency delaying enterprise optical migration. Commercial real estate landlords exhibit highest price sensitivity; federal agencies demonstrate lowest sensitivity due to mission-critical electromagnetic restrictions.
Supply Chain Analysis
Domestic-content mandates from the Department of Defense reshape sourcing toward qualified U.S.-based photonics foundries and LED packaging facilities. Component supply concentrates in Taiwan for optical modulator chips, South Korea for advanced LED substrates, and domestic Texas-Arizona corridors for defense-hardened assembly. Critical dependencies include gallium nitride wafers, silicon photonics foundry capacity, and infrared emitter arrays. Single-source vulnerability runs through Taiwan-based optical semiconductor fabrication. Distribution feeds through defense prime contractors and commercial lighting specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical engineering talent scarcity props pricing across all tiers, with photonics specialist compensation premiums creating a supply-constrained bottleneck that sustains vendor margins despite competitive pressure.
For Market Incumbents: Hedge against Wi-Fi 7 encroachment by accelerating IEEE 802.11bb certification timelines and embedding Li-Fi modems into mobile chipset reference designs through Qualcomm-style partnerships. Vertical integration into gallium nitride wafer sourcing mitigates Taiwan foundry concentration risk. Prioritize defense contractor relationships where electromagnetic sensitivity mandates sustain premium pricing. For New Entrants and Emerging Players: E-rate funding channels for K-12 educational institutions offer the most penetrable white-space entry, with aging building electromagnetic concerns creating procurement urgency absent in commercial real estate. Target Texas and Illinois school districts with device-per-student connectivity mandates. Pursue specification partnerships with educational technology distributors rather than direct enterprise sales. For Investors and Strategic Acquirers: The window for entry favors electromagnetic-hardened system integrators with existing FDA 510(k) clearance pathways and defense security clearances. Long-term viability centers on hybrid optical-RF convergence architectures enabling seamless mobility handoff. Watch IEEE 802.11bb ratification timelines as the inflection signal unlocking enterprise procurement budgets.| Strategic Initiative | Industry Significance |
|---|---|
| IEEE 802.11bb Certification Acceleration | FCC Part 15 pre-certification captures first-mover advantage in enterprise channels before standards ratification. |
| Defense Security Clearance Acquisition | TEMPEST-level facility access unlocks federal procurement pipelines concentrated in Texas and Maryland corridors. |
| Hybrid Optical-RF Platform Development | Seamless handoff capability addresses mobility limitations that constrain pure Li-Fi enterprise adoption. |
| Educational Institution Distribution Partnership | E-rate eligibility positioning captures K-12 budget cycles accelerating faster than commercial real estate replacement. |
| Photonics Talent Pipeline Investment | Scotland-to-USA technology transfer replication mitigates domestic optical engineering scarcity premium. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for triangulation against primary interviews with defense procurement officers, hospital biomedical engineers, commercial real estate facilities managers, and LED lighting specification architects. FCC Part 15 equipment authorization databases, FDA 510(k) clearance records, and GSA procurement schedules supplied installation and certification trajectory data. Bottom-up facility deployment estimates reconciled against top-down semiconductor shipment volumes.
Data-stream reconciliation across optical component bill-of-materials, LED fixture production volumes, and federal contract award notifications informed the analytical framework. Segmentation modeling incorporated technology modality, application environment, end-user procurement authority, and deployment mobility architecture. CAGRs derived from fitted adoption curves calibrated to electromagnetic sensitivity mandate expansion and LED infrastructure replacement cycle timing. Defense budget appropriation trajectories and California Title 24 energy code compliance deadlines served as industry-specific forecast inputs.
The model holds under continued FCC unlicensed spectrum policy stability and IEEE 802.11bb ratification within standard-setting timelines; deviation in defense procurement priority shifts or Wi-Fi 7 performance breakthroughs would shift adoption trajectories. Forecasts reflect these documented assumptions with acknowledged sensitivity to optical engineering labor market tightness and Taiwan foundry capacity constraints. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
5G WIT120 Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Latin America Wireless Mesh Networking Market