
 Saudi Arabia Portable Air Conditioner Market | 2026-2036
Saudi Arabia Portable Air Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Portable Air Conditioner Market Insights
Commercial tenants in Riyadh's retail and food-service sectors is reorganizing procurement patterns for portable air conditioners, displacing traditional residential buyers as the fastest-growing archetype. Zamil AC leverages its domestic manufacturing footprint to control distribution across the Kingdom's eastern provinces. GREE sustains cost competitiveness through captive supply of rotary compressors from its Chinese parent operations. LG differentiates via inverter technology leadership in the premium residential segment.
Portable air conditioners are self-contained refrigeration systems rated between 8,000 and 14,000 BTU per hour, designed for spaces lacking permanent ductwork or where landlord restrictions prohibit structural modifications. The units circulate refrigerant through a closed vapor-compression cycle, exhausting condenser heat through a flexible hose routed to a window or drop ceiling. Floor standing units dominate volume sales among Saudi renters seeking seasonal mobility, while inverter technology captures margin pools through electricity savings during peak summer tariff periods. Smart-connected models represent the fastest-growing technology segment as Wi-Fi-enabled scheduling aligns with Saudi Arabia's rising digital household penetration.
The Saudi Standards, Metrology and Quality Organization (SASO) enforces mandatory energy efficiency labeling and seasonal performance testing for all imported cooling equipment, raising compliance costs for non-compliant suppliers. The Saudi Energy Efficiency Center mandates minimum Energy Efficiency Ratio thresholds that compress demand for low-grade evaporative units in favor of compressor-based systems. Stakeholders must monitor potential alignment between SASO standards and Gulf Standardization Organization harmonization efforts, which would reshape cross-border supplier eligibility across the GCC.
Market Dynamics
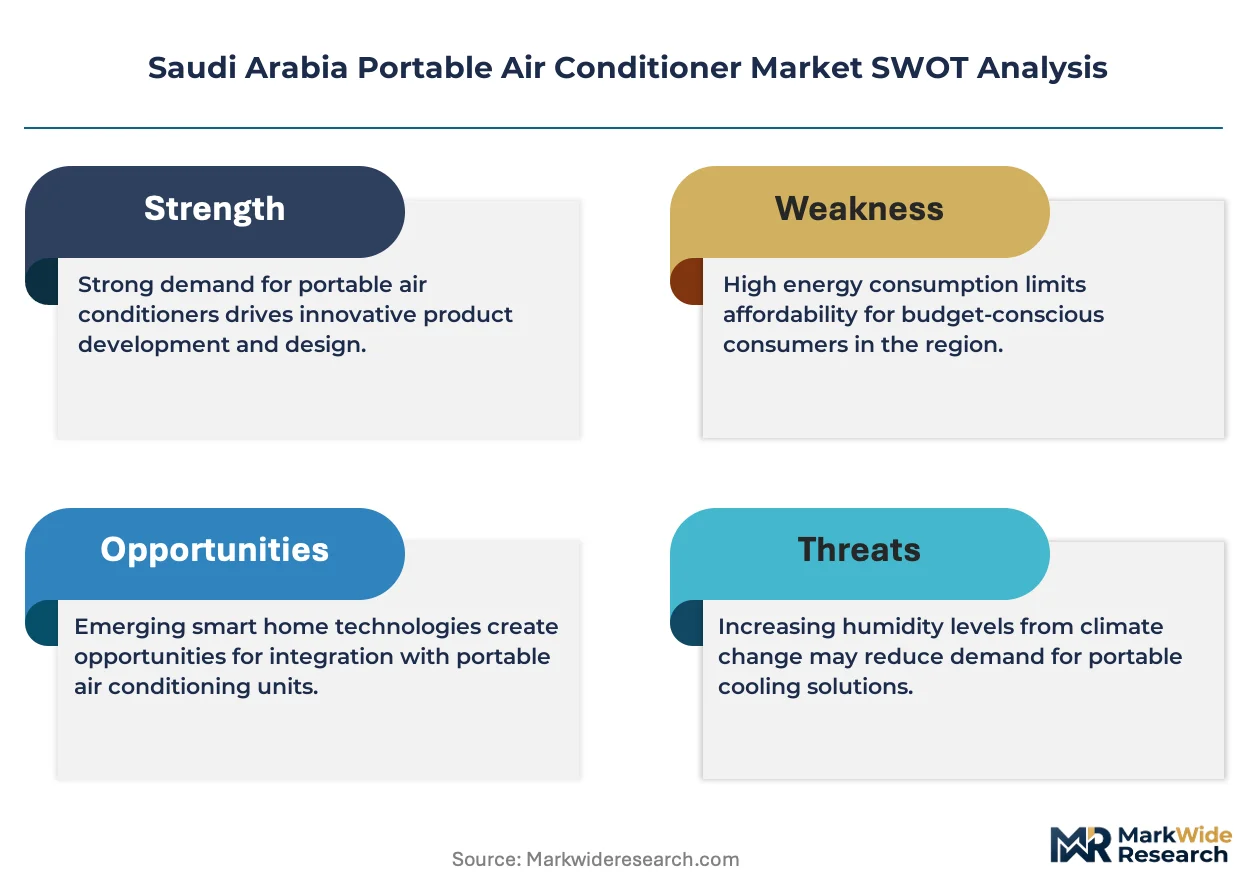
SASO's tightened Energy Efficiency Ratio mandates are compressing demand for low-grade evaporative units and forcing rapid product line upgrades across import-dependent suppliers serving Saudi Arabia's rental-heavy cooling market.
Growth Catalysts
- Riyadh-Jeddah Urbanization Corridor:Apartment construction in these metros is accelerating portable unit deployment where permanent ductwork is prohibited by lease terms.
- SASO Energy Labeling Mandate:The Saudi Standards, Metrology and Quality Organization's seasonal performance testing is filtering out inefficient imports and elevating compressor-based system preference.
- Inverter Technology Maturation:Variable-speed compressor adoption is cutting electricity consumption during peak summer tariff windows, justifying premium pricing for cost-conscious Saudi households.
Market Restraints
- Rotary Compressor Supply Concentration:Captive Chinese manufacturing of core components creates vulnerability for non-vertically integrated Saudi distributors during peak import seasons.
- Single-Hose Thermal Efficiency Ceiling:The physics of condenser heat rejection through flexible ducting imposes hard limits on cooling performance per watt in Saudi Arabia's 50°C ambient conditions.
- Evaporative Cooler Substitution:Low-cost desert cooler units retain foothold in rural Eastern Province markets where humidity stays below 40% and electricity subsidies persist.
Strategic Opportunities
- Asir Province Climate Niche:Mountainous southwestern terrain with milder summers offers underexploited demand for mid-BTU seasonal units among domestic tourism operators.
- Wi-Fi Module Integration:Smart-connected scheduling is penetrating Riyadh's tech-forward rental segments faster than traditional thermostat-controlled models.
- GCC Standardization Harmonization:Potential alignment between SASO and Gulf Standardization Organization protocols would unlock cross-border supplier eligibility for Saudi distributors.
Industry Challenges
- SASO Certification Timeline Compression:Accelerated seasonal performance testing requirements are stretching third-party laboratory capacity in Jeddah and Dammam, delaying product launches.
- Refrigerant Transition Complexity:The shift from R-410A to lower-GWP alternatives demands retooling of service networks across the Kingdom's sparse western regions.
- Last-Mile Cold Chain Integration:E-commerce fulfillment of portable units requires reverse logistics capabilities for condensate drainage accessories that most Saudi parcel networks lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Portable Air Conditioner Market |
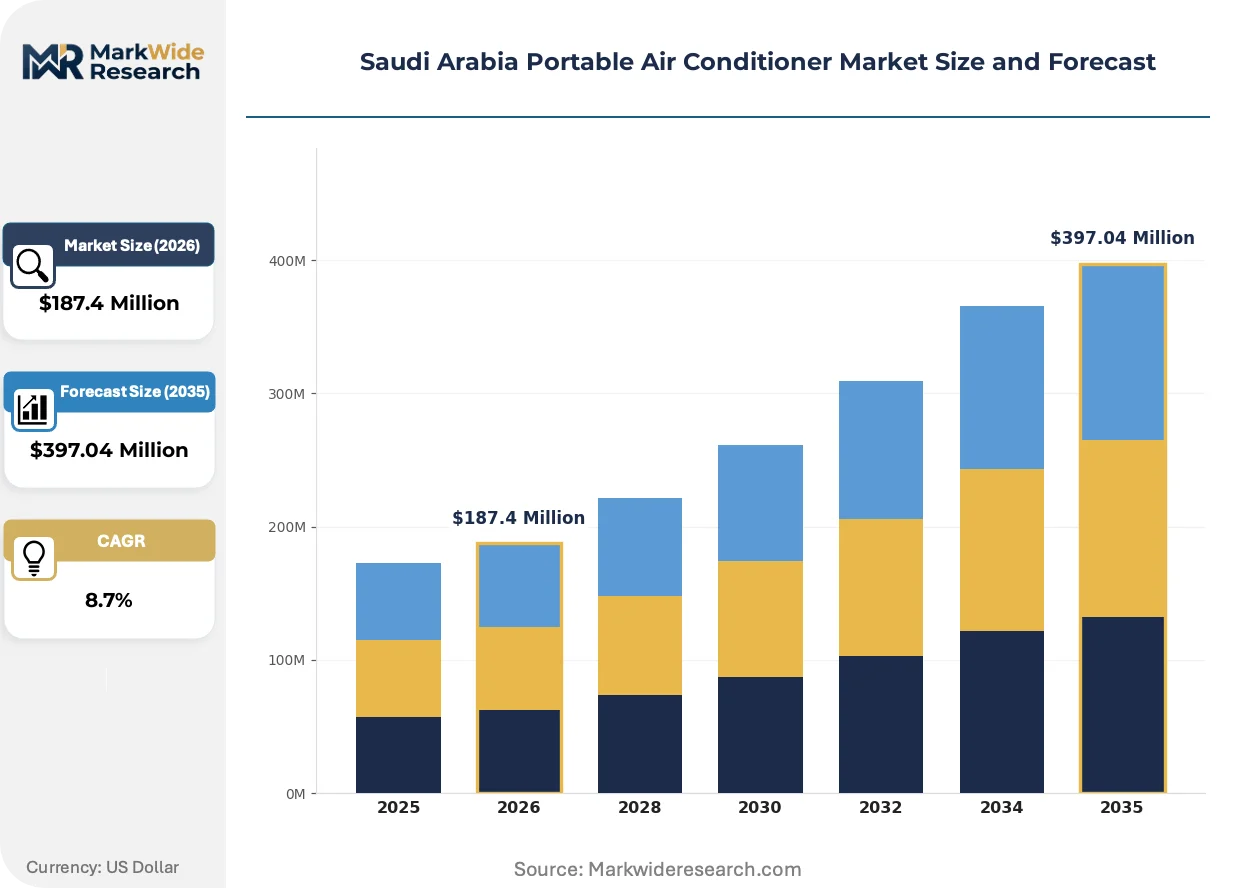
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Standing, Window, Wall Mounted, Hybrid Technology: Evaporative, Compressor, Inverter, Smart End User: Residential, Commercial, Industrial, Hospitality Sales Channel: Online Retail, Offline Retail, Distributors, Wholesalers |
| Companies Covered | Zamil AC, GREE, Panasonic, LG, Daikin, Alessa Industries, Carrier, Awal Gulf Manufacturing, Hitachi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Portable Air Conditioner Market Trends and Innovations
Dual-hose thermal architecture and refrigerant chemistry advances are reshaping product performance benchmarks, while digital connectivity and procurement platform migration are altering how Saudi buyers source cooling equipment.
Rotary compressor design is miniaturizing through magnetic bearing and brushless DC motor integration. Saudi renters in Riyadh's high-rise towers are adopting these compact units at twice the pace of conventional piston models. The technology is miniaturizing floor-standing footprints enough to clear balcony door clearances that previously blocked portable installation.
SASO's alignment with IEC 62087 standby power testing protocols is forcing redesign of control board architectures. Import license delays now average six weeks longer for units failing vampire draw thresholds. Eastern Province distributors are pre-qualifying suppliers against draft standards to avoid customs detention during Ramadan procurement surges.
Building management systems in Jeddah's commercial towers are unbundling cooling procurement from lease agreements. Food-service tenants now source portable units directly through B2B platforms rather than landlord intermediaries. This disintermediation concentrates purchasing power with procurement officers at chain operators, compressing margins for traditional distributor networks.
Saudi Arabia Portable Air Conditioner Market Segmentation
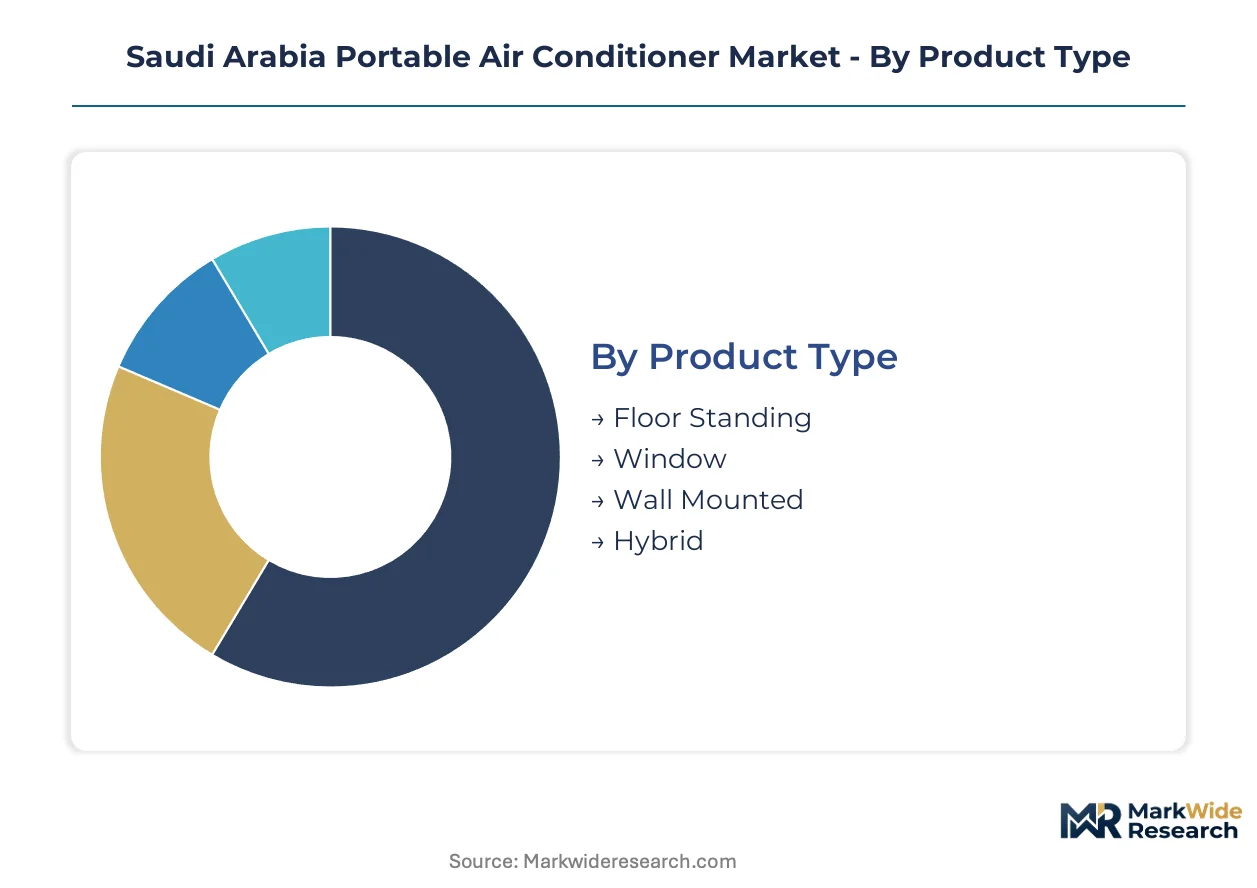
SASO energy efficiency mandates are fragmenting the Saudi portable cooling market into compliance tiers. Product differentiation now hinges on seasonal performance certification rather than raw cooling capacity alone.
Product Type:
SASO labeling thresholds favor floor-standing and hybrid configurations that accommodate dual-hose architectures for improved thermal efficiency ratings.
- Floor Standing:Self-contained vertical units with caster-mounted mobility dominate Riyadh apartment rentals where lease terms prohibit structural modifications. Saudi tenants in Jeddah's high-rise towers favor these for balcony exhaust routing during peak summer loads.
- Hybrid:Convertible units switch between single and dual-hose operation based on ambient humidity. Asir Province tourism operators are adopting these for seasonal flexibility across elevation-varying microclimates.
- Window:Sash-mounted units require landlord approval rare in Saudi rental contracts.
- Wall Mounted:Through-wall installation faces SASO thermal bridging compliance costs that erode portability economics.
Established volume favors floor standing; emerging adoption favors hybrid.
Technology:
Cost tier stratification separates subsidized evaporative units from premium inverter systems facing peak electricity tariffs.
- Inverter:Variable-speed compressors modulate refrigerant flow to cut consumption during Saudi peak tariff windows. Riyadh households with smart meter exposure are upgrading from fixed-speed units despite 40-60% price premiums.
- Smart:Wi-Fi-enabled scheduling and geofencing align with Saudi digital household penetration. Jeddah's tech-forward rental segments are adopting these at triple the pace of thermostat-controlled alternatives.
- Compressor:Fixed-speed vapor-compression systems face SASO efficiency minimums that are retiring entry-tier import lines.
- Evaporative:Desert coolers retain Eastern Province rural share where humidity stays below 40% and electricity subsidies persist.
Compressor technology anchors current volume; smart connectivity is climbing the fastest.
End User:
Application concentration is shifting from residential renters toward commercial tenants with direct procurement authority.
- Commercial:Retail and food-service tenants in Riyadh's mall and tower developments now source portable units directly through B2B platforms. This disintermediation from landlord intermediaries concentrates purchasing power with chain procurement officers.
- Residential:Apartment dwellers across the Riyadh-Jeddah corridor drive seasonal replacement cycles. SASO labeling is filtering preference toward certified inverter models despite higher upfront outlays.
- Hospitality:Domestic tourism operators in Asir Province require mid-BTU seasonal units for mountain lodging capacity expansion.
- Industrial:Workshop and warehouse cooling demands fixed installations that portable units rarely satisfy under Saudi thermal load requirements.
Residential segments dominate current unit volume; commercial procurement is gaining share fastest.
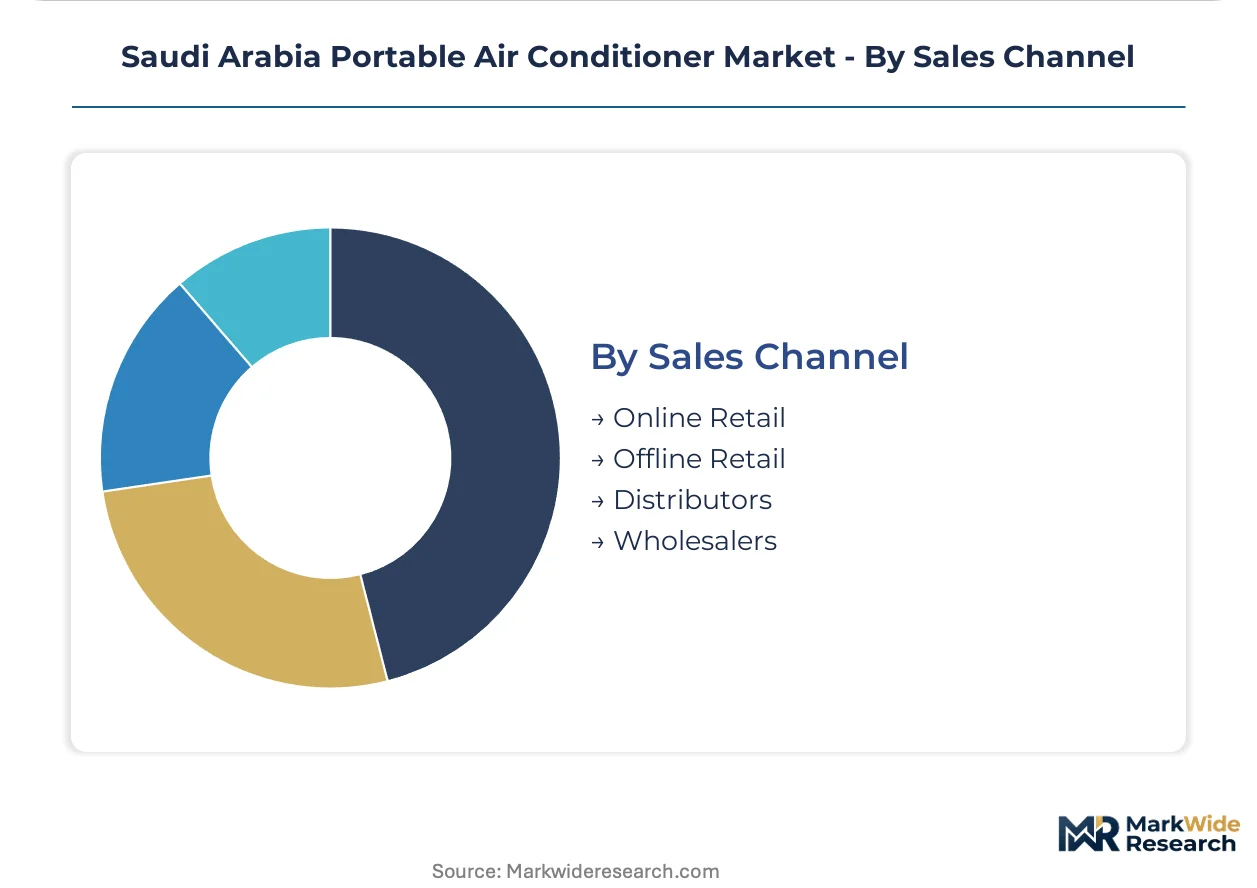
Sales Channel:
Customer type bifurcation separates bulk institutional buyers from individual renters with distinct fulfillment expectations.
- Distributors:Eastern Province networks control inventory positioning ahead of Ramadan procurement surges. Zamil AC leverages domestic manufacturing footprints to pre-qualify suppliers against draft SASO standards.
- Online Retail:E-commerce platforms are penetrating Riyadh's younger renter demographics. Last-mile reverse logistics for condensate drainage accessories remains an unmet capability gap for most Saudi parcel networks.
- Offline Retail:Appliance showrooms in Jeddah and Dammam serve warranty-sensitive buyers requiring physical inspection.
- Wholesalers:Bulk procurement for commercial chain operators concentrates through specialized B2B platforms bypassing traditional distributor margins.
Distributor networks anchor established volume; online retail is expanding most quickly among individual purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese-manufactured rotary compressors flow through Jeddah and Dammam ports to serve Saudi Arabia's rental-heavy cooling market, with SASO certification gates determining supplier eligibility before inland distribution to Riyadh and the Eastern Province.
Riyadh
Apartment construction in the capital is accelerating portable unit deployment where lease terms prohibit permanent ductwork installations. SASO's seasonal performance testing filters inefficient imports before they reach retail channels. The King Abdullah Financial District concentrates food-service tenants sourcing cooling equipment through direct B2B procurement platforms.
Eastern Province
Industrial cities like Jubail and Dammam generate demand for workshop cooling where fixed installations prove uneconomical. Electricity subsidies in rural zones sustain evaporative cooler competition against compressor-based systems. Zamil AC leverages its domestic manufacturing footprint to control inventory positioning ahead of Ramadan procurement surges.
Western Region
Jeddah's high-rise towers favor floor-standing units with balcony exhaust routing during peak summer thermal loads. The Saudi Energy Efficiency Center's minimum EER thresholds compress demand for low-grade imports through the Red Sea port. Smart-connected models penetrate tech-forward rental segments at triple the pace of thermostat-controlled alternatives.
Asir Province
Mountainous southwestern terrain with milder summers offers underexploited demand for mid-BTU seasonal units among domestic tourism operators. Hybrid configurations switch between single and dual-hose operation across elevation-varying microclimates. Abha and surrounding lodging clusters require flexible cooling for capacity expansion without structural modifications.
NEOM Northwest
The giga-project's construction phase creates transient cooling demand favoring portable solutions over permanent infrastructure. SASO alignment with IEC standby power protocols delays import license approvals for non-compliant control board architectures. Field logistics networks remain underdeveloped for last-mile fulfillment of condensate drainage accessories.
Saudi Arabia Portable Air Conditioner Market Competitive Landscape
Player mix skews toward vertically integrated manufacturers with captive compressor supply and domestic assembly footprints. Market structure concentrates around three archetypes: Chinese exporters with rotary compressor backward integration, Saudi-based fabricators with Eastern Province manufacturing assets, and Korean-Japanese electronics conglomerates with inverter technology portfolios. Competitive moves center on SASO pre-certification against draft standards and direct B2B platform disintermediation bypassing traditional distributor margins.
Among the domestic manufacturing tier, Zamil AC and Alessa Industries exemplify the Saudi-based archetype with Eastern Province production positioning. GREE represents the Chinese exporter model with upstream control over rotary compressor supply chains. LG occupies the premium technology tier through inverter differentiation in Riyadh and Jeddah residential segments.
| Leading Market Players |
|---|
| Zamil AC |
| GREE |
| Panasonic |
| LG |
| Daikin |
| Alessa Industries |
| Carrier |
| Awal Gulf Manufacturing |
| Hitachi |
| Others |
Pricing and Supply Chain Analysis
Rotary compressor scale economies in Chinese manufacturing clusters compress unit production costs enough to sustain price floors across Saudi Arabia's import-dependent cooling market. SASO certification timelines and Ramadan procurement surges concentrate inventory risk with Eastern Province distributors who pre-position stock ahead of seasonal demand windows.
Pricing Analysis
Fixed-speed compressor units trade at entry price points, inverter systems command 40-60% premiums, and smart-connected models sit atop tiered pricing stratification across premium, standard, and economy levels. Price differentiation hinges on SASO energy efficiency certification grade and after-sales service bundling. Pricing pressure stems from B2B platform disintermediation concentrating procurement power with commercial chain operators. Residential renters in Riyadh's apartment corridor exhibit highest price sensitivity; food-service tenants in Jeddah's commercial towers show lowest sensitivity due to peak tariff avoidance calculus.
Supply Chain Analysis
Just-in-time inventory strategies dominate Chinese exporter operations, while Saudi distributors maintain strategic stockpiles ahead of SASO testing bottlenecks and Ramadan demand spikes. Manufacturing concentrates in China, South Korea, and domestic Eastern Province facilities. Supply chains draw from rotary compressor, aluminum coil, and refrigerant chemical inputs. Single-source vulnerability runs through captive Chinese compressor supply for non-vertically integrated distributors. Distribution runs through Jeddah and Dammam port clearance before inland forwarding to Riyadh and regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware sales as SASO-mandated seasonal performance testing and refrigerant transition compliance create recurring certification and maintenance revenue layers. Installation, extended warranty, and energy audit services outpace unit shipment growth across the Saudi rental cooling market.
For Market Incumbents: Fortify Eastern Province manufacturing footprints against Chinese exporter cost pressure through backward integration into compressor assembly and pre-certification against draft SASO standards. Expand direct B2B platform presence to intercept commercial tenant procurement migrating from landlord intermediaries. Channel control and certification investment anchor defensive positioning.
For New Entrants and Emerging Players: Last-mile reverse logistics for condensate drainage accessories represents a service-layer gap where incumbents under-serve e-commerce fulfillment needs. Target Asir Province tourism operators with hybrid-configuration seasonal rental programs. Penetrate through Wi-Fi module integration partnerships with Saudi telecom operators bundling smart home services.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors inverter technology specialists with SASO pre-certification capabilities over fixed-speed commodity assemblers. Long-term viability rests on compliance infrastructure and service network density rather than manufacturing scale alone. Watch SASO-GCC harmonization negotiations as inflection signal for cross-border supplier eligibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Pre-Certification Investment | Accelerates product launch timelines through Jeddah and Dammam testing capacity. |
| Dual-Hose Product Line Expansion | Captures premium tier demand as SASO efficiency thresholds favor thermal architecture upgrades. |
| Direct B2B Platform Integration | Disintermediates traditional distributor margins concentrated with Riyadh food-service chain procurement. |
| Smart Connectivity Module Partnership | Aligns with Saudi digital household penetration through Wi-Fi-enabled scheduling adoption. |
| Asir Province Tourism Channel Development | Exploits underpenetrated mountainous lodging demand with hybrid-configuration seasonal offerings. |
Research Methodology
The analysis maps floor-standing, hybrid, and smart-connected product segments, each validated through distributor inventory managers, commercial procurement officers at food-service chains, residential property leasing agents, and SASO certification laboratory directors. Primary interviews combined with secondary validation from SASO technical regulations, Saudi Customs import manifests, and Eastern Province industrial zone investment disclosures. Bottom-up unit shipment modeling and top-down cooling equipment market sizing provided triangulation checks.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled technology type, end-user application, sales channel, and regional climate zone segmentation dimensions. CAGRs derived from unit economics analysis incorporating electricity tariff trajectories, urbanization rates, and regulatory compliance cost evolution. Forecast inputs included SASO testing capacity expansion schedules and inverter technology adoption curves.
Forecasts assume regulatory continuity in SASO energy efficiency mandates and Saudi Energy Efficiency Center minimum EER thresholds; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market