
 Global Massive MIMO Market | 2026-2036
Global Massive MIMO Market Size, Share, and Industry Trends Forecast 2026-2036
Global Massive MIMO Market Outlook
Enterprise and government buyers is rotating toward private 5G networks and campus deployments, displacing traditional macro-cell-centric procurement from mobile network operators. Huawei Technologies Co., Ltd. leverages its integrated baseband-to-radio portfolio to dominate turnkey deployments across Asia-Pacific and Middle East markets. Ericsson sustains R&D intensity in intelligent beam management algorithms, positioning its portfolio for high-interference urban corridors. Samsung Electronics Co., Ltd. anchors its position through captive semiconductor fabrication, controlling cost structures for massive antenna arrays.
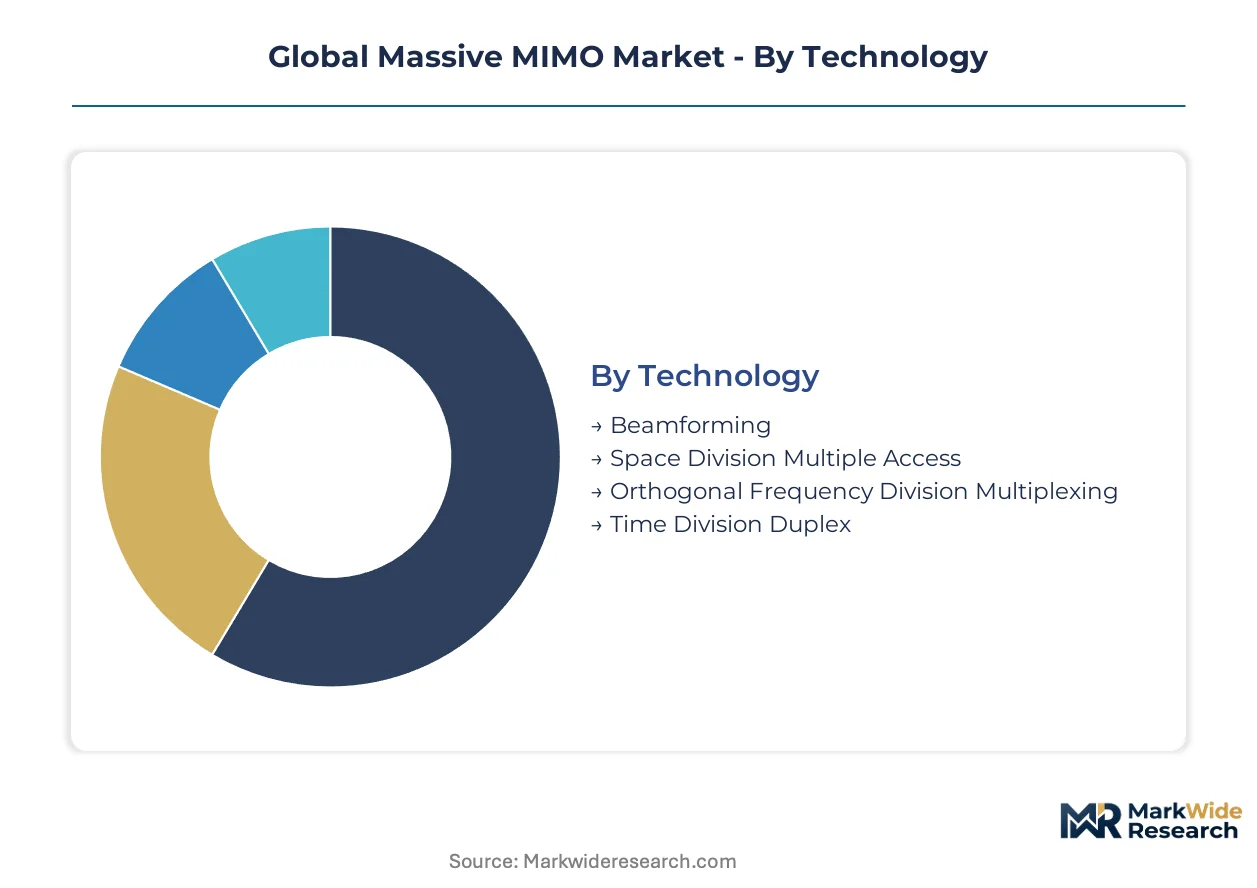
Massive MIMO denotes antenna systems deploying hundreds of radiating elements coordinated through digital signal processing to serve multiple user terminals simultaneously within the same time-frequency resource, typically operating at sub-6 GHz and mmWave bands with 64T64R or 128T128R configurations. Beamforming technology leads deployment volumes as network operators prioritize spectral efficiency gains in sub-6 GHz rollouts, while transceiver components capture concentrated margin pools due to gallium nitride power amplifier integration and thermal management complexity. Time Division Duplex configurations grow fastest in Asia-Pacific deployments where unpaired spectrum allocations dominate, contrasting with Frequency Division Duplex maturity in legacy European markets.
The Federal Communications Commission in the United States, the European Telecommunications Standards Institute, and China's Ministry of Industry and Information Technology each shape equipment certification timelines and spectrum allocation rules that directly determine vendor market access and product development roadmaps. 3GPP Release 18 specifications will introduce AI-native air interface optimization, forcing stakeholders to monitor standardization timelines against internal R&D commit thresholds. Vendors must decide whether to prioritize open RAN interoperability investments or maintain proprietary stack advantages as operator procurement criteria diverge across regulatory jurisdictions.
Market Dynamics
The transition from proprietary radio access networks toward open, disaggregated architectures is fragmenting vendor lock-in patterns and forcing equipment suppliers to recalibrate software-hardware bundling strategies across deployment contracts.
Growth Catalysts
- Spectrum auction momentum:Brazil's Anatel mid-band auctions and India's TRAI 5G spectrum sales are accelerating base station procurement cycles in dense urban corridors.
- Release 17 beam management:3GPP specifications for enhanced channel state information reporting are mandating interoperability upgrades across macro-cell installations.
- AI-native air interface development:Machine learning-based precoding algorithms are compressing spectral efficiency gaps between theoretical and achieved throughput in live networks.
Market Restraints
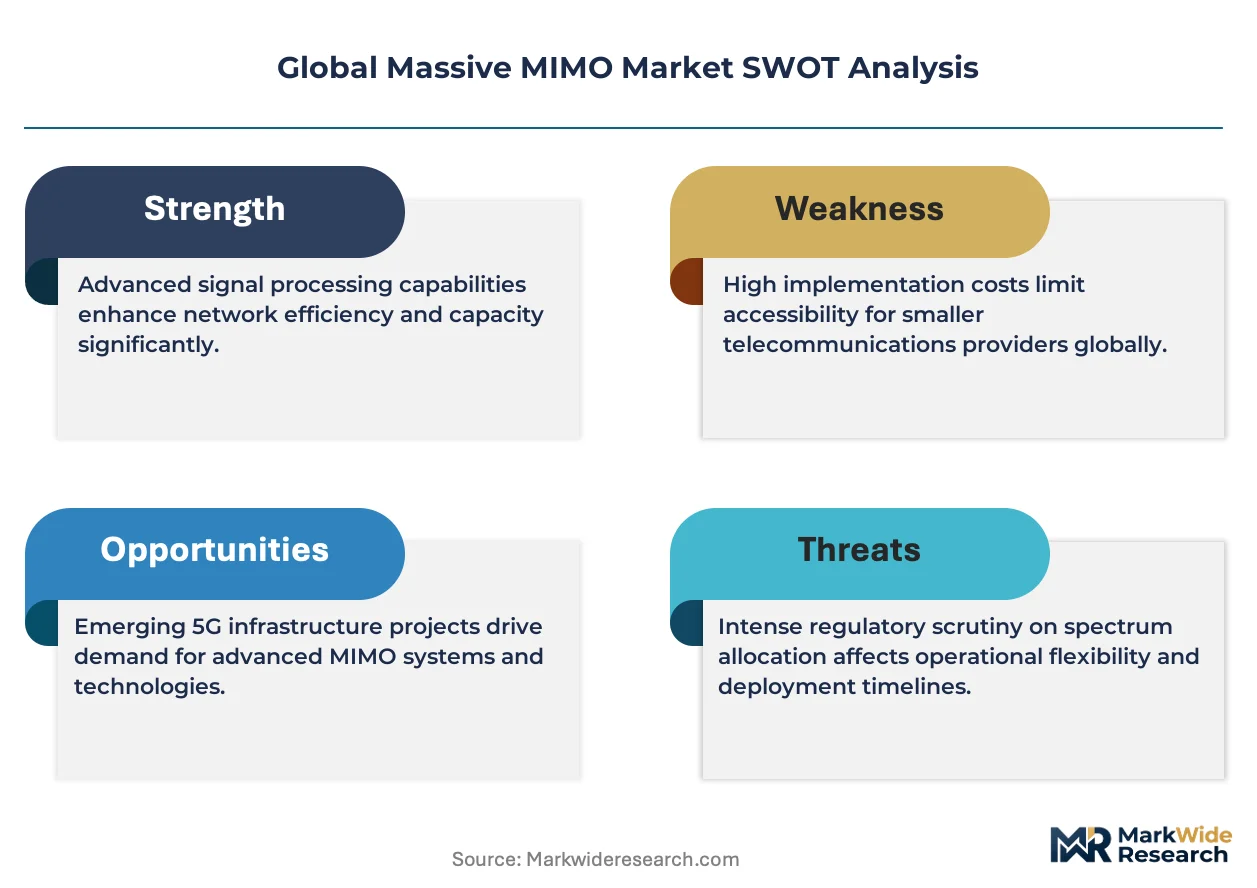
- Gallium nitride substrate concentration:Wafer supply from Japanese and US substrate producers creates chokepoints for high-efficiency power amplifier fabrication.
- Legacy FDD infrastructure drag:European operators with paired spectrum allocations face slower migration timelines compared to TDD-dominant Asian deployments.
- Radio frequency component thermal density:128T128R array configurations exceed passive cooling limits in tropical climates without active thermal management retrofits.
Strategic Opportunities
- Private campus network white space:Manufacturing facilities and port authorities in Germany and South Korea are procuring dedicated massive MIMO cells for ultra-reliable low-latency applications.
- Release 18 AI optimization:Anticipated 3GPP specifications for machine learning-driven beam tracking will create first-mover advantages for R&D-heavy vendors.
- Rural coverage mandates:Universal service obligations in India and Indonesia are subsidizing equipment costs for sparse-population deployments using lower-order MIMO configurations.
Industry Challenges
- RF systems engineering talent scarcity:Specialized expertise in millimeter-wave antenna calibration and electromagnetic simulation remains concentrated among a narrow cohort of experienced designers.
- Multi-vendor integration complexity:Open RAN deployments require sustained systems integration investment to harmonize radio units from different suppliers with common baseband processing pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Massive MIMO Market |
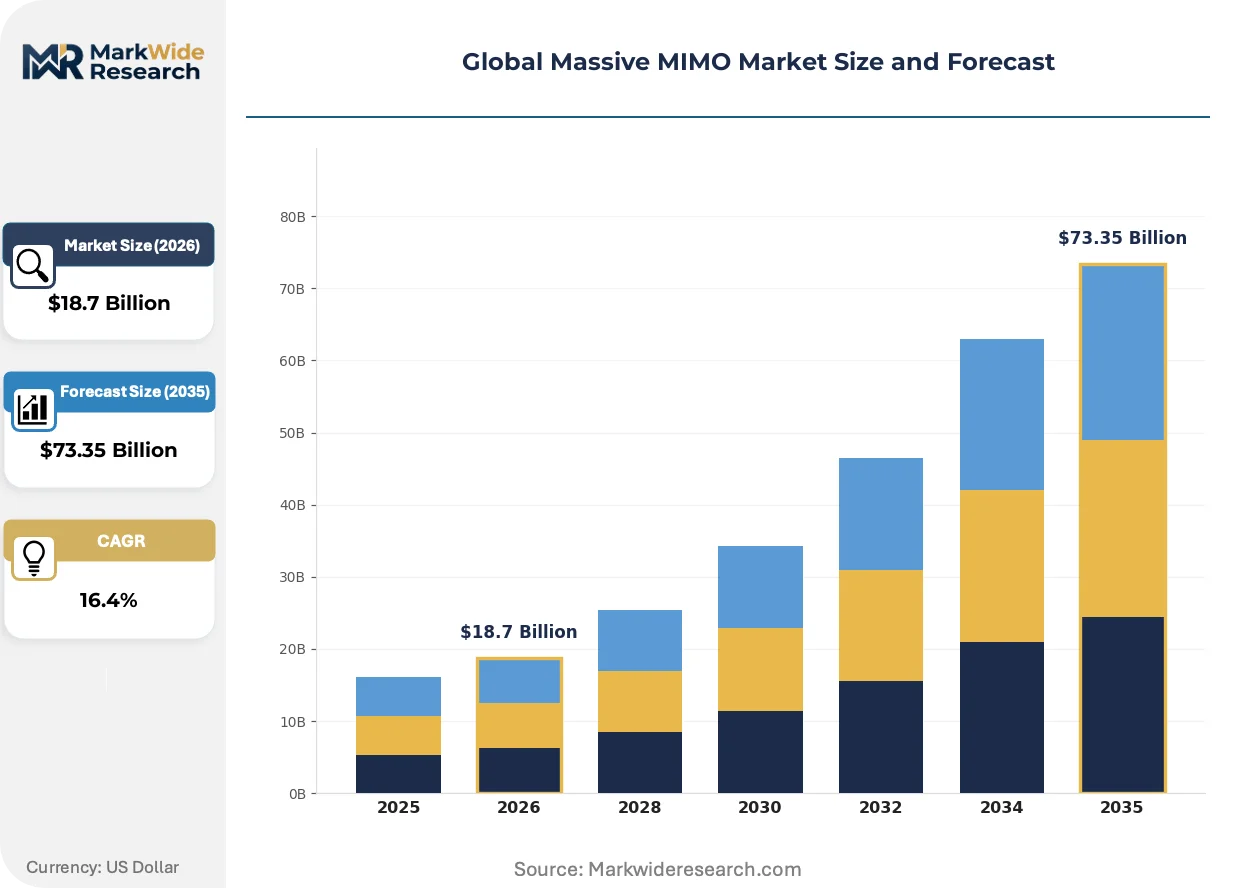
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Beamforming, Space Division Multiple Access, Orthogonal Frequency Division Multiplexing, Time Division Duplex Component: Transceivers, Antennas, Amplifiers, Processors Application: Telecommunications, Broadcasting, Internet of Things, Smart Cities End User: Mobile Network Operators, Enterprises, Government, Research Institutions |
| Companies Covered | Huawei Technologies Co., Ltd., Ericsson, Nokia Corporation, Qualcomm Technologies, Inc., ZTE Corporation, Samsung Electronics Co., Ltd., Airspan Networks, Cisco Systems, Inc., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Massive MIMO Market Strategic Shifts
Digital beamforming architectures are supplanting analog precoding approaches, compressing hardware complexity while expanding software-defined reconfiguration capabilities across sub-6 GHz and millimeter-wave bands.
Gallium nitride power amplifiers are displacing legacy LDMOS devices in massive MIMO radio heads, enabling higher output power density with reduced thermal footprint. Tier-1 operators in China and the United States are specifying GaN-based transceivers for new macro-cell tenders, forcing supply chain requalification among second-tier vendors. This displacement is compressing the addressable market for silicon-based RF power solutions in base station applications above 3.5 GHz.
The European Telecommunications Standards Institute's tightened electromagnetic exposure compliance testing is extending equipment certification timelines by four to six months for new antenna form factors. Manufacturers must now submit volumetric near-field measurement data across multiple operational modes, increasing pre-launch engineering overhead. High-gain massive MIMO panels with 192-element arrays face particular scrutiny under the revised EN 62232 assessment protocols.
Enterprise buyers are consolidating vendor relationships through framework agreements that bundle radio equipment with multi-year managed services contracts, displacing traditional capital-purchase procurement cycles. Mobile network operators in Japan and Australia are responding by unbundling hardware supply from installation and optimization services, creating separate commercial tracks for equipment-only and full-turnover contracts. This bifurcation is most visible in port automation and smart factory deployments where internal IT teams assume operational responsibility.
Global Massive MIMO Market Segmentation
Massive MIMO deployments fragment across multiple technical and commercial dimensions. Regulatory frameworks from the FCC, ETSI, and MIIT impose divergent certification requirements that reshape how each segment penetrates national markets.
Technology:
FCC Part 27 rules in the United States, ETSI EN 301 908 in Europe, and MIIT 5G NR specifications in China each mandate distinct beam management protocols that determine which technologies gain operator traction.
- Beamforming:Digital precoding architectures coordinate hundreds of antenna elements through baseband signal processing to generate steerable narrow beams. China Mobile and Verizon Communications specify 64T64R and 128T128R configurations for sub-6 GHz urban densification, prioritizing spectral efficiency gains over hardware simplicity.
- Time Division Duplex:Unpaired spectrum operation enables flexible uplink-downlink ratio configuration through software-defined frame structures. TRAI's mid-band allocations in India and Anatel's 3.5 GHz auctions in Brazil favor TDD deployments where asymmetric traffic patterns dominate, compressing equipment qualification cycles for vendors with proven tropical-climate thermal designs.
- Space Division Multiple Access:Spatial multiplexing layers multiple data streams onto identical time-frequency resources through precoding matrix optimization.
- Orthogonal Frequency Division Multiplexing:Subcarrier-based modulation underpins 5G NR physical layer waveforms with cyclic prefix configurations.
Beamforming handles the majority of throughput; Time Division Duplex is the fastest mover on share.
Component:
Supply concentration in gallium nitride substrates and RF semiconductor fabrication dictates which component categories capture margin expansion versus commoditization pressure.
- Transceivers:Integrated RF chains combining digital-to-analog conversion, upconversion, and power amplification in compact radio head enclosures. GaN-on-SiC power amplifier integration from Japanese and US substrate producers creates supply chokepoints for high-efficiency designs specified by China Telecom and T-Mobile US, forcing second-tier vendors into extended qualification timelines.
- Amplifiers:LDMOS-to-GaN displacement is compressing addressable markets for silicon-based solutions above 3.5 GHz while expanding thermal management engineering requirements.
- Antennas:Passive radiating element arrays with calibration networks for beam steering precision across azimuth and elevation planes.
- Processors:Baseband computation engines executing channel estimation, precoding, and scheduling algorithms in real time.
Transceivers concentrate the steepest margin expansion; Amplifiers are climbing the fastest on technology refresh cycles.
Application:
End-use demand bifurcates between macro-cell volume deployment and specialized vertical integration with divergent procurement modalities.
- Telecommunications:Macro-cell and small-cell base station installations serving consumer mobile broadband and fixed wireless access. Bharti Airtel and Deutsche Telekom drive procurement volumes through framework agreements bundling equipment with multi-year managed services, displacing traditional capital-purchase cycles.
- Smart Cities:Integrated sensor networks and video analytics requiring massive MIMO backhaul for high-density urban sensing. Seoul Metropolitan Government and Barcelona City Council specify dedicated cells for traffic management and public safety applications, creating procurement channels outside operator-centric sales organizations.
- Internet of Things:Massive machine-type communication overlays on 5G NR infrastructure for industrial sensor density.
- Broadcasting:Terrestrial television and radio transmission infrastructure leveraging 5G broadcast modes.
Telecommunications absorbs the dominant deployment volume; Smart Cities is expanding most quickly on municipal procurement autonomy.
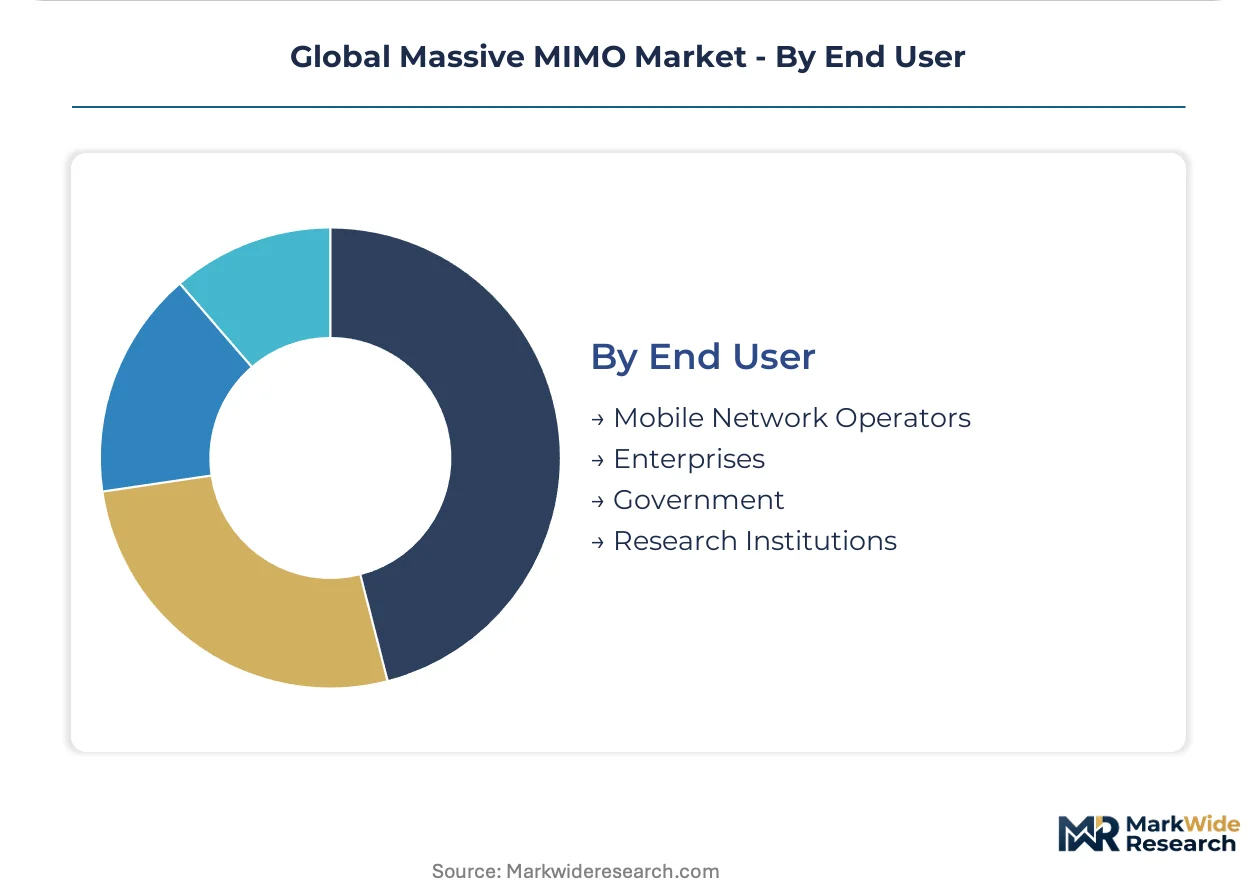
End User:
Procurement authority is fragmenting from centralized mobile network operators toward distributed enterprise and government buyers with distinct technical specifications.
- Mobile Network Operators:Traditional macro-cell deployers with spectrum licenses and national coverage obligations. Reliance Jio and Orange SA anchor equipment volumes through competitive tender processes, though unbundling of hardware supply from installation services is creating separate commercial tracks for equipment-only procurement.
- Enterprises:Manufacturing facilities, port authorities, and logistics hubs procuring private 5G networks for ultra-reliable low-latency applications. Hyundai Motor Company and Port of Rotterdam specify campus-scale massive MIMO deployments with internal IT teams assuming operational responsibility, bypassing operator-managed service models.
- Government:Defense, public safety, and universal service programs with subsidized rural coverage mandates.
- Research Institutions:Academic and national laboratory testbeds for air interface experimentation and standardization prototyping.
Mobile Network Operators retain the dominant procurement volume; Enterprises are gaining share fastest on private network autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese equipment exports dominate supply flows into Southeast Asian and Middle Eastern deployment programs, while European vendors capture upgrade cycles in legacy infrastructure markets. Trade corridors concentrate around turnkey project financing tied to national spectrum auction schedules.
China
China Mobile and China Telecom drive procurement volumes through centralized 5G densification programs in the Yangtze River Delta and Pearl River Delta. MIIT certification requirements for 64T64R and 128T128R configurations compress vendor qualification timelines. Shenzhen and Beijing host concentrated R&D clusters where domestic vendors refine GaN-on-SiC integration for tropical-climate deployments.
United States
Verizon Communications and T-Mobile US accelerate sub-6 GHz urban coverage expansion following FCC Part 27 mid-band auctions. The Federal Communications Commission mandates specific beam management protocols that reshape equipment interoperability testing. Texas and California anchor deployment clusters where operators trial AI-native air interface optimization ahead of 3GPP Release 18.
Germany
Deutsche Telekom and Vodafone Germany procure massive MIMO infrastructure for industrial private network deployments in Bavaria and North Rhine-Westphalia. ETSI EN 301 908 electromagnetic exposure compliance testing extends certification timelines for high-gain antenna arrays. The Port of Rotterdam corridor influences German port automation specifications for ultra-reliable low-latency campus networks.
India
Reliance Jio and Bharti Airtel scale 5G rollouts following TRAI mid-band spectrum allocations in Maharashtra and Karnataka. Universal service obligations subsidize equipment costs for rural coverage in sparse-population states. Delhi-NCR and Bangalore concentrate systems integration capabilities for multi-vendor Open RAN deployments.
Brazil
Claro and Vivo accelerate base station procurement after Anatel 3.5 GHz auctions in São Paulo and Rio de Janeiro metropolitan corridors. National telecom regulator mandates drive interoperability upgrades across macro-cell installations. The São Paulo industrial belt generates demand for manufacturing facility private networks with internal IT operational models.
Global Massive MIMO Market Competitive Environment
Player mix skews toward integrated equipment vendors with captive semiconductor fabrication and software-defined radio portfolios. Consolidation pressure concentrates among tier-1 suppliers capable of delivering turnkey baseband-to-antenna solutions. Two strategic archetypes dominate: full-stack integrators controlling thermal management and power amplifier supply chains, and specialist component suppliers focused on GaN substrate qualification. Competitive moves center on strategic partnerships for Open RAN interoperability and geographic expansion through project financing tied to national spectrum auctions.
Among Asia-Pacific-based integrated vendors, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify full-stack archetypes with turnkey deployment capabilities spanning baseband processing to radio head integration. Samsung Electronics Co., Ltd. anchors the specialist tier through captive semiconductor fabrication controlling cost structures for massive antenna arrays. Ericsson represents the European integrated model with concentrated R&D in intelligent beam management algorithms. These three companies occupy distinct competitive positions shaped by regulatory market access rather than interchangeable product substitution.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Ericsson |
| Nokia Corporation |
| Qualcomm Technologies, Inc. |
| ZTE Corporation |
| Samsung Electronics Co., Ltd. |
| Airspan Networks |
| Cisco Systems, Inc. |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
GaN-on-SiC power amplifier substitution for legacy LDMOS devices is simultaneously relocating fabrication gravity toward Japanese and US substrate producers while compressing margin structures for silicon-dependent vendors across Asia-Pacific procurement markets. This materials transition feeds directly into equipment qualification timelines and tender pricing dynamics as operators specify thermal efficiency thresholds.
Pricing Analysis
128T128R configuration premiums over 64T64R and 32T32R legacy tiers reflect thermal management complexity and gallium nitride integration costs rather than raw element count. Three-tier pricing structure across premium, standard, and economy levels separates turnkey deployment bundles from equipment-only procurement and managed service overlays. Pricing pressure stems from Open RAN interoperability mandates forcing multi-vendor integration investments without commensurate hardware margin expansion. Mobile network operators exhibit highest price sensitivity through competitive tender processes, while enterprise private network buyers absorb premium positioning for campus autonomy.
Supply Chain Analysis
Inbound logistics costs through congested Asian port corridors and constrained container availability on transpacific trade lanes are amplifying lead time variability for radio head deliveries into North American deployment schedules. Fabrication concentrates in China, Japan, and the United States for baseband processing, RF semiconductor, and antenna calibration subsystems respectively. Critical dependencies include gallium nitride substrates, silicon carbide wafers, and precision electromagnetic simulation software. Single-source vulnerability around Japanese GaN-on-SiC wafer supply creates chokepoints for high-efficiency power amplifier qualification. Distribution runs through operator framework agreements, direct enterprise procurement, and systems integrator channels with diverging service-attach expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors are capturing expanding recurring revenue from multi-year managed services contracts attached to campus deployments, with service layers growing faster than underlying hardware sales across private 5G procurement markets.
For Market Incumbents: Consolidate control over thermal management and GaN power amplifier supply chains through backward integration or captive qualification partnerships, defending against margin compression from Open RAN disaggregation. Prioritize R&D investment in AI-native beam tracking algorithms ahead of 3GPP Release 18 standardization to maintain proprietary stack advantages where operator procurement criteria still permit. Lock in framework agreements with China Mobile and Verizon Communications that bundle installation and optimization services, creating switching costs for hardware-only competitors. For New Entrants and Emerging Players: ETSI EN 301 908 certification fast-tracks for high-gain antenna arrays offer entry pathways into European industrial private network deployments where electromagnetic exposure compliance extends timelines for established vendors. Target manufacturing facility and port authority segments in Germany and South Korea with campus-scale deployments using lower-order MIMO configurations that bypass macro-cell qualification barriers. Pursue systems integrator partnerships rather than direct operator sales to amortize multi-vendor integration overhead across project portfolios. For Investors and Strategic Acquirers: The market sits at a standardization-transition phase that favors R&D-heavy vendors with proven AI-native air interface development capabilities and established regulatory qualification track records. Long-term viability over the next decade rests on positioning for machine learning-driven spectral efficiency gains rather than hardware volume scale. Monitor 3GPP Release 18 timeline commitments against internal R&D spend ratios as the inflection signal for vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Integration Partnership | Secures substrate supply from Japanese producers for high-efficiency power amplifier fabrication. |
| AI-Native Beam Tracking Development | Positions portfolio for 3GPP Release 18 machine learning specifications in urban corridors. |
| Private Campus Network Framework Agreement | Captures manufacturing facility demand in Germany's Bavaria industrial belt. |
| Open RAN Interoperability Certification | Unlocks Deutsche Telekom and Bharti Airtel multi-vendor procurement channels. |
| Thermal Management Retrofit Service Launch | Addresses 128T128R cooling limits in tropical climates for Brazil and India deployments. |
Study Parameters
A standing panel of baseband engineering directors, RF systems architects, mobile network operator procurement leads, and private 5G deployment project managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with equipment vendor technical leads and operator network planning executives, validated against secondary sources including FCC equipment authorization databases, ETSI harmonized standards publications, 3GPP technical specification releases, and national spectrum auction disclosures from Anatel and TRAI. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations across technology, component, and application segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning beamforming architecture generations, transceiver integration tiers, telecommunications versus vertical application splits, and mobile network operator versus enterprise procurement modalities. CAGRs derived from logistic diffusion curves fitted to historical deployment trajectories, adjusted for spectrum auction schedules and regulatory certification timeline assumptions specific to massive MIMO equipment qualification.
Decision-makers should treat outputs as directional under assumptions of sustained 3GPP standardization momentum and stable gallium nitride substrate supply; material deviation in either factor would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Wigig Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
APAC Small Cell 5G Market