
 North America Data Virtualization Market | 2026-2036
North America Data Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Virtualization Market Insights
Healthcare organizations is hardening as the fastest-expanding end-use vertical for data virtualization platforms across North America. IBM Corporation leverages its hybrid cloud architecture to anchor enterprise deployments in regulated industries requiring strict data sovereignty. Oracle Corporation sustains competitive pressure through specialized database virtualization layers that integrate with legacy on-premise systems. Denodo differentiates via dedicated logical data fabric technology that dominates financial services implementations in major metropolitan hubs.
Data virtualization constitutes a middleware layer that abstracts physical data storage locations through real-time query federation, enabling unified access across distributed databases, cloud warehouses, and streaming sources without replication or movement. The technology employs semantic modeling, query optimization engines, and caching mechanisms to deliver sub-second response times for analytical workloads while preserving source system performance. Cloud deployment models are capturing the fastest expansion as enterprises migrate from capital-intensive on-premise infrastructure to consumption-based architectures, though hybrid configurations retain the largest margin pools due to complexity premiums. Data integration solutions lead solution type demand as organizations confront fragmented data estates spanning decades of technical debt, while data governance modules are gaining traction amid tightening compliance requirements.
FedRAMP authorization frameworks in the United States and Canada's Protected B security classification under Treasury Board standards shape procurement criteria for government and regulated industry buyers. The US Securities and Exchange Commission's cybersecurity disclosure rules and Canada's OPC guidance on cross-border data transfers further constrain architecture decisions for financial services deployments. Stakeholders must evaluate vendor roadmaps for AI-augmented query optimization and automated metadata management as these capabilities determine long-term platform stickiness and total cost of ownership trajectories.
Market Dynamics
FedRAMP authorization mandates are compressing procurement cycles for cloud-native data virtualization platforms across United States federal agencies and defense contractors, forcing legacy on-premise vendors to accelerate hybrid architecture roadmaps or face disqualification from contract pools.
Growth Catalysts
- FedRAMP Moderate/High authorization:United States federal cloud migration policies require FedRAMP-authorized data virtualization layers for cross-agency data sharing, creating captive demand from defense and civilian agencies.
- Healthcare data interoperability:HIPAA-compliant logical data fabrics enable real-time patient record federation across hospital networks without physical data movement, accelerating clinical analytics deployments.
- Real-time query federation:Semantic modeling engines with sub-second response capabilities are displacing traditional ETL pipelines for operational analytics in capital markets trading floors.
Market Restraints
- Specialized talent scarcity:Shortage of data architects proficient in logical data modeling and distributed query optimization constrains enterprise deployment velocity.
- Hybrid complexity premiums:Dual on-premise and cloud infrastructure maintenance creates persistent operational overhead versus pure-cloud alternatives.
- Canada's Protected B classification:Treasury Board security standards limit cross-border data virtualization deployments between Canadian federal systems and US cloud regions.
Strategic Opportunities
- AI-augmented query optimization:Automated metadata management and machine learning-driven performance tuning are converging with data virtualization platforms to reduce total cost of ownership.
- Mid-market financial services:Regional banks and credit unions in the United States Southeast represent underpenetrated demand for cloud-native logical data fabrics.
- SEC cybersecurity disclosure rules:Mandated incident reporting requirements are compelling financial institutions to deploy unified data access layers for audit trail consolidation.
Industry Challenges
- Legacy system integration friction:Mainframe and COBOL-based core banking systems resist seamless semantic layer abstraction, requiring costly custom adapter development.
- Cross-border data sovereignty:OPC guidance on transnational data transfers creates architectural complexity for Canadian financial services firms operating US subsidiaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Virtualization Market |
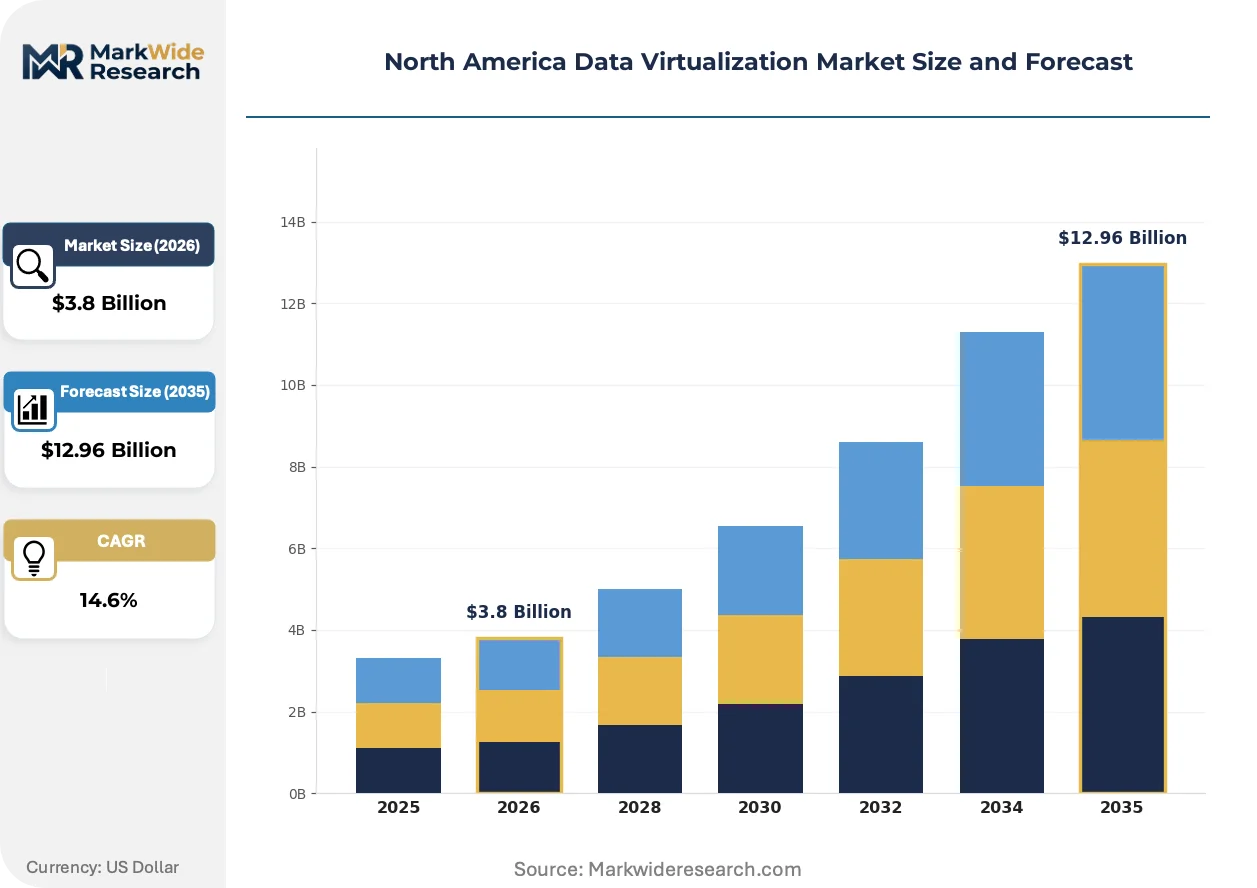
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud, Hybrid, Multi-Cloud Solution Type: Data Integration, Data Management, Data Governance, Data Analytics End User: Healthcare Organizations, Financial Institutions, Retail Businesses, Educational Institutions Service Type: Consulting, Implementation, Support & Maintenance, Training |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, Cisco Systems, Dell Technologies, SAP SE, Informatica, Denodo, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Virtualization Market Trends and Innovations
Logical data fabric architectures are displacing traditional data warehousing approaches as enterprises prioritize real-time analytics over batch consolidation, with semantic modeling and automated data discovery emerging as the critical differentiators in platform selection.
Automated metadata management is integrating machine learning classification with data virtualization query engines to enable self-optimizing performance tuning. Healthcare organizations in the United States Northeast are deploying these capabilities to federate electronic health records across multi-hospital networks without replication overhead. The technology is integrating predictive caching algorithms that pre-position frequently accessed datasets, compressing analytical latency from minutes to sub-second response times.
Canada's OPC guidance on cross-border data transfers is tightening architectural constraints for financial services firms operating dual-country infrastructure. The regulation requires explicit consent mechanisms and data residency controls that complicate unified logical data layer deployments spanning Toronto and New York operations. Canadian banks are responding by segmenting virtualization architectures into sovereign data zones with explicit jurisdictional boundaries.
Consumption-based pricing models are displacing perpetual license structures as cloud-native platforms capture preference among capital-constrained mid-market buyers. United States regional banks and healthcare networks are migrating from upfront capital expenditure to operational expenditure frameworks that scale with query volume. The shift is most visible in the Southeast United States, where smaller financial institutions lack dedicated infrastructure teams to manage on-premise virtualization clusters.
North America Data Virtualization Market Segmentation
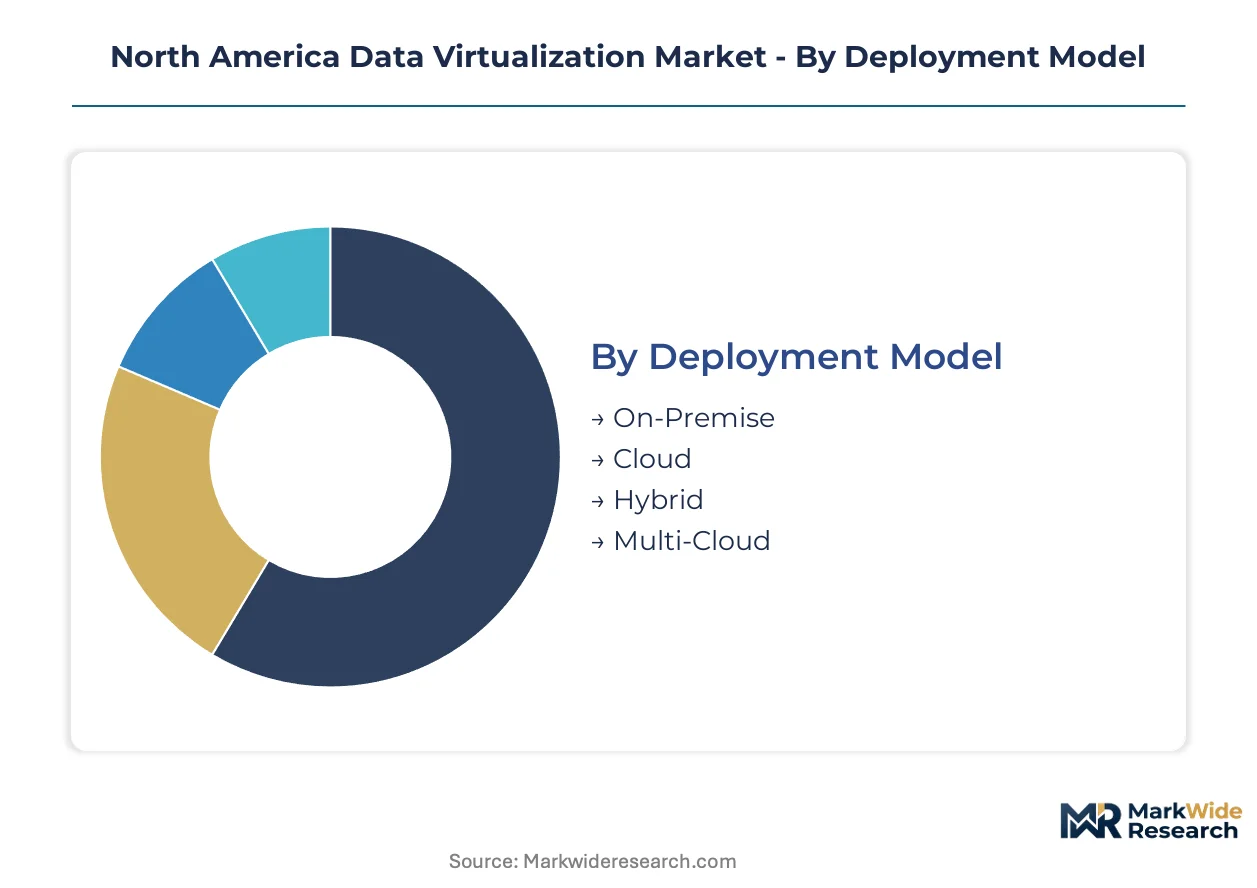
Data virtualization architectures fragment across deployment topologies, functional modules, and service wrappers that determine integration depth with existing enterprise stacks. Each segmentation axis reveals distinct margin structures and capability requirements that shape vendor positioning across North American regulated industries.
Deployment Model:
Standalone virtualization layers operate independently of broader data platforms, while embedded deployments integrate within cloud data warehouses or analytics suites as native query federation engines.
- On-Premise:Dedicated hardware clusters running virtualization middleware within enterprise data centers, typically deployed for HIPAA-compliant healthcare networks requiring physical data residency. Demand concentrates in Boston and New York hospital systems confronting strict patient data sovereignty requirements under state-level privacy statutes.
- Cloud:Fully managed service instances hosted in FedRAMP-authorized regions, eliminating capital expenditure for infrastructure. United States federal agencies and defense contractors in the Washington DC corridor are compressing procurement cycles around these offerings to satisfy cross-agency data sharing mandates.
- Hybrid:Split architectures maintaining sensitive workloads on-premise while bursting analytical queries to cloud resources. Canadian financial institutions leverage this pattern to satisfy Treasury Board Protected B classification while accessing US-based market data.
- Multi-Cloud:Abstraction layers spanning AWS, Azure, and GCP simultaneously to prevent vendor lock-in. Regional banks in the US Southeast are adopting these configurations to negotiate pricing leverage across competing hyperscalers.
Volume placements concentrate in Hybrid; the faster expansion belongs to Cloud.
Solution Type:
Functional modules range from foundational connectivity engines to governance overlays that embed policy enforcement directly within query paths.
- Data Integration:Core federation engines executing real-time query decomposition across distributed sources. Financial services clusters in Manhattan and Chicago deploy these layers to unify trading data across legacy mainframe and modern cloud warehouse estates without replication overhead.
- Data Governance:Policy enforcement modules embedding data quality rules, lineage tracking, and access controls within the virtualization layer. HIPAA-covered entities in the US Northeast are prioritizing these capabilities to automate compliance documentation for OCR audits.
- Data Management:Metadata catalogs and semantic modeling tools that standardize business definitions across technical schemas. Canadian healthcare networks use these to federate provincial health records while maintaining jurisdictional data boundaries.
- Data Analytics:Embedded visualization and exploration interfaces consuming virtualized datasets directly. Retail businesses in California and Texas are deploying these for customer 360 initiatives spanning e-commerce and brick-and-mortar transaction streams.
Revenue concentration sits with Data Integration; Data Governance is climbing the fastest amid tightening SEC cybersecurity disclosure requirements.
End User:
Adoption intensity varies sharply by sector regulatory burden and data fragmentation complexity.
- Healthcare Organizations:Multi-hospital networks federating electronic health records across acquired facilities without costly data migration. The US Northeast corridor from Boston to Philadelphia represents the densest concentration of deployments.
- Financial Institutions:Capital markets firms and retail banks unifying decades of technical debt across core banking, trading, and risk systems. FedRAMP authorization requirements are forcing infrastructure modernization across US federal credit unions and defense sector lenders.
- Retail Businesses:Omnichannel merchants consolidating point-of-sale, e-commerce, and supply chain data for real-time inventory optimization.
- Educational Institutions:University systems and research consortia sharing sensitive datasets across institutional boundaries while preserving IRB compliance.
Financial Institutions command the largest contract values; Healthcare Organizations are gaining share fastest as interoperability mandates accelerate.
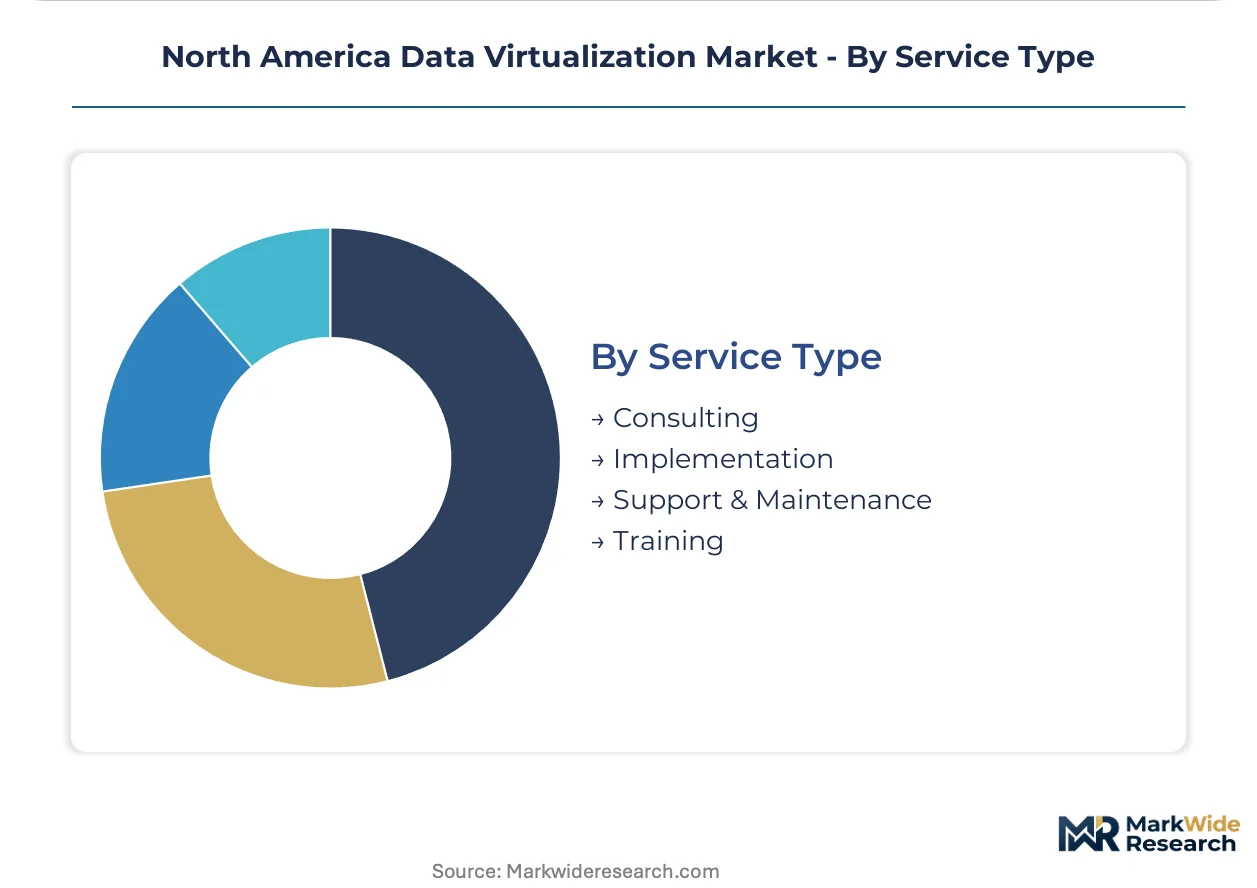
Service Type:
Professional services wrap technology deployments with specialized expertise in logical data modeling and distributed query optimization.
- Consulting:Architecture design and data strategy engagements defining semantic models and source system integration patterns. Boutique firms in New York and Toronto dominate financial services advisory for cross-border data sovereignty challenges.
- Implementation:Technical deployment services configuring adapters, optimizing query performance, and establishing caching policies. Scarcity of architects proficient in logical data modeling is constraining delivery capacity across North American systems integrators.
- Support & Maintenance:Ongoing operational assistance including patch management, performance tuning, and incident response. Subscription structures are displacing time-and-material arrangements as platforms shift to consumption-based pricing.
- Training:Certification programs and knowledge transfer for customer data engineering teams. Canadian federal agencies are mandating these investments to build internal capability for Protected B-compliant operations.
Implementation services capture the highest hourly rates; Support & Maintenance contracts are expanding most quickly as installed bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Massachusetts and New York City accelerate data virtualization clustering through state tax credits for enterprise software R&D facilities. Federal cloud migration mandates under FedRAMP authorization requirements compress procurement cycles across defense and civilian agencies.
United States
Financial services clusters in Manhattan and Chicago deploy logical data fabrics to unify trading data across legacy mainframe and cloud warehouse estates. SEC cybersecurity disclosure rules compel audit trail consolidation through unified data access layers. The US Northeast corridor from Boston to Philadelphia hosts the densest concentration of HIPAA-compliant healthcare network deployments.
Canada
Treasury Board Protected B classification standards limit cross-border data virtualization between federal systems and US cloud regions. Canadian banks segment architectures into sovereign data zones with explicit jurisdictional boundaries. Toronto and Vancouver financial centers drive hybrid deployment patterns to satisfy residency controls while accessing market data.
Mexico
Banxico regulatory guidance on financial data localization creates demand for on-premise virtualization layers among retail banks and credit unions. Manufacturing supply chains in Nuevo León and Jalisco deploy logical data fabrics to unify ERP systems across maquiladora operations. Mexico City financial institutions accelerate compliance modernization ahead of anticipated data protection framework updates.
North America Data Virtualization Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors and database incumbents commanding premium positions in regulated industries while cloud-native challengers capture mid-market expansion. The vendor landscape organizes into three tiers: legacy infrastructure conglomerates with hybrid cloud portfolios, specialized logical data fabric pure-plays, and hyperscaler-integrated platform extensions. Dominant competitive moves center on FedRAMP authorization acceleration and AI-augmented query optimization roadmap investments.
Within the enterprise infrastructure tier, IBM Corporation and Oracle Corporation exemplify archetypal positioning through hybrid architecture anchoring and legacy system integration specialization respectively. Denodo occupies a distinct pure-play position representing dedicated logical data fabric technology. Microsoft Corporation anchors the hyperscaler-integrated vector through native query federation capabilities embedded within cloud data platforms.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| Cisco Systems |
| Dell Technologies |
| SAP SE |
| Informatica |
| Denodo |
| Salesforce |
| Others |
Pricing and Supply Chain Analysis
FedRAMP-authorized federal agencies and defense contractors concentrate procurement power, anchoring the market to consumption-based SaaS pricing that scales with query volume rather than perpetual licensing. This buyer archetype's mandate-driven demand compresses sales cycles while forcing legacy vendors toward hybrid subscription models.
Pricing Analysis
Short lead-time deployments command premium pricing as federal procurement officers prioritize FedRAMP-authorized platforms with immediate availability over extended implementation timelines. The dominant pricing structure stratifies across premium, standard, and economy tiers tied to query throughput and governance module depth. Price differentiation hinges on HIPAA certification grade and FedRAMP authorization level, with Moderate baseline separating from High baseline offerings. Cost compression in the mid-market tier is intensifying because regional banks negotiate volume discounts against multi-cloud alternatives. Healthcare networks in the US Northeast exhibit highest price sensitivity due to constrained capital budgets, while defense contractors show least sensitivity given mission-critical requirements.
Supply Chain Analysis
Regional distribution centers in Northern Virginia and Dallas-Fort Worth anchor hub-and-spoke delivery patterns for cloud-native virtualization platforms, minimizing latency for federal and financial services clients. Geographic supply concentration centers on the United States for hyperscaler infrastructure, Canada for sovereign data zone compliance hardware, and Ireland for EU data residency gateway components. Raw material dependencies draw from specialized semiconductors for query optimization engines, enterprise-grade storage arrays for caching layers, and cryptographic modules for FedRAMP boundary protection. Single-source vulnerability in FedRAMP-authorized cloud regions creates structural risk for cross-agency deployments. Distribution runs through certified systems integrators with cleared personnel for defense sector implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America data virtualization market functions as a cost-of-compliance story where FedRAMP authorization creates a barrier-to-entry moat that rewards pre-certified incumbents with captive federal demand.
For Market Incumbents: Cement FedRAMP High authorization as a competitive fortress by accelerating AI-augmented query optimization roadmaps before challengers close the capability gap. Invest in cleared personnel pipelines within the Washington DC corridor to defend against emerging cloud-native entrants targeting defense contractor adjacencies. Prioritize backward integration into automated metadata management to reduce customer total cost of ownership and deepen platform stickiness. For New Entrants and Emerging Players: HIPAA interoperability mandates in the United States open a window for specialized logical data fabric offerings targeting mid-market hospital networks in the Southeast. Penetrate regional banks and credit unions in Texas and Florida through consumption-based pricing that eliminates upfront capital barriers. Pursue channel partnerships with boutique consulting firms in Toronto to navigate Canadian Protected B compliance requirements without direct regulatory investment. For Investors and Strategic Acquirers: The window for entry favors pure-play logical data fabric specialists with established healthcare or financial services vertical penetration. Acquisition targets should demonstrate automated metadata management capabilities and FedRAMP Moderate baseline authorization as minimum viable positioning. Watch for inflection when AI-augmented query optimization becomes table stakes rather than differentiator, compressing margin pools for laggards.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Captures captive federal demand under cross-agency data sharing mandates. |
| AI-Augmented Query Optimization | Reduces latency from minutes to sub-second response for trading floor workloads. |
| Healthcare Interoperability Partnership | Enables HIPAA-compliant EHR federation across multi-hospital networks. |
| Multi-Cloud Architecture Expansion | Prevents vendor lock-in while negotiating pricing leverage across hyperscalers. |
| Canadian Sovereign Data Zone Development | Satisfies Treasury Board Protected B classification for Toronto financial centers. |
Research Methodology
Multi-period observation of FedRAMP authorization timelines, HIPAA audit patterns, and cloud migration capex disclosures anchored the trend analysis, supplemented by interviews with CTOs at regional banks, IT procurement officers at hospital networks, platform engineers at systems integrators, and compliance leads at defense contractors. Secondary validation drew from SEC cybersecurity disclosure filings, Treasury Board procurement bulletins, CMS Medicare interoperability reports, and hyperscaler infrastructure expansion announcements. Bottom-up deployment tracking across metropolitan clusters triangulated against top-down vendor revenue segmentation.
Input-output matrices modeled deployment model transitions, solution type adoption curves, and end-use vertical penetration across the projection horizon. Segmentation dimensions included on-premise versus cloud-native topology, data integration versus governance functional emphasis, and financial services versus healthcare regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating FedRAMP mandate acceleration and HIPAA interoperability deadline effects. Forecast inputs incorporated query volume scaling patterns and consumption-based pricing conversion rates.
Caveats apply where FedRAMP authorization delays, HIPAA enforcement variability, or hyperscaler capacity constraints could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Fuel Management Software Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
System Integrator Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Global Web Push Notification Software Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
South Korea Cloud OSS BSS Market
Digital Solutions
Platform Architecture Market
Digital Solutions
Parking Management Systems Market