
 Near Field Communication Market | 2026-2036
Near Field Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Near Field Communication Market Outlook
EMVCo certification is shifting the cost-of-entry calculus for terminal manufacturers seeking retail deployment. NXP Semiconductors leverages its secure element portfolio to anchor premium payment terminal supply chains. Broadcom sustains dominance in smartphone NFC controller integration through foundry partnerships and IP depth. STMicroelectronics specializes in automotive-qualified NFC for vehicle access, a segment with distinct qualification barriers.
Near Field Communication denotes short-range wireless technology operating at 13.56 MHz, enabling data exchange between devices separated by up to 10 centimeters through inductive coupling between loop antennas. The technology powers contactless transactions, device pairing, and physical access verification across consumer and enterprise contexts. Payment terminals command the largest revenue pool among product types, though wearables represent the fastest-expanding installation base as smartwatches embed transit credentials. Mobile payments generate the highest transaction volume among applications, while access control delivers superior margins due to enterprise security requirements and recurring credential management.
The NFC Forum governs interoperability protocols, while ISO/IEC 14443 and ISO/IEC 18092 define physical and data-link layer specifications that hardware must satisfy for cross-vendor compatibility. The European Commission's Digital Identity Wallet framework and the US NIST guidelines for contactless authentication are elevating security requirements for government-adjacent deployments. Stakeholders must monitor whether regional digital identity mandates fragment certification pathways or converge toward unified standards.
Market Dynamics
EMVCo certification mandates are compressing hardware margins while concentrating procurement among vendors with pre-certified secure element portfolios, fundamentally restructuring terminal manufacturing economics.
Growth Catalysts
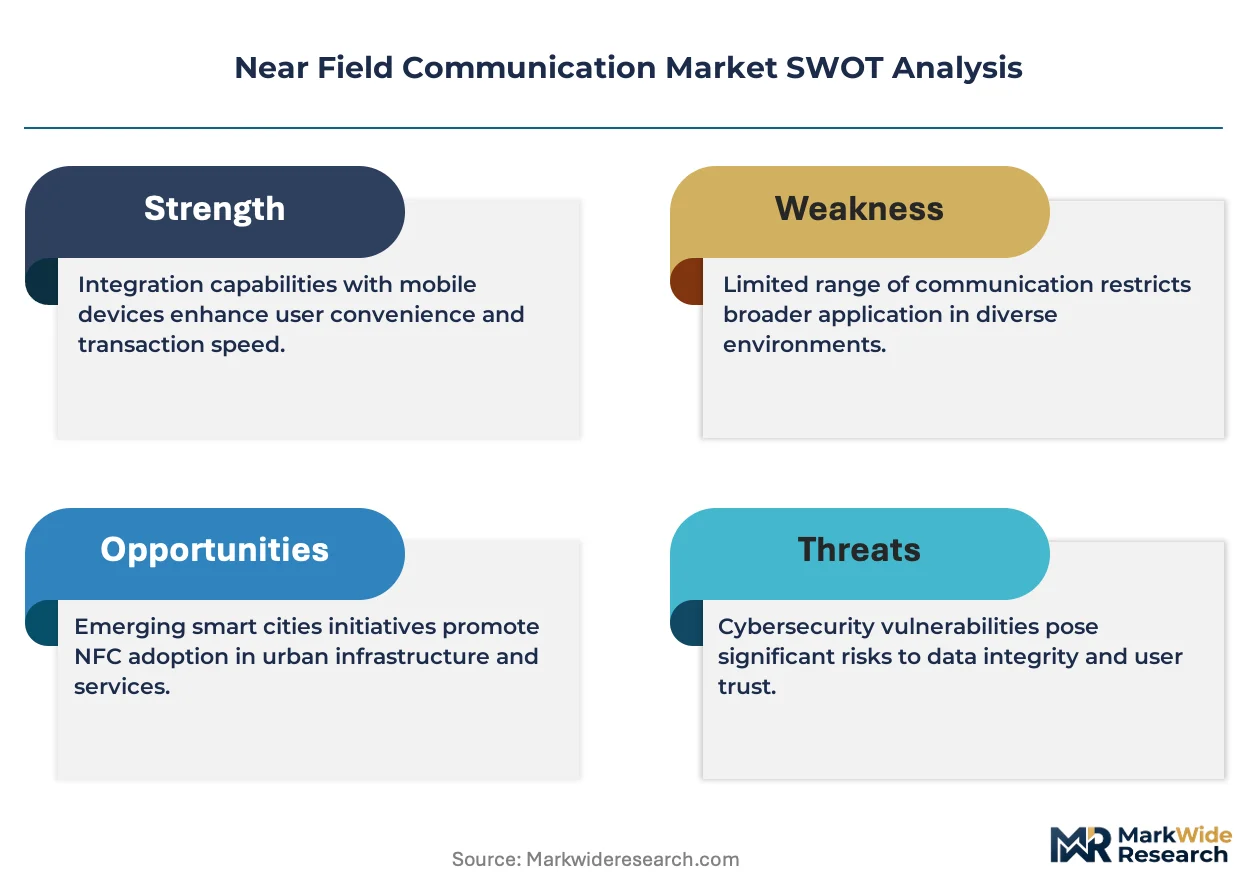
- EMVCo compliance deadlines:European and North American retail terminal refresh cycles are accelerating replacement demand as legacy magnetic stripe infrastructure phases out.
- Mobile wallet infrastructure:China UnionPay and commercial bank digital credential issuance is driving antenna and controller procurement at manufacturing scale.
- Automotive digital key adoption:Vehicle OEMs are embedding NFC for passive entry, creating qualified chip demand distinct from consumer electronics specifications.
Market Restraints
- Silicon supply concentration:Advanced secure element foundry capacity concentrates among Taiwan and South Korea facilities, exposing procurement to geopolitical disruption.
- Certification cost escalation:EMVCo and PCI PTS testing timelines extend hardware development cycles by 8-14 months for new terminal entrants.
- Ultra-wideband substitution:Apple's UWB deployment in vehicle access and spatial awareness applications threatens NFC's position in premium device pairing.
Strategic Opportunities
- India digital payment infrastructure:NPCI's RuPay contactless expansion and UPI offline protocols are creating greenfield terminal deployment opportunities.
- Healthcare credential convergence:NIST SP 800-63 digital identity guidelines are opening federal-adjacent access control contracts requiring multi-factor authentication hardware.
- NFC-Bluetooth Low Energy hybrid architectures:Wearable manufacturers are combining protocols for extended-range device provisioning without sacrificing security.
Industry Challenges
- RF engineering talent scarcity:Antenna design for metal-rich environments and interference mitigation requires specialized electromagnetic simulation expertise concentrated among semiconductor vendors.
- Legacy system integration friction:Enterprise access control retrofits demand middleware development to bridge proprietary Wiegand and OSDP protocols with modern credential formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near Field Communication Market |
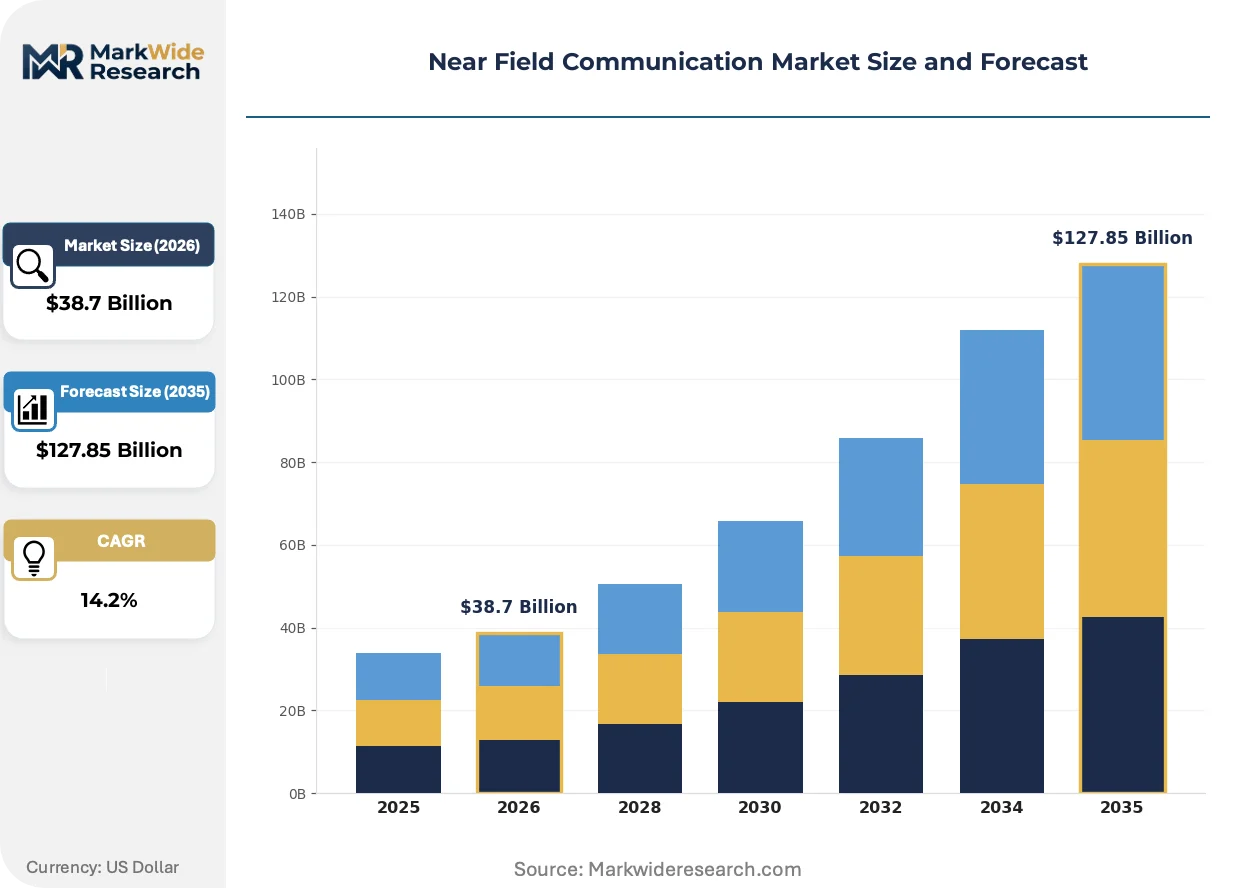
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Wearables, Payment Terminals, Tags End User: Retail, Transportation, Healthcare, Hospitality Application: Mobile Payments, Data Transfer, Access Control, Ticketing Technology: NFC Forum, ISO/IEC Standards, Proprietary Solutions, Contactless |
| Companies Covered | NXP Semiconductors, Broadcom, STMicroelectronics, Qualcomm Technologies, Texas Instruments, Infineon Technologies, Samsung Electronics, Sony Corporation, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near Field Communication Market Strategic Shifts
Secure element integration is migrating from discrete chips to embedded solutions within application processors, compressing bill-of-materials complexity while elevating software security requirements.
Embedded secure elements are expanding into mid-tier smartphones as MediaTek and Qualcomm integrate certified enclaves directly into SoC designs. Tier-two OEMs in Southeast Asia and Latin America are adopting these consolidated architectures to bypass discrete component procurement. This integration is expanding into payment terminal chipsets, where NXP and Samsung are combining controller and secure element functions to reduce PCB footprint and power draw.
REACH substance restrictions and RoHS recast directives in Europe are forcing antenna substrate material transitions away from halogenated flame retardants. Manufacturers are qualifying ceramic-filled hydrocarbon laminates and liquid crystal polymer alternatives that maintain 13.56 MHz impedance matching. Module suppliers serving German automotive OEMs are bearing the steepest qualification burdens, with material change notifications triggering KBA vehicle type approval reviews.
Transit agencies are unbundling closed-loop card issuance from fare collection infrastructure, opening procurement to credential-agnostic readers. Transport for London's cEMV acceptance and Tokyo Metro's mobile Suica expansion are shifting capital expenditure toward software-defined payment acceptance. This unbundling is most advanced in East Asian megacities, where private sector wallet providers now underwrite terminal deployment in exchange for transaction data access.
Near Field Communication Market Segmentation
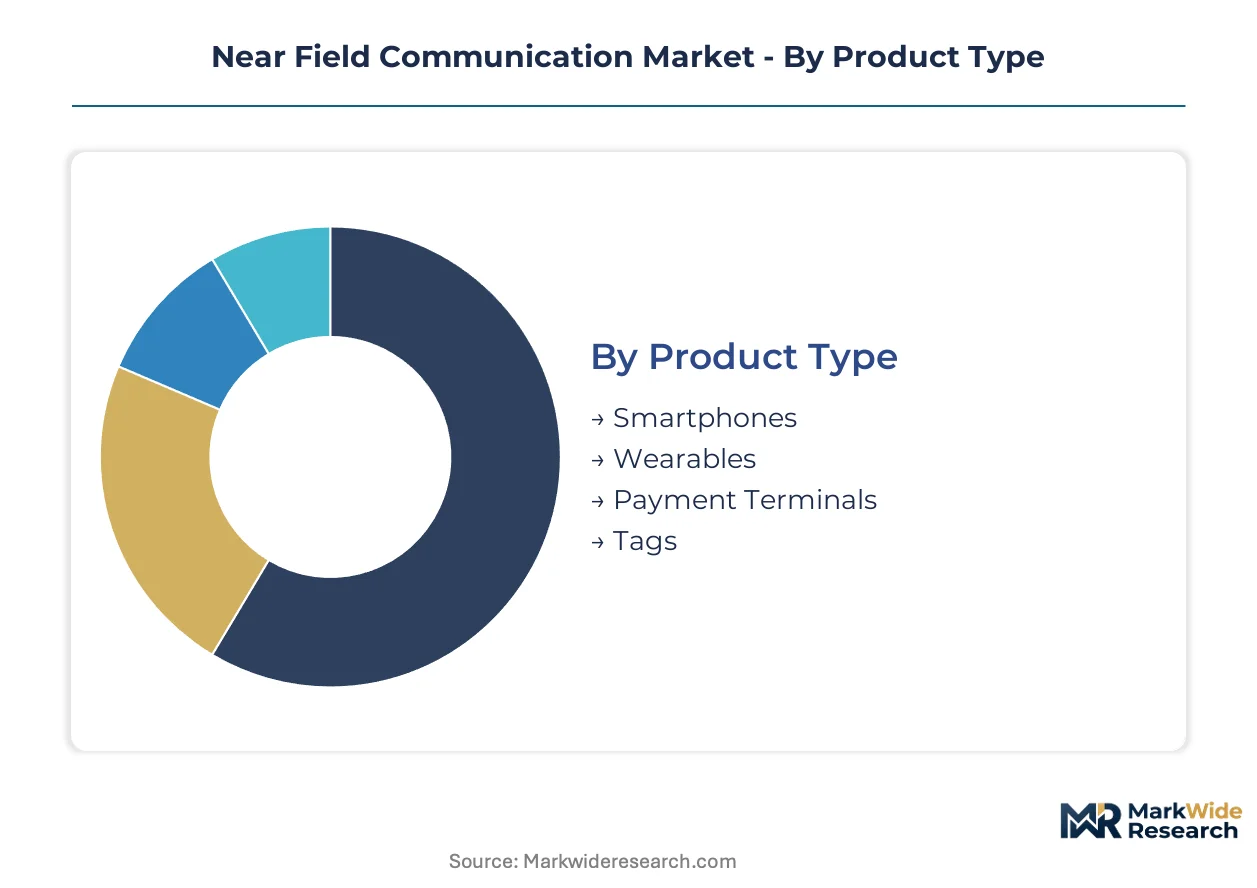
NFC market segmentation reveals divergent certification burdens across hardware categories. Terminal manufacturers face EMVCo and PCI PTS compliance, while smartphone integration demands NFC Forum interoperability validation.
Product Type:
Certification requirements fragment sharply across this category, with payment terminals bearing the heaviest EMVCo and PCI PTS testing loads while tags face minimal regulatory overhead.
- Payment Terminals:EMVCo Level 1 and Level 2 certification mandates 8-14 month validation cycles for hardware-software integration. European and North American merchant refresh cycles concentrate procurement among NXP Semiconductors and Ingenico supply chains as legacy magnetic stripe infrastructure phases out.
- Smartphones:NFC Forum Device Requirements and GSMA NFC Handset specifications govern interoperability. China UnionPay certification adds a secondary approval layer for domestic market access, driving antenna controller procurement at manufacturing scale in Shenzhen and Dongguan manufacturing clusters.
- Wearables:Compact antenna design for metal-rich enclosures demands specialized electromagnetic simulation expertise.
- Tags:ISO/IEC 14443 Type A/B compliance suffices for most deployments; passive designs avoid active certification burdens.
Payment terminals sit at the top of the volume ranking, with wearables climbing the fastest.
End User:
Customer procurement patterns separate into high-frequency transaction environments versus security-critical credential management contexts.
- Retail:Merchant acquirers mandate PCI PTS 6.x compliance for countertop and mobile point-of-sale terminals. EMVCo certification deadlines in Germany, France, and the United States are accelerating terminal replacement demand as contactless transaction thresholds rise.
- Transportation:Transit agencies unbundle closed-loop card issuance from fare collection infrastructure. Transport for London and Tokyo Metro are shifting capital expenditure toward software-defined payment acceptance, with private sector wallet providers underwriting terminal deployment.
- Healthcare:NIST SP 800-63 digital identity guidelines are opening federal-adjacent access control contracts requiring multi-factor authentication hardware.
- Hospitality:Property management system integration demands middleware development for credential provisioning.
Retail dominates transaction throughput, with transportation expanding most quickly.
Application:
Revenue models diverge between transaction-fee-based mobile payments and recurring-license access control deployments.
- Mobile Payments:Tokenized credential issuance through Apple Pay, Google Pay, and Samsung Pay generates the highest transaction volume. China UnionPay and commercial bank digital credential issuance is driving controller and secure element procurement at manufacturing scale.
- Access Control:Enterprise security requirements and recurring credential management deliver superior margins. NIST guidelines for contactless authentication are elevating security requirements for government-adjacent deployments in the United States.
- Data Transfer:Bluetooth Low Energy hybrid architectures are displacing pure NFC for extended-range device provisioning.
- Ticketing:Transit agency unbundling is opening procurement to credential-agnostic readers across East Asian megacities.
Mobile payments command the largest revenue pool, with access control gaining share fastest.
Technology:
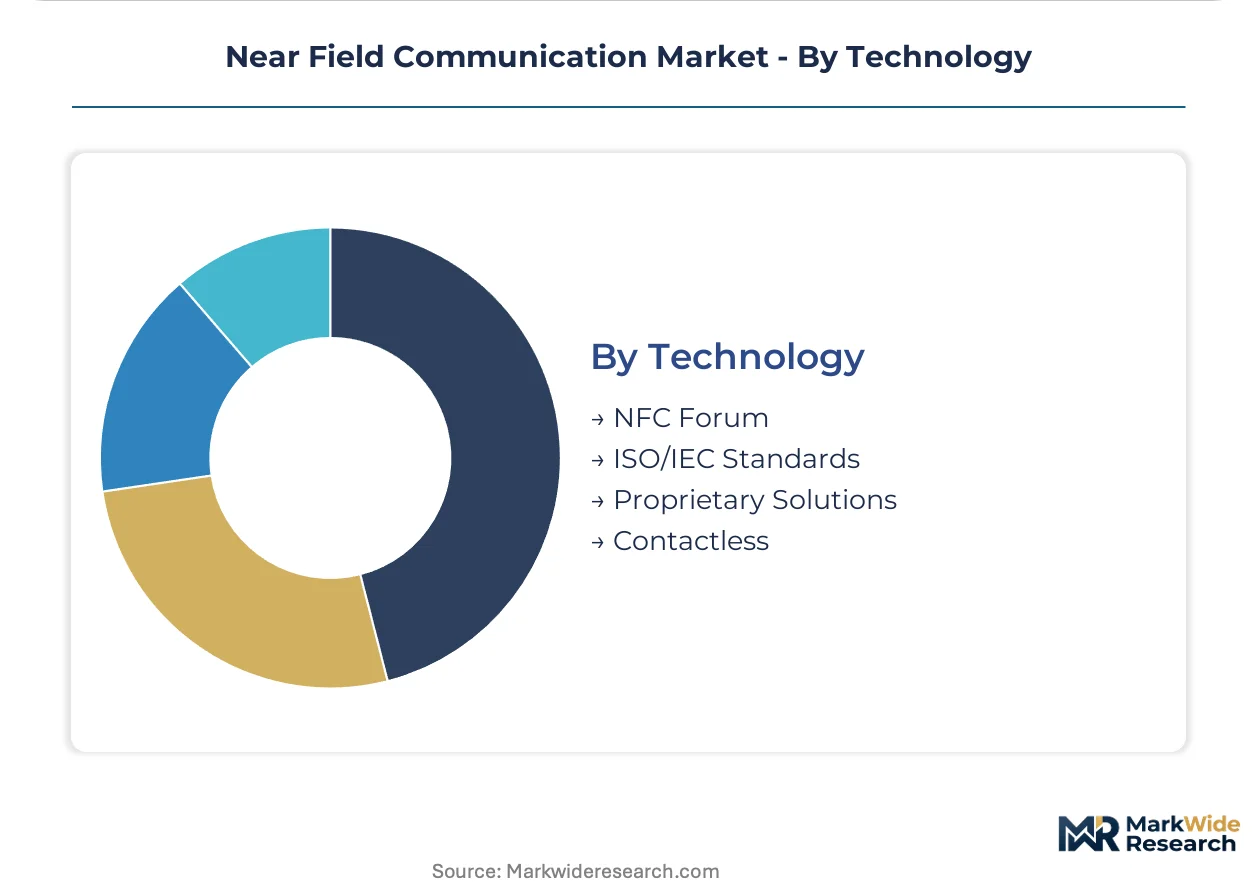
Standardization concentration determines supply chain access, with proprietary solutions locking customers into single-vendor maintenance.
- NFC Forum:NCI (NFC Controller Interface) and LLCP (Logical Link Control Protocol) specifications govern Android and iOS interoperability. The forum's certification program concentrates smartphone controller supply among Broadcom, NXP, and Qualcomm.
- ISO/IEC Standards:ISO/IEC 14443 and ISO/IEC 18092 define physical and data-link layer specifications for cross-vendor compatibility. EMVCo builds upon these foundations for payment terminal compliance, creating a layered certification stack.
- Proprietary Solutions:Sony FeliCa and MIFARE Classic maintain regional strongholds in Japan and legacy transit systems.
- Contactless:Generic 13.56 MHz implementations without protocol-specific certification face interoperability limitations.
ISO/IEC standards anchor the largest installed base, with NFC Forum specifications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent pools in Shenzhen, Eindhoven, and Austin anchor the three dominant design clusters for NFC antenna and controller development. These concentrations attract secure element architects and electromagnetic simulation specialists from competing semiconductor domains. Migration patterns favor jurisdictions with established payment certification ecosystems and proximity to terminal manufacturing.
United States
Merchant acquirers in the United States are accelerating PCI PTS 6.x terminal deployments ahead of EMVCo compliance deadlines. NIST SP 800-63 guidelines for contactless authentication are elevating federal-adjacent procurement standards. Austin and Silicon Valley host the primary controller design centers serving domestic smartphone OEMs and automotive digital key programs.
Germany
Automotive OEM procurement of vehicle access NFC modules is concentrating demand in Baden-Württemberg and Bavaria. KBA vehicle type approval reviews enforce REACH and RoHS recast compliance for antenna substrate materials. Stuttgart and Munich engineering centers specialize in metal-rich environment antenna design for premium vehicle enclosures.
China
China UnionPay certification drives controller and secure element procurement at manufacturing scale in Shenzhen and Dongguan clusters. MIIT standards for mobile payment interoperability create a secondary approval layer distinct from NFC Forum specifications. Shanghai and Beijing house the principal EMVCo testing facilities serving Asia-Pacific terminal exports.
Japan
Sony FeliCa maintains regional protocol dominance in transit and retail payment infrastructure. METI digital identity frameworks are expanding NFC deployment in government service access. Tokyo and Osaka engineering centers focus on compact antenna integration for wearable form factors.
India
NPCI's RuPay contactless expansion and UPI offline protocols are creating greenfield terminal deployment opportunities in Maharashtra and Karnataka. RBI guidelines for tokenized credential issuance are accelerating secure element procurement. Bengaluru and Mumbai host the primary system integrators bridging legacy Wiegand protocols with modern credential formats.
Near Field Communication Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the NFC controller and secure element landscape. Market structure tilts toward consolidation at the premium tier, where EMVCo certification portfolios create sticky supplier relationships. Three archetypes dominate: semiconductor conglomerates with payment security heritage, smartphone-focused controller specialists, and automotive-qualified module suppliers. Competitive moves concentrate on strategic partnerships for foundry capacity and portfolio diversification into adjacent connectivity protocols.
Within the semiconductor conglomerate tier, NXP Semiconductors and Broadcom occupy positions shaped by their respective secure element and smartphone controller legacies. STMicroelectronics exemplifies the automotive-qualified specialist archetype, anchoring vehicle access module supply chains through distinct qualification barriers. These three companies represent the dominant competitive anchors across payment terminal, smartphone, and automotive deployment vectors.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Broadcom |
| STMicroelectronics |
| Qualcomm Technologies |
| Texas Instruments |
| Infineon Technologies |
| Samsung Electronics |
| Sony Corporation |
| Apple Inc. |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent concentration in Shenzhen and Eindhoven anchors labor-cost differentials that widen pricing-tier spreads between premium-certified secure elements and commodity controller modules. European KBA vehicle type approval requirements and REACH substance restrictions elevate material qualification burdens for automotive-qualified NFC, compressing margins for suppliers without pre-certified portfolios.
Pricing Analysis
Bundled hardware-software certification packages from NXP and Samsung command premium positioning against unbundled component sourcing by Southeast Asian tier-two OEMs. Price differentiation rests on EMVCo Level 2 certification status and antenna substrate material grade, with ceramic-filled hydrocarbon laminates carrying 15-20% cost premiums over legacy halogenated alternatives. Cost compression in mid-tier smartphone controllers is intensifying because MediaTek and Qualcomm are integrating secure elements directly into SoC designs, eroding discrete chip pricing power. Merchant acquirers in retail represent the most price-sensitive buyer segment, while automotive OEMs in Germany demonstrate lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Apple and Samsung, while distribution runs through specialized semiconductor distributors serving mid-tier terminal manufacturers in India and Southeast Asia. Advanced secure element foundry capacity concentrates in Taiwan and South Korea, with antenna substrate raw materials drawing from Japanese liquid crystal polymer suppliers and German ceramic-filled laminate specialists. Single-source vulnerability in Taiwan-based foundry exposure represents the dominant structural risk, compounded by MIIT certification requirements that fragment procurement pathways for China-bound shipments. Module suppliers maintain regional fulfillment hubs in Dongguan and Stuttgart to satisfy divergent automotive and consumer electronics qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure element integration into application processors is compressing bill-of-materials complexity while opening premium-tier margin expansion for vendors with pre-certified software stacks. Embedded enclave adoption across mid-tier smartphones concentrates procurement among SoC-integrated suppliers, rewarding early consolidation moves.
For Market Incumbents: Anchor EMVCo certification portfolios against ultra-wideband substitution threats by deepening automotive digital key qualifications through KBA type approval pathways. Secure foundry partnerships in Taiwan and South Korea through long-term capacity reservations, while expanding controller-secure element integration to defend PCB footprint advantages against discrete component vendors.
For New Entrants and Emerging Players: NPCI's RuPay contactless expansion in India opens a window for greenfield terminal deployment targeting Maharashtra and Karnataka transit agency procurement. Target credential-agnostic reader opportunities in East Asian megacities where Transport for London-style cEMV unbundling is shifting capital expenditure toward software-defined payment acceptance. Pursue middleware development partnerships bridging legacy Wiegand protocols with modern credential formats as the primary go-to-market angle.
For Investors and Strategic Acquirers: Automotive semiconductor suppliers are the most active acquirer in this space, seeking NFC module capabilities to complement existing vehicle access portfolios. Five-to-ten year viability hinges on successful navigation of REACH and RoHS recast material transitions alongside UWB-NFC hybrid architecture adoption. Monitor NIST SP 800-63 guideline implementation velocity in federal-adjacent healthcare access control contracts as the critical inflection indicator for multi-factor authentication hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Integration into SoC | Consolidates controller and enclave functions, reducing PCB footprint for MediaTek and Qualcomm designs. |
| EMVCo Level 2 Certification Investment | Creates 8-14 month validation barriers that concentrate terminal procurement among NXP and Ingenico supply chains. |
| Automotive Digital Key Qualification | Opens vehicle access module opportunities through KBA type approval and REACH-compliant substrate transitions. |
| NFC-BLE Hybrid Architecture Development | Enables extended-range wearable provisioning without sacrificing security for transit credential deployment. |
| Credential-Agnostic Reader Deployment | Captures Transport for London-style unbundling opportunities as private sector wallet providers underwrite terminal installation. |
Study Parameters
Direct dialogue with semiconductor procurement managers, automotive platform engineers, terminal manufacturing executives, and transit agency technology officers grounded qualitative findings in operational reality. Secondary validation drew from MIIT mobile payment standards filings, EMVCo certification registries, KBA vehicle type approval databases, and SEC semiconductor supplier disclosures. Bottom-up shipment modeling across smartphone, wearable, terminal, and automotive installation bases triangulated against top-down payment transaction volume projections.
Top-down macroeconomic drivers and bottom-up unit economics converged across the analysis window through segmented demand modeling by product type, end user, application, and technology standard. Controller procurement patterns, secure element integration rates, antenna substrate material transitions, and certification timeline distributions formed the core forecast inputs. CAGRs derived from weighted average growth contributions across these segmentation dimensions, with scenario testing applied to UWB substitution velocity and India digital payment infrastructure buildout assumptions.
Revisions become necessary when REACH recast implementation timelines accelerate, Taiwan foundry capacity experiences geopolitical disruption, or Apple UWB deployment expands beyond vehicle access into retail payment contexts. Forecasts reflect documented assumptions regarding EMVCo compliance deadline adherence and China UnionPay certification pathway stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market