
 Wi-Fi 7 Market | 2026-2036
Wi-Fi 7 Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi 7 Market Insights
China's semiconductor foundry expansion is reshaping component availability for Wi-Fi 7 equipment manufacturers worldwide. Qualcomm Technologies leverages its integrated modem-RF platforms to dominate premium smartphone and client device segments. Broadcom sustains technology leadership through specialized silicon for enterprise access points and carrier-grade infrastructure. MediaTek competes aggressively in mid-tier router and consumer electronics markets with cost-optimized chipset designs.
Wi-Fi 7 refers to the IEEE 802.11be standard delivering theoretical peak rates of 46 Gbps through 320 MHz channel bandwidth, 4K-QAM modulation, and multi-link operation across 2.4 GHz, 5 GHz, and 6 GHz bands simultaneously. The standard targets environments requiring deterministic low-latency performance, including industrial automation, immersive XR streaming, and high-density enterprise venues. Routers and access points capture the dominant share of hardware revenue as enterprises refresh infrastructure to support Wi-Fi 7's multi-gigabit throughput. Residential end users represent the fastest-growing adoption segment as ISPs bundle Wi-Fi 7 gateways with fiber service upgrades. Cloud-based deployment models are gaining traction among distributed enterprises seeking centralized policy management and AI-driven network optimization.
The FCC governs 6 GHz spectrum access through automated frequency coordination rules in the United States, while ETSI and national regulators across Europe implement comparable frameworks under the CE marking regime. China's MIIT sets domestic radio transmission standards that influence chipset design and equipment certification requirements for manufacturers serving that market. Stakeholders must monitor spectrum auction timelines and unlicensed band expansion decisions across multiple jurisdictions to anticipate capacity constraints and competitive positioning shifts.
Market Dynamics
Enterprise refresh cycles are compressing as deterministic latency requirements from industrial automation and immersive streaming workloads force infrastructure replacement decisions before traditional depreciation schedules expire.
Growth Catalysts
- 6 GHz spectrum liberalization:FCC automated frequency coordination rules in the United States and comparable ETSI frameworks across Europe are expanding contiguous channel availability for multi-link operation.
- Industrial automation:Manufacturing facilities in Germany, Japan, and South Korea are deploying Wi-Fi 7 for time-sensitive networking to replace wired Ethernet in motion control applications.
- Immersive XR streaming:Healthcare simulation centers and defense training facilities require 46 Gbps theoretical throughput for uncompressed video transport.
Market Restraints
- Silicon supply concentration:Advanced node production for 320 MHz-capable baseband processors depends on Taiwan and South Korea foundry capacity with limited geographic diversification.
- Equipment cost structure:4K-QAM modulation and multi-link radio front-ends require gallium nitride power amplifiers that trade off efficiency against bill-of-materials expansion.
- Legacy infrastructure lock-in:Enterprises with recent Wi-Fi 6E deployments face accelerated write-off pressures before measurable throughput exhaustion justifies replacement.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for telecom equipment production are attracting chipset packaging and testing investments to serve domestic and Middle East export markets.
- Cloud-managed enterprise LAN:AI-driven radio resource management delivered as subscription services creates recurring revenue streams distinct from hardware monetization.
- Multi-link operation convergence:Integration of Wi-Fi 7 with 5G NR-U in unlicensed 6 GHz bands enables private network deployments without spectrum auction costs.
Industry Challenges
- RF engineering talent scarcity:320 MHz channel bonding and 4K-QAM implementation require specialized expertise in millimeter-wave circuit design that outpaces university pipeline output.
- Interoperability certification complexity:Wi-Fi Alliance certification timelines for multi-link operation features lag chipset availability by 6-9 months, delaying enterprise procurement.
- Legacy power-over-Ethernet constraints:Existing 802.3bt infrastructure at 90W limits full 4x4 MIMO 320 MHz access point deployment without electrical retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi 7 Market |
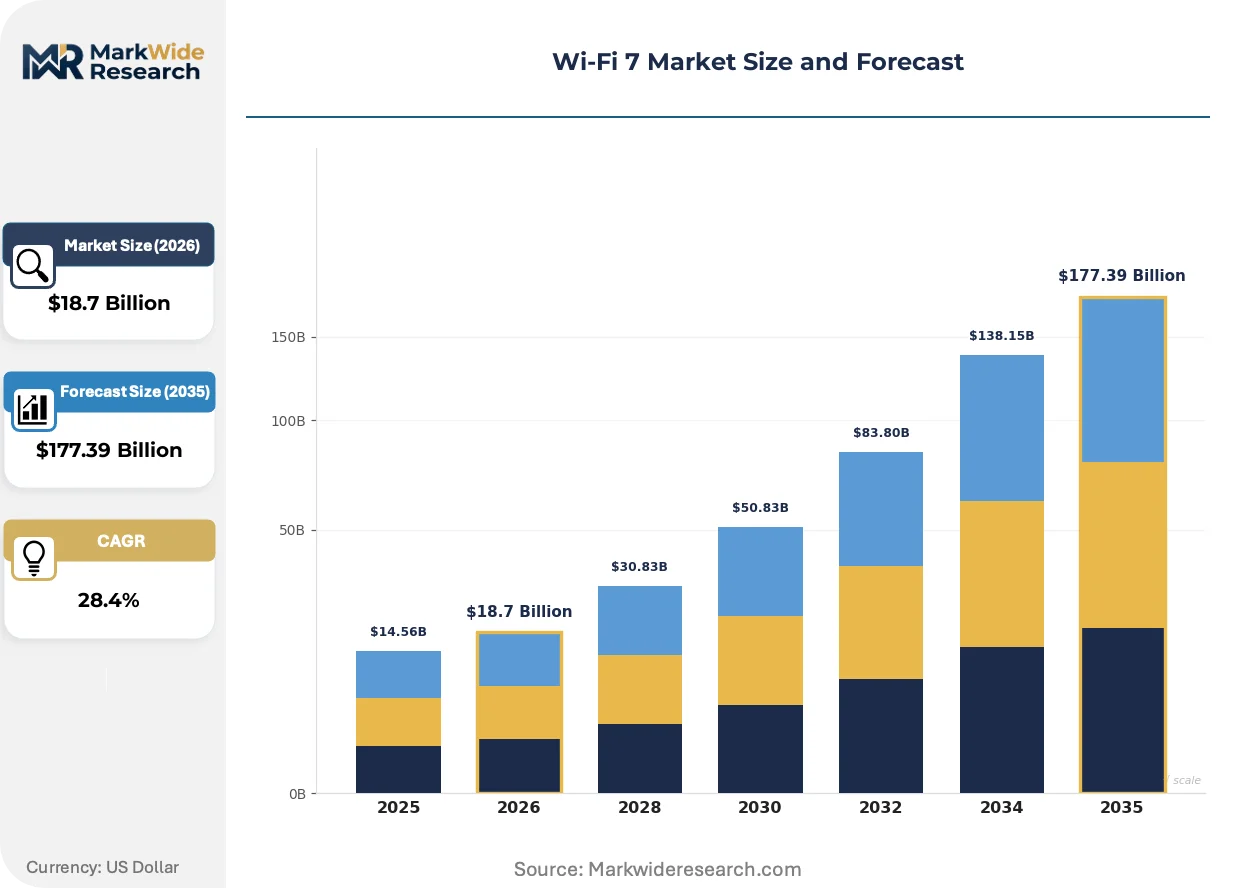
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Access Points, Network Adapters, Range Extenders End User: Residential, Commercial, Industrial, Educational Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: Multi-User MIMO, Beamforming, OFDMA, Mesh Networking |
| Companies Covered | Qualcomm Technologies, Inc., Broadcom Inc., Intel Corporation, Cisco Systems, Inc., MediaTek Inc., TP-Link Technologies, ZTE Corporation, CommScope, Netgear Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi 7 Market Trends and Innovations
Radio access network architectures are decoupling hardware from control plane intelligence, enabling software-defined spectrum management that responds to real-time congestion patterns rather than static configuration.
Multi-link operation is virtualizing the physical layer abstraction for client devices by presenting multiple simultaneous connections across 2.4 GHz, 5 GHz, and 6 GHz bands as a single logical interface. Enterprise IT departments are piloting this capability in high-density convention centers and stadium venues where single-band congestion historically degraded user experience. The technology is virtualizing traditional site survey and channel planning workflows by automating band-steering decisions that previously required manual RF engineering intervention.
ETSI harmonized standards for 6 GHz unlicensed access are mandating automated frequency coordination databases that prevent interference with incumbent satellite services across the European Union. Industrial equipment manufacturers must redesign outdoor access point enclosures to meet stricter power spectral density limits in this band. German automotive test tracks and French aerospace facilities represent early compliance adopters given their proximity to licensed satellite earth stations requiring protection.
Network-as-a-service procurement models are displacing capital-intensive ownership structures among mid-market enterprises with distributed branch footprints. Managed service providers are consolidating hardware supply and cloud controller subscriptions into per-seat pricing that transfers obsolescence risk from IT budgets to vendor balance sheets. This transition is most visible in United States healthcare clinic networks and United Kingdom retail chains where standardization across hundreds of sites outweighs customization preferences.
Wi-Fi 7 Market Segmentation
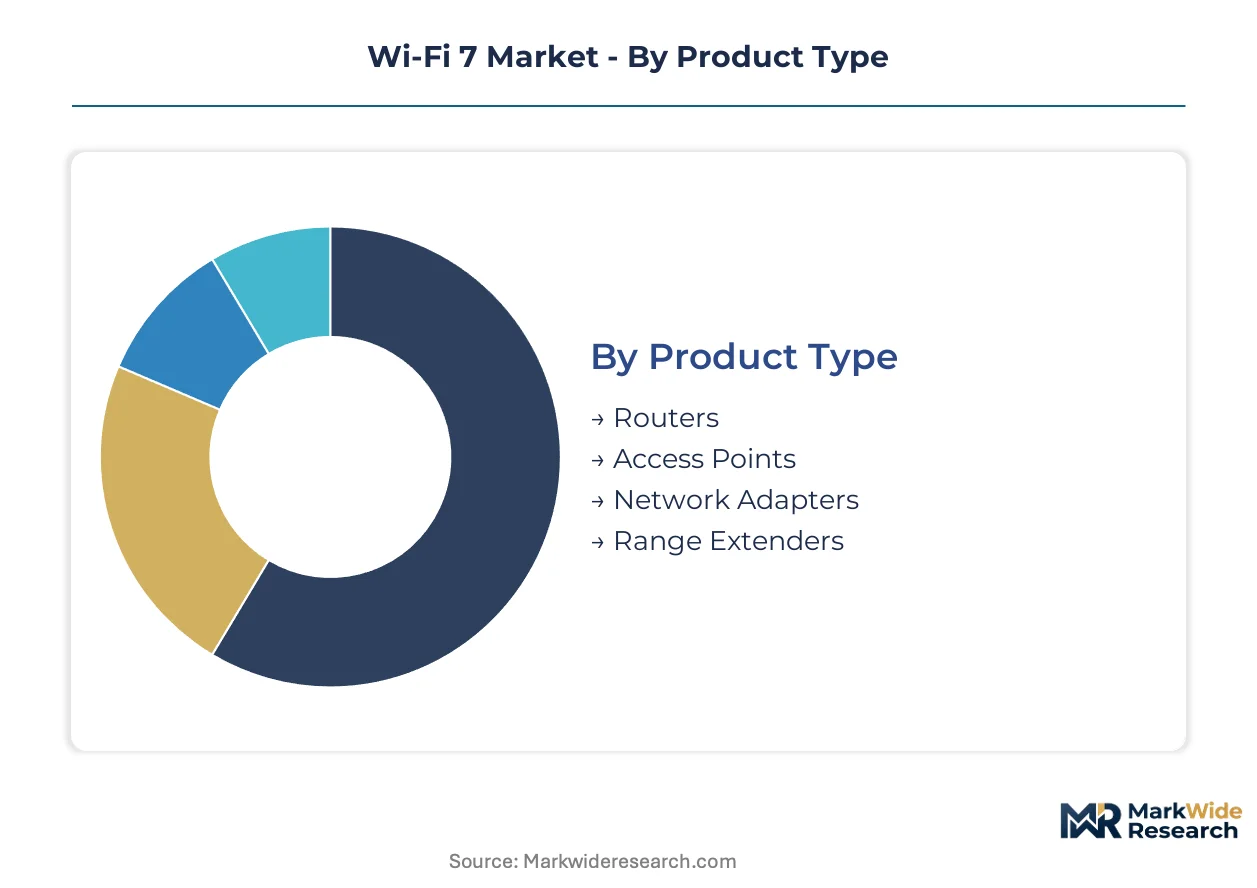
Wi-Fi 7 equipment exhibits sharply divergent service requirements across product categories, with enterprise infrastructure demanding multi-year support contracts while consumer hardware operates on minimal after-sales engagement. Segmentation by product type, end user, deployment model, and technology reveals distinct margin profiles and channel strategies that manufacturers must navigate simultaneously.
Product Type:
After-sales service intensity varies dramatically across Wi-Fi 7 hardware categories, with enterprise access points requiring 24/7 technical support and firmware lifecycle management while consumer routers ship with limited warranty coverage and self-service troubleshooting.
- Access Points:Enterprise-grade hardware with 4x4 MIMO configurations and 320 MHz channel support. Demand concentrates in United States healthcare clinic networks and German automotive manufacturing facilities where deterministic latency requirements mandate vendor-managed service contracts. FCC automated frequency coordination compliance adds ongoing regulatory maintenance burdens.
- Routers:Consumer and SMB gateway devices integrating Wi-Fi 7 baseband processors with Ethernet switching. Chinese OEMs are scaling production for domestic fiber-to-the-home deployments and Middle East export markets, leveraging MIIT certification pathways to accelerate time-to-revenue.
- Network Adapters:PCIe and USB client devices enabling legacy hardware upgrades. Gaming PC builders in South Korea and Japan represent concentrated demand for low-latency competitive multiplayer applications.
- Range Extenders:Signal amplification hardware for residential coverage gaps. Price-sensitive positioning limits service attach rates compared to full router replacements.
Access Points holds the largest share; momentum sits with Routers as ISP bundling accelerates consumer gateway refreshes.
End User:
Customer acquisition costs and contract structures diverge sharply across Wi-Fi 7 end-user segments, with industrial deployments requiring proof-of-concept validation periods that extend sales cycles by 12-18 months versus residential transactional purchases.
- Commercial:Enterprise campuses, hospitality venues, and retail chains deploying high-density Wi-Fi 7 infrastructure. Cloud-managed procurement models are displacing capital-intensive ownership among United States healthcare networks and United Kingdom retail chains. ETSI harmonized standards for 6 GHz automated frequency coordination impose ongoing compliance monitoring requirements across European Union deployments.
- Residential:Individual consumers and multi-dwelling units upgrading home networks. Fiber service providers in Japan and South Korea are bundling Wi-Fi 7 gateways with gigabit subscriptions to reduce churn and capture equipment margin.
- Industrial:Manufacturing facilities deploying time-sensitive networking for motion control and automated guided vehicles. German automotive test tracks and French aerospace facilities lead adoption given proximity to satellite earth stations requiring ETSI-mandated interference protection.
- Educational:K-12 and university campuses refreshing infrastructure to support immersive XR laboratories and hybrid learning environments. Budget cycles tied to fiscal years create pronounced seasonal demand concentration.
Commercial captures dominant revenue share; Residential is climbing the fastest as mass-market pricing erodes enterprise-premium gaps.
Deployment Model:
Capital efficiency requirements and internal IT capability gaps are driving Wi-Fi 7 procurement toward operational expenditure models that transfer obsolescence risk from enterprise balance sheets to vendor recurring revenue streams.
- Cloud-Based:Centralized controller platforms delivering AI-driven radio resource management and policy orchestration. Distributed enterprises with limited on-site technical staff favor this model for standardized multi-site deployments.
- Managed Services:Comprehensive outsourcing encompassing hardware procurement, installation, monitoring, and lifecycle refresh. United States mid-market healthcare clinic networks are consolidating vendor relationships to reduce procurement complexity across hundreds of sites.
- On-Premises:Traditional capital ownership with internal IT management. Regulated industries with data sovereignty requirements maintain preference despite higher total cost of ownership.
- Hybrid:Split architectures retaining sensitive control plane functions on-premises while leveraging cloud analytics for optimization. Financial services institutions in Singapore and Switzerland are piloting this approach for branch network modernization.
Managed Services holds the largest share; momentum sits with Cloud-Based as AI-driven optimization capabilities mature.
Technology:
Patent licensing intensity and implementation complexity create tiered margin structures across Wi-Fi 7 technology categories, with multi-link operation and 4K-QAM modulation commanding premium positioning versus commoditized baseline features.
- Multi-User MIMO:Spatial stream multiplexing enabling simultaneous client communication. Enterprise access point vendors differentiate through 16x16 configurations supporting stadium-density deployments.
- OFDMA:Subcarrier allocation for efficient small-packet transmission. Industrial automation applications in Japan and Germany leverage this capability for deterministic latency in motion control systems.
- Beamforming:Directional signal concentration extending range and reducing interference. Residential mesh systems utilize this to minimize node count in large-footprint homes.
- Mesh Networking:Self-organizing multi-node coverage extension. Consumer adoption is accelerating in suburban United States markets where construction materials degrade single-router performance.
Multi-User MIMO holds the largest share; momentum sits with OFDMA as industrial time-sensitive networking requirements expand.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced node foundry capacity for 320 MHz-capable baseband processors concentrates in Taiwan and South Korea, creating geographic dependencies that equipment manufacturers must navigate through multi-sourcing strategies and strategic inventory positioning.
United States
Enterprise campus networks in healthcare and automotive verticals are accelerating procurement of Wi-Fi 7 access points to support bandwidth-intensive collaboration tools and time-sensitive networking workloads. FCC automated frequency coordination rules govern 6 GHz spectrum access, expanding contiguous channel availability for multi-link operation. Austin and Detroit metropolitan clusters anchor deployment activity, with automotive test tracks leading industrial automation pilots.
China
Domestic OEMs are scaling production of Wi-Fi 7 chipsets and infrastructure equipment for both local deployment and export markets, particularly across manufacturing corridors in the Yangtze River Delta. MIIT sets domestic radio transmission standards that influence chipset design and equipment certification requirements for manufacturers serving this market. Shenzhen and Shanghai anchor the semiconductor packaging and testing investments feeding Middle East export demand.
Germany
Automotive manufacturing facilities and industrial automation sites are deploying Wi-Fi 7 for time-sensitive networking to replace wired Ethernet in motion control applications. ETSI harmonized standards mandate automated frequency coordination databases that prevent interference with incumbent satellite services across the European Union. Bavaria and Baden-Württemberg host the automotive test tracks and aerospace facilities representing early compliance adopters.
Japan
Gaming PC builders and immersive streaming service providers represent concentrated demand for low-latency competitive multiplayer applications and uncompressed video transport. METI industrial policy frameworks support private 5G and Wi-Fi convergence in unlicensed spectrum bands. Tokyo and Osaka metropolitan clusters drive residential gateway refreshes as fiber service providers bundle Wi-Fi 7 equipment with gigabit subscriptions.
South Korea
Electronics manufacturers are integrating Wi-Fi 7 baseband processors into premium smartphones and client devices targeting export markets. National spectrum management authorities have aligned 6 GHz unlicensed access rules with regional harmonization frameworks. Seoul Capital Area and Busan-Ulsan industrial zones concentrate chipset design houses and RF engineering talent pools serving global equipment vendors.
Wi-Fi 7 Market Competitive Landscape
Integrated platform specialists and specialized silicon architects split the market between premium client devices and enterprise infrastructure segments. The vendor base organizes around three strategic archetypes: modem-RF integrators serving smartphone OEMs, enterprise access point silicon specialists, and cost-optimized chipset designers targeting mid-tier consumer markets. Competitive positioning hinges on multi-link operation certification timelines and gallium nitride power amplifier supply relationships rather than manufacturing scale alone.
Within the integrated platform tier, Qualcomm Technologies, Inc. and Broadcom Inc. exemplify divergent specialization strategies—one anchoring premium mobile client segments, the other sustaining technology leadership through carrier-grade infrastructure silicon. MediaTek Inc. occupies a position within the cost-optimized archetype, representing aggressive mid-market positioning through volume-oriented chipset designs. These three entities collectively illustrate how patent licensing intensity and implementation complexity create tiered margin structures across technology categories.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Broadcom Inc. |
| Intel Corporation |
| Cisco Systems, Inc. |
| MediaTek Inc. |
| TP-Link Technologies |
| ZTE Corporation |
| CommScope |
| Netgear Inc. |
| Others |
Pricing and Supply Chain Analysis
Taiwan foundry concentration risk determines both the pricing tier spreads across enterprise, mid-market, and consumer Wi-Fi 7 equipment and the geographic shape of multi-sourcing strategies that equipment vendors must deploy. FCC and ETSI regulatory certification costs create fixed barriers that compress margins at the economy tier while amplifying premium capture for vendors with pre-certified multi-link operation silicon.
Pricing Analysis
FCC automated frequency coordination rules dictate the pricing tier structure across Wi-Fi 7 hardware categories. Three-tier pricing structure across premium, standard, and economy levels separates enterprise access points with 4x4 MIMO 320 MHz support from mid-tier routers and entry-level range extenders. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in consumer gateways is intensifying because Chinese OEMs are scaling production for ISP bundling programs. Residential fiber subscribers exhibit highest price sensitivity, while German automotive manufacturers and United States healthcare networks demonstrate lowest sensitivity due to deterministic latency requirements.
Supply Chain Analysis
Gallium nitride power amplifiers and advanced node baseband processors anchor upstream feedstock dependencies for Wi-Fi 7 equipment manufacturing. Taiwan and South Korea foundries supply 320 MHz-capable silicon, while China provides printed circuit board assembly and enclosure manufacturing. Raw material dependencies include gallium nitride substrates, high-frequency laminates, and multi-layer ceramic capacitors. Single-source vulnerability concentrates in Taiwan foundry capacity for premium smartphone chipset production. Distribution runs through OEM direct sales for enterprise access points, retail channels for consumer routers, and ISP bundling programs for residential gateways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wi-Fi 7 incumbents must defend against private 5G NR-U substitution in industrial automation and enterprise campus applications where deterministic latency requirements overlap. The substitution threat intensifies as spectrum auction costs decline and 5G radio unit pricing compresses.
For Market Incumbents: Build certification moats through accelerated Wi-Fi Alliance multi-link operation compliance timelines. Secure gallium nitride power amplifier supply agreements with Taiwan and South Korea substrate vendors to defend against cost-optimized entrants. Expand enterprise service contract attach rates in United States healthcare and German automotive verticals where replacement cycles are compressing. Counter private 5G substitution by emphasizing unlicensed 6 GHz deployment speed and avoiding spectrum auction costs. For New Entrants and Emerging Players: Pursue India PLI scheme incentives for telecom equipment manufacturing to serve Middle East export markets with cost-optimized router designs. Target cloud-managed enterprise LAN procurement models among United States mid-market healthcare clinic networks seeking to consolidate vendor relationships across distributed sites. Exploit interoperability certification lag times by pre-integrating with dominant cloud controller platforms before formal Wi-Fi Alliance approval. For Investors and Strategic Acquirers: ETSI harmonized standards for 6 GHz automated frequency coordination reshape the acquisition landscape by elevating regulatory compliance capabilities above pure silicon performance metrics. Long-term viability centers on vendors with demonstrated multi-jurisdiction certification throughput and established relationships with Taiwan foundry capacity allocators. Acquisition target archetypes include specialized RF engineering firms with millimeter-wave circuit design expertise and cloud-managed networking software platforms with AI-driven radio resource management. Cross-checking against FCC equipment authorization database trends is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Link Operation Certification Acceleration | Wi-Fi Alliance pre-certification partnerships compress enterprise procurement delays by 6-9 months. |
| Gallium Nitride Supply Agreement | Taiwan substrate vendor relationships secure power amplifier allocation amid foundry capacity constraints. |
| Cloud Controller Platform Integration | AI-driven radio resource management subscriptions create recurring revenue distinct from hardware monetization. |
| India Manufacturing Footprint Expansion | PLI scheme incentives reduce landed cost for Middle East and African export markets. |
| Private 5G Convergence Partnership | Integration with 5G NR-U unlicensed spectrum deployments defends against substitution in industrial verticals. |
Research Methodology
Cross-validation between semiconductor foundry capacity disclosures and enterprise procurement survey data anchors the qualitative findings in this Wi-Fi 7 market analysis. Primary interviews with RF engineering directors at access point manufacturers, procurement leads at United States healthcare networks, cloud controller platform product managers, and Taiwan foundry account managers combined with secondary validation from FCC equipment authorization databases, ETSI harmonized standards documentation, SEC 10-K filings from listed chipset vendors, and MIIT radio transmission certification records. Bottom-up equipment shipment estimates and top-down addressable market sizing provide triangulation across the analysis window.
Calibration against historical Wi-Fi 6 and Wi-Fi 6E adoption curves informs the projection framework across product type, end user, deployment model, and technology segmentation dimensions. CAGRs derive from fitted S-curve penetration models incorporating 6 GHz spectrum liberalization timelines, enterprise refresh cycle compression factors, and residential fiber subscription bundling attach rates. Industry-specific forecast inputs include gallium nitride power amplifier yield improvement trajectories and automated frequency coordination database deployment schedules across United States, European Union, and Chinese regulatory jurisdictions.
Sensitivities concentrate around Taiwan foundry capacity allocation shifts, FCC spectrum reallocation decisions, and private 5G NR-U pricing compression in industrial automation applications. Forecasts reflect assumptions regarding multi-link operation certification timeline convergence and gallium nitride substrate supply elasticity. Cross-checking against Wi-Fi Alliance certification announcement velocity and hyperscaler capex disclosures for cloud-managed networking infrastructure is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Global Wi-Fi Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Multefire Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
APAC Small Cell 5G Market