
 Industrial Wireless Transmitter Market | 2026-2036
Industrial Wireless Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wireless Transmitter Market Outlook
German automation OEMs is broadening the supply base for precision wireless transmitters across European process industries. Emerson Electric Company leverages its Plantweb digital ecosystem to anchor long-term service contracts in hydrocarbon processing. Honeywell International Inc. competes through its Experion platform integration, while Siemens AG dominates in power generation wireless deployments across Central European utilities.
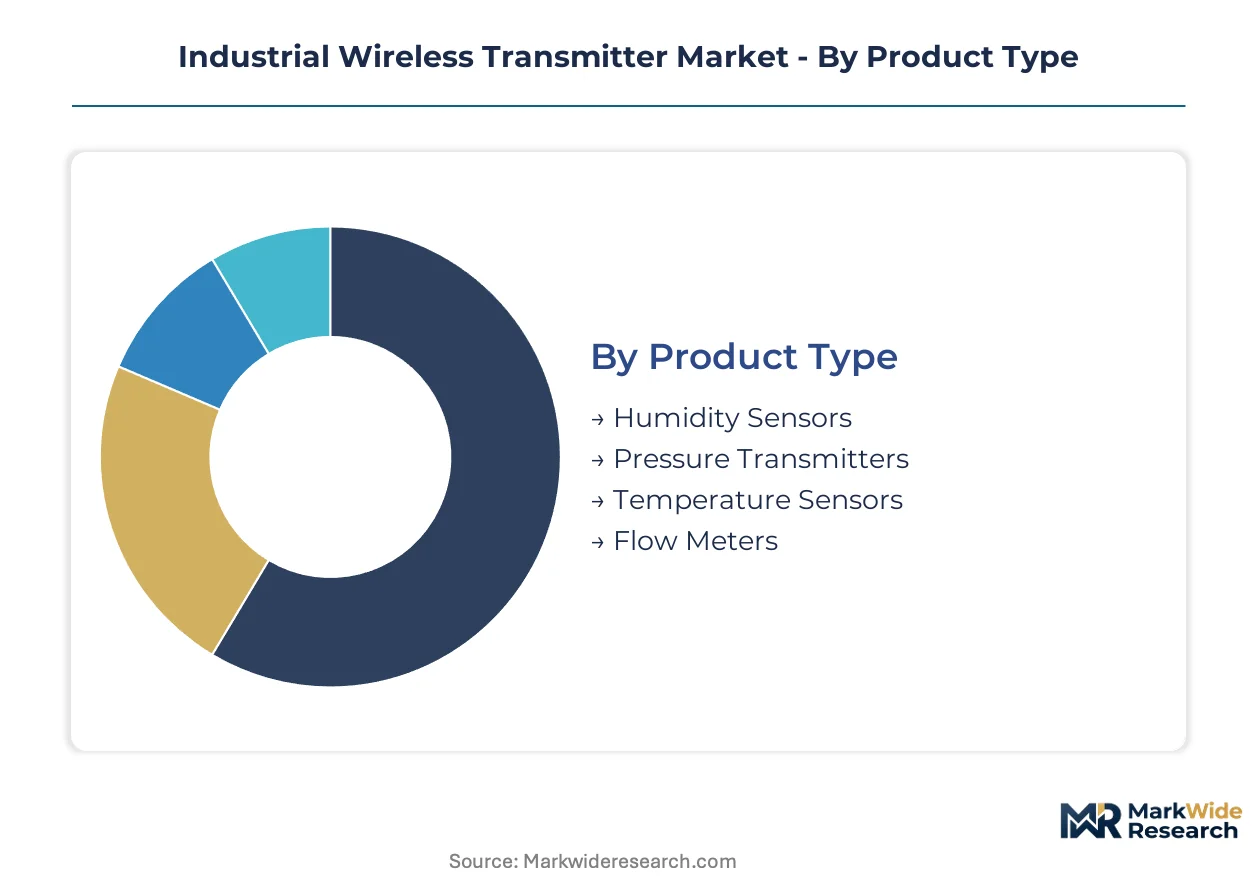
Industrial wireless transmitters are radio-frequency devices that convert physical process variables into digital signals for remote monitoring, typically operating in unlicensed ISM bands with transmit power below one watt to ensure regulatory compliance. These instruments eliminate cabling infrastructure in hazardous environments while enabling real-time data acquisition from rotating equipment and remote tank farms. Pressure transmitters command the largest product segment due to universal deployment across steam systems and pipeline networks, while LoRaWAN technology represents the fastest-expanding connectivity category for long-range, low-power asset tracking in chemical processing. Temperature sensors maintain mature margins in food safety applications where HACCP mandates drive replacement cycles.
The FCC governs spectrum allocation and device certification for US industrial wireless deployments, while the EU Radio Equipment Directive establishes harmonized frequency access across member states. IEC 62591 and ISA100.11a standards define interoperability protocols that determine supplier qualification for multinational energy projects. Stakeholders must evaluate how emerging cybersecurity mandates from NIST and EU agencies will reshape transmitter authentication requirements and firmware update obligations.
Market Dynamics
LoRaWAN protocol adoption is compressing deployment timelines for asset tracking networks in chemical processing facilities, while FCC Part 15 power restrictions continue to shape transmitter hardware design trade-offs across North American installations.
Growth Catalysts
- EU Radio Equipment Directive harmonization:Cross-border frequency alignment reduces certification duplication costs for multinational energy projects spanning Germany, France, and the Netherlands.
- Oil and gas refinery sensor densification:Hazardous area classification requirements drive replacement of wired instrumentation with intrinsically safe wireless pressure transmitters on rotating equipment.
- ISM band propagation characteristics:Sub-gigahertz spectrum penetration enables reliable signal transmission through metal tank farms and concrete process buildings without repeater infrastructure.
Market Restraints
- Semiconductor supply concentration:RF front-end component sourcing remains concentrated among Taiwanese foundries, exposing lead time volatility for industrial-grade transceiver modules.
- ISA100.11a interoperability certification costs:Third-party testing fees for wirelessHART and ISA100 protocol compliance add fixed overhead for low-volume transmitter variants.
- Power budget physics:One-watt FCC Part 15 transmit power ceiling limits effective range in dense steel environments, forcing mesh network architectures that increase node count requirements.
Strategic Opportunities
- India PLI scheme for industrial automation:Domestic manufacturing incentives for process control equipment create localized assembly opportunities for wireless transmitter OEMs serving South Asian chemical plants.
- Food safety HACCP mandate expansion:Temperature monitoring compliance requirements in cold chain logistics drive demand for battery-powered LoRaWAN sensors with multi-year operational life.
- 5G-RedCap and LoRaWAN convergence:Hybrid connectivity architectures combining licensed cellular fallback with unlicensed primary links enable new service models for critical infrastructure monitoring.
Industry Challenges
- IEC 62591 firmware update authentication:Cybersecurity mandates from NIST SP 800-82 and EU agencies require secure over-the-air update capabilities that strain embedded processor resources in legacy transmitter designs.
- Intrinsic safety barrier integration:Wireless transmitters deployed in Zone 0/1 hazardous locations must maintain IS certification compatibility with existing galvanic isolation infrastructure, complicating retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wireless Transmitter Market |
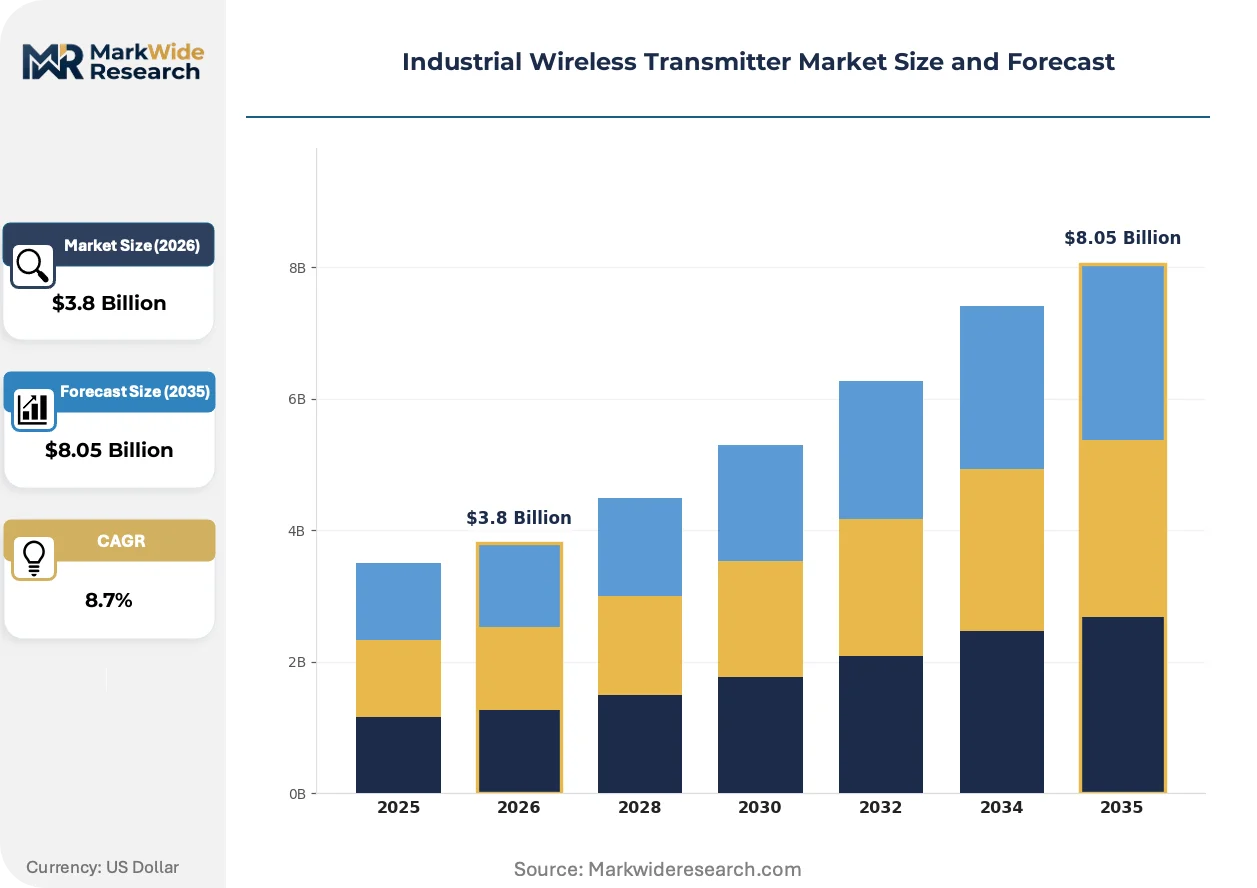
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humidity Sensors, Pressure Transmitters, Temperature Sensors, Flow Meters End User: Manufacturing, Chemical Processing, Food & Beverage, Pharmaceuticals Technology: Zigbee, LoRaWAN, Bluetooth, Wi-Fi Installation: Fixed, Portable, Integrated, Modular |
| Companies Covered | Emerson Electric Company, Honeywell International Inc., Schneider Electric Corporation, ABB Group Ltd, Siemens AG, Yokogawa Electric, OleumTech Corporation, Rohde & Schwarz GmbH & Co. KG, Adcon Telemetry GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wireless Transmitter Market Strategic Shifts
Edge computing integration is relocating signal processing from centralized DCS systems to field-mounted transmitter enclosures, compressing latency for closed-loop control applications while reducing backhaul bandwidth requirements.
Multi-protocol radio silicon is unifying WirelessHART, ISA100.11a, and LoRaWAN physical layers into single-chip transceiver solutions. Chemical processors in the US Gulf Coast are piloting these unified modules to simplify spare parts inventory across mixed-vendor installations. This convergence is unifying previously siloed maintenance workflows and reducing technician training burdens for heterogeneous network environments.
EU cybersecurity certification schemes under the Radio Equipment Directive are mandating secure boot and signed firmware for industrial wireless devices. German automotive OEMs now require transmitter suppliers to demonstrate compliance with IEC 62443-4-2 security level SL-2 as a procurement gate. Power generation utilities across Central Europe are accelerating vendor qualification timelines to meet these emerging authentication standards before 2027 grid modernization deadlines.
Maintenance contract unbundling is separating hardware procurement from lifecycle calibration services. US oil and gas operators now source transmitters through direct manufacturer channels while contracting third-party metrology firms for annual drift verification. This bifurcation is most pronounced in Permian Basin upstream facilities where specialized calibration houses compete on technician mobility rather than equipment margin.
Industrial Wireless Transmitter Market Segmentation
Wireless transmitter procurement patterns diverge sharply across certification regimes, with hazardous area classifications and protocol interoperability requirements fragmenting supplier qualification pathways. End-users segment investments by physical measurement domain and connectivity architecture, each carrying distinct firmware authentication burdens under emerging cybersecurity mandates.
Product Type:
ISA100.11a and WirelessHART certification costs vary by measurement complexity, with pressure and temperature devices facing the steepest third-party testing fees for intrinsic safety compliance.
- Pressure Transmitters:Piezoresistive sensing elements dominate steam system and pipeline monitoring applications. Demand concentrates in Permian Basin upstream facilities and German automotive hydraulic test rigs where ASME B31.3 compliance drives specification rigidity.
- Temperature Sensors:RTD and thermocouple-based designs serve food safety HACCP mandates and power generation steam temperature monitoring. German utilities and US Gulf Coast refineries anchor procurement volumes for IEC 60584-certified variants.
- Humidity Sensors:Capacitive polymer designs target pharmaceutical cleanroom and cold chain logistics applications with FDA 21 CFR Part 11 data integrity requirements.
- Flow Meters:Ultrasonic and Coriolis principles apply to chemical processing custody transfer, with OIML R117 metrology certification gating European refinery adoption.
Leading the category by volume: Pressure Transmitters. Growing fastest: Temperature Sensors.
End User:
Capital deployment intensity scales with regulatory inspection frequency, separating continuous process industries from batch manufacturing in wireless sensor densification economics.
- Chemical Processing:Continuous reactor monitoring and tank farm inventory management drive LoRaWAN deployments across US Gulf Coast and Rotterdam-Antwerp chemical clusters. NIST SP 800-82 cybersecurity mandates are accelerating firmware authentication upgrades.
- Manufacturing:Automotive assembly lines and metal fabrication facilities deploy vibration and temperature transmitters on rotating equipment. German Industry 4.0 investments dominate procurement for ISO 22400-compliant OEE monitoring.
- Pharmaceuticals:FDA process analytical technology initiatives and EU GMP Annex 15 qualification requirements drive validated wireless installations in sterile processing suites.
- Food & Beverage:Cold chain logistics and thermal processing monitoring align with FSMA preventive controls and EU 178/2002 traceability mandates.
Highest certification overhead: Pharmaceuticals. Steepest volume expansion: Chemical Processing.
Technology:
Protocol selection locks customers into specific ecosystem architectures, with mesh versus star topologies determining lifecycle spare parts strategy and technician training investment.
- LoRaWAN:Sub-gigahertz unlicensed spectrum enables kilometer-range transmission through metal infrastructure without repeater deployment. Chemical processors in the US Gulf Coast and German bulk chemical sites pilot unified multi-protocol modules to simplify heterogeneous network maintenance.
- Zigbee:IEEE 802.15.4-based mesh networking serves manufacturing asset tracking with deterministic latency for closed-loop control applications in automotive paint shops.
- Wi-Fi:High-bandwidth 802.11 variants support video-integrated condition monitoring in power generation turbine halls where backhaul infrastructure exists.
- Bluetooth:Low-energy implementations target portable maintenance tools and short-range configuration interfaces for field technician smartphone integration.
Widest addressable range: LoRaWAN. Tightest latency control: Zigbee.
Installation:
Mounting architecture determines intrinsic safety barrier compatibility and Zone 0/1 hazardous area retrofit engineering complexity.
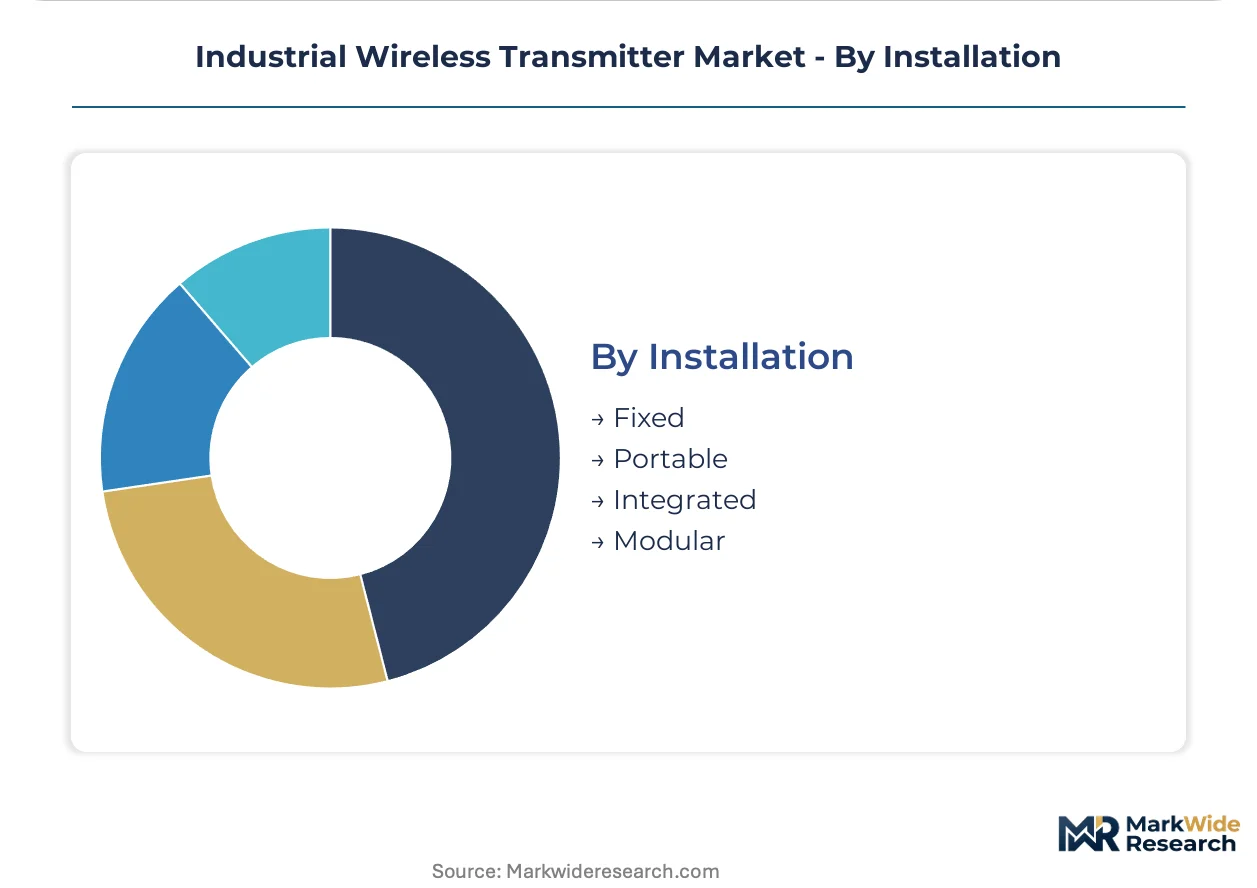
- Fixed:Permanent enclosure mounting on vessels and piping dominates refinery and chemical plant deployments. IS certification alignment with existing galvanic isolation infrastructure complicates brownfield engineering in North Sea and Middle Eastern upstream facilities.
- Portable:Battery-powered temporary monitoring serves turnaround maintenance and contractor-led inspection campaigns in seasonal agricultural processing.
- Integrated:Transmitter-actor combinations embedded in valve positioners and pump skids reduce wiring termination points in modular process plant construction.
- Modular:Swappable sensor heads and radio modules extend operational life across rotating equipment fleets with varying measurement requirements.
Dominant revenue share: Fixed. Fastest replacement cycle: Portable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Taiwan and South Korea feed RF component supply chains that underpin transmitter manufacturing across major industrial economies. Regional procurement patterns diverge sharply between mature automation markets and emerging chemical processing corridors.
United States
Permian Basin upstream operators and Gulf Coast refineries drive intrinsically safe wireless pressure transmitter procurement for rotating equipment monitoring. FCC Part 15 unlicensed spectrum rules govern device certification, while NIST SP 800-82 cybersecurity mandates reshape firmware authentication requirements. Houston-area chemical processors pilot multi-protocol modules to unify WirelessHART and LoRaWAN maintenance workflows.
Germany
Automotive OEM hydraulic test rigs and Industry 4.0 assembly lines anchor precision transmitter demand across Baden-Württemberg and Bavaria. The EU Radio Equipment Directive harmonizes cross-border frequency access, reducing certification costs for suppliers serving Dutch and French chemical clusters. Ruhr Valley power generation utilities accelerate vendor qualification timelines to meet IEC 62443-4-2 SL-2 security standards before 2027 grid deadlines.
China
Yangtze River Delta chemical processors and Pearl River Delta manufacturing hubs deploy sub-gigahertz LoRaWAN networks for tank farm inventory management. MIIT spectrum allocations in unlicensed ISM bands enable kilometer-range transmission through dense steel infrastructure. Sichuan-Chongqing shale gas developments drive hazardous area wireless sensor densification for wellhead monitoring.
India
Gujarat chemical corridors and Maharashtra refinery complexes represent emerging demand centers for battery-powered temperature and pressure transmitters. The PLI scheme for industrial automation creates localized assembly opportunities for OEMs serving South Asian process plants. Reliance Industries' Jamnagar complex pilots LoRaWAN asset tracking networks with multi-year operational life requirements.
Saudi Arabia
Eastern Province oil and gas infrastructure and Jubail Industrial City petrochemical complexes drive Zone 0/1 hazardous area wireless deployments. The country's national communications regulator manages spectrum licensing for industrial IoT networks in parallel with GCC harmonization efforts. SABIC affiliate facilities anchor transmitter procurement volumes for intrinsically safe rotating equipment monitoring.
Industrial Wireless Transmitter Market Competitive Environment
Global majors compete with regional champions across certification regimes and protocol ecosystems, creating a tiered structure where scale-driven conglomerates anchor hydrocarbon processing while specialized mid-caps capture food safety and pharmaceutical niches. Market structure consolidates around three archetypes: diversified industrial conglomerates with digital platform ecosystems, RF technology specialists with test and measurement heritage, and regional automation integrators with localized service networks. Dominant competitive moves include strategic partnerships for multi-protocol silicon development and geographic expansion through distributor network consolidation in emerging chemical processing corridors.
Among diversified industrial conglomerates, Emerson Electric Company and Honeywell International Inc. occupy positions anchoring long-term service contracts through integrated digital ecosystems, while Siemens AG exemplifies the European-centric archetype with utility-focused deployments across Central European power generation markets. RF technology heritage from Rohde & Schwarz GmbH & Co. KG represents the test-equipment-to-industrial pivot strategy, and Yokogawa Electric sits within the Asia-Pacific specialist tier serving process industry automation requirements.
| Leading Market Players |
|---|
| Emerson Electric Company |
| Honeywell International Inc. |
| Schneider Electric Corporation |
| ABB Group Ltd |
| Siemens AG |
| Yokogawa Electric |
| OleumTech Corporation |
| Rohde & Schwarz GmbH & Co. KG |
| Adcon Telemetry GmbH |
| Others |
Value Chain & Pricing Dynamics
EU cybersecurity certification schemes under the Radio Equipment Directive gate qualified supply access while stratifying transmitter procurement across premium authenticated tiers and standard unverified alternatives. IEC 62443-4-2 SL-2 compliance investments compress margins for mid-tier suppliers while concentrating pricing power among firmware-authenticated vendors serving German automotive OEMs and Central European utilities.
Pricing Analysis
Warranty and lifecycle calibration bundling separates Emerson and Honeywell's integrated service contracts from unbundled hardware transactions common among US Permian Basin operators. Three-tier pricing structure across premium authenticated, standard certified, and economy unverified levels reflects ISA100.11a and WirelessHART certification overhead. Cost compression in economy tiers intensifies as Taiwanese RF component lead time volatility forces buffer stock carrying costs onto distributors. Chemical processors exhibit highest price sensitivity due to volume procurement, while pharmaceutical sterile suites accept premium tiers for FDA 21 CFR Part 11 data integrity compliance.
Supply Chain Analysis
Skilled RF engineering workforce scarcity in Taiwan, South Korea, and Germany constrains transceiver module production scaling for industrial-grade transmitters. Silicon wafer fabrication draws from TSMC and Samsung foundry capacity, while precision sensing elements rest on Bosch and TE Connectivity ceramic substrate supply. Single-source vulnerability in sub-gigahertz RF front-end components exposes lead time volatility across North American and European transmitter OEMs. Distribution runs through authorized industrial automation distributors with field service technician networks anchoring aftermarket calibration revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as firmware authentication requirements force backward control over secure boot silicon and embedded cryptographic modules.
For Market Incumbents: To counter multi-protocol radio convergence threatening ecosystem lock-in, anchor Plantweb and Experion platform stickiness through mandatory firmware update subscriptions. Deepen backward integration into secure element manufacturing to bypass Taiwanese foundry queue constraints for SL-2 certified modules. For New Entrants and Emerging Players: Capture India PLI scheme localization incentives for Gujarat chemical corridor deployments before incumbent distributor networks consolidate. Target battery-powered LoRaWAN temperature sensors for cold chain logistics where HACCP mandate expansion outpaces established service infrastructure. Lead with third-party metrology partnerships rather than hardware margin competition. For Investors and Strategic Acquirers: Siemens AG accelerating IEC 62443-4-2 vendor qualification timelines is the leading indicator that authenticated firmware capabilities will separate viable acquisition targets from stranded technology. Five-to-ten year viability hinges on SL-2 certification achievement, not historical WirelessHART install base. Target mid-cap RF specialists with existing secure boot IP rather than legacy transmitter assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Silicon Integration | Unifies WirelessHART, ISA100.11a, and LoRaWAN layers to reduce spare parts inventory complexity. |
| Secure Boot Firmware Development | Meets EU Radio Equipment Directive authentication mandates before 2027 grid modernization deadlines. |
| Localization Assembly Partnership | Leverages India PLI scheme incentives to serve Gujarat and Maharashtra chemical processing corridors. |
| Third-Party Metrology Unbundling | Separates hardware procurement from calibration services to capture Permian Basin operator procurement shifts. |
| Edge Computing Module Embedding | Relocates signal processing to field enclosures for closed-loop control latency reduction. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this industrial wireless transmitter assessment. Primary interviews with plant engineers, maintenance directors at hydrocarbon processing facilities, OEM procurement teams, and aftermarket service heads combined with FCC Part 15 device certification databases, IEC standards documentation, and EU Radio Equipment Directive harmonization records. Bottom-up transmitter shipment analysis triangulated against top-down process industry automation spending estimates.
Granularity-level modeling disaggregated volume and value across pressure, temperature, humidity, and flow measurement types; LoRaWAN, Zigbee, Wi-Fi, and Bluetooth connectivity architectures; fixed, portable, integrated, and modular installation formats; and chemical processing, manufacturing, pharmaceutical, and food and beverage end-use sectors. CAGRs derived from segment-level growth rate reconciliation against macro industrial automation capex indicators, with ISA100.11a and WirelessHART protocol adoption curves informing connectivity technology trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NIST cybersecurity mandate timing, Taiwanese semiconductor supply normalization, and EU grid modernization deadline adherence. Material deviation in firmware authentication requirements or sub-gigahertz spectrum allocation policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Global Wi-Fi Market
Wireless Technologies
Multefire Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
Wireless Access Point Market