
 Global Wi-Fi 6 Market | 2026-2036
Global Wi-Fi 6 Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wi-Fi 6 Market Foresight
Enterprise networking procurement from corporate networks and educational institutes is collapsing into telecommunication provider-led managed service contracts. Cisco Systems, Inc. leverages its Meraki cloud architecture to dominate campus deployments. Qualcomm Technologies Inc. anchors the semiconductor layer with integrated radio platforms for original equipment manufacturers. Broadcom, Inc. specializes in high-density system-on-chip designs that sustain throughput under concurrent user loads.
Wi-Fi 6 denotes the IEEE 802.11ax standard operating across 2.4 GHz, 5 GHz, and 6 GHz bands with maximum theoretical throughput of 9.6 Gbps, employing Orthogonal Frequency Division Multiple Access and Multi-User Multiple Input Multiple Output to optimize spectral efficiency in dense environments. The technology serves industrial automation and smart city backbones where latency-sensitive machine-to-machine traffic coexists with consumer data streams. Access points and routers command the hardware margin pool as enterprise refresh cycles accelerate, while Target Wake Time functionality opens adjacent revenue in battery-constrained Internet of Things endpoints. Network Interface Cards face commoditization pressure as original device manufacturers embed Wi-Fi 6 natively across laptop and mobile chipsets.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct 6 GHz band power rules that fragment certification pathways and delay single-SKU global product launches. The Wi-Fi Alliance's certification program compounds compliance costs for multi-region vendors. Stakeholders must monitor spectrum reallocation proceedings and pre-position modular radio designs that adapt to jurisdictional power thresholds without hardware redesign.
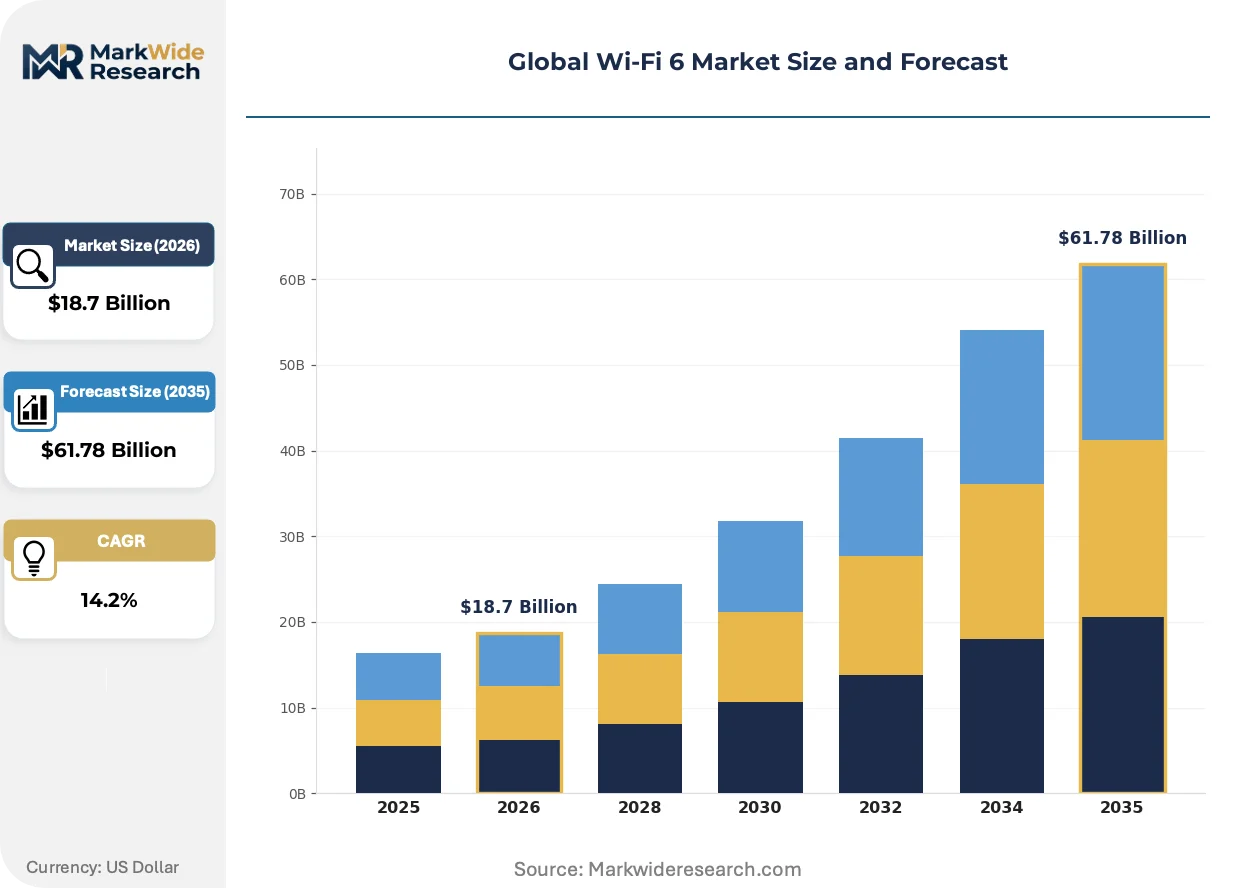
Market Dynamics
The FCC's 6 GHz spectrum allocation under Wi-Fi 6E rules is fragmenting certification pathways and forcing modular radio architectures that adapt to jurisdictional power thresholds without hardware redesign.
Growth Catalysts
- Industrial automation backbones:Manufacturing campuses in Germany and China are accelerating router procurement to support latency-sensitive machine-to-machine traffic alongside consumer data streams.
- Smart city infrastructure mandates:Municipal deployments across the United States are driving access point density requirements for public Wi-Fi coverage and connected transit systems.
- ETSI 6 GHz power rules:The European framework is creating certification clarity that enables single-SKU product launches across EU member states, reducing compliance overhead for vendors.
Market Restraints
- Multi-region certification costs:The Wi-Fi Alliance program compounds expenses when vendors must satisfy FCC, ETSI, and MIIT power rules simultaneously for global product releases.
- Semiconductor supply concentration:Integrated radio platform manufacturing concentrates in East Asian foundries, exposing procurement timelines to geopolitical friction and capacity constraints.
- Network Interface Card commoditization:Native Wi-Fi 6 embedding across laptop and mobile chipsets is compressing margins for discrete NIC suppliers.
Strategic Opportunities
- Battery-constrained IoT endpoints:Target Wake Time functionality opens adjacent revenue streams in sensor networks and wearable devices where power efficiency determines deployment viability.
- Telecommunication provider managed services:Enterprise networking procurement is collapsing into carrier-led contracts that bundle hardware, installation, and ongoing network management.
- India smart city expansion:The country's urban infrastructure investments are creating demand for outdoor-rated access points capable of operating in high-temperature, high-humidity environments.
Industry Challenges
- Legacy 802.11ac infrastructure integration:Enterprise refresh cycles must maintain backward compatibility while extracting performance gains from Wi-Fi 6 deployments, complicating network architecture decisions.
- RF engineering talent scarcity:Orthogonal Frequency Division Multiple Access and Multi-User MIMO optimization require specialized expertise that outpaces current university pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wi-Fi 6 Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Points, Routers, Network Interface Cards, Repeaters, Bridges Technology: Orthogonal Frequency Division Multiple Access, Multi-User Multiple Input Multiple Output, Target Wake Time, Basic Service Set Coloring, Spatial Reuse Application: Enterprise Networking, Smart Cities, Connected Homes, Public Wi-Fi, Industrial Automation End User: Telecommunication Providers, Corporate Networks, Educational Institutes, Hospitality Services, Government Agencies |
| Companies Covered | Cisco Systems, Inc., Qualcomm Technologies Inc., Broadcom, Inc., Intel Corporation, Huawei Technologies Co., Ltd., NETGEAR, Inc., Juniper Networks, Inc., Extreme Networks, Inc., Fortinet, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wi-Fi 6 Market Shifts & Advancements
Orthogonal Frequency Division Multiple Access is fundamentally altering how spectral efficiency gets priced and deployed across dense environments. Three forces are compressing the competitive window for vendors.
Orthogonal Frequency Division Multiple Access enables simultaneous data transmission to multiple devices within a single channel, improving throughput in stadiums, convention centers, and manufacturing floors. Large venue operators and industrial facility managers are adopting the technology aggressively to support device densities exceeding 50 clients per access point. This capability is displacing legacy 802.11ac deployments in high-density settings where contention-based access previously throttled performance.
ETSI's harmonized 6 GHz power rules across European member states are reducing regulatory fragmentation that previously forced hardware variants. The framework permits standard power indoor and low power indoor modes that align with FCC approaches, simplifying certification pathways for multi-region vendors. German and French network equipment manufacturers are responding by accelerating single-SKU development timelines for enterprise access points.
Enterprise procurement patterns are consolidating around managed service contracts that bundle hardware refresh, cloud-based network management, and guaranteed uptime service level agreements. This model displaces traditional capital expenditure purchases by IT departments at universities and corporate campuses. The United States and China exhibit the strongest concentration of this shift, with telecommunication providers capturing margin that previously flowed to value-added resellers.
Global Wi-Fi 6 Market Segmentation
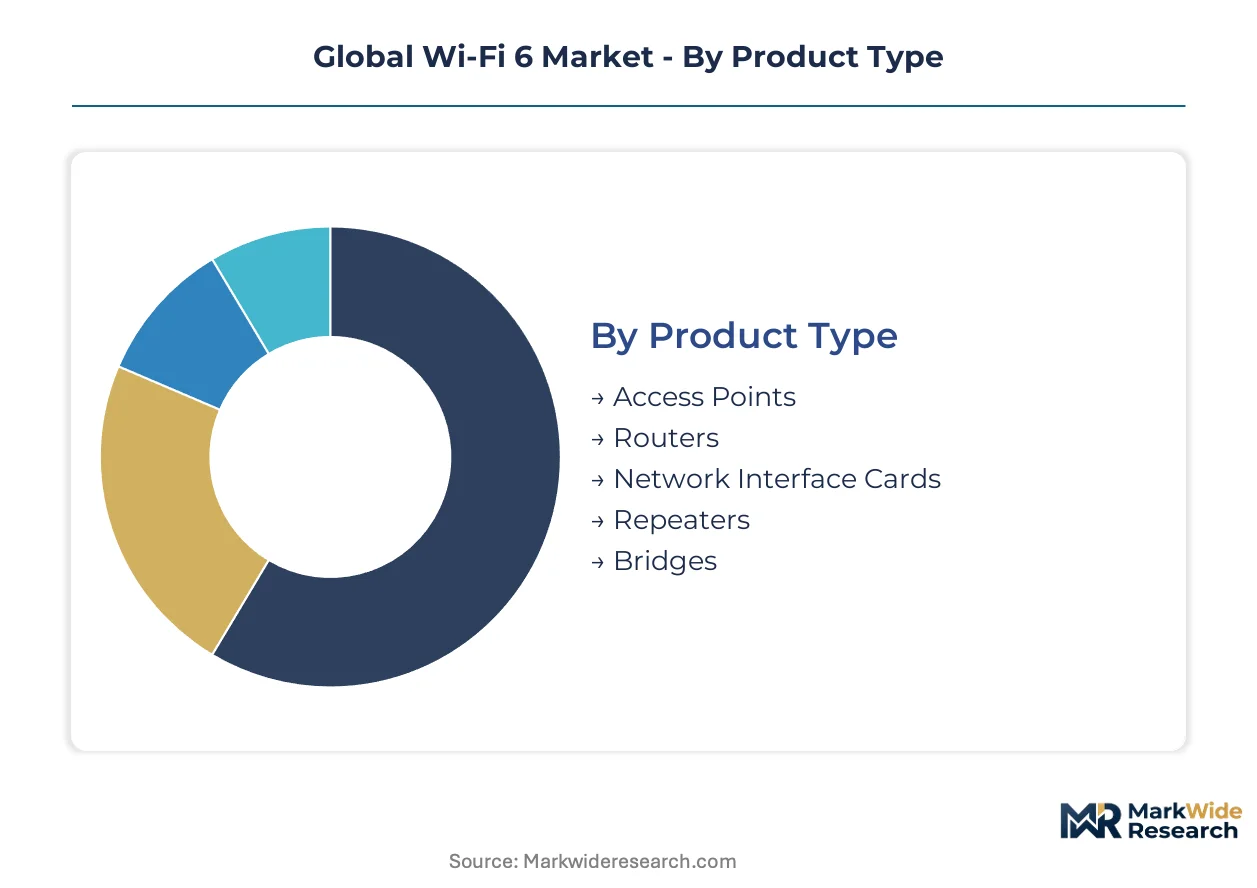
Wi-Fi 6 market segmentation reveals how regulatory frameworks, deployment architectures, and procurement patterns fragment revenue pools across hardware categories and service models. Understanding these divisions exposes where margin concentrates and where commoditization pressures intensify.
Product Type:
FCC, ETSI, and MIIT power thresholds for 6 GHz operation create divergent hardware certification requirements that reshape product development priorities across access point and router portfolios.
- Access Points:Enterprise-grade hardware supporting 9.6 Gbps theoretical throughput with OFDMA and MU-MIMO capabilities. Manufacturing campuses in Germany and China are accelerating procurement to support 50+ concurrent clients per unit in dense industrial environments.
- Routers:Campus and branch infrastructure devices integrating cloud-managed architectures. Telecommunication providers in the United States are bundling these into managed service contracts that displace traditional IT capital expenditure cycles.
- Network Interface Cards:Discrete wireless adapters facing compression as laptop and mobile OEMs embed Wi-Fi 6 natively into chipsets.
- Repeaters:Signal extension hardware deployed in residential and small office settings where full infrastructure replacement is cost-prohibitive.
- Bridges:Point-to-point wireless links connecting distributed facilities across manufacturing and logistics campuses.
Established volume favors access points; emerging adoption favors routers.
Technology:
Cost tier differentiation separates premium implementations with full feature stacks from economy deployments using baseline 802.11ax compliance.
- Orthogonal Frequency Division Multiple Access:Spectral efficiency technology enabling simultaneous transmission to multiple devices within a single channel. Stadium and convention center operators are adopting aggressively to support extreme client densities exceeding legacy 802.11ac capacity limits.
- Multi-User Multiple Input Multiple Output:Spatial stream allocation allowing concurrent uplink and downlink communication with multiple clients. Smart city infrastructure projects in the United States specify this capability for connected transit and public safety networks.
- Target Wake Time:Power scheduling mechanism extending battery life in IoT endpoints. Sensor network deployments are climbing the fastest as power efficiency determines viability in remote monitoring applications.
- Basic Service Set Coloring:Interference mitigation technique distinguishing overlapping network transmissions in dense deployments.
- Spatial Reuse:Channel optimization technology improving throughput in high-interference environments.
Enterprise deployments concentrate on OFDMA and MU-MIMO; IoT expansion drives Target Wake Time integration.
Application:
Customer maturity varies sharply between enterprise buyers with dedicated RF engineering staff and municipal purchasers navigating public procurement complexity.
- Enterprise Networking:Corporate campus and branch infrastructure requiring guaranteed uptime SLAs. Educational institutes in China are consolidating procurement under carrier-led managed service contracts.
- Smart Cities:Municipal deployments spanning public Wi-Fi, connected transit, and environmental monitoring. Outdoor-rated access points capable of high-temperature, high-humidity operation are seeing steepest expansion trajectory in India urban infrastructure investments.
- Connected Homes:Residential broadband CPE and mesh systems where consumer price sensitivity limits feature adoption.
- Public Wi-Fi:Airport, stadium, and retail venue deployments monetizing through advertising or premium tier access.
- Industrial Automation:Manufacturing floor networks where latency-sensitive machine-to-machine traffic demands deterministic performance.
Enterprise Networking commands current margin pools; Smart Cities represent the fastest-growing application segment.
End User:
Procurement authority is shifting from IT departments to procurement offices as contracts consolidate and extend duration.
- Telecommunication Providers:Carriers capturing enterprise networking spend through bundled hardware, installation, and management services. The United States and China exhibit strongest concentration of this procurement collapse.
- Corporate Networks:Private enterprise IT organizations maintaining direct vendor relationships for campus refresh cycles.
- Educational Institutes:Universities and K-12 districts migrating to subscription models that convert capital expenditure to operational expenditure.
- Hospitality Services:Hotel and venue operators where guest Wi-Fi quality directly affects booking platform ratings.
- Government Agencies:Federal, state, and municipal purchasers subject to extended procurement timelines and security certification requirements.
Telecommunication Providers are consolidating share fastest; Corporate Networks retain premium customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated radio platform manufacturing concentrates in East Asian foundries, exposing procurement timelines to geopolitical friction and capacity constraints. The United States, China, and Germany concentrate demand as smart city infrastructure and industrial automation backbones expand.
United States
Municipal deployments across the United States are driving access point density requirements for public Wi-Fi coverage and connected transit systems. The FCC's unlicensed 6 GHz spectrum allocation under Wi-Fi 6E rules is reshaping product certification requirements. Dallas and Austin clusters anchor enterprise networking procurement as telecommunication providers capture margin through bundled managed service contracts.
China
Manufacturing campuses in China are accelerating router procurement to support latency-sensitive machine-to-machine traffic alongside consumer data streams. MIIT enforces distinct 6 GHz band power rules that fragment certification pathways and delay single-SKU global product launches. The Yangtze River Delta industrial corridor concentrates semiconductor foundry capacity for integrated radio platforms serving original equipment manufacturers.
Germany
German manufacturing campuses are accelerating router and access point procurement to support industrial automation backbones. ETSI's harmonized 6 GHz power rules across European member states are reducing regulatory fragmentation that previously forced hardware variants. The Baden-Württemberg industrial cluster anchors enterprise-grade hardware development timelines for single-SKU product launches.
India
Urban infrastructure investments in India are creating demand for outdoor-rated access points capable of operating in high-temperature, high-humidity environments. The country's national telecommunications regulator frames spectrum allocation proceedings that vendors must monitor. Maharashtra and Karnataka state clusters concentrate smart city deployment authority as procurement shifts to carrier-led managed service models.
Japan
Enterprise refresh cycles in Japan are maintaining backward compatibility while extracting performance gains from Wi-Fi 6 deployments. METI guidelines influence industrial facility network architecture decisions for latency-sensitive applications. The Kanto region around Tokyo anchors corporate campus infrastructure procurement as educational institutes migrate to subscription-based operational expenditure models.
Global Wi-Fi 6 Market Competitive Landscape
Concentration sits with semiconductor specialists and cloud-managed networking platforms. The vendor base spans three tiers: integrated circuit designers supplying original equipment manufacturers, infrastructure hardware fabricators serving enterprise campuses, and telecommunication providers bundling managed services. Strategic moves center on modular radio architectures that adapt to jurisdictional power thresholds and cloud-native network management capabilities that displace traditional capital expenditure cycles.
Within the semiconductor tier, Qualcomm Technologies Inc. and Broadcom, Inc. exemplify integrated radio platform suppliers. Cisco Systems, Inc. anchors the infrastructure hardware segment through cloud-managed campus deployments. These three companies occupy positions that span the technology stack from chip design through enterprise access point deployment, representing the vertical integration pattern that compresses margin for discrete component suppliers.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Qualcomm Technologies Inc. |
| Broadcom, Inc. |
| Intel Corporation |
| Huawei Technologies Co., Ltd. |
| NETGEAR, Inc. |
| Juniper Networks, Inc. |
| Extreme Networks, Inc. |
| Fortinet, Inc. |
| Others |
Supply & Pricing Matrix
Long-term managed service contracts lock in both semiconductor supply access and price visibility for enterprise networking hardware, as telecommunication providers in the United States and China bundle installation, cloud management, and guaranteed uptime into multi-year agreements that convert traditional capital expenditure cycles into predictable operational expenditure streams.
Pricing Analysis
FCC 6 GHz power rules dictate the pricing tier structure across access point portfolios, with certification-grade differentiation separating indoor standard-power hardware from low-power indoor variants. Three-tier pricing structure across premium, standard, and economy levels reflects OFDMA and MU-MIMO feature depth alongside cloud-management capabilities. Cost compression in the Network Interface Card segment is intensifying because laptop and mobile OEMs embed Wi-Fi 6 natively into chipsets, eliminating discrete adapter demand. Educational institutes exhibit the highest price sensitivity as they migrate to subscription models, while telecommunication providers prioritize guaranteed service level agreements over unit cost.
Supply Chain Analysis
East Asian foundry capacity concentration in Taiwan and South Korea anchors integrated radio platform manufacturing for original equipment manufacturers. The supply chain draws from advanced node semiconductor fabrication, RF front-end component assembly, and cloud software development centers. Single-source vulnerability concentrates in Yangtze River Delta packaging facilities where geopolitical friction threatens procurement timelines. Distribution runs through direct enterprise sales teams, telecommunication provider procurement offices, and value-added reseller channels serving mid-market campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi 6 market sits in early-cycle expansion as industrial automation backbones in Germany and China accelerate router procurement for latency-sensitive machine-to-machine traffic, with smart city infrastructure mandates in the United States and India extending the addressable hardware base beyond traditional enterprise networking.
For Market Incumbents: Consolidate cloud-managed platform capabilities to capture telecommunication provider-led procurement consolidation, while deepening backward integration into RF semiconductor design to defend margin against Qualcomm and Broadcom pricing power. Priority rests on modular radio architectures that adapt to jurisdictional power thresholds without hardware redesign, preserving single-SKU economics across FCC, ETSI, and MIIT certification regimes. For New Entrants and Emerging Players: Managed service bundling gaps in India's high-temperature outdoor access point segment offer the most penetrable white-space target, as Maharashtra and Karnataka state clusters concentrate smart city deployment authority. Battery-constrained IoT endpoints utilizing Target Wake Time functionality present a second entry vector where power efficiency expertise outweighs incumbent scale advantages. Go-to-market positioning should emphasize carrier partnership channels over direct enterprise sales. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor specialists with captive RF design capabilities and cloud-native network management platforms serving telecommunication provider procurement offices. Long-term viability hinges on sustained enterprise refresh cycles and industrial automation backbone expansion across manufacturing corridors. The signal to watch is ETSI 6 GHz harmonization progress across European member states, which would validate single-SKU economics and compress compliance overhead for multi-region vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Radio Architecture Development | Enables FCC, ETSI, and MIIT compliance without hardware redesign, preserving margin. |
| Cloud-Managed Platform Integration | Cisco Meraki-type architectures capture telecommunication provider bundling demand. |
| Target Wake Time Feature Stack | Opens adjacent revenue in sensor networks where power efficiency determines viability. |
| Outdoor-Rated Access Point Certification | Qualifies hardware for India smart city high-temperature, high-humidity deployments. |
| Telecommunication Provider Partnership | Positions vendors for managed service contract capture in United States and China. |
Research Methodology
A spread of perspectives from enterprise IT procurement officers, telecommunication provider network planning directors, semiconductor RF engineering leads, and Wi-Fi Alliance certification managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC spectrum allocation filings, ETSI harmonization documents, MIIT technical specifications, and SEC 10-K disclosures from networking hardware vendors. Bottom-up unit shipment modeling triangulated against top-down enterprise networking capital expenditure patterns across the analysis window.
Segmentation dimensions modeled include product type, technology feature depth, application vertical, and end-user procurement authority across the projection horizon. CAGRs were derived from installed base refresh cycle timing, smart city infrastructure investment trajectories, and industrial automation backbone deployment rates. Forecast inputs incorporated semiconductor foundry capacity utilization, regulatory certification timeline assumptions, and telecommunication provider managed service contract penetration curves.
Forecasts assume regulatory continuity in FCC, ETSI, and MIIT 6 GHz power regimes; material policy shifts would require re-modeling certification pathway economics and single-SKU viability. Practitioners should keep alternative scenarios live as geopolitical friction in East Asian foundry regions and spectrum reallocation proceedings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market