
 Telecom Wireless Data Market | 2026-2036
Telecom Wireless Data Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Wireless Data Market Analytics
Enterprise buyers are reorganizing procurement priorities around private 5G networks and edge computing integration, displacing consumer-centric data plans as the primary growth vector. T-Mobile US leverages its mid-band spectrum depth to anchor industrial IoT contracts across automotive and logistics campuses. Verizon competes through millimeter-wave deployments in dense urban corridors, sustaining premium positioning for high-throughput enterprise applications. Deutsche Telekom differentiates via its Open RAN interoperability standards, extending vendor flexibility for European manufacturing clients.
Telecom wireless data encompasses radio-frequency-based transmission services enabling mobile internet access, voice over IP, and machine-to-machine communication across licensed and unlicensed spectrum bands operating from 600 MHz to 39 GHz. The underlying infrastructure relies on base station densification, carrier aggregation protocols, and packet-core virtualization to deliver latency below 20 milliseconds for real-time applications. 5G technology leads capital allocation due to network slicing capabilities that partition bandwidth for deterministic industrial use cases, while Wi-Fi 6 occupies complementary indoor environments where licensed spectrum costs prove prohibitive. Mobile broadband within the service type dimension generates the dominant revenue pool, though private network deployment models are capturing the fastest expansion as mines, ports, and factories seek captive connectivity.
The FCC governs spectrum auctions and net neutrality principles in the United States, directly shaping carrier investment cycles and wholesale access economics. EMA and national telecom regulators across Europe enforce cybersecurity certification and data localization under the EU AI Act and GDPR, raising compliance thresholds for cross-border service provisioning. China's MIIT coordinates GB standards for base station equipment and dual carbon goals that mandate energy efficiency benchmarks. Stakeholders must monitor spectrum reallocation timelines and open-interface mandates to calibrate infrastructure lock-in against vendor diversification strategies.
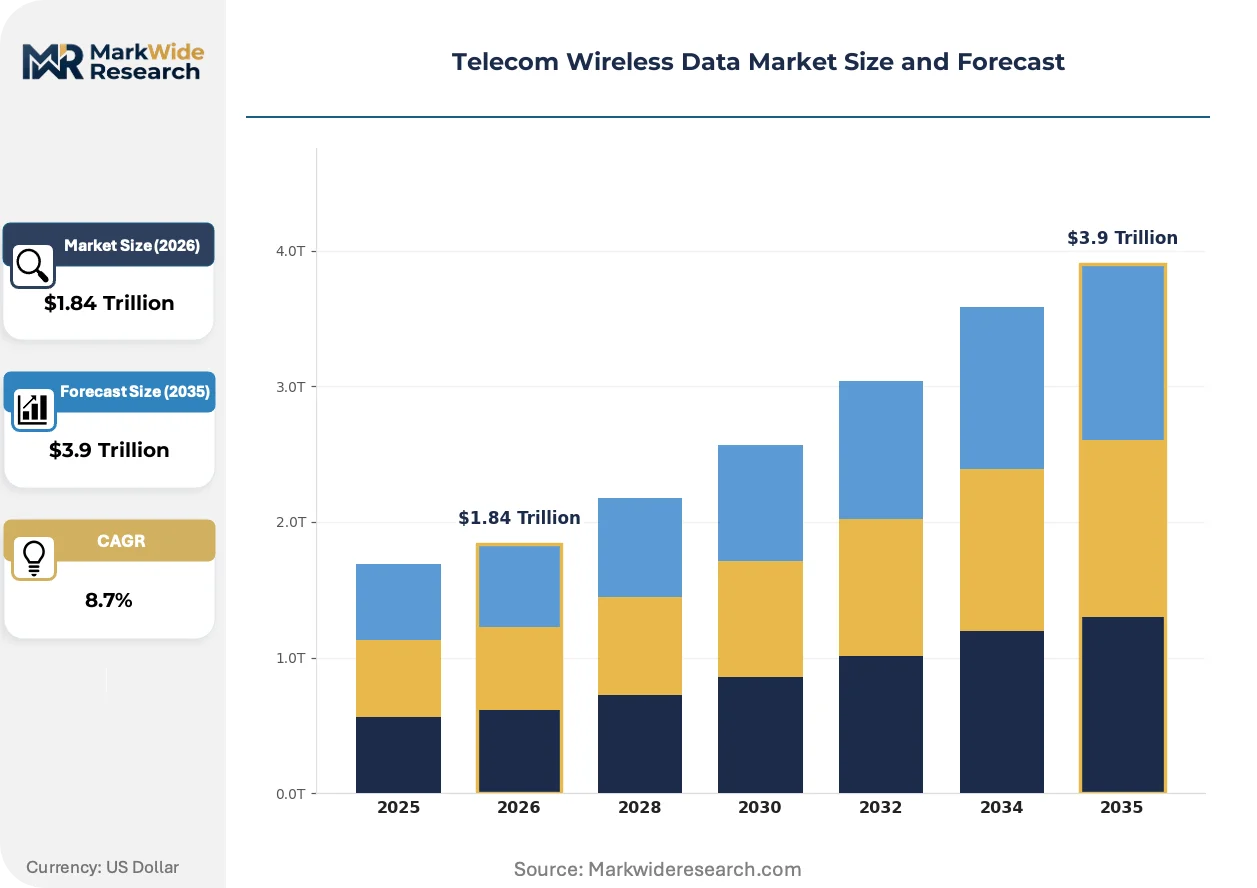
Market Dynamics
Network slicing capabilities are compressing carrier business models from commodity bandwidth resale toward differentiated service-level agreements for deterministic industrial automation.
Growth Catalysts
- Private 5G spectrum frameworks:Germany's BNetzA and Japan's MIC have released localized licenses enabling captive networks at manufacturing sites and container terminals.
- Edge computing convergence:Ultra-reliable low-latency communication pairs with distributed compute nodes to support real-time quality control in automotive assembly.
- Rural broadband gaps:India's Universal Service Obligation Fund subsidizes tower deployment in unserved districts, expanding addressable subscriber bases.
Market Restraints
- Licensed spectrum costs:Auction prices for C-band and mmWave blocks in the United States consume 15-25% of carrier capex budgets.
- Base station equipment concentration:Three vendors supply 70% of active antenna units, creating single-source vulnerability for Open RAN migrations.
- Energy consumption thresholds:China's MIIT enforces dual carbon efficiency mandates that accelerate depreciation cycles for legacy 4G infrastructure.
Strategic Opportunities
- Mine and port automation:Resource extraction and maritime logistics sectors in Australia and Chile are procuring standalone networks for equipment teleoperation.
- Neutral host infrastructure:Shared small-cell deployments in stadiums and transit hubs enable multi-tenant revenue models without spectrum ownership.
- Fixed wireless access substitution:5G-based home broadband is capturing wireline subscribers in suburban United States markets where fiber trenching costs prove prohibitive.
Industry Challenges
- Radio frequency engineering talent scarcity:Specialized expertise in massive MIMO antenna design and beamforming algorithms commands premium compensation.
- Multi-vendor integration complexity:Disaggregated RAN stacks from separate suppliers require extended testing cycles to achieve carrier-grade reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Wireless Data Market |
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.9 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 4G, 5G, LTE, Wi-Fi 6 End User: Consumers, Enterprises, Government, Manufacturers Service Type: Data Services, Voice Services, SMS, Mobile Broadband Deployment: Private Network, Public Network, Hybrid Network, Cloud-based |
| Companies Covered | T-Mobile US, Verizon, AT&T, China Mobile, Deutsche Telekom, China Telecom, SoftBank, Bharti Airtel, Vodafone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Wireless Data Market Evolving Landscape
Open RAN architectures are fragmenting vendor ecosystems and compelling incumbent suppliers to disaggregate hardware-software stacks. This shift reconfigures procurement evaluation criteria toward interoperability testing.
Cloud-native packet core implementations are supplanting proprietary hardware appliances in carrier central offices. Tier-1 operators in South Korea and the United States are migrating subscriber management functions to containerized platforms running on commodity servers. This transition compresses capital intensity per subscriber while enabling rapid service instantiation for enterprise slices.
The EU AI Act and accompanying cybersecurity certification schemes under ENISA are mandating formal risk assessments for network management systems processing automated traffic optimization. Equipment vendors must demonstrate conformity with Common Criteria EAL4+ standards before deployment in member state critical infrastructure. German and French carriers are prioritizing suppliers with pre-certified security architectures to accelerate approval timelines.
Enterprise buyers are consolidating connectivity procurement under single managed service contracts rather than negotiating separate agreements with multiple carriers. Manufacturing conglomerates in Japan and Germany now specify performance guarantees spanning private campus networks and wide-area roaming under unified vendor relationships. This pattern concentrates account control with integrators capable of orchestrating heterogeneous access technologies.
Telecom Wireless Data Market Segmentation
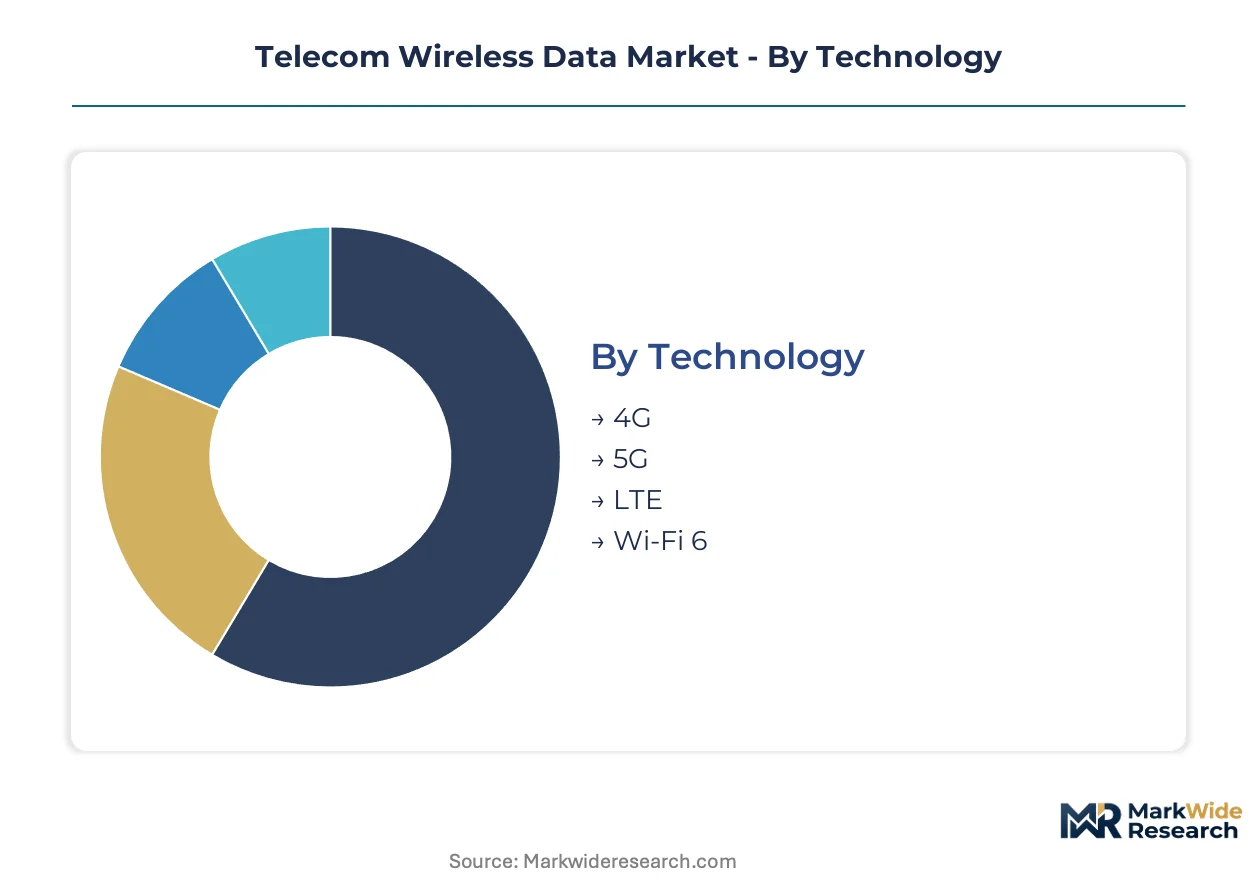
Segmentation in telecom wireless data reveals how spectrum licensing, infrastructure economics, and use-case requirements partition demand across distinct buyer groups and technical specifications. Carrier capital allocation and enterprise procurement strategies diverge sharply based on these dimensions.
Technology:
FCC spectrum auctions and MIIT equipment certification create divergent deployment timelines across radio access technologies, with mid-band licenses accelerating 5G rollouts while legacy 4G amortization stretches in emerging markets.
- 5G:Network slicing partitions bandwidth for deterministic industrial automation, with South Korean carriers deploying standalone architectures for manufacturing campus contracts. Enterprise demand for private network slices drives premium pricing over consumer mobile broadband.
- 4G:Carrier aggregation protocols extend equipment lifecycles in rural India and Southeast Asia where Universal Service Obligation subsidies prioritize coverage over latency. Bharti Airtel and Reliance Jio leverage existing spectrum holdings to minimize capital intensity per subscriber.
- LTE:Licensed assisted access blends unlicensed 5 GHz spectrum with anchored LTE carriers for indoor enterprise coverage where mmWave penetration fails.
- Wi-Fi 6:Orthogonal frequency-division multiple access reduces contention in dense stadium and convention center environments without licensed spectrum costs.
5G handles the majority of carrier infrastructure investment; Wi-Fi 6 is climbing the fastest on share as neutral host models expand.
End User:
Procurement scale and performance guarantees separate enterprise buyers from consumer segments, with German manufacturing conglomerates consolidating connectivity under single managed service contracts.
- Enterprises:Private 5G spectrum frameworks from Germany's BNetzA and Japan's MIC enable captive networks at automotive assembly plants and container terminals. Network slicing SLAs specify latency below 10 milliseconds for robotic quality control systems.
- Manufacturers:Mines in Australia and Chile procure standalone networks for equipment teleoperation, with packet-core virtualization enabling rapid service instantiation without carrier dependency.
- Consumers:Mobile broadband subscriptions concentrate ARPU in urban corridors where fiber trenching costs prevent wireline competition.
- Government:Critical infrastructure mandates under the EU AI Act require Common Criteria EAL4+ certification for network management systems processing automated traffic optimization.
Enterprises command the highest infrastructure investment per site; Manufacturers are expanding most quickly as resource extraction sectors digitize.
Service Type:
Revenue concentration and margin structure vary by payload characteristics, with data-intensive applications displacing voice-centric pricing models.
- Mobile Broadband:Dominates carrier revenue pools through tiered data allowances and speed-based pricing differentiation. T-Mobile US anchors industrial IoT contracts through mid-band depth while Verizon sustains premium positioning via millimeter-wave urban density.
- Data Services:Machine-to-machine communication across licensed and unlicensed spectrum bands enables predictive maintenance in logistics hubs and smart meter aggregation for utilities.
- Voice Services:VoLTE compression and packet-core efficiency improvements sustain voice as a bundled commodity with declining standalone ARPU.
- SMS:Application-to-person messaging for two-factor authentication and marketing retains utility despite over-the-top messaging displacement.
Mobile Broadband generates the dominant revenue pool; Data Services are gaining share fastest as IoT endpoints proliferate.
Deployment:
Infrastructure ownership models determine capital intensity and operational flexibility, with shared small-cell architectures fragmenting traditional carrier control.
- Private Network:Captive connectivity at factories and ports eliminates roaming dependencies and enables deterministic latency for automated guided vehicles. Edge computing convergence pairs ultra-reliable low-latency communication with distributed compute nodes.
- Hybrid Network:Campus-private cores with wide-area roaming fallback consolidate procurement under unified vendor relationships for Japanese manufacturing conglomerates.
- Public Network:Traditional carrier subscription models dominate consumer and small enterprise segments with standardized SLAs.
- Cloud-based:Containerized packet core implementations on commodity servers compress capital intensity per subscriber for tier-1 operators in South Korea and the United States.
Private Network deployment absorbs the fastest-growing infrastructure investment; Hybrid Network architectures are expanding most quickly as enterprises seek unified connectivity procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean carriers export network slicing architectures to German manufacturing conglomerates seeking deterministic latency for automotive assembly automation.
United States
T-Mobile US anchors industrial IoT contracts through mid-band spectrum depth across automotive campuses, while Verizon sustains premium positioning via millimeter-wave urban density. FCC spectrum auctions for C-band and mmWave blocks consume substantial carrier capex budgets. Dense deployments concentrate in Detroit automotive corridors and Dallas-Fort Worth logistics hubs.
Germany
BNetzA localized spectrum licenses enable captive private 5G networks at manufacturing sites and container terminals. EU AI Act cybersecurity certification mandates Common Criteria EAL4+ standards for network management systems. Industrial automation clusters in Bavaria and Baden-Württemberg drive enterprise procurement consolidation under unified vendor relationships.
China
MIIT coordinates GB standards for base station equipment and enforces dual carbon efficiency mandates accelerating legacy 4G depreciation. Domestic carriers deploy standalone 5G architectures for smart factory contracts. Equipment manufacturing concentrates in Shenzhen and Dongguan within the Pearl River Delta.
India
Bharti Airtel and Reliance Jio expand rural coverage through Universal Service Obligation Fund subsidies to capture mobile broadband subscribers. TRAI frameworks govern spectrum allocation and interconnection charges. Tower deployment accelerates in Maharashtra and Gujarat manufacturing belts alongside Karnataka's technology corridor.
Japan
MIC localized licenses support private campus networks at automotive assembly plants and container terminals. METI industrial policy prioritizes ultra-reliable low-latency communication for robotic quality control. Enterprise demand clusters in Toyota City manufacturing complexes and Yokohama port logistics facilities.
Telecom Wireless Data Market Competitive Landscape
Player mix skews toward national carrier incumbents with deep spectrum holdings and integrated infrastructure operations. Market structure concentrates around three strategic tiers: mid-band specialists leveraging propagation advantages for suburban and industrial coverage, millimeter-wave operators targeting dense urban throughput premiums, and converged fixed-mobile challengers substituting wireline broadband. Dominant competitive moves include spectrum portfolio swaps to fill geographic coverage gaps and cloud-native core virtualization to compress capital intensity per subscriber.
Within the national carrier tier, T-Mobile US exemplifies mid-band depth strategies, while Deutsche Telekom represents Open RAN interoperability approaches for European manufacturing clients. Bharti Airtel occupies a position as a rural expansion specialist in emerging market contexts. These carriers anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| T-Mobile US |
| Verizon |
| AT&T |
| China Mobile |
| Deutsche Telekom |
| China Telecom |
| SoftBank |
| Bharti Airtel |
| Vodafone |
| Others |
Value Network & Pricing Analysis
FCC equipment certification and EU AI Act cybersecurity mandates gate supplier qualification while simultaneously stratifying price tiers across network infrastructure procurement. These dual regulatory filters compress margins for uncertified vendors while enabling premium capture for pre-qualified suppliers serving critical infrastructure deployments.
Pricing Analysis
5G network slicing commands substantial premiums over legacy 4G data services and Wi-Fi 6 campus deployments due to deterministic latency guarantees. Three-tier pricing structure across premium enterprise slices, standard mobile broadband, and economy IoT connectivity reflects certification grade and service-level agreement stringency. Cost compression in consumer mobile broadband intensifies as Reliance Jio and Bharti Airtel expand rural coverage with subsidized infrastructure. Enterprise manufacturing buyers exhibit lowest price sensitivity, prioritizing latency performance over per-gigabyte costs.
Supply Chain Analysis
Strait of Malacca transit underwrites semiconductor component flows for baseband processors and radio-frequency front-end modules destined for Asian manufacturing hubs. Active antenna unit production concentrates in China, South Korea, and Finland, with gallium nitride power amplifiers and advanced substrates anchoring cost structures. Single-source vulnerability pervades massive MIMO radio unit supply, as three vendors dominate carrier-grade equipment. Distribution runs through carrier-direct procurement channels and systems integrator consortia for private network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Telecom Wireless Data Market is recovering from spectrum auction cost cyclicality, with carrier capex inflecting upward as 5G standalone architectures reach deployment maturity across industrial automation clusters.
For Market Incumbents: Consolidate spectrum portfolio depth through targeted swaps that fill mid-band coverage gaps in automotive manufacturing corridors. Deepen vendor diversification via Open RAN interoperability investments to reduce single-source dependency on concentrated radio equipment suppliers. Lock in multi-year enterprise slice contracts with German and Japanese manufacturing conglomerates before neutral host competitors capture campus connectivity procurement. For New Entrants and Emerging Players: Common Criteria EAL4+ pre-certification fast-tracks market access for cybersecurity-hardened network management systems under EU AI Act mandates. Target private 5G deployment at Australian mining operations and Chilean port logistics facilities where captive connectivity demand outstacks carrier service availability. Pursue systems integrator partnerships rather than direct carrier competition to bypass spectrum ownership barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native packet core virtualization as containerized platforms displace proprietary hardware appliances. Long-term viability favors vendors with software-centric margin structures and recurring enterprise slice revenue over hardware-dependent equipment manufacturers. Monitor Open RAN interoperability certification timelines as inflection indicator for vendor ecosystem reordering.| Strategic Initiative | Industry Significance |
|---|---|
| Network Slicing Commercialization | Enables deterministic SLAs for robotic quality control at Toyota City manufacturing complexes. |
| Open RAN Interoperability Certification | Fragments vendor lock-in and accelerates Deutsche Telekom's multi-supplier campus deployments. |
| Edge Computing Node Co-location | Pairs ultra-reliable low-latency communication with distributed compute at Yokohama port facilities. |
| Private Spectrum License Acquisition | Captures captive connectivity revenue from BNetzA and MIC localized framework allocations. |
| Cloud-Native Core Virtualization | Compresses capital intensity per subscriber for T-Mobile US and South Korean tier-1 operators. |
Research Methodology
Initial hypotheses were tested against primary input from carrier network planning executives, enterprise IT procurement directors, base station equipment vendors, and regulatory affairs specialists at spectrum authorities, then refined against secondary validation. FCC auction records, TRAI tariff orders, MIIT equipment certification databases, and carrier SEC 10-K infrastructure disclosure filings anchored quantitative sizing. Bottom-up subscriber and traffic forecasts triangulated against top-down spectrum allocation and capex trajectory analysis.
Variance-decomposition framing isolated technology migration pace, enterprise slice adoption curves, and regulatory timeline uncertainty as primary forecast sensitivity drivers. Segmentation modeling spanned radio access technology generation, end-user archetype, service payload type, and deployment ownership structure across the analysis window. CAGRs derived from logistic diffusion curves fitted to historical technology transition patterns, with inputs from equipment vendor order backlogs and carrier guidance commentary.
Decision-makers should treat outputs as directional under sustained carrier capex commitment and spectrum auction schedule assumptions; material deviation would warrant model refresh. Specific risk factors include Open RAN interoperability delays, energy efficiency mandate acceleration under MIIT dual carbon goals, and rural subsidy program modifications in India. Practitioners should keep alternative scenarios live as private network procurement consolidation patterns and neutral host infrastructure economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Multefire Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Wi-Fi 7 Market