
 Global Mobile User Interface Services Market | 2026-2036
Global Mobile User Interface Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile User Interface Services Market Outlook
Asset-light subscription and pay-per-sprint financing is rewriting competitive entry barriers in mobile UI services. Brainvire Infotech leverages its offshore delivery model to sustain margin advantages across North American healthcare accounts. Octal IT Solution anchors its positioning through deep specialization in cross-platform React Native implementations. Classic Informatics competes on design-led differentiation rather than pure development scale.
Mobile user interface services encompass the design, engineering, and optimization of visual interaction layers for handheld devices, typically delivered through component-based architectures with pixel-density responsiveness and touch-gesture mapping. These services enable commercial entities to deploy consistent brand experiences across iOS and Android ecosystems while reducing native rebuild cycles. Cross-platform technology commands the widest deployment footprint, though native development retains premium pricing in performance-sensitive entertainment and healthcare verticals. Enterprise client types generate the largest contract values, while startup demand concentrates in rapid-prototype design and minimum-viable-product testing phases.
FDA guidelines on mobile health application interfaces, EU GDPR requirements for consent-driven personalization, and India's TRAI data-privacy consultations collectively elevate compliance costs for UI service providers. The EU AI Act further constrains automated interface adaptation using behavioral biometrics, forcing architectural redesigns for European deployments. Stakeholders must weigh regulatory fragmentation against platform standardization when selecting technology stacks and geographic delivery centers.
Market Dynamics
Cross-platform UI frameworks are compressing development cycles while fragmenting vendor differentiation, forcing service providers to pivot from code volume toward design-system IP and regulatory compliance capabilities.
Growth Catalysts
- GDPR consent architecture:European mandates for granular data permissioning are creating specialized demand for privacy-by-design interface layers that healthcare and financial services clients cannot build in-house.
- React Native maturation:The framework's native module bridging now supports performance-critical healthcare diagnostics interfaces previously requiring pure Swift or Kotlin development.
- India's healthcare digitization:CDSCO and NHA interoperability mandates are accelerating tender volumes for compliant mobile front-ends across public hospital networks.
Market Restraints
- Silicon design-tool licensing:Figma and Adobe XD subscription cost inflation is squeezing margin at mid-tier agencies without enterprise volume discounts.
- EU AI Act biometric constraints:Behavioral authentication interfaces face architectural redesign requirements that extend European delivery timelines by 30-40%.
- Native development talent scarcity:Swift and Kotlin specialists command premium rates that cross-platform projects cannot absorb, concentrating high-performance work with incumbents.
Strategic Opportunities
- Brazil's ANVISA digital health pathway:Streamlined mobile medical device interface approvals are opening Latin America's largest healthcare market to specialized UI vendors.
- Voice-gesture convergence:Integration of Alexa Custom Assistant with haptic feedback layers is creating new interface categories for automotive and industrial wearables.
- Outcome-based pricing models:Subscription structures tied to user engagement metrics are displacing fixed-scope contracts in North American enterprise accounts.
Industry Challenges
- Accessibility certification backlog:WCAG 2.2 AA compliance testing queues at third-party auditors are delaying product launches for US healthcare clients.
- Legacy EMR integration complexity:Epic and Cerner API fragmentation forces custom middleware development that consumes 25-35% of project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile User Interface Services Market |
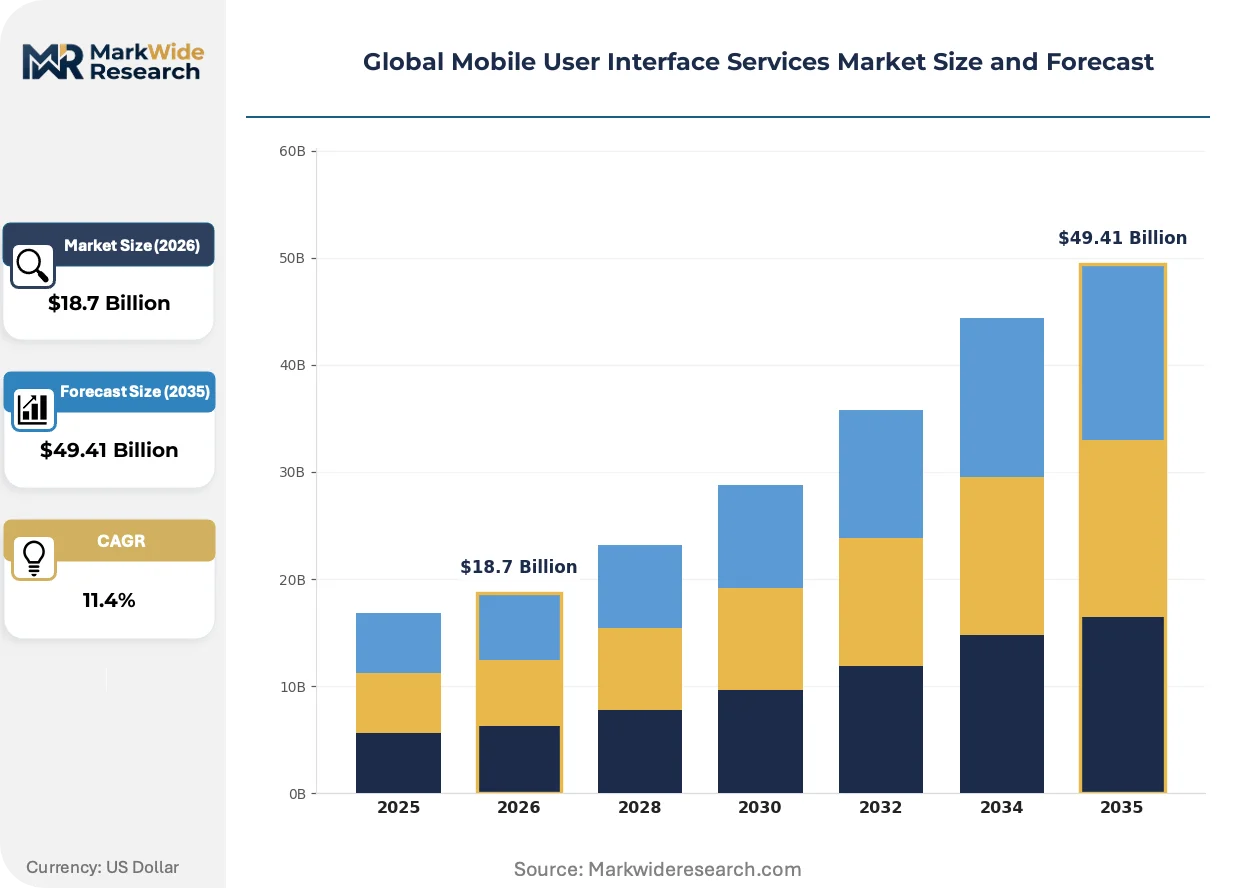
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Development, Testing, Consulting Client Type: Startups, Enterprises, Agencies, Freelancers Technology: Native, Hybrid, Web-Based, Cross-Platform End User: Healthcare, Retail, Education, Entertainment |
| Companies Covered | Sapphire Software Solutions, Webkul, Aalpha Information Systems, IT-Geeks, Brainvire Infotech, Octal IT Solution, Capital Numbers, Classic Informatics, Andersen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile User Interface Services Market Strategic Shifts
Interface delivery is bifurcating between commodity cross-platform builds and premium immersive experiences, with regulatory compliance emerging as the decisive vendor selection criterion in regulated verticals.
Spatial computing toolkits from Apple and Meta are virtualizing gesture-based interaction design for healthcare surgical planning and automotive HMI prototyping. Medical device manufacturers in the United States are piloting visionOS interfaces for pre-operative visualization, compressing the traditional 18-month hardware-software co-development cycle into parallel digital validation tracks.
EU AI Act Article 52 transparency mandates are forcing algorithmic interface components to expose decision logic to end-users. Automated personalization engines in German and French banking applications must now render explanatory overlays, increasing front-end payload complexity but creating compliance-first vendor differentiation.
Enterprise procurement teams are consolidating vendor rosters around design-system ownership rather than project-based engagement. North American healthcare networks are licensing component libraries outright, displacing time-and-materials relationships with perpetual-usage agreements that transfer IP risk to service providers.
Global Mobile User Interface Services Market Segmentation
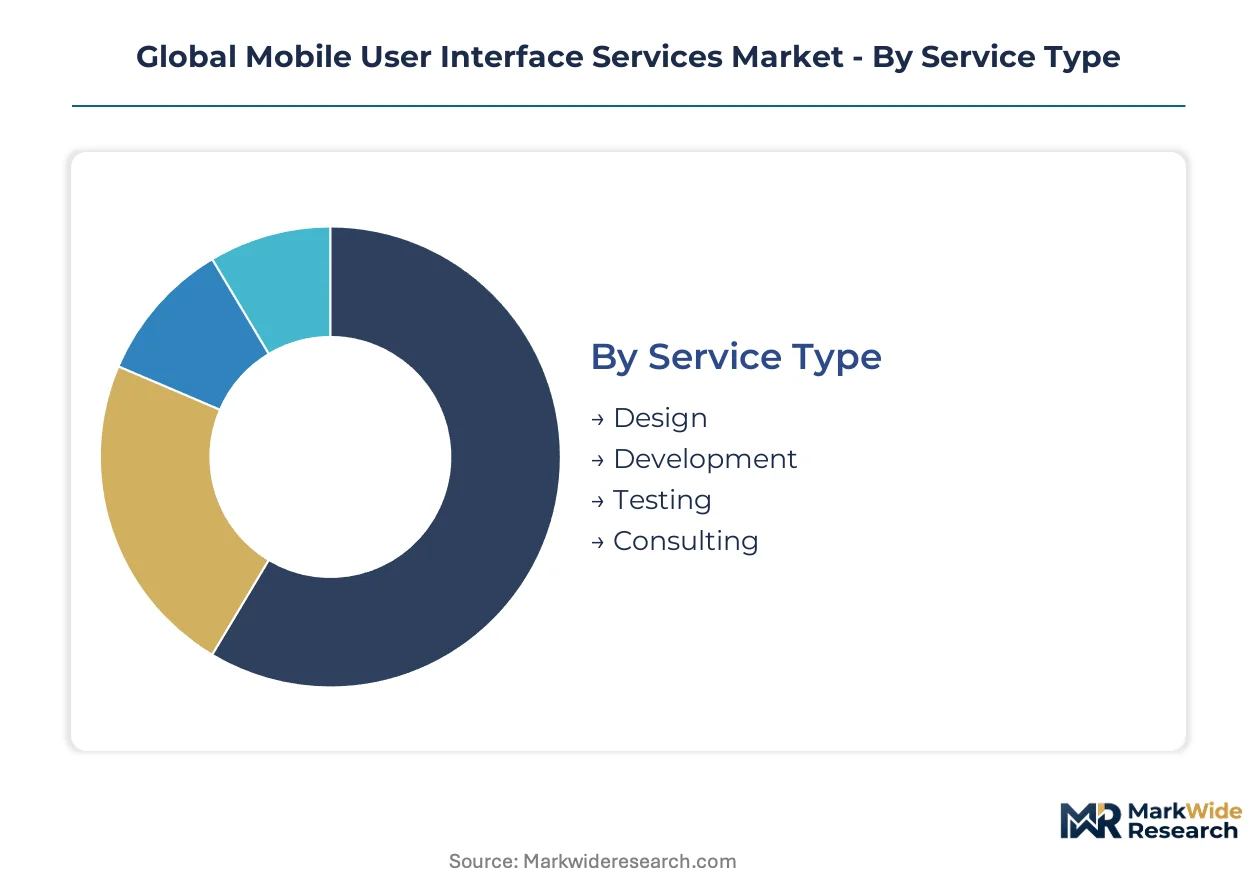
Mobile UI services fragment across four operational dimensions that determine pricing architecture and delivery model selection. Service type dictates talent composition and project cadence, while technology stack selection locks in performance ceilings and regulatory compliance pathways.
Service Type:
After-sales service intensity varies dramatically across service categories, with maintenance retainers and iterative optimization creating recurring revenue pools that pure design shops cannot access.
- Design:Component library creation and design-system governance require specialized interaction designers with healthcare and financial services domain expertise. FDA and GDPR consent-layer specifications are concentrating demand in the United States and Germany where regulatory stringency elevates premium pricing.
- Development:Engineering services bridge visual specifications to deployable code through React Native, Swift, or Kotlin implementations. India's healthcare digitization tenders and Brazil's ANVISA pathway are accelerating contract velocity for compliant front-end builds.
- Testing:WCAG 2.2 AA certification and biometric interface validation for EU AI Act compliance extend delivery timelines significantly.
- Consulting:Strategic advisory on technology stack selection and regulatory roadmap planning commands highest hourly rates.
By volume, Development leads. By growth pace, Consulting is ahead.
Client Type:
Customer procurement sophistication determines contract structure, with enterprise buyers demanding IP transfer and outcome-based pricing that startups cannot negotiate.
- Enterprises:Healthcare networks and financial institutions license design-system IP outright, displacing time-and-materials relationships with perpetual-usage agreements. Epic and Cerner integration complexity consumes substantial project budgets.
- Startups:Rapid-prototype design and minimum-viable-product testing phases concentrate demand here, with compressed timelines favoring cross-platform frameworks over native development.
- Agencies:White-label development partnerships and staff augmentation models dominate this segment.
- Freelancers:Individual practitioners compete on cost for commodity UI component builds without regulatory compliance requirements.
Enterprises generate largest contract values. Startups expand most quickly.
Technology:
Stack selection locks in performance characteristics and talent cost structures that persist through product lifecycle.
- Cross-Platform:React Native maturation now supports performance-critical healthcare diagnostics interfaces previously requiring pure native code. Framework bridging capabilities are compressing development cycles across United States and Indian delivery centers.
- Native:Swift and Kotlin implementations retain premium pricing in entertainment and healthcare verticals where frame-rate sensitivity and biometric authentication performance are non-negotiable. Talent scarcity concentrates high-performance work with established incumbents.
- Hybrid:Web-view containers with native wrapper deployment suit internal enterprise tools with limited device hardware access requirements.
- Web-Based:Progressive web applications bypass app store approval processes for content-heavy experiences without native feature dependencies.
Cross-Platform dominates deployment footprint. Native commands highest pricing tier.
End User:
Vertical regulatory intensity determines compliance architecture and vendor qualification requirements.
- Healthcare:FDA mobile health application guidelines, EU MDR interface requirements, and India's CDSCO interoperability mandates create specialized demand for privacy-by-design interface layers. North American hospital networks represent the fastest-concentrating demand pool.
- Retail:Personalization engine deployment for recommendation interfaces faces EU AI Act transparency mandates requiring explanatory overlay architecture.
- Entertainment:Frame-rate optimization and haptic feedback integration drive native development preference despite higher cost structure.
- Education:Accessibility-first design for diverse learner populations prioritizes WCAG compliance without biometric data handling complexity.
Healthcare leads contract value concentration. Retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where regulatory complexity commands premium rates, while Indian delivery centers compete on velocity and margin compression. This asymmetry shapes vendor footprint decisions across the value chain.
United States
FDA mobile health application guidelines and Epic-Cerner integration complexity drive contract values upward. HIPAA consent-layer specifications elevate demand for privacy-by-design specialists. Hospital networks in the Boston-Cambridge corridor and Silicon Valley cluster are licensing design-system IP outright rather than engaging project-based vendors.
Germany
EU AI Act transparency mandates and GDPR granular permissioning requirements extend delivery timelines by 30-40%. Automotive OEMs in Stuttgart and Munich are piloting voice-gesture convergence interfaces for next-generation HMI systems. The country's national data protection regulator enforces biometric authentication constraints that force architectural redesigns.
India
CDSCO interoperability mandates and NHA tender volumes accelerate public hospital network digitization. TRAI data-privacy consultations are elevating compliance costs for domestic vendors. Bengaluru and Hyderabad delivery centers leverage React Native maturation to compress healthcare diagnostics development cycles previously requiring native code.
Brazil
ANVISA streamlined mobile medical device interface approvals open Latin America's largest healthcare market. São Paulo-based vendors are capturing cross-border contracts from US and European clients seeking cost-advantaged compliance pathways. The country's national health surveillance agency is harmonizing digital health standards with FDA and EU MDR frameworks.
United Kingdom
Financial services personalization engines face EU AI Act explanatory overlay requirements despite post-Brexit regulatory divergence. London fintech clusters are consolidating vendor rosters around design-system ownership rather than time-and-materials relationships. The Financial Conduct Authority is consulting on algorithmic interface transparency rules that mirror Brussels standards.
Global Mobile User Interface Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope but defensible margin. The vendor base spans three tiers: global consultancies with regulatory compliance practices, offshore delivery specialists with healthcare domain expertise, and boutique design studios competing on aesthetic differentiation. Consolidation pressure favors players with design-system IP and perpetual-usage licensing capabilities. Geographic expansion and outcome-based pricing model adoption represent the dominant competitive vectors reshaping contract structures.
Within the offshore delivery tier, Brainvire Infotech and Octal IT Solution exemplify margin-sustainable positioning across North American healthcare accounts. Classic Informatics occupies a design-led differentiation niche rather than competing on pure development scale. These three anchors illustrate the strategic bifurcation between velocity-driven engineering and compliance-intensive creative services.
| Leading Market Players |
|---|
| Sapphire Software Solutions |
| Webkul |
| Aalpha Information Systems |
| IT-Geeks |
| Brainvire Infotech |
| Octal IT Solution |
| Capital Numbers |
| Classic Informatics |
| Andersen |
| Others |
Value Chain & Pricing Dynamics
GDPR consent-layer complexity and EU AI Act biometric constraints determine both pricing tier spreads and supply chain shape, forcing vendors to choose between premium compliance-first positioning in Germany and velocity-driven delivery from Indian centers. Healthcare networks in the United States absorb 30-40% timeline extensions for regulatory validation, while Brazilian ANVISA pathways attract cost-sensitive buyers seeking streamlined approvals.
Pricing Analysis
Enterprise healthcare buyers anchor a three-tier pricing structure across premium native development, standard cross-platform implementation, and economy rapid-prototype tiers. Price differentiation stems from FDA certification grade and Epic-Cerner integration complexity. Cost compression in the economy tier is intensifying because Figma and Adobe XD subscription inflation squeezes mid-tier agencies without enterprise volume discounts. Startup segments exhibit highest price sensitivity; hospital networks purchasing perpetual design-system IP show least.
Supply Chain Analysis
Tariff exposure between the United States and India on specialized healthcare IT talent dominates supply chain risk assessment for North American client delivery. Engineering capacity concentrates in India, the United States, and Germany, with Bengaluru and Hyderabad centers feeding cross-platform development velocity. Raw material dependencies include Figma design-tool licensing, React Native framework maintenance, and WCAG certification auditor capacity. Single-source vulnerability in accessibility certification testing extends delivery timelines. Distribution runs through direct enterprise sales teams and white-label agency partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile UI services sit in early-cycle expansion as healthcare digitization mandates across India, Brazil, and the United States accelerate tender volumes for compliant front-end builds. Regulatory fragmentation creates vendor selection premiums that favor compliance-capable incumbents.
For Market Incumbents: Harden design-system IP ownership against emerging platform-agnostic competitors by licensing component libraries through perpetual-usage agreements that transfer compliance risk to clients. Expand native Swift and Kotlin capacity in the United States to capture premium pricing for FDA-validated healthcare diagnostics interfaces. Certification investment in WCAG 2.2 AA and EU AI Act transparency architecture defends margin position against offshore velocity players. For New Entrants and Emerging Players: Build out specialized GDPR consent-layer implementation practices targeting German financial services and healthcare verticals where regulatory stringency blocks commodity competition. Brazil's ANVISA streamlined pathway represents the most penetrable geography for cost-advantaged compliance positioning. Channel partnership with São Paulo-based vendors already capturing cross-border contracts accelerates market entry without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: EU AI Act Article 52 transparency mandates reshape the acquisition landscape toward vendors with explanatory overlay architecture and algorithmic interface audit capabilities. Long-term viability favors design-system IP owners with healthcare domain expertise over pure development shops. The signal to watch is hospital network procurement consolidation around perpetual-usage licensing versus time-and-materials relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Design-System IP Acquisition | Perpetual-usage licensing transfers compliance risk to healthcare network clients. |
| Regulatory Compliance Certification | WCAG 2.2 AA and EU AI Act validation opens German and US hospital procurement. |
| Cross-Platform Framework Specialization | React Native maturation compresses healthcare diagnostics development cycles. |
| Geographic Delivery Expansion | Brazilian ANVISA pathway captures Latin American healthcare digitization tenders. |
| Outcome-Based Pricing Transition | Subscription structures tied to engagement metrics displace fixed-scope contracts. |
Study Parameters
Operator-level perspectives from CTOs at healthcare networks, UI/UX directors at financial services firms, procurement leads at hospital GPOs, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA mobile health application filings, EU AI Act implementation guidance, CDSCO interoperability mandates, and ANVISA digital health pathway documentation. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates across the analysis window.
Scenario-bracketing framed the analytical approach across regulatory acceleration, framework maturation, and talent cost inflation pathways. Segmentation dimensions modeled include service type, client archetype, technology stack, and end-user vertical with geographic delivery center overlay. CAGRs derived from weighted average of historical contract velocity and forward tender pipeline analysis. React Native framework adoption curves and Epic-Cerner integration complexity indices served as industry-specific forecast inputs throughout the projection horizon.
Stress conditions across GDPR enforcement intensity, FDA guidance revision timing, and design-tool licensing cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization trajectories and framework performance ceilings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Visualization Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Driving School Software Market
Software & Services
Customs Declaration Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Global Online Proofing Software Market
Software & Services
Middleware Market
Software & Services
Global Document Management Software Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Vlog Editing Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Enterprise-Grade Saas Market