
 Europe Wireless Microphone Market | 2026-2036
Europe Wireless Microphone Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wireless Microphone Market Analytics
Buyer concentration across European live performance venues and broadcast houses is restructuring procurement patterns toward multi-channel digital ecosystems. Shure Incorporated leverages its established channel relationships across touring and installed sound to sustain premium positioning. Sennheiser electronic GmbH & Co. KG anchors its competitive stance through deep R&D investment in spectral efficiency and RF reliability. Audio-Technica Corporation competes aggressively on value-engineered digital platforms targeting mid-tier corporate and education buyers.
A wireless microphone system comprises a transmitter, receiver, and microphone element operating across licensed or license-exempt radio frequency bands, typically between 470 and 694 MHz in Europe, with digital variants employing advanced modulation schemes to maximize channel density in congested spectrum. Its primary purpose is to deliver untethered audio capture for professional entertainment, broadcast journalism, and institutional communication where cable runs prove impractical. Handheld configurations dominate live performance revenue owing to vocalist preference and rental fleet standardization, while lavalier demand accelerates in broadcasting and corporate video production as multi-camera workflows proliferate. Digital technology leads new system sales as analog inventories face obsolescence pressure from ongoing spectrum reallocation mandates.
The EU Radio Equipment Directive establishes baseline conformity requirements for RF equipment marketed across member states, while national regulators such as Ofcom in the United Kingdom and BNetzA in Germany administer specific frequency assignments and white-space database rules that directly constrain product operability. CE marking under RED and adherence to evolving ETSI standards determine market access viability for non-European manufacturers. Stakeholders must monitor pending spectrum auction outcomes and harmonized standard revisions to anticipate inventory obsolescence cycles and certification timelines.
Market Dynamics
The EU Radio Equipment Directive and national spectrum reallocations are compressing analog inventory lifecycles while accelerating digital wireless platform turnover across European live performance venues and broadcast infrastructure.
Growth Catalysts
- Digital modulation advancement:Advanced modulation schemes maximize channel density in congested 470-694 MHz spectrum, enabling multi-channel digital ecosystems in touring and installed sound applications.
- Live performance venue expansion:German concert halls and theaters are expanding procurement of digital wireless systems to replace aging analog fleets ahead of regulatory deadlines.
- Broadcast infrastructure modernization:Multi-camera workflows proliferating across UK and French television production accelerate lavalier microphone demand for untethered talent audio.
Market Restraints
- RF spectrum scarcity:Ongoing 700 MHz band clearance for mobile broadband services across EU member states reduces available wireless microphone frequencies and forces hardware replacement cycles.
- Certification cost burden:CE marking under RED and evolving ETSI standards impose recurring compliance expenses on manufacturers, particularly affecting smaller equipment vendors.
- Component supply concentration:RF chipset fabrication concentrates in East Asian foundries, exposing European system integrators to lead-time volatility and currency fluctuation risk.
Strategic Opportunities
- White-space database integration:Ofcom's TV white-space pilot programs in the United Kingdom create openings for cognitive radio-enabled microphones that dynamically access unused spectrum.
- Corporate education vertical:Underpenetrated mid-tier corporate and institutional training facilities across Poland and Spain present volume opportunities for value-engineered digital platforms.
- EU Green Deal alignment:Ecodesign requirements emerging under European sustainability frameworks reward manufacturers with repairable, energy-efficient RF architectures and extended product lifecycles.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in spectral efficiency and interference mitigation is concentrating among legacy broadcast engineers approaching retirement, constraining vendor R&D expansion.
- Legacy system integration friction:Hybrid analog-digital environments in historic European venues require complex frequency coordination and antenna distribution reconfiguration during phased upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wireless Microphone Market |
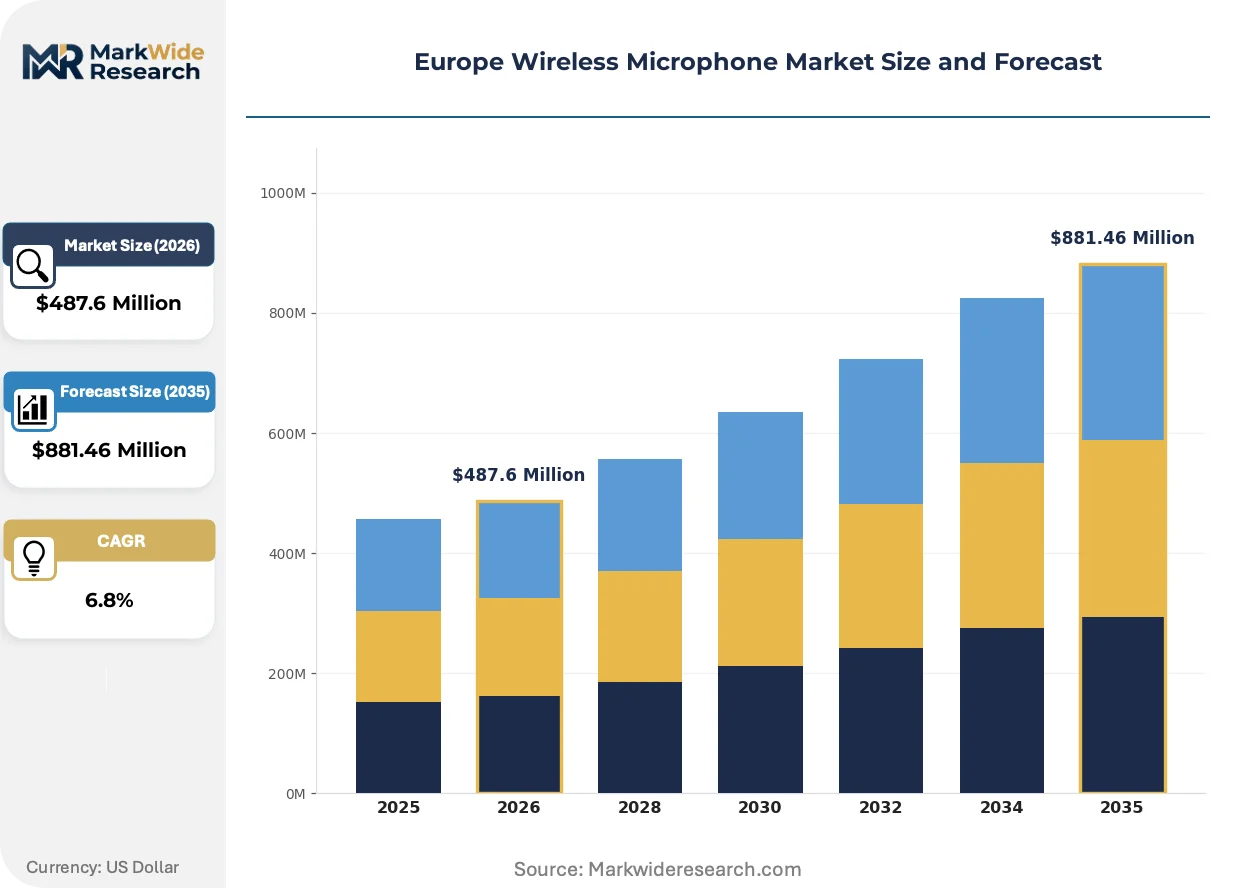
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Lavalier, Headset, Instrument Application: Live Performance, Broadcasting, Corporate Events, Education Technology: Frequency Modulation, Infrared, Digital, Analog End User: Musicians, Podcasters, Educators, Presenters |
| Companies Covered | Shure Incorporated, Sennheiser electronic GmbH & Co. KG, Audio-Technica Corporation, Sony Corporation, AKG Acoustics GmbH, Lectrosonics, Yamaha Corporation, RØDE Microphones, LEWITT GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wireless Microphone Market Evolving Landscape
Digital wireless architectures are unifying audio transport, control, and monitoring functions while spectrum policy and procurement patterns compress equipment replacement timelines across European entertainment infrastructure.
Spectral coexistence technology is unifying automated frequency coordination with networked receiver management. Major touring productions and broadcast rental houses in Germany and France are adopting these integrated platforms to reduce setup complexity. This unification is compressing the competitive advantage of standalone spectrum analyzer vendors and shifting value toward full-stack system providers.
CE marking under RED is tightening electromagnetic compatibility and RF exposure requirements for equipment marketed across member states. Manufacturers must now demonstrate compliance with harmonized ETSI standards that exceed prior national certification thresholds. Handheld and bodypack transmitters face the steepest redesign obligations as SAR testing protocols expand to professional audio devices.
Equipment-as-a-service models are displacing capital purchase patterns among mid-sized European rental companies and regional theater chains. Monthly subscription arrangements for multi-channel digital systems include firmware updates and spectrum reconfiguration support. This shift is most visible in the United Kingdom where Ofcom's dynamic frequency assignment policies create ongoing compliance service demand.
Europe Wireless Microphone Market Segmentation
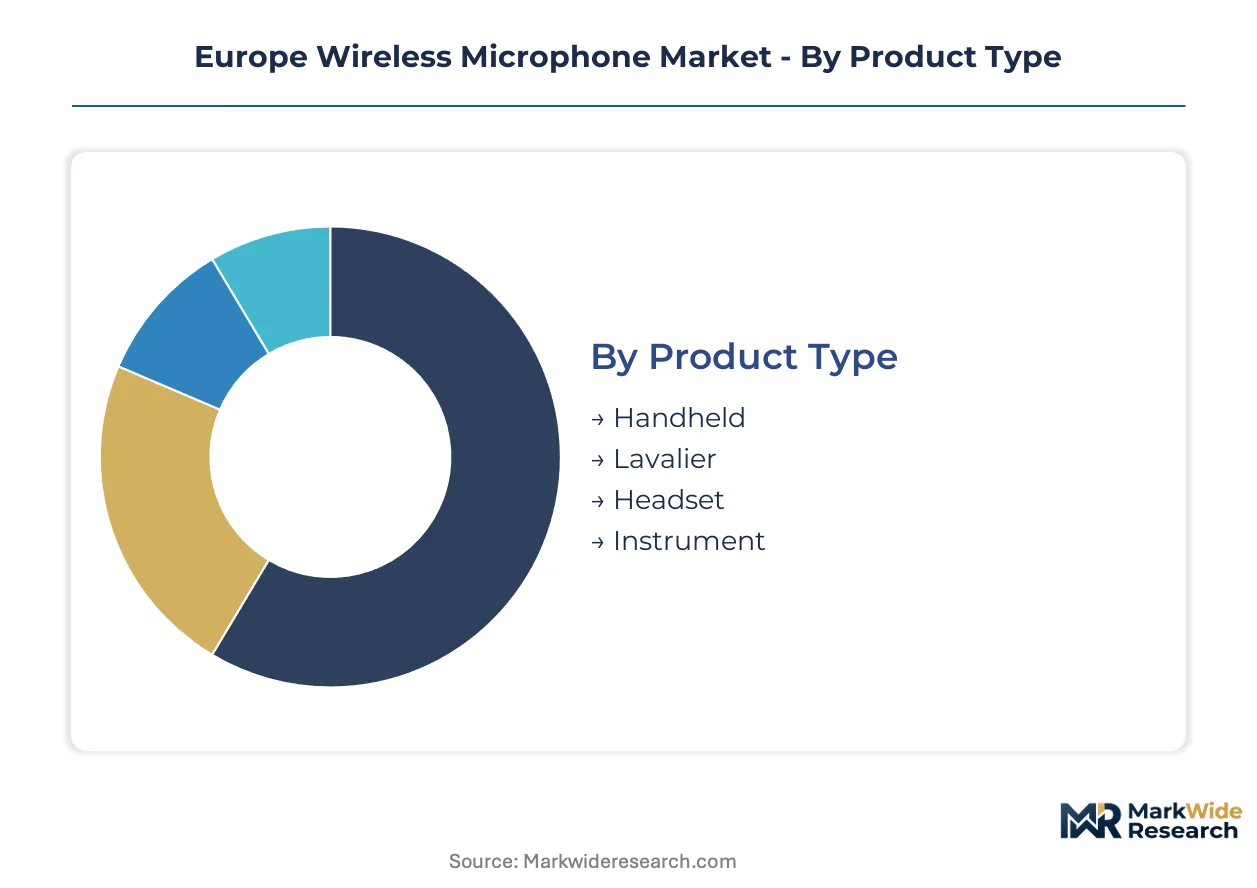
Wireless microphone procurement across Europe follows distinct technical and use-case logics that reshape vendor positioning. Buyers prioritize spectral efficiency, form-factor ergonomics, and integration complexity differently across live performance, broadcast, and institutional environments.
Product Type:
Stage ergonomics and talent mobility requirements dominate buyer selection criteria across German concert halls and UK broadcast studios.
- Handheld:Vocalist preference for tactile control and visual stage presence drives specification. German touring productions and rental fleets standardize on ruggedized metal chassis designs with interchangeable capsule architectures.
- Lavalier:Concealment demands in multi-camera television workflows accelerate specification. French broadcast houses and UK production companies prioritize moisture-resistant omnidirectional elements for talent comfort during extended shoots.
- Headset:Fitness instructors and theater performers across Spain and Italy favor secure-fit designs eliminating hand-held positioning constraints.
- Instrument:Specialized clip-on and contact microphone configurations serve orchestral and amplified ensemble applications in Austrian and Dutch performance venues.
Volume sits with Handheld systems; growth tilts toward Lavalier configurations.
Application:
Regulatory pressure and workflow digitization are compressing replacement timelines unevenly across European verticals.
- Live Performance:Spectrum reallocation mandates in Germany and France force hardware turnover in historic venues. Multi-channel digital ecosystems replace aging analog inventories ahead of BNetzA and ANSM deadlines.
- Broadcasting:Multi-camera production proliferation across UK and French television networks demands untethered talent audio. Lavalier and headset configurations dominate procurement for news and entertainment programming.
- Corporate Events:Hybrid meeting permanence post-pandemic drives installed sound upgrades in underpenetrated Polish and Spanish conference facilities.
- Education:Mid-tier institutional budgets across Italy and Portugal favor value-engineered digital platforms for lecture capture and campus event production.
Live Performance commands the largest installed base; Broadcasting exhibits the steepest expansion trajectory.
Technology:
Spectral policy and RF reliability standards determine platform viability across EU member state regulatory regimes.
- Digital:Advanced modulation schemes maximize channel density in congested 470-694 MHz spectrum. CE marking under RED and evolving ETSI standards accelerate displacement of analog inventories.
- Analog:Legacy fleet obsolescence pressure intensifies as 700 MHz clearance for mobile broadband services reduces available frequencies. Historic venue infrastructure faces complex hybrid upgrade paths.
- Frequency Modulation:Narrowband FM architectures persist in budget-conscious education and small venue applications across Eastern Europe.
- Infrared:Secure, spectrum-independent operation attracts confidential corporate and government briefing room installations in Switzerland and Luxembourg.
Digital platforms absorb the majority of new system sales; Infrared carves defensive niches in security-sensitive environments.
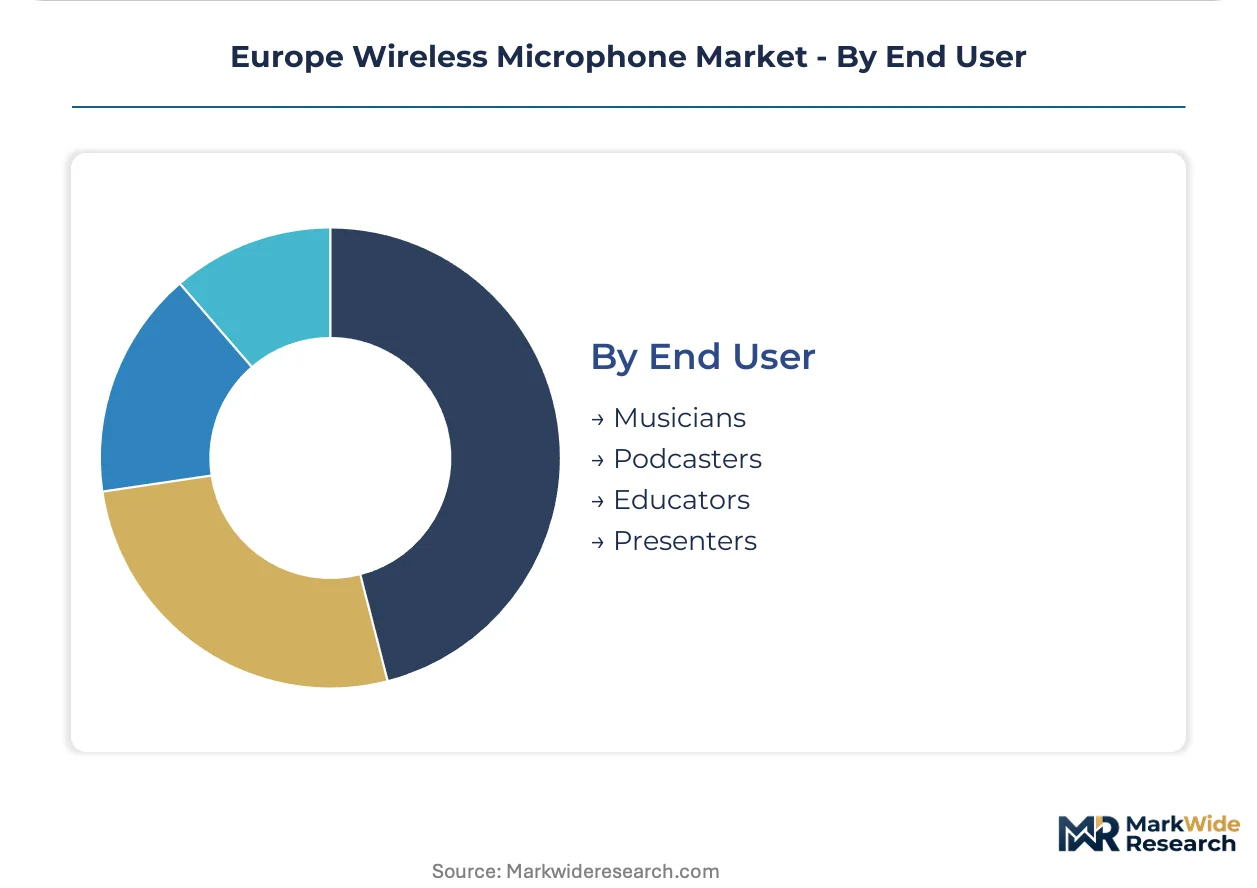
End User:
Professional identity and technical sophistication shape purchasing authority and specification complexity across buyer personas.
- Musicians:Touring artists and resident ensembles prioritize sonic transparency and road-durable construction. German and UK rental houses stock standardized multi-channel configurations reducing tour-to-venue compatibility friction.
- Podcasters:Independent content creators and studio operators across France and the Netherlands favor plug-and-play digital systems with minimal RF engineering expertise requirements.
- Educators:K-12 and university AV departments in Spain and Poland balance budget constraints against durability demands in high-use institutional settings.
- Presenters:Corporate executives and public speakers prioritize discreet form factors and rapid deployment simplicity for conference and keynote applications.
Musicians represent the most equipment-intensive user category; Podcasters are gaining share fastest among emerging buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European demand concentrates in Germany, the United Kingdom, and France as these markets host the continent's largest broadcast and entertainment infrastructure. National spectrum regulators are compressing equipment replacement timelines unevenly across member states.
Germany
BNetzA spectrum reallocation mandates are forcing hardware turnover in historic Berlin and Munich performance venues. The Federal Network Administration's 700 MHz clearance deadlines accelerate digital wireless procurement for touring productions. Bavarian concert halls and North Rhine-Westphalian broadcast centers anchor multi-channel system deployments.
United Kingdom
Ofcom's dynamic frequency assignment policies create ongoing compliance service demand among London rental houses and regional theater chains. TV white-space pilot programs enable cognitive radio-enabled microphone trials. Manchester and Birmingham production facilities are standardizing on networked receiver management platforms.
France
ANSM frequency coordination requirements reshape Parisian broadcast studio procurement patterns. Multi-camera television workflows across Île-de-France accelerate lavalier microphone specification for untethered talent audio. Lyon and Marseille live performance venues face phased analog-to-digital upgrade obligations.
Italy
Rai Way infrastructure modernization drives lavalier and headset demand across Milan and Rome television production centers. The Ministry of Economic Development's spectrum harmonization timelines compress equipment replacement budgets. Venetian historic theaters confront complex hybrid upgrade paths for integrated sound systems.
Spain
Underpenetrated corporate and institutional training facilities across Madrid and Barcelona present volume opportunities for value-engineered digital platforms. The National Markets and Competition Commission's pending spectrum auction outcomes determine inventory obsolescence cycles. Catalan broadcast operators prioritize moisture-resistant microphone elements for outdoor production workflows.
Europe Wireless Microphone Market Competitive Landscape
German producers anchor one tier; Japanese and American specialists hold differentiated positions in component architecture and broadcast integration. The vendor base structures around three tiers: full-stack system providers, RF component specialists, and value-engineered platform vendors. Consolidation pressure intensifies as spectrum compliance costs favor scaled R&D operations. Dominant competitive moves include strategic partnerships for white-space database integration and portfolio diversification into networked audio ecosystems.
Within the full-stack system tier, Shure Incorporated and Sennheiser electronic GmbH & Co. KG exemplify divergent geographic anchoring strategies—American road-durability heritage against German spectral efficiency engineering. Audio-Technica Corporation occupies a position bridging premium broadcast specification with mid-tier institutional accessibility. These three represent archetypes that smaller specialists must navigate: proprietary ecosystem lock-in, RF reliability certification, or aggressive value engineering.
| Leading Market Players |
|---|
| Shure Incorporated |
| Sennheiser electronic GmbH & Co. KG |
| Audio-Technica Corporation |
| Sony Corporation |
| AKG Acoustics GmbH |
| Lectrosonics |
| Yamaha Corporation |
| RØDE Microphones |
| LEWITT GmbH |
| Others |
Value Network & Pricing Analysis
Premium-standard bifurcation between touring-grade digital ecosystems and mid-tier institutional platforms manifests in divergent margin structures and sourcing strategies across European wireless microphone procurement. CE marking tier and RF chipset provenance separate price bands, with German and UK rental houses absorbing premium positioning while Polish and Spanish education buyers drive volume at compressed margins.
Pricing Analysis
Volume concentrates in mid-tier digital systems while margins accrue to multi-channel touring configurations with integrated spectrum management. Price differentiation hinges on ETSI certification tier and after-sales service bundling, with SaaS-style firmware subscription models gaining traction among UK rental operators. Cost compression in the mid-tier intensifies as Audio-Technica and value-engineered competitors expand Polish and Spanish market presence. Corporate education buyers exhibit highest price sensitivity; broadcast rental houses in France and Germany demonstrate lowest sensitivity due to workflow-critical reliability requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for RF chipset fabrication, constraining European system integrators during foundry allocation cycles. RF transceivers, precision oscillators, and lithium-polymer cells draw from East Asian supply bases, exposing vendors to logistics chokepoint risk through Rotterdam and Hamburg port clusters. Distribution runs through specialized AV distributors in Düsseldorf and London, with direct OEM relationships penetrating large German broadcast houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's wireless microphone sector sits in an analog-to-digital transition phase as spectrum reallocation mandates render legacy FM systems obsolete. Digital modulation platforms with automated frequency coordination are displacing hybrid analog-digital inventories across German and UK live performance infrastructure.
For Market Incumbents: To counter margin erosion from value-engineered competitors, deepen backward integration into RF module design and establish captive repair facilities in the Netherlands to satisfy EU Green Deal serviceability requirements. Lock channel control through exclusive spectrum reconfiguration service contracts with UK rental houses navigating Ofcom's dynamic assignment policies. For New Entrants and Emerging Players: Begin with underpenetrated corporate training facilities in Barcelona and Warsaw, where hybrid meeting permanence drives installed sound upgrades without incumbent loyalty. Position around plug-and-play digital systems requiring minimal RF engineering expertise, targeting independent podcasters and mid-tier education AV departments with transparent pricing and rapid deployment support. For Investors and Strategic Acquirers: Re-rating potential sits with RF software specialists possessing white-space database integration capabilities given Ofcom's cognitive radio pilot expansion. Prioritize acquisition targets with ETSI pre-certification pipelines and established German broadcast relationships. Monitor BNetzA spectrum auction timelines as inflection indicators for inventory obsolescence-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| White-Space Database Integration | Ofcom's pilot programs enable cognitive radio-enabled microphones to access unused spectrum dynamically. |
| RF Module Backward Integration | In-house transceiver design reduces exposure to Taiwan foundry lead-time volatility and currency fluctuation. |
| Subscription Service Model | Monthly firmware and spectrum reconfiguration bundles capture recurring revenue from UK rental operators. |
| EU Green Deal Certification | Repairable architectures and extended lifecycles satisfy emerging ecodesign requirements for public sector tenders. |
| Polish and Spanish Channel Expansion | Underpenetrated corporate education verticals offer volume scale without premium-tier competitive intensity. |
Research Methodology
Multi-period observation of BNetzA and Ofcom regulatory filings, ETSI standard revision timelines, and German rental house inventory cycles anchored the trend analysis, supplemented by interviews with RF engineering directors at broadcast equipment vendors, procurement leads at UK theater chains, and spectrum coordination specialists at French production facilities. Secondary validation drew from CE marking databases, customs import records for RF components, and SEC filings of listed audio equipment manufacturers. Bottom-up channel checks across Düsseldorf and London distributors triangulated against top-down spectrum allocation modeling.
Input-output matrices mapped transmitter-receiver pair shipments against frequency band availability, venue construction permits, and broadcast production hour indices across the projection horizon. Segmentation dimensions modeled include product architecture, application vertical, technology platform, and end-user sophistication tier. CAGRs derived from logistic diffusion curves fitted to digital adoption rates in comparable professional audio equipment categories, with RF spectrum scarcity coefficients and regulatory deadline proximity serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; live performance venue data carries tighter precision than dispersed corporate education procurement. Forecasts reflect assumptions regarding BNetzA enforcement timelines, foundry capacity allocation, and ETSI harmonization schedules that could shift materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Wireless Camera Market