
 Global Wi-Fi Market | 2026-2036
Global Wi-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wi-Fi Market Foresight
Managed network service revenue is tilting toward subscription-based cloud platforms as enterprises abandon capital-intensive hardware ownership. Cisco Systems leverages its Meraki cloud architecture to capture recurring revenue from mid-market customers. Hewlett Packard Enterprise (Aruba) anchors its position through AI-powered network automation that reduces operational overhead for distributed enterprises. Huawei Technologies competes aggressively on manufacturing scale, though its geographic reach faces constraints in certain Western markets.
Wi-Fi denotes a family of wireless networking protocols operating in the 2.4 GHz, 5 GHz, and 6 GHz unlicensed spectrum bands, using orthogonal frequency-division multiple access to enable high-throughput data transmission between devices and access points. Its primary purpose is to deliver localized internet connectivity without wired infrastructure across residential, commercial, and industrial environments. Wi-Fi 6 and Wi-Fi 6E technology segments command premium positioning as enterprises prioritize low-latency connectivity for dense device environments. Enterprise connectivity applications generate the strongest margin pools, while smart city infrastructure represents the fastest-growing deployment category as municipalities integrate wireless backbones for traffic management and public safety systems.
The FCC in the United States, Ofcom in the United Kingdom, and the European Telecommunications Standards Institute collectively govern spectrum allocation and device certification, with recent 6 GHz band openings directly stimulating hardware refresh demand. China's MIIT enforces domestic cybersecurity standards that shape product design requirements for vendors serving the Chinese market. Stakeholders must monitor regulatory momentum around spectrum harmonization and energy-efficiency mandates, as these frameworks will determine which technology generations achieve viable economies of scale.
Market Dynamics
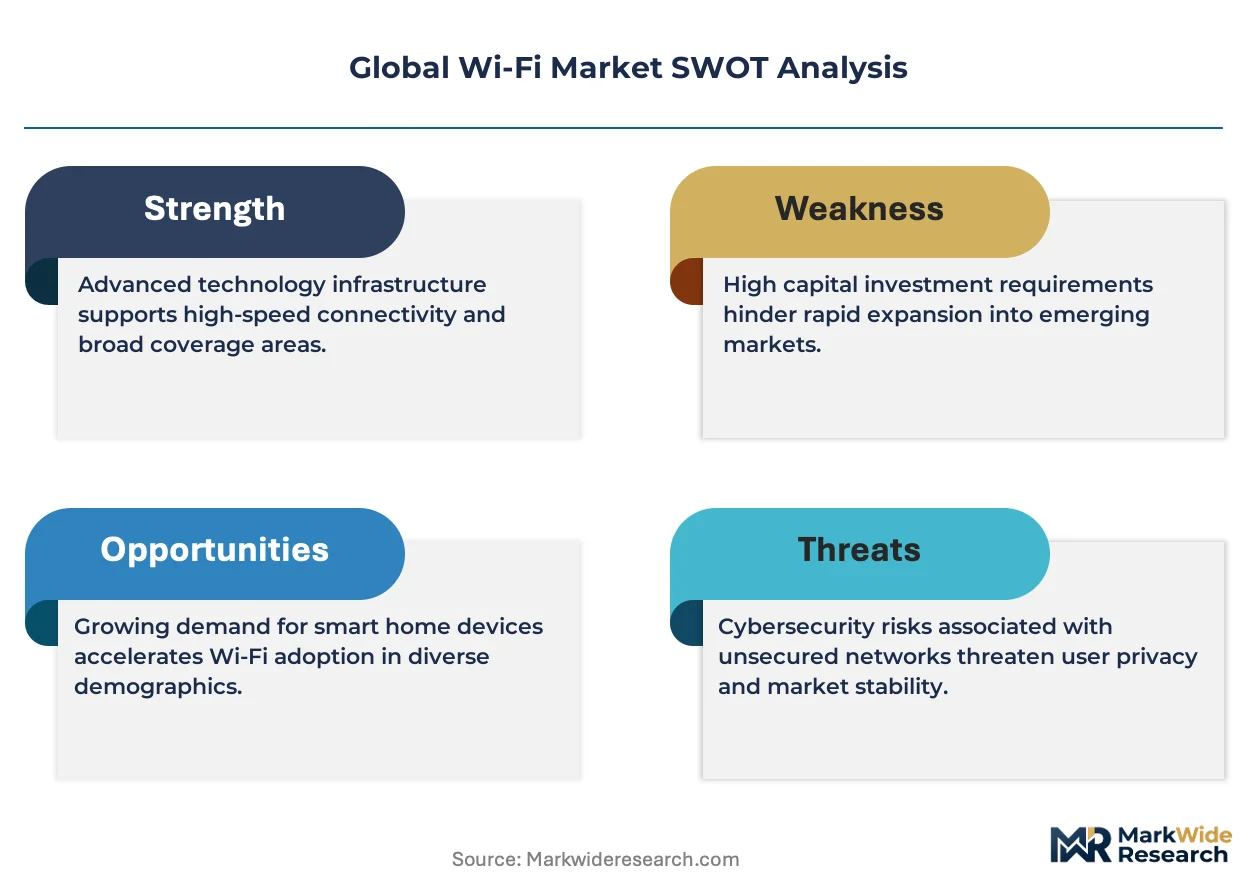
The Wi-Fi market is restructuring around spectrum allocation decisions by regulators in the United States, United Kingdom, and China, with 6 GHz band openings forcing infrastructure refresh cycles that favor vendors with cloud-managed platform architectures.
Growth Catalysts
- Wi-Fi 6E spectrum unlicensing:The FCC's 6 GHz band allocation in the United States and Ofcom's corresponding move in the United Kingdom have unlocked 1,200 MHz of contiguous spectrum, enabling gigabit-throughput applications in dense enterprise environments.
- Healthcare system digitization:Hospital networks are deploying next-generation wireless infrastructure to support real-time patient monitoring, surgical robotics, and electronic health record mobility across clinical floors.
- Industrial automation density:Manufacturing facilities in Germany and China are retrofitting production lines with wireless sensor networks, creating demand for deterministic low-latency connectivity that wired Ethernet cannot economically deliver.
Market Restraints
- Semiconductor supply concentration:Baseband processor and RF front-end module production concentrates among a limited set of foundry operators, creating vulnerability to geopolitical trade restrictions.
- Legacy 2.4 GHz interference saturation:The 2.4 GHz band suffers from overcrowding by Bluetooth, Zigbee, and microwave devices, degrading performance in residential and small-office deployments.
- Cybersecurity compliance fragmentation:China's MIIT enforces domestic encryption standards that diverge from IEEE 802.11i implementations, forcing product variant proliferation and certification duplication.
Strategic Opportunities
- Smart city infrastructure backlog:Municipalities in India and Brazil lack comprehensive wireless backbones for traffic management and public safety, representing greenfield deployment potential.
- Private 5G-Wi-Fi convergence:Enterprises are integrating Citizens Broadband Radio Service (CBRS) private cellular with Wi-Fi 6E under unified policy engines, creating bundled solution demand.
- EU Green Deal energy mandates:The European Commission's efficiency directives for network equipment are accelerating replacement of power-hungry legacy access points with Wi-Fi 6E hardware.
Industry Challenges
- RF engineering talent scarcity:The compound annual need for spectrum planners and antenna designers exceeds graduate pipeline output in the United States and Western Europe.
- Multi-vendor interoperability certification:Wi-Fi Alliance certification timelines lag hardware release cycles, forcing enterprises to delay production deployments pending interoperability validation.
- Cloud controller migration complexity:Organizations with on-premises wireless LAN controllers face forklift upgrade paths to cloud-native architectures, disrupting capital planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wi-Fi Market |
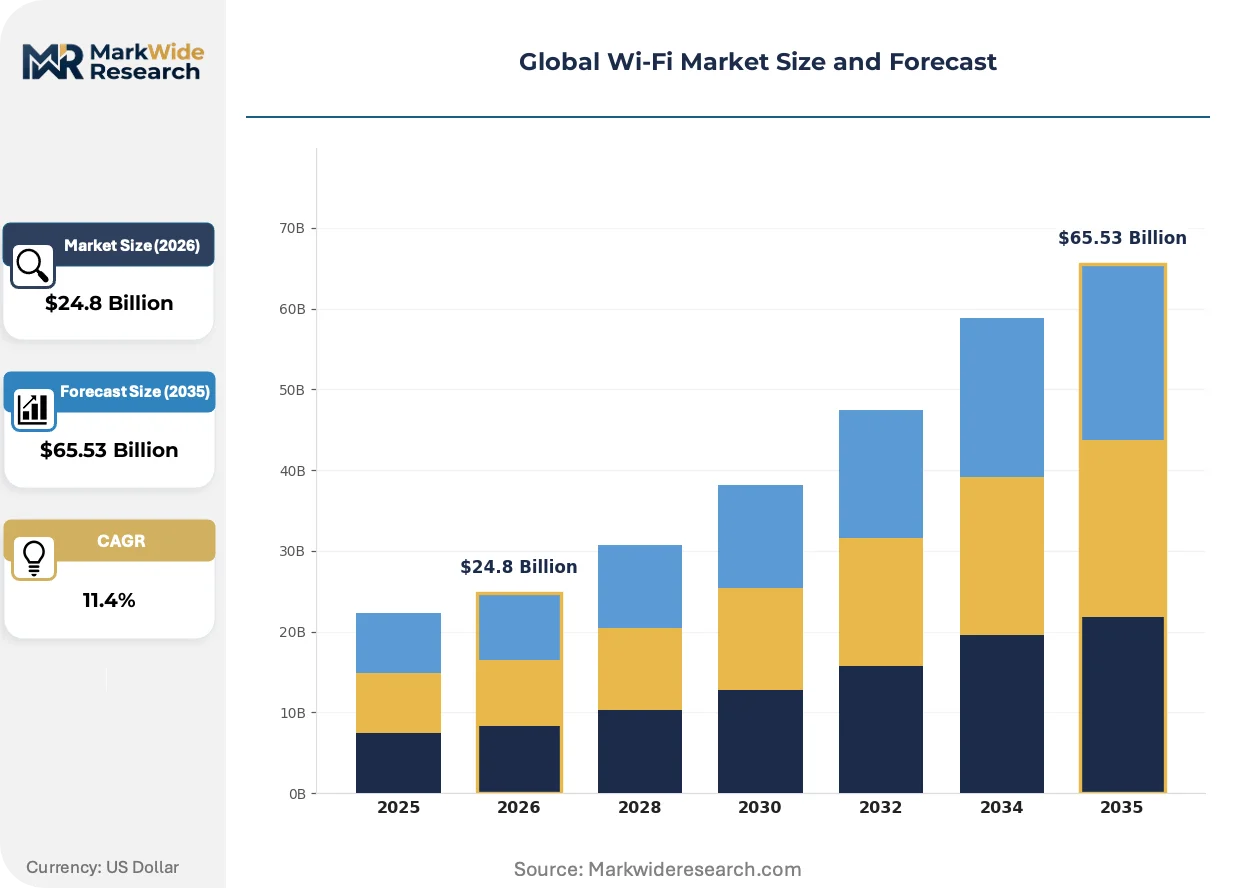
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $65.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Wireless Access Points, Range Extenders, Adapters, Gateways Technology: Wi-Fi 4, Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7 Application: Home Networking, Enterprise Connectivity, Public Hotspots, Smart City Infrastructure, Educational Institutions End User: Residential Consumers, Small Office/Home Office, Large Corporations, Hospitality Sector, Government Entities |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise (Aruba), CommScope (Ruckus Networks), Huawei Technologies, Juniper Networks, Fortinet, Extreme Networks, Ubiquiti, TP-Link Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wi-Fi Market Shifts & Advancements
Enterprise wireless infrastructure is pivoting from hardware-centric ownership models to software-defined consumption, with artificial intelligence operations and automated radio resource management becoming baseline procurement requirements.
Wi-Fi 6E is migrating from early-adopter enterprise campuses to mainstream commercial real estate. The technology adds 6 GHz spectrum access to existing 2.4 GHz and 5 GHz capabilities, doubling available channel bandwidth. Property managers in Class A office buildings across the United States are specifying Wi-Fi 6E as a tenant amenity standard. This migration is compressing depreciation schedules for 802.11ac Wave 2 equipment and forcing managed service providers to accelerate refresh programs.
Ofcom's Shared Access framework in the United Kingdom is creating tiered spectrum licensing that permits localized 6 GHz deployments without nationwide exclusivity fees. Industrial sites are securing localized licenses for private wireless networks that overlay Wi-Fi 6E for non-critical telemetry. Manufacturing clusters in the English Midlands are negotiating collective license arrangements to reduce administrative overhead. This regulatory innovation is diverting capital that would have flowed to licensed small-cell infrastructure.
Enterprise buyers are consolidating vendor relationships to reduce operational fragmentation. Distributed organizations with hundreds of branch locations are eliminating secondary wireless suppliers to standardize on single-platform cloud management. Retail chains in Germany are consolidating previously heterogeneous access point estates under unified dashboards. This concentration is compressing margins for point-product vendors without managed service attach rates.
Global Wi-Fi Market Segmentation
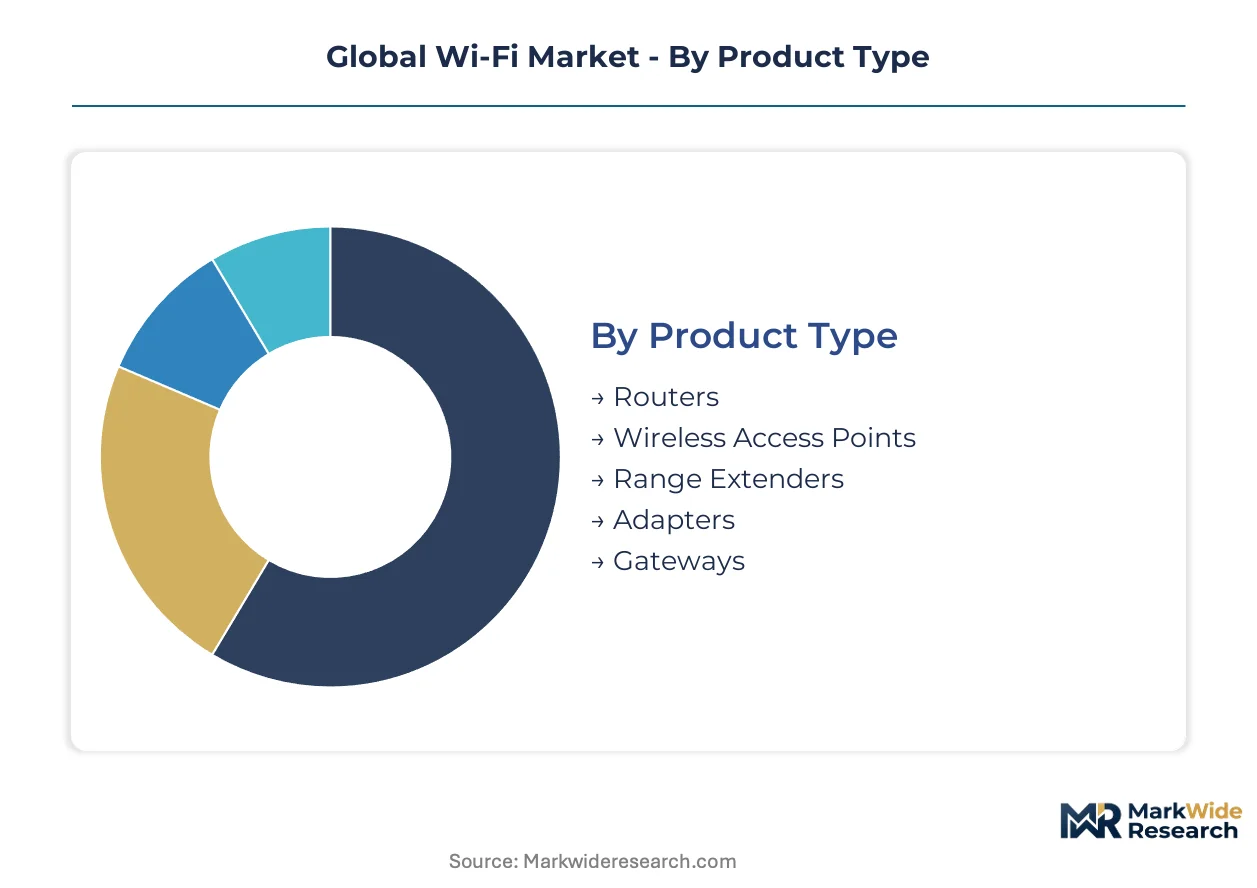
Wi-Fi market segmentation reveals distinct procurement patterns across hardware categories, technology generations, deployment contexts, and buyer archetypes. Understanding these divisions exposes where margin pools concentrate and which segments command premium positioning versus commodity competition.
Product Type:
Mature hardware categories dominate installed base volumes while emerging form factors capture deployment growth in specialized environments.
- Routers:Centralized traffic management devices integrating modem, firewall, and switching functions for residential and small-office environments. Demand clusters in United States suburban developments and German multi-dwelling units where fiber-to-the-home rollouts necessitate high-throughput CPE replacement.
- Wireless Access Points:Dedicated radio units providing distributed coverage across enterprise campuses and commercial facilities. Hospital systems in the United Kingdom and manufacturing complexes in China are standardizing on cloud-managed access point architectures to reduce on-site IT overhead.
- Range Extenders:Signal amplification devices addressing coverage gaps in residential deployments with structural interference challenges.
- Adapters:Peripheral connectivity modules enabling Wi-Fi capability for legacy wired devices and desktop computing equipment.
- Gateways:Converged access devices bridging residential LANs with service provider networks, incorporating voice and IoT hub functionality.
Routers retain volume leadership across consumer channels; wireless access points hold the steepest expansion curve in enterprise procurement.
Technology:
Cost tiers stratify sharply across protocol generations, with premium spectrum access commanding hardware price multiples over legacy implementations.
- Wi-Fi 4:Legacy 802.11n protocol operating in 2.4 GHz and 5 GHz bands with maximum 600 Mbps theoretical throughput. Survives primarily in price-sensitive emerging market residential deployments and industrial retrofit scenarios where bandwidth requirements remain modest.
- Wi-Fi 5:802.11ac Wave 2 standard delivering gigabit speeds through 160 MHz channel bonding and MU-MIMO. Still constitutes the majority of installed enterprise infrastructure in United States mid-market commercial real estate awaiting depreciation-triggered refresh cycles.
- Wi-Fi 6:802.11ax protocol introducing OFDMA and target wake time for dense IoT environments. Enterprise campuses in Germany and healthcare facilities in Singapore are prioritizing Wi-Fi 6 for deterministic latency in surgical robotics and automated guided vehicle coordination.
- Wi-Fi 6E:Extended 6 GHz spectrum access variant eliminating legacy band congestion for high-density deployments. FCC and Ofcom spectrum unlicensing has accelerated adoption in United States Class A office buildings and United Kingdom industrial parks.
- Wi-Fi 7:Emerging 802.11be standard with 320 MHz channels and multi-link operation for ultra-low latency applications. Early traction concentrates in financial trading floors and broadcast production facilities requiring sub-millisecond jitter performance.
Wi-Fi 5 maintains installed base dominance; Wi-Fi 6E is climbing the fastest as regulatory approvals unlock 6 GHz hardware procurement.
Application:
Customer type determines procurement sophistication, with enterprise buyers demanding managed service integration versus consumer self-installation patterns.
- Home Networking:Residential coverage solutions for single and multi-family dwellings. United States cable operators bundle Wi-Fi 6 gateways as retention tools against fiber overbuild competition.
- Enterprise Connectivity:Campus-wide infrastructure for corporate headquarters, branch offices, and distributed facilities. German automotive suppliers are consolidating heterogeneous vendor estates under unified cloud management platforms.
- Public Hotspots:Guest access infrastructure for transportation terminals, retail venues, and municipal spaces. Airports in India and Brazil are upgrading to Wi-Fi 6E to support passenger streaming and biometric boarding pass validation.
- Smart City Infrastructure:Metropolitan wireless backbones integrating traffic management, environmental sensing, and public safety systems. Cities in China deploy unified Wi-Fi and IoT sensor networks for real-time congestion optimization.
- Educational Institutions:Campus coverage for K-12 schools and university environments supporting one-to-one device programs. United Kingdom higher education institutions are specifying Wi-Fi 6E for hybrid lecture hall streaming and VR laboratory applications.
Enterprise connectivity commands the highest average selling prices; smart city infrastructure is expanding most quickly as municipal digitization budgets mature.
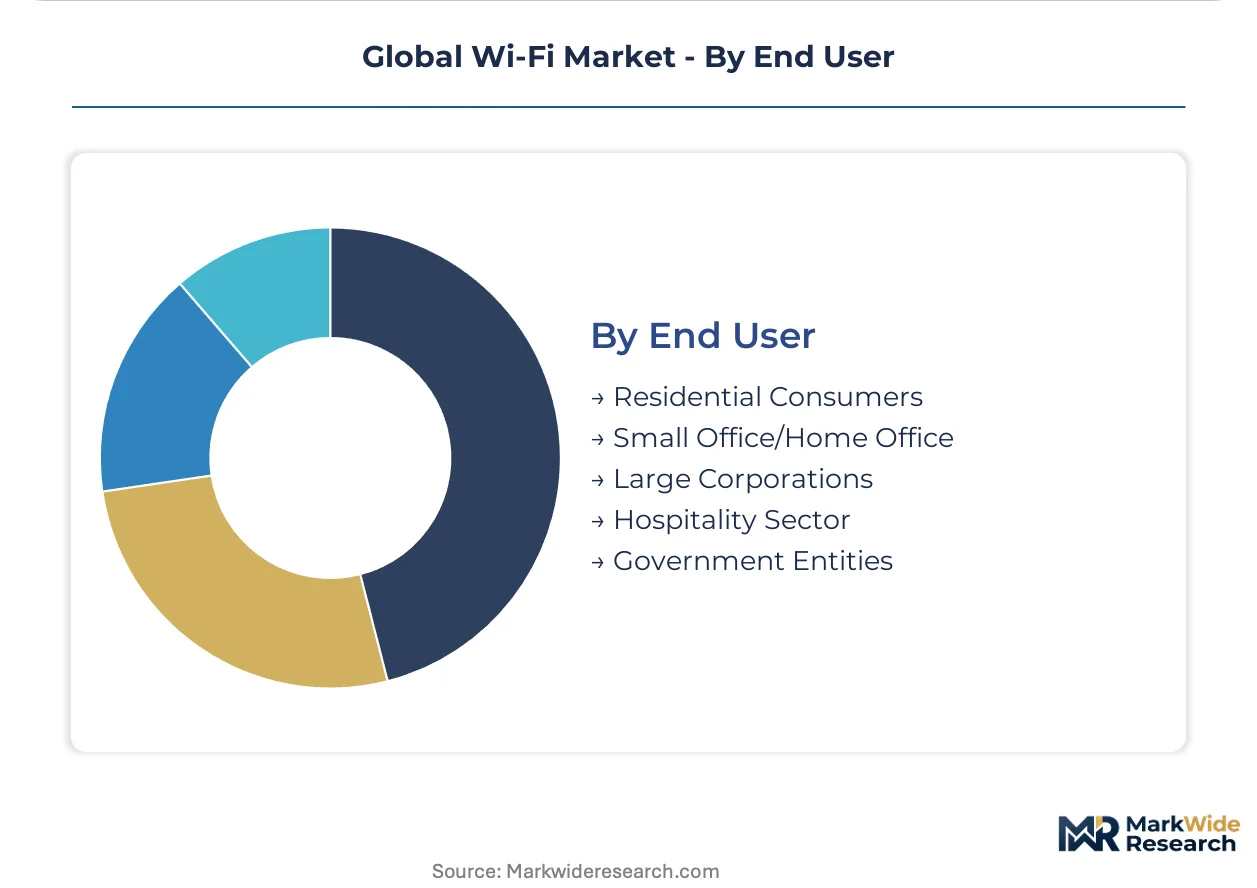
End User:
Volume concentration sits with residential consumers while margin extraction favors large corporations with complex deployment and support requirements.
- Residential Consumers:Individual households purchasing through retail channels and ISP equipment rental programs. United States and Chinese markets drive absolute unit volumes through cable and fiber subscriber growth.
- Small Office/Home Office:Micro-businesses and remote workers requiring professional-grade coverage without enterprise IT staffing. Mesh system adoption is accelerating in this segment as hybrid work patterns persist.
- Large Corporations:Multi-site organizations with thousands of access points under centralized policy management. Financial services firms in the United Kingdom and pharmaceutical manufacturers in Germany are consolidating on single-vendor cloud architectures.
- Hospitality Sector:Hotels, resorts, and conference venues providing guest connectivity as core amenity. Premium properties in Singapore and Dubai specify Wi-Fi 6E as competitive differentiation for business traveler segments.
- Government Entities:Federal, state, and municipal agencies with cybersecurity certification requirements and domestic preference procurement rules. China's MIIT enforces encryption standards that shape product variants for public sector deployment.
Residential consumers generate absolute unit leadership; large corporations deliver the steepest margin expansion through managed service attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes cloud-managed enterprise platforms while China emphasizes domestic cybersecurity compliance. Germany concentrates on industrial automation density. Brazil and India represent greenfield smart city deployment with limited legacy infrastructure to displace.
United States
Enterprise campuses and Class A commercial real estate drive hardware refresh demand. The FCC's 6 GHz spectrum unlicensing accelerates Wi-Fi 6E procurement timelines. Property managers in Manhattan and San Francisco specify cloud-managed access points as tenant amenity standards.
China
Manufacturing complexes and municipal smart city networks absorb high equipment volumes. MIIT enforces domestic encryption standards that shape product variants for public sector procurement. Industrial clusters in Shenzhen and Shanghai retrofit production lines with wireless sensor networks.
Germany
Automotive suppliers and pharmaceutical manufacturers consolidate heterogeneous vendor estates. The EU Green Deal energy mandates accelerate replacement of legacy access points with efficient hardware. Bavarian production facilities standardize on unified cloud management platforms.
India
Airports and municipal traffic management systems represent greenfield wireless backbone deployment. TRAI spectrum policies influence equipment certification requirements. Cities in Maharashtra and Karnataka integrate Wi-Fi with IoT sensors for congestion optimization.
Brazil
Municipal digitization budgets mature for public safety and environmental sensing networks. Localized regulatory frameworks permit shared infrastructure models. São Paulo metro authorities negotiate collective license arrangements to reduce administrative overhead.
Global Wi-Fi Market Competitive Landscape
Capability concentration sits with cloud-architecture specialists; scale advantage sits with manufacturing-integrated conglomerates. The vendor base stratifies into three tiers: subscription-platform providers, hardware-centric incumbents, and price-competitive commodity suppliers. Dominant competitive moves include M&A to acquire AI-powered automation software and strategic partnerships to bundle private cellular with Wi-Fi convergence.
Within the cloud-platform tier, Cisco Systems and Hewlett Packard Enterprise exemplify the shift toward recurring revenue models. Huawei Technologies occupies a position shaped by manufacturing scale and geographic constraints. These three anchors represent divergent strategic responses to the same spectrum and regulatory forces.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise (Aruba) |
| CommScope (Ruckus Networks) |
| Huawei Technologies |
| Juniper Networks |
| Fortinet |
| Extreme Networks |
| Ubiquiti |
| TP-Link Technologies |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwanese semiconductor foundries is compressing baseband processor pricing while simultaneously forcing RF front-end module suppliers to extend payment terms, creating divergent margin trajectories across Wi-Fi hardware tiers.
Pricing Analysis
Long-term offtake agreements dominate enterprise procurement, with three-year subscription contracts for cloud-managed platforms anchoring vendor revenue predictability. Price differentiation hinges on spectrum certification tier—FCC Part 15 Class A versus Class B—and volume scale commitments above ten thousand access points. Cost compression in Wi-Fi 5 legacy hardware is intensifying because depreciation-triggered refresh cycles are accelerating trade-in allowances. Small-office buyers exhibit acute price sensitivity, while hospital systems and financial trading floors prioritize deterministic latency over unit cost.
Supply Chain Analysis
Export-control regimes restricting RF semiconductor flows to Chinese equipment vendors are fragmenting procurement channels and inflating lead times for 6 GHz power amplifiers. Manufacturing concentrates in Taiwan, China, and Vietnam, with baseband silicon drawing from TSMC and Samsung foundry capacity. Supply chain risk centers on single-source vulnerability for gallium nitride substrates used in high-efficiency front-end modules. Distribution runs through direct enterprise sales teams for large deployments and value-added resellers serving mid-market commercial real estate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi market is approaching a platform-economics inflection where cloud-native network operating systems are displacing controller-based architectures, with the Wi-Fi Alliance's EasyMesh certification creating interoperability standards that reshape vendor lock-in dynamics.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into AI-powered radio resource management software, countering the threat from white-label hardware vendors bundling third-party cloud controllers. Prioritize certification investment in Wi-Fi 7 and 6E spectrum compliance to maintain enterprise procurement eligibility as FCC and Ofcom enforcement tightens.
For New Entrants and Emerging Players: Establish a beachhead in Brazil and India's smart city infrastructure segments, where greenfield deployment lacks incumbent hardware estates to displace. Target municipal traffic management and public safety networks with project-based professional services bundled with Wi-Fi 6E access points, leveraging localized regulatory knowledge as a go-to-market wedge against global platform vendors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-managed platform providers with healthcare and education vertical penetration, signaling durable cash flow quality across the analysis window. Acquisition targets should demonstrate API-first architectures enabling private 5G-Wi-Fi convergence. The signal to watch is Ofcom Shared Access license uptake in United Kingdom industrial clusters as a proxy for localized private network demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Controller Migration | Enables subscription revenue capture from mid-market enterprises abandoning on-premises hardware ownership. |
| AI-Powered Radio Resource Management | Reduces operational overhead for distributed facilities through automated interference mitigation and channel optimization. |
| Wi-Fi 6E Spectrum Certification | Unlocks procurement eligibility in United States Class A commercial real estate and United Kingdom industrial parks. |
| Private 5G-Wi-Fi Convergence | Captures bundled solution demand from manufacturing facilities integrating CBRS cellular with unified policy engines. |
| Vertical Integration into RF Front-End | Secures gallium nitride substrate supply against foundry concentration risk and export-control fragmentation. |
Research Methodology
Operator-level perspectives from network infrastructure directors, hospital IT procurement leads, commercial real estate technology officers, and managed service provider engineering heads anchored the qualitative base. Primary interview findings were cross-validated against FCC equipment authorization databases, Ofcom spectrum license registers, Wi-Fi Alliance certification listings, and hyperscaler capex disclosures. Bottom-up unit economics from access point bill-of-materials were triangulated with top-down enterprise IT spending surveys.
Scenario-bracketing framed the analytical approach across the projection horizon, with technology generation (Wi-Fi 5 through Wi-Fi 7), deployment context (enterprise campus versus smart city versus residential), and buyer archetype (large corporation versus government entity versus consumer) constituting the core segmentation dimensions. CAGRs were derived from installed base depreciation schedules and regulatory-triggered refresh cycle modeling, with 6 GHz spectrum allocation timelines and EU Green Deal energy mandates serving as industry-specific demand drivers.
Stress conditions across semiconductor foundry utilization, export-control enforcement intensity, and enterprise cloud-migration velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spectrum harmonization progress and interoperability certification timelines. Material shifts in FCC or MIIT regulatory posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wireless Charger Market