
 Location Based Advertising Market | 2026-2036
Location Based Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Location Based Advertising Market Analysis
First-party location data is consolidating as the core input for audience segmentation, displacing reliance on deprecating mobile identifiers. Google LLC leverages its mapping infrastructure and consent-management tooling to sustain deterministic geofencing capabilities across Android ecosystems. Meta Platforms Inc. anchors its local awareness products on aggregated event signals rather than granular GPS traces. GroundTruth differentiates through owned-and-operated venue polygons that cover millions of commercial points-of-interest.
Location based advertising delivers promotional content to consumer devices based on real-time or stored geographic coordinates, typically processed through GPS satellite triangulation, Bluetooth low-energy beacon proximity detection, or Wi-Fi access point fingerprinting with accuracy thresholds ranging from one meter to fifty meters depending on sensor density. The primary commercial purpose is bridging offline physical presence with digital campaign attribution, enabling retailers to measure store visit lift from ad exposure. GPS technology leads deployment scale due to universal smartphone integration, while beacon installations grow fastest in enclosed retail environments where sub-meter precision unlocks aisle-level messaging. Cloud-based delivery models capture the dominant margin pool by amortifying infrastructure across thousands of advertiser accounts.
The Federal Trade Commission enforces truth-in-advertising standards that extend to location claims, while the FCC governs wireless spectrum usage for beacon and RFID transmissions that underpin proximity networks. The California Consumer Privacy Act and its successor statute mandate explicit opt-in protocols before geolocation data collection, directly shaping platform architecture and consent flow design. Stakeholders must monitor evolving state-level privacy ballot measures and their divergence from federal precedent to determine whether to centralize compliance operations or fragment by jurisdiction.
Market Dynamics
The deprecation of mobile advertising identifiers is forcing platforms to rebuild audience graphs around consented location signals and first-party data cooperatives.
Growth Catalysts
- GDPR Article 7 consent frameworks:Publishers who implement granular opt-in flows for geolocation access now command premium CPMs from privacy-conscious advertisers in European markets.
- Retail media networks:Grocery and big-box chains monetize in-store beacon infrastructure through sponsored product placements triggered by aisle proximity.
- Connected vehicle telemetry:Automotive OEMs aggregate anonymized GPS traces from infotainment systems to sell aggregated movement patterns to out-of-home buyers.
Market Restraints
- Signal degradation from iOS privacy changes:Apple's App Tracking Transparency framework severed deterministic location pipelines that powered precision geofencing for half a decade.
- Beacon hardware supply concentration:Bluetooth low-energy module fabrication clusters in Taiwan create vulnerability to semiconductor allocation shocks.
- Wi-Fi fingerprinting accuracy limits:Indoor positioning systems struggle to distinguish vertical floors in dense urban retail environments, compressing attribution confidence.
Strategic Opportunities
- EU AI Act compliance tooling:Platforms that automate risk classification for geolocation inference models capture enterprise accounts fleeing liability exposure.
- India's digital public infrastructure:The Account Aggregator framework enables consent-architected location data sharing between banks and retailers for credit-triggered offers.
- 5G network slicing:Telecom operators sell guaranteed-latency location delivery to time-sensitive advertisers running flash promotions during live events.
Industry Challenges
- Cross-device identity stitching:Matching GPS signals from smartphones to CTV impressions requires probabilistic graph techniques that degrade in cookieless environments.
- Attribution window compression:Retailers demand same-day store visit verification, forcing platforms to abandon longer lookback models that improved statistical significance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location Based Advertising Market |
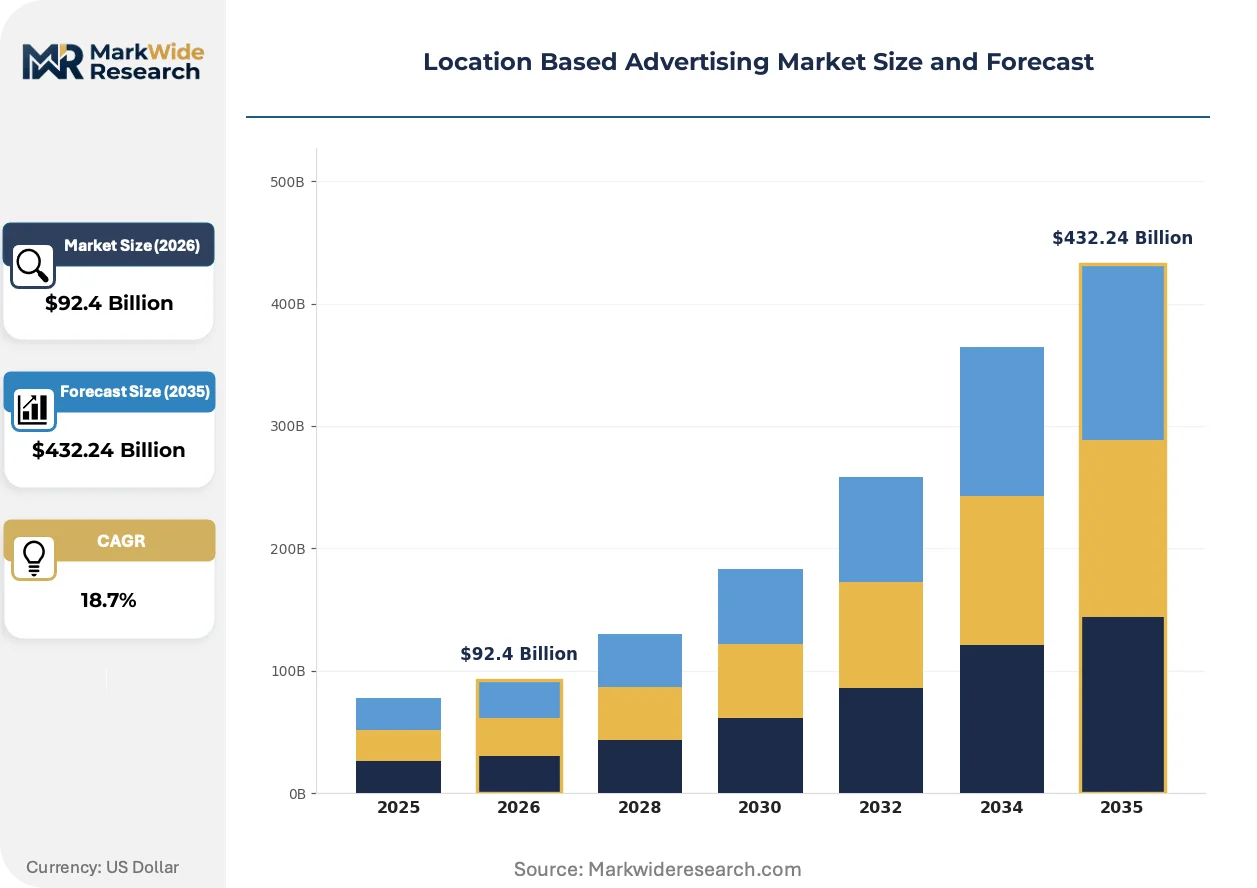
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $432.24 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Beacons, RFID, Wi-Fi Application: Retail Marketing, Social Media, Navigation, Events End User: Retailers, Advertisers, Enterprises, Marketers Delivery Model: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Google LLC, Meta Platforms Inc., Amazon.com Inc., Foursquare, IBM Corporation, Cidewalk Technologies Inc., GroundTruth, Yelp Inc., Near Intelligence Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location Based Advertising Market Emerging Trajectories
Privacy-preserving computation techniques are rewriting how location intelligence moves between data silos without centralizing sensitive consumer traces.
Federated learning is rewriting the economics of audience modeling. Platforms train geobehavioral classifiers on-device using local GPS histories, then share only model updates rather than raw coordinates. Retail advertisers in the United States adopt this architecture fastest where CCPA litigation risk concentrates.
The EU AI Act's risk-tier classification for biometric inference is rewriting vendor liability structures. Platforms processing geolocation to predict sensitive attributes—health status, political affiliation, religious practice—face mandatory conformity assessments. German automotive advertisers now segregate location data pipelines to isolate high-risk inference chains.
Retailer procurement of location intelligence is consolidating around clean room architectures. Big-box buyers refuse to ship customer files to external platforms, instead requiring vendors to deploy computation inside retailer-controlled environments. This pattern is most advanced in French grocery and British pharmacy verticals where data protection officer influence peaks.
Location Based Advertising Market Segmentation
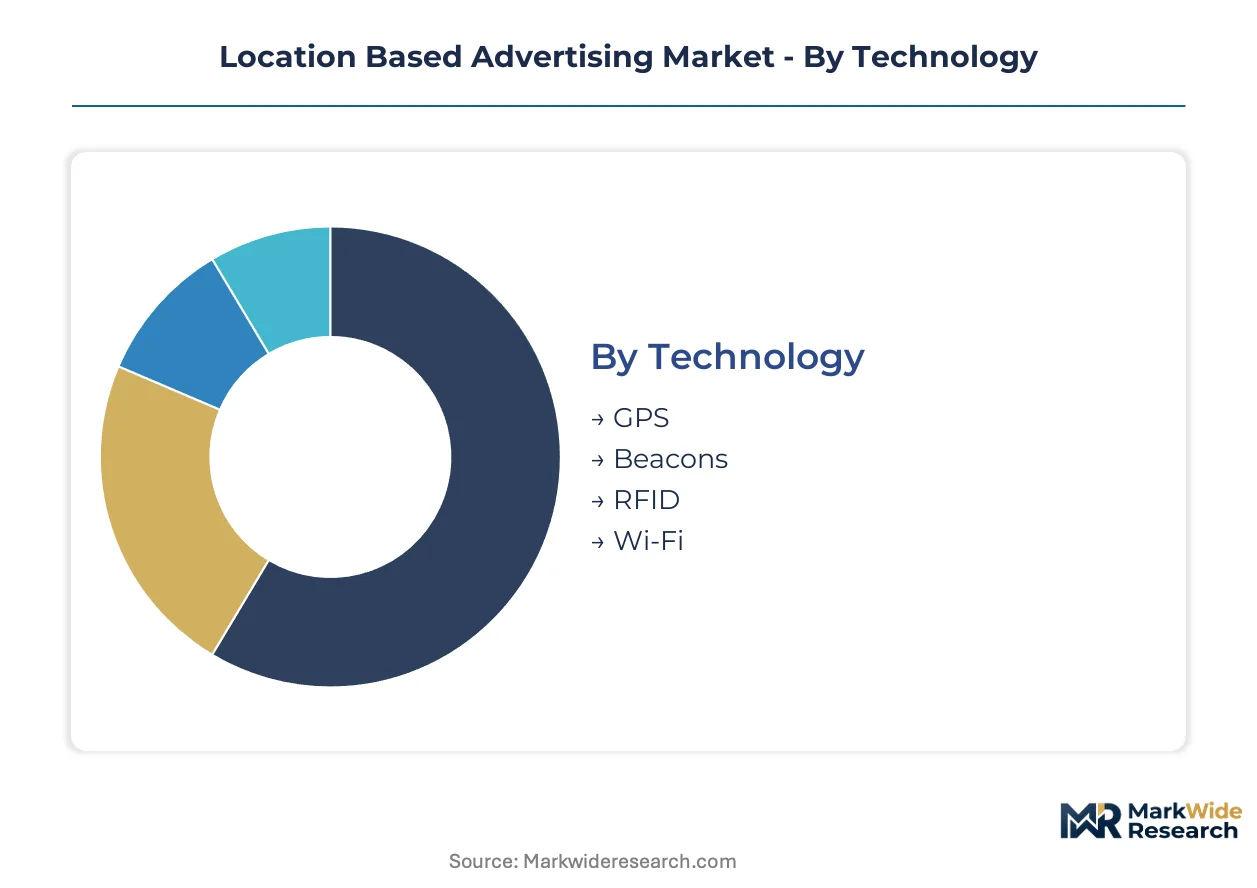
Segmentation in location based advertising reveals how technical architecture, deployment context, and buyer economics intersect. Platform vendors configure pricing and compliance tooling around these axes to capture margin in privacy-regulated environments.
Technology:
GPS satellite triangulation, Bluetooth beacon proximity, and wireless fingerprinting each impose distinct infrastructure costs and precision ceilings on campaign execution.
- GPS:Satellite triangulation leverages existing smartphone hardware without incremental capital expenditure. Dense urban corridors in the United States generate the highest signal density for real-time bidding systems, though indoor accuracy degrades below usable thresholds for aisle-level targeting.
- Beacons:Bluetooth low-energy transmitters enable sub-meter precision in enclosed retail environments where GPS signals attenuate. Grocery and big-box chains monetize this infrastructure through sponsored product placements triggered by aisle proximity, creating hardware lock-in effects for platform vendors.
- RFID:Radio-frequency identification supports passive tag detection at point-of-sale terminals for attribution verification. Deployment concentrates in apparel and electronics retail verticals where inventory tagging infrastructure already exists.
- Wi-Fi:Access point fingerprinting triangulates position using signal strength mapping of known router locations. Indoor positioning systems struggle to distinguish vertical floors in dense urban retail environments, compressing attribution confidence for multi-level venues.
GPS leads on scale; Beacons lead on momentum.
Application:
Functional use cases determine data latency requirements and consent complexity, with retail applications demanding immediate signal processing while social platforms tolerate batch aggregation.
- Retail Marketing:Proximity-triggered promotions convert foot traffic through beacon networks deployed by national chains. The EU AI Act and GDPR compliance requirements reshape how platforms process geolocation data for ad targeting in European markets.
- Social Media:Aggregated event signals anchor local awareness products without granular GPS trace retention. Meta Platforms Inc. structures its architecture around this pattern to limit regulatory exposure.
- Navigation:Turn-by-turn routing applications generate continuous location streams that feed movement pattern inference for out-of-home buyers. Automotive OEMs aggregate anonymized GPS traces from infotainment systems for this purpose.
- Events:Temporary venue deployments during sports and entertainment programming require rapid infrastructure provisioning. 5G network slicing enables telecom operators to sell guaranteed-latency location delivery for flash promotions during live events.
Retail Marketing commands the dominant revenue pool; Events shows the steepest expansion trajectory.
End User:
Buyer sophistication and data governance maturity create tiered pricing power, with enterprise procurement teams demanding clean room architectures that external platforms must accommodate.
- Retailers:Grocery and pharmacy chains refuse to ship customer files to external platforms, requiring vendor computation inside retailer-controlled environments. French grocery and British pharmacy verticals exhibit the most advanced deployment of this pattern.
- Advertisers:Agency holding groups consolidate location intelligence spending around first-party data cooperatives as mobile advertising identifiers deprecate. Premium CPMs flow to publishers who implement granular opt-in flows for geolocation access.
- Enterprises:Corporate procurement mandates segregate location data pipelines to isolate high-risk inference chains under EU AI Act liability frameworks. German automotive advertisers pioneered this architecture.
- Marketers:Brand-side teams demand same-day store visit verification, forcing platforms to abandon longer lookback models that improved statistical significance.
Retailers extract the most favorable contract terms; Advertisers represent the volume anchor.
Delivery Model:
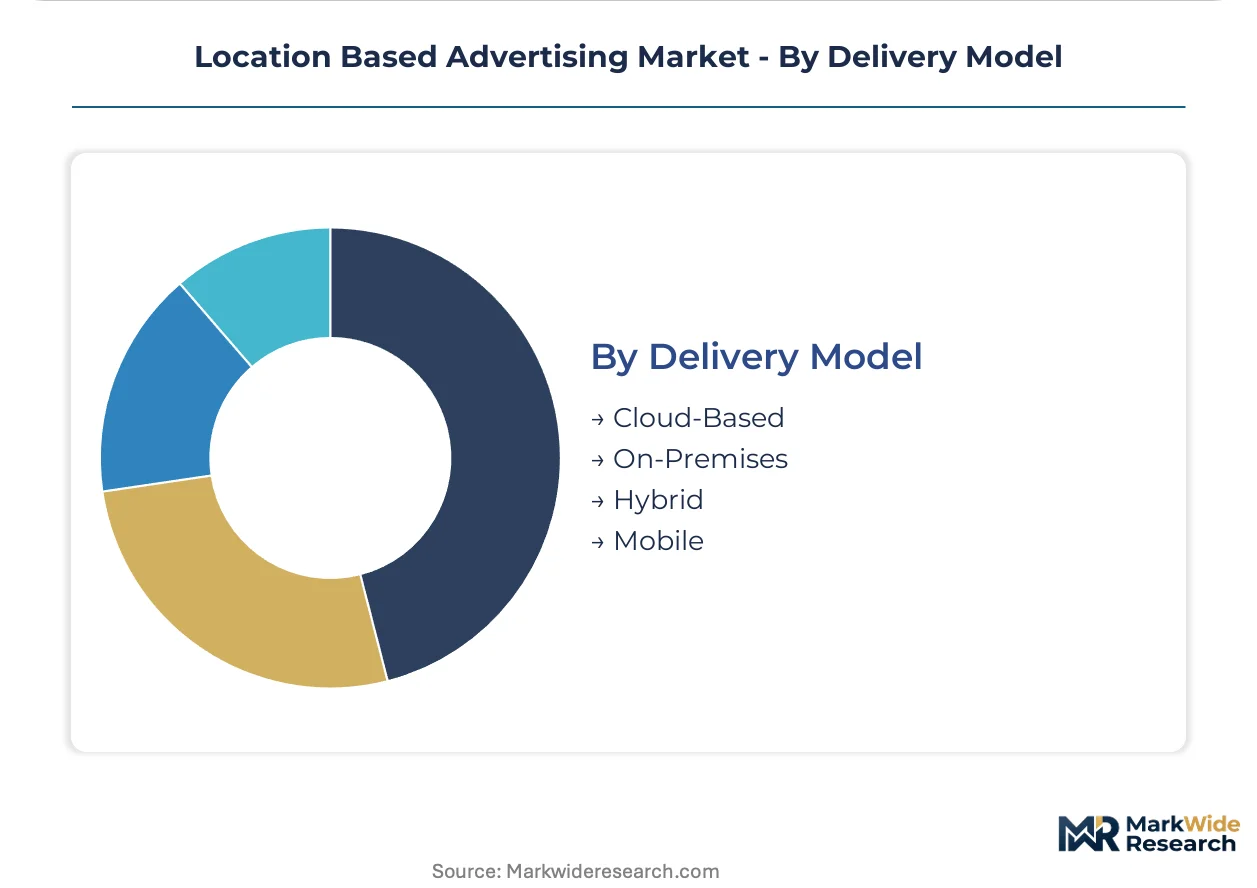
Infrastructure ownership and operational responsibility allocation determine margin structure and compliance accountability across deployment options.
- Cloud-Based:Multi-tenant infrastructure amortizes fixed costs across thousands of advertiser accounts, capturing the dominant margin pool in the sector.
- On-Premises:Single-tenant deployments satisfy data residency requirements in regulated industries and national jurisdictions with localization mandates.
- Hybrid:Split architectures process sensitive inference inside client environments while leveraging cloud scale for campaign optimization.
- Mobile:Edge-resident execution on consumer devices supports federated learning architectures where model updates rather than raw coordinates traverse networks.
Cloud-Based dominates current revenue; Hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's dense concentration of ad-tech infrastructure anchors global location-based advertising innovation, while regulatory divergence across major economies forces platforms to architect jurisdiction-specific compliance stacks.
United States
Dense urban corridors in New York, Chicago, and Los Angeles generate the highest location signal density for real-time bidding systems. The FTC enforces truth-in-advertising standards extending to location claims, while the FCC governs wireless spectrum for beacon transmissions. California's CCPA and its successor statute mandate explicit opt-in protocols before geolocation collection, directly shaping platform architecture.
Germany
Automotive OEMs in Stuttgart and Munich aggregate anonymized GPS traces from infotainment systems for out-of-home buyers. The EU AI Act's risk-tier classification for biometric inference mandates conformity assessments for platforms predicting sensitive attributes from movement patterns. German advertisers now segregate location data pipelines to isolate high-risk inference chains.
United Kingdom
London's retail media networks monetize in-store beacon infrastructure through sponsored product placements triggered by aisle proximity. GDPR Article 7 consent frameworks command premium CPMs from privacy-conscious advertisers. British pharmacy verticals exhibit the most advanced deployment of clean room architectures for location intelligence procurement.
India
The Account Aggregator framework enables consent-architected location data sharing between banks and retailers in Mumbai and Bangalore for credit-triggered offers. TRAI governs telecommunications infrastructure supporting 5G network slicing for time-sensitive advertisers. Bangalore's tech corridor hosts the fastest-growing cluster of privacy-preserving computation startups.
France
French grocery chains refuse to ship customer files to external platforms, requiring vendor computation inside retailer-controlled environments. CNIL enforces GDPR implementation with particular scrutiny on geolocation retention periods. Paris and Lyon anchor Europe's most advanced deployment of federated learning architectures for on-device audience modeling.
Location Based Advertising Market Vendor Landscape
Global majors compete with regional champions across mapping infrastructure, consent-management tooling, and venue polygon ownership. The market structure tiers around data scale, with cloud-based delivery models capturing dominant margins by amortizing infrastructure across thousands of advertiser accounts. Three archetypes dominate: mapping-platform owners leveraging deterministic geofencing, retail-media network operators monetizing beacon infrastructure, and privacy-preserving computation specialists deploying federated learning. Competitive moves concentrate on M&A for first-party data assets and strategic partnerships for clean room architectures.
Within the mapping-platform tier, Google LLC exemplifies infrastructure-led positioning through its Android ecosystem integration. Meta Platforms Inc. anchors the social-aggregation archetype, structuring architecture around event signals rather than granular GPS retention. GroundTruth occupies a specialist position through owned-and-operated venue polygon coverage.
| Leading Market Players |
|---|
| Google LLC |
| Meta Platforms Inc. |
| Amazon.com Inc. |
| Foursquare |
| IBM Corporation |
| Cidewalk Technologies Inc. |
| GroundTruth |
| Yelp Inc. |
| Near Intelligence Inc. |
| Others |
Supply Flow & Price Mechanics
Retail procurement teams demanding clean room architectures for location intelligence are forcing platform vendors to absorb infrastructure deployment costs inside client-controlled environments, compressing margins for cloud-native providers while rewarding hybrid delivery specialists with pricing power in European grocery and British pharmacy verticals.
Pricing Analysis
Beacon hardware costs and cloud infrastructure fees pass through to advertisers via hybrid subscription-transactional models. Price differentiation hinges on precision tier—sub-meter beacon proximity commands premium rates against GPS-based geofencing—and compliance certification level under GDPR Article 7 and EU AI Act frameworks. Pricing pressure intensifies as iOS privacy changes degrade signal quality, forcing platforms to discount deterministic location products. Mid-market advertisers exhibit highest price sensitivity; enterprise retailers with dedicated data protection officers accept premium positioning for liability isolation.
Supply Chain Analysis
Freight logistics for Bluetooth low-energy module fabrication concentrates supply vulnerability in Taiwan, where semiconductor allocation shocks ripple through beacon hardware availability. The location advertising supply chain draws from Taiwanese chip foundries, South Korean sensor manufacturers, and Chinese assembly operations for beacon hardware; cloud infrastructure rests on hyperscaler data centers in the United States, Ireland, and Singapore. Single-source vulnerability in Taiwan-based BLE module production creates disruption risk for aisle-level retail deployments. Distribution runs through direct enterprise sales for large retailers and programmatic exchanges for mid-market advertisers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
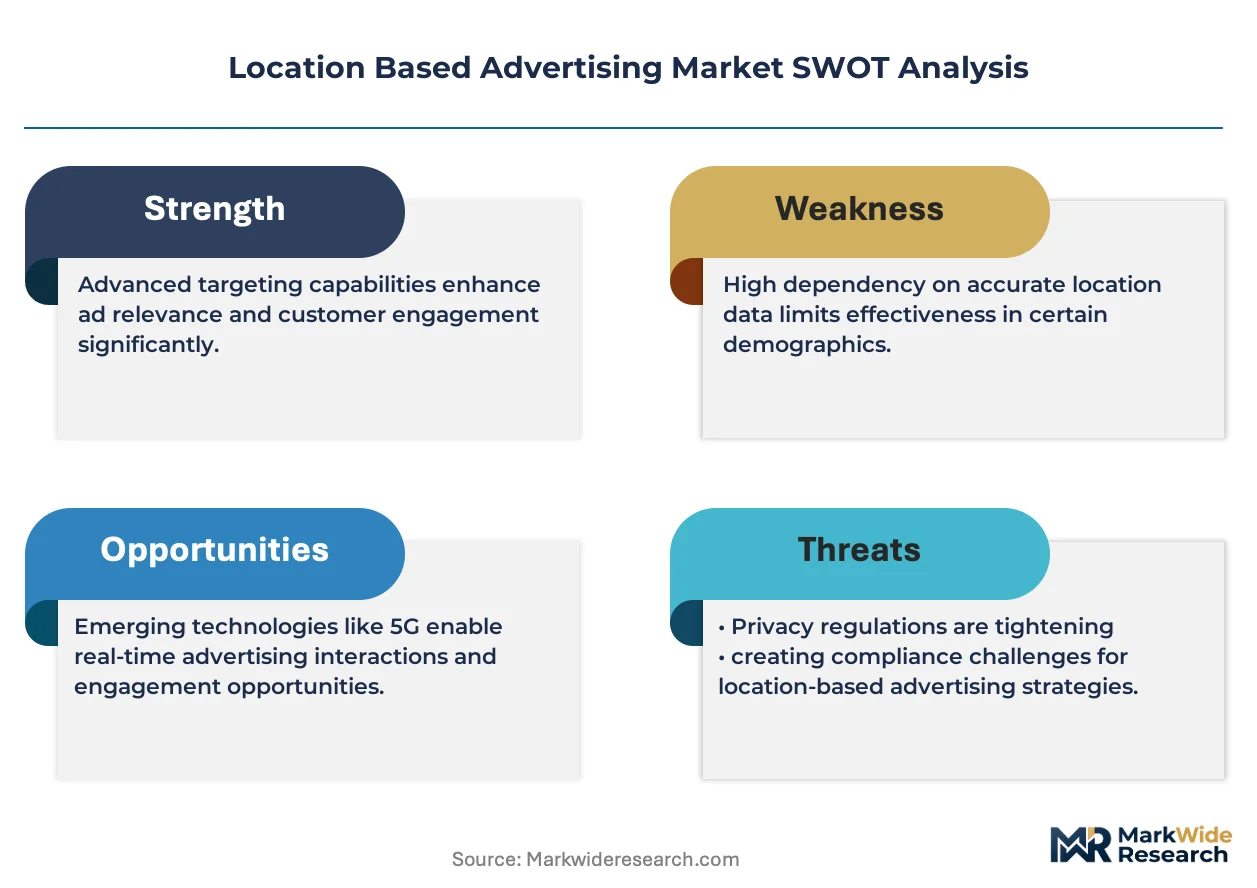
The location based advertising market functions as a regulatory compounder where EU AI Act risk-tier classifications and GDPR consent mandates continuously reshape platform architecture, driving demand for compliance-automation tooling that commands sustained pricing premiums.
For Market Incumbents: Anchor defensive positioning through backward integration into first-party data cooperative networks as mobile advertising identifiers deprecate. Prioritize clean room architecture certification to isolate high-risk inference chains under German automotive advertiser procurement standards. Consolidate venue polygon ownership through targeted asset acquisition to defend against mapping-platform competitors.
For New Entrants and Emerging Players: Mid-market pharmacy chains in France and grocery cooperatives in India represent underserved buyer archetypes with unmet demand for consent-architected location sharing. Federated learning deployment for on-device audience modeling offers the most penetrable technical wedge against cloud-incumbent dominance. Pursue partnership-first go-to-market positioning with telecom operators selling 5G network slicing for guaranteed-latency delivery.
For Investors and Strategic Acquirers: Asymmetric upside sits with privacy-preserving computation specialists deploying federated learning architectures that limit liability exposure under EU AI Act conformity assessments. Long-term viability favors vendors with hybrid delivery models and retailer-controlled environment deployment capability. Monitor India's Account Aggregator framework adoption velocity as inflection indicator for consent-architected data sharing market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Architecture Deployment | Isolates high-risk inference chains under EU AI Act liability frameworks for German automotive advertisers. |
| Federated Learning Platform Launch | Enables on-device audience modeling without raw coordinate transmission, limiting CCPA litigation exposure. |
| Venue Polygon Asset Acquisition | Expands owned-and-operated coverage for deterministic geofencing against mapping-platform competitors. |
| 5G Network Slicing Partnership | Secures guaranteed-latency location delivery for flash promotions during live sports and entertainment events. |
| Consent-Management Tooling Integration | Automates GDPR Article 7 granular opt-in flows to capture premium CPMs from privacy-conscious European advertisers. |
Methodological Framework
Coverage spans the United States, Germany, the United Kingdom, India, and France, with primary inputs from each market triangulated through interviews with ad-tech platform executives, retail media network operators, data protection officers, and programmatic trading specialists. Secondary validation draws from SEC filings of listed ad-tech vendors, GDPR enforcement actions published by CNIL and ICO, TRAI telecommunications reports, and EU AI Act implementation guidance. Bottom-up segment sizing and top-down macroeconomic cross-checks reconcile volume and value estimates.
Rate-of-change decomposition isolates technology adoption curves, regulatory enforcement intensity, and buyer procurement pattern shifts across the projection horizon. Segmentation dimensions modeled include technology type, application vertical, end-user sophistication tier, and delivery model architecture. CAGRs derive from logistic diffusion curves fitted to historical deployment data and elasticity-adjusted spend projections. Forecast inputs incorporate beacon hardware shipment volumes and cloud infrastructure capex disclosures from hyperscalers.
Underlying measurement precision varies by segment; GPS-based deployments carry tighter precision than Wi-Fi fingerprinting systems where vertical floor distinction degrades attribution confidence. Forecasts reflect assumptions about iOS privacy framework evolution and EU AI Act enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market