
 Wireless Camera Market | 2026-2036
Wireless Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Camera Market Analytics
Resolution-tier migration toward 4K and AI-enhanced imaging is unwinding legacy 1080p volume dominance across the wireless camera landscape. Hikvision leverages its manufacturing scale to anchor professional-grade supply lines for enterprise security deployments. Arlo Technologies competes through subscription-anchored cloud services that extend recurring revenue beyond hardware margins. Samsung Electronics dominates consumer retail channels with integrated smart-home ecosystems that bundle wireless cameras with appliances and displays.
A wireless camera captures and transmits video data without physical cabling, typically operating at 2.4 GHz or 5 GHz frequencies with resolutions spanning 2MP to 8MP and power consumption profiles optimized for battery or solar operation. These devices serve commercial surveillance, residential security, and mobile content creation by eliminating installation constraints of coaxial or Ethernet infrastructure. IP Cameras lead enterprise procurement due to PoE-optional flexibility and ONVIF interoperability, while Video Doorbells capture the fastest consumer growth as porch-piracy concerns reshape last-yard security spending. Wi-Fi technology anchors volume production, though Cellular variants command premium positioning in remote and construction-site deployments where broadband infrastructure remains absent.
FCC Part 15 rules govern unlicensed wireless transmission bands in the United States, directly shaping radio module selection and range claims for devices sold in North America. The EU AI Act and GDPR impose algorithmic transparency and data-retention limits on facial recognition and cloud-analytics features, forcing architecture redesigns for European market access. China's GB standards and MIIT radio-type approval requirements create parallel certification tracks that segment supply chains by destination geography. Stakeholders must monitor evolving spectrum auctions and cross-border data-localization mandates to determine whether regional product variants or unified global platforms deliver superior capital efficiency.
Market Dynamics
The wireless camera market is undergoing a fundamental architecture shift as edge AI inference displaces cloud-dependent analytics, forcing chipset redesigns and power budget reallocations across the entire hardware stack. This transition is compressing development cycles while expanding addressable use cases beyond traditional security into predictive maintenance and retail analytics.
Growth Catalysts
- Wi-Fi 6E Spectrum Allocation:The FCC's 6 GHz band opening eliminates channel congestion in dense urban deployments, enabling 4K streaming without interference degradation in multi-dwelling residential towers.
- Smart City Infrastructure:Municipal procurement in Germany, China, and the United States is standardizing on ONVIF-compliant wireless nodes for traffic monitoring and public safety mesh networks.
- Battery Chemistry Advances:Lithium-thionyl chloride cells and solar harvesting circuits are extending field maintenance intervals beyond 24 months in remote agricultural and construction monitoring.
Market Restraints
- Image Sensor Supply Concentration:Sony and OmniVision control CMOS wafer capacity, creating allocation bottlenecks when smartphone and automotive demand peaks collide.
- GDPR Algorithmic Transparency:The EU AI Act's facial recognition audit requirements impose documentation burdens that add 8-14 months to European product launches.
- Ethernet-over-Coax Substitution:Existing analog infrastructure upgrades using MoCA adapters delay full wireless replacement cycles in budget-constrained commercial retrofits.
Strategic Opportunities
- India Smart Cities Mission:The country's urban transformation program targets 100 metropolitan deployments where trenching costs make wireless the only viable last-mile video option.
- Insurance Premium Incentives:US property underwriters are discounting premiums 5-15% for residential policyholders with verified video doorbell coverage, creating direct consumer pull-through.
- Computer Vision-Edge Convergence:TinyML frameworks running on Ambarella and Qualcomm silicon are enabling on-device package detection and perimeter analytics without recurring cloud fees.
Industry Challenges
- Firmware Security Patching:IoT device fleets require OTA update infrastructure that most hardware OEMs lack, exposing installed bases to botnet recruitment and liability exposure.
- Multi-Protocol Integration:Thread, Zigbee, Z-Wave, and proprietary smart home ecosystems demand engineering resources that fragment R&D budgets and delay certification completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Camera Market |
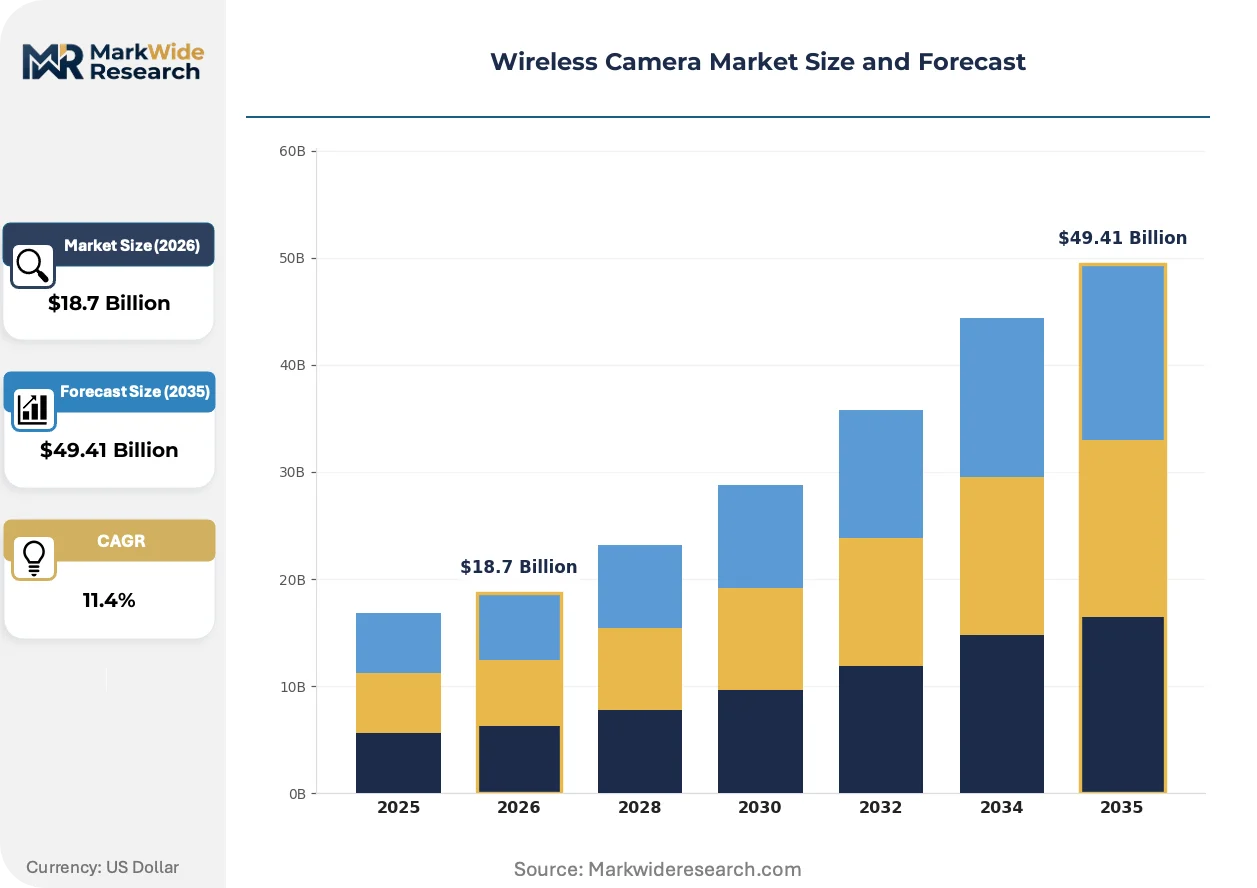
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Cameras, Action Cameras, Video Doorbells, Body Cameras Technology: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Consumers, SMBs, Enterprises, Security Professionals Application: Home Security, Retail Surveillance, Event Monitoring, Wildlife Observation |
| Companies Covered | Arlo Technologies, Hikvision, FLIR Lorex, Samsung Electronics, Amazon, Google, Canon, Dahua Technology, Wyze Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Camera Market Evolving Landscape
Edge-native processing architectures are displacing cloud-reliant pipelines, redistributing computational load and reshaping how vendors monetize hardware through software attach rates rather than subscription dependency.
System-in-package (SiP) modules integrating ISP, neural accelerator, and radio transceiver is miniaturizing board footprints below 25mm square. Wearable and drone-mounted camera manufacturers in South Korea and Japan are adopting these integrated stacks for sub-50 gram payload requirements. The compression of physical dimensions is enabling entirely new form factors—button cameras, eyeglass mounts, and wildlife collar tags—that were mechanically impossible with discrete component layouts.
REACH substance restrictions and RoHS recast directives in Europe are phasing out cadmium-based quantum dots and certain brominated flame retardants from camera housings and PCB substrates. Manufacturers serving EU markets are reformulating polymer compounds and resubmitting technical documentation to notified bodies. Consumer electronics with direct skin contact—baby monitors, pet wearables—face the tightest compliance timelines and are driving material substitution decisions across global supply chains.
Residential buyers are consolidating vendor relationships within single smart home ecosystems rather than assembling point solutions. Amazon Alexa, Google Home, and Apple HomeKit certification requirements are becoming gatekeeping filters that determine retail shelf placement and online discoverability. This preference consolidation is most pronounced in the United States and United Kingdom, where voice assistant penetration exceeds 60% of broadband households and interoperability claims directly influence purchase decisions.
Wireless Camera Market Segmentation
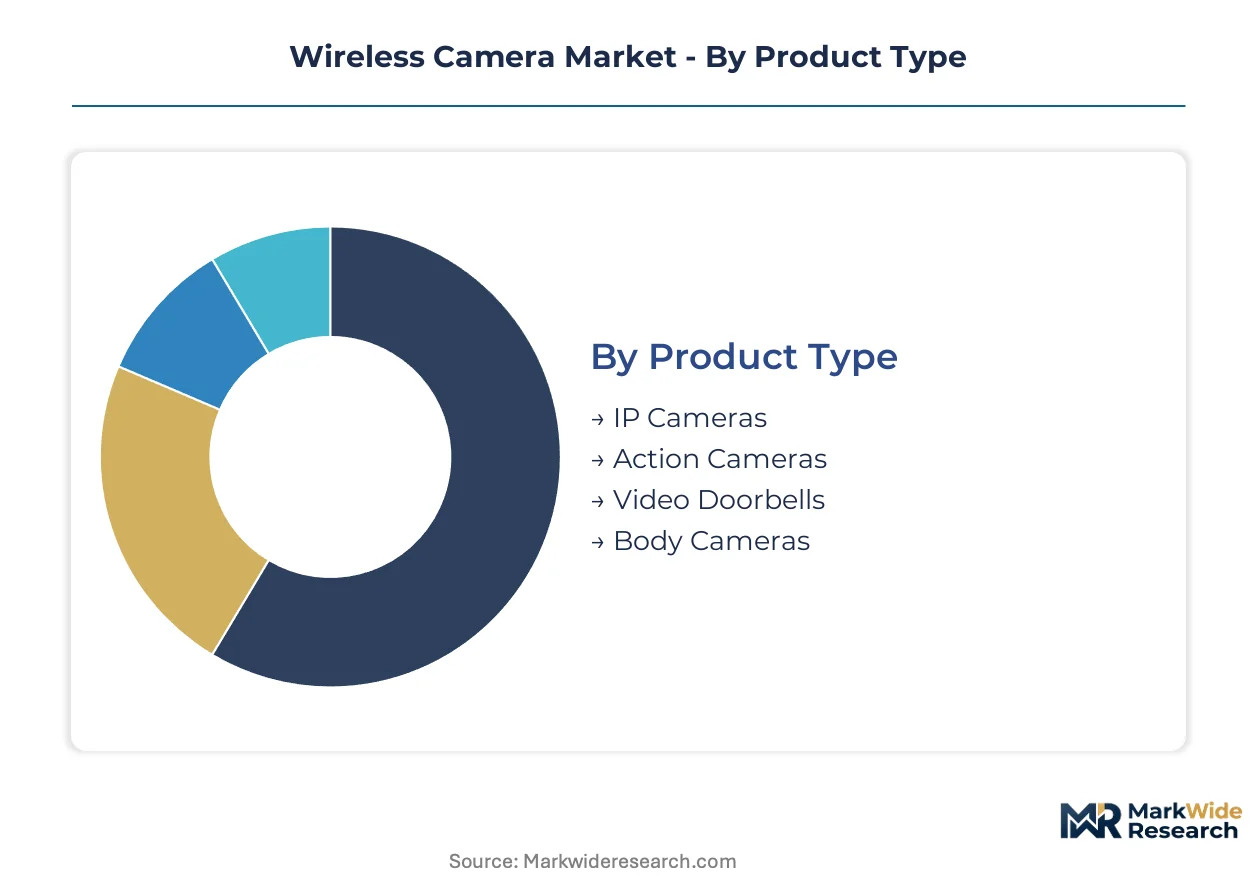
Wireless camera purchasing patterns diverge sharply across use cases and connectivity requirements, with professional security buyers prioritizing ONVIF interoperability while residential consumers favor ecosystem integration over standalone specifications.
Product Type:
IP Cameras and Video Doorbells anchor domestic procurement volumes in the United States and China, while Action Cameras and Body Cameras serve export-led demand from content creators and law enforcement agencies.
- IP Cameras:These devices transmit video over Internet Protocol networks with PoE-optional flexibility and ONVIF compliance for enterprise security systems. Demand concentrates in Germany and the United States where municipal smart city budgets fund traffic monitoring and public safety mesh deployments constrained by trenching costs.
- Video Doorbells:Battery-powered or hardwired units with two-way audio and cloud storage integration target residential porch-piracy concerns. United States insurance premium discounts of 5-15% for verified coverage accelerate consumer adoption faster than any other product segment.
- Action Cameras:Ruggedized, mountable devices for sports and adventure content creation with waterproof housings and stabilization.
- Body Cameras:Wearable units for security personnel and law enforcement with evidence-chain encryption and shift-long battery operation.
IP Cameras holds the largest share; momentum sits with Video Doorbells.
Technology:
Cost tiers separate volume production from premium positioning, with Wi-Fi dominating consumer price points and Cellular commanding remote deployment premiums where broadband infrastructure is absent.
- Wi-Fi:Operating at 2.4 GHz and 5 GHz with emerging 6 GHz Wi-Fi 6E support, this technology enables 4K streaming in dense urban residential towers. FCC 6 GHz band allocations eliminate channel congestion in multi-dwelling United States deployments where interference previously degraded performance.
- Cellular:LTE and 5G modules provide connectivity in agricultural, construction, and wilderness locations without fixed broadband. China MIIT radio-type approval requirements and United States FCC Part 15 certification create parallel tracks that segment supply chains by destination geography.
- Bluetooth:Short-range protocol for setup, configuration, and proximity-based triggers in battery-constrained devices.
- Zigbee:Low-power mesh networking for smart home ecosystem integration with extended standby operation.
Wi-Fi commands absolute volume; Cellular climbs the fastest as remote monitoring expands beyond infrastructure limits.
End User:
Customer type determines procurement sophistication, with Enterprises and Security Professionals demanding SLA-backed support while Consumers and SMBs prioritize retail availability and self-installation.
- Enterprises:Large organizations with centralized IT security policies and vendor consolidation mandates. These buyers standardize on Hikvision and Axis supply lines for campus and facility deployments across the United States, China, and Germany.
- Consumers:Residential households purchasing through Amazon, Best Buy, and carrier retail channels. Arlo Technologies and Ring compete through subscription-anchored cloud services that extend recurring revenue beyond hardware margins in voice assistant-integrated homes.
- SMBs:Small and medium businesses with limited IT staff seeking plug-and-play solutions without enterprise complexity.
- Security Professionals:Monitoring service providers and integrators requiring centralized management platforms and alarm verification protocols.
Enterprises dominate absolute spending; Consumers gain share fastest through insurance incentives and smart home bundling.
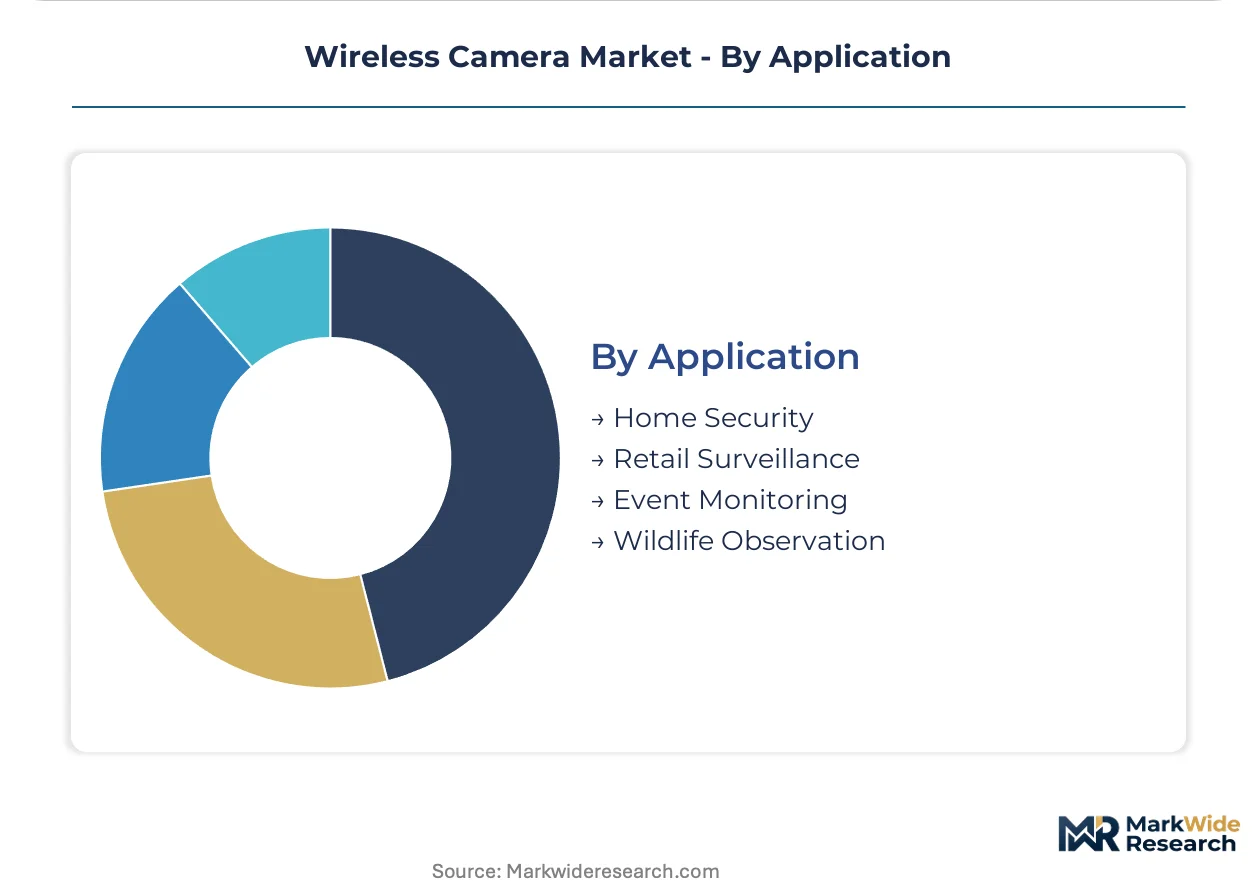
Application:
Application maturity varies by regulatory exposure, with Home Security and Retail Surveillance facing GDPR algorithmic transparency requirements while Wildlife Observation operates with minimal compliance burden.
- Home Security:Residential perimeter monitoring, package detection, and intrusion alerting with mobile notification integration. United Kingdom and United States households with voice assistant penetration exceeding 60% consolidate vendor relationships within single ecosystems rather than assembling point solutions.
- Retail Surveillance:In-store traffic analysis, loss prevention, and heat-mapping for merchandising optimization. EU AI Act facial recognition audit requirements impose 8-14 month documentation delays for European product launches, forcing architecture redesigns for market access.
- Event Monitoring:Temporary deployment for concerts, sports, and public gatherings with rapid installation requirements.
- Wildlife Observation:Battery and solar-powered trail cameras for research and hobbyist use in remote locations without infrastructure.
Home Security holds the largest share; Retail Surveillance shows steepest expansion trajectory as computer vision analytics commoditize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing for wireless camera modules clusters in East Asian manufacturing corridors, while demand generation spreads across three continents with distinct regulatory and infrastructure profiles.
United States
FCC Part 15 rules governing unlicensed 6 GHz spectrum allocation are accelerating Wi-Fi 6E device certification cycles. Insurance premium discounts of 5-15% for verified video doorbell coverage are pulling residential adoption faster than hardware replacement alone. Silicon Valley and Austin clusters host cloud analytics engineering for edge AI inference stacks.
China
MIIT radio-type approval requirements and GB standards create parallel certification tracks that segment supply chains by destination geography. The Smart Cities Mission is deploying ONVIF-compliant wireless nodes for traffic monitoring where trenching costs prohibit cabled infrastructure. Shenzhen and Hangzhou manufacturing bases anchor professional-grade CMOS module production for enterprise security exports.
Germany
EU AI Act algorithmic transparency mandates and GDPR data-retention limits are forcing architecture redesigns for facial recognition features. Municipal procurement is standardizing wireless mesh networks for public safety applications across urban cores. Bavaria and Baden-Württemberg industrial corridors concentrate system integrator expertise for European enterprise deployments.
India
The Smart Cities Mission targeting 100 metropolitan deployments is making wireless the only viable last-mile video option given trenching cost constraints. TRAI spectrum management and BIS certification requirements are shaping radio module selection for domestic market entry. Bangalore and Hyderabad technology clusters are developing localized firmware for battery-optimized agricultural monitoring applications.
Japan
METI energy efficiency guidelines and JIS standards are driving low-power design requirements for battery-constrained devices. Wearable and drone-mounted camera manufacturers are adopting system-in-package modules for sub-50 gram payload requirements. Tokyo and Osaka metropolitan areas concentrate R&D for wildlife collar tags and eyeglass-mounted form factors.
Wireless Camera Market Competitive Landscape
Concentration sits with diversified electronics conglomerates and specialized security technology vendors competing across tiered price-performance segments. The vendor base spans vertically integrated component manufacturers, cloud-service bundlers, and ecosystem-integrated consumer brands. Two strategic archetypes dominate: manufacturing-scale suppliers anchoring enterprise procurement, and subscription-anchored platforms extending recurring revenue beyond hardware margins. Competitive moves center on edge AI silicon partnerships and smart home ecosystem certification races.
Among the manufacturing-scale tier, Hikvision and Dahua Technology represent integrated supply chain control from image sensor sourcing to finished device assembly. Arlo Technologies occupies a position within the subscription-anchored archetype, exemplifying cloud-service bundling that extends customer lifetime value. Samsung Electronics anchors the ecosystem-integrated tier, bundling wireless cameras with appliance and display portfolios. These three companies collectively illustrate the strategic segmentation between enterprise security procurement, consumer recurring revenue models, and smart home platform consolidation.
| Leading Market Players |
|---|
| Arlo Technologies |
| Hikvision |
| FLIR Lorex |
| Samsung Electronics |
| Amazon |
| Canon |
| Dahua Technology |
| Wyze Labs |
| Others |
Value Network & Pricing Analysis
Silicon-to-substrate substitution in image sensor packaging is redrawing manufacturing maps from Japan toward Taiwan and South Korea while compressing module costs for mid-tier Wi-Fi camera producers. This displacement simultaneously concentrates wafer-level supply in East Asian foundry corridors and erodes pricing power for legacy CMOS suppliers serving 1080p volume segments.
Pricing Analysis
FCC Part 15 certification tiers dictate the pricing tier structure separating professional-grade ONVIF-compliant units from consumer retail SKUs. Three-tier pricing structure across premium, standard, and economy levels aligns with AI feature depth and cloud storage bundling rather than hardware specifications alone. Cost compression in the standard tier is intensifying because Arlo Technologies and Ring are subsidizing hardware through subscription attach rates. Enterprise security buyers show least price sensitivity due to SLA requirements, while SMB procurement teams drive hardest bargain negotiations.
Supply Chain Analysis
China and Taiwan anchor CMOS image sensor wafer fabrication and system-in-package module assembly for wireless camera production. Sony and OmniVision supply chains draw from Japanese precision equipment and South Korean memory components. Single-source vulnerability concentrates in Sony's CMOS allocation decisions when smartphone and automotive demand peaks collide. Distribution runs through Shenzhen electronics markets for white-label procurement and Amazon-Best Buy retail channels for branded consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are multiplying as edge AI inference requirements splinter demand between cloud-dependent and on-device processing architectures. This technical bifurcation creates distinct vendor ecosystems where no single incumbent dominates both hardware and silicon layers.
For Market Incumbents: Secure upstream control over neural accelerator silicon partnerships with Ambarella and Qualcomm before edge-native architectures commoditize cloud analytics revenue. Hikvision and Dahua Technology must accelerate ONVIF-optional firmware development to defend against subscription-anchored competitors. Certification investment in EU AI Act compliance documentation represents the critical lever for European market retention. For New Entrants and Emerging Players: Firmware security patching as a managed service presents an exploitable gap where hardware OEMs lack OTA infrastructure expertise. Agricultural monitoring in India offers the most penetrable geography given trenching cost constraints and government procurement volume. A channel partnership with domestic system integrators in Bangalore and Hyderabad provides the fastest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors ecosystem-integrated consumer brands over standalone hardware vendors. Long-term viability hinges on recurring revenue attachment rates rather than unit shipment volumes. Acquisition targets should demonstrate HomeKit-Alexa-Google Home triple certification and sub-50 gram SiP integration capabilities. The signal to watch is insurance premium incentive expansion beyond the United States into European property markets.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Partnership | Qualcomm and Ambarella neural accelerator integration enables on-device analytics without cloud fees. |
| Smart Home Ecosystem Certification | HomeKit-Alexa-Google Home triple certification determines retail shelf placement in voice-assistant households. |
| Regional Compliance Investment | EU AI Act documentation preparation prevents 8-14 month European launch delays for facial recognition features. |
| Battery Chemistry Supplier Agreement | Lithium-thionyl chloride cell sourcing from South Korean suppliers extends field maintenance intervals beyond 24 months. |
| Insurance Channel Partnership | Verified video doorbell coverage unlocks 5-15% premium discounts that accelerate consumer pull-through. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across enterprise security procurement teams, smart home ecosystem engineers, CMOS foundry operations managers, and municipal IoT deployment leads. Primary interview findings were cross-referenced against FCC equipment authorization databases, MIIT radio-type approval filings, EU AI Act implementation guidance, and hyperscaler smart home platform disclosures. Bottom-up unit shipment estimates from Shenzhen distribution channels were triangulated with top-down smart city budget allocations across the analysis window.
Across the projection horizon, the analytical framework modeled product type segmentation by connectivity technology and end-user sophistication tier. CAGRs were derived from regression analysis against smart home penetration curves and insurance incentive program rollouts. Forecast inputs incorporated Wi-Fi 6E device certification velocity, edge AI silicon shipment forecasts, and municipal procurement pipeline visibility for traffic monitoring deployments.
Underlying assumptions cover sustained FCC 6 GHz spectrum availability and stable lithium cell pricing, with deviation risk concentrated in Sony CMOS allocation decisions during smartphone demand surges. Forecasts reflect these documented conditions with acknowledged sensitivity to cross-border data localization mandates and REACH substance restriction enforcement timelines. Recalibration cycles align with material shifts in spectrum auction outcomes and insurance underwriting guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Wireless Charger Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Wireless Smart Home Market