
 Mobile Hotspot Device Market | 2026-2036
Mobile Hotspot Device Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Hotspot Device Market Insights
E-commerce distribution is reshaping how mobile hotspot devices reach end buyers, with direct-to-consumer platforms capturing growing share from traditional retail. NETGEAR leverages its established brand strength in networking hardware to sustain premium positioning across online channels. TP-Link Technologies competes aggressively on price while extending its geographic footprint through marketplace listings and regional warehousing. Sierra Wireless specializes in ruggedized enterprise-grade units, anchoring its revenue in B2B distributor relationships rather than mass retail.
A mobile hotspot device is a compact wireless router that converts cellular signals into local Wi-Fi networks, typically supporting 5-15 simultaneous connections through integrated 4G LTE or 5G NR modems with throughput rates exceeding 1 Gbps in premium configurations. These devices serve commercial and consumer users requiring internet access beyond fixed broadband coverage, including remote workers, field service teams, and transit operators. Portable units dominate consumer sales volume due to pocket-sized form factors and battery-powered operation, while 5G NR technology represents the fastest-growing segment as carriers expand millimeter-wave coverage and enterprise buyers prioritize low-latency connectivity. The government end-user category maintains stable procurement cycles through public safety and emergency response budgets, though margin pools remain thinner than in enterprise verticals with customized security requirements.
The FCC in the United States mandates SAR limits and spectrum compliance for all cellular-enabled devices, while CE marking under EU RoHS and RED directives governs market access across European member states. India's TRAI enforces equipment certification through mandatory testing at designated laboratories, adding lead time for foreign manufacturers. Stakeholders must monitor spectrum auction outcomes and carrier network buildout timelines to align product roadmaps with actual deployment velocity rather than announced coverage targets.
Market Dynamics
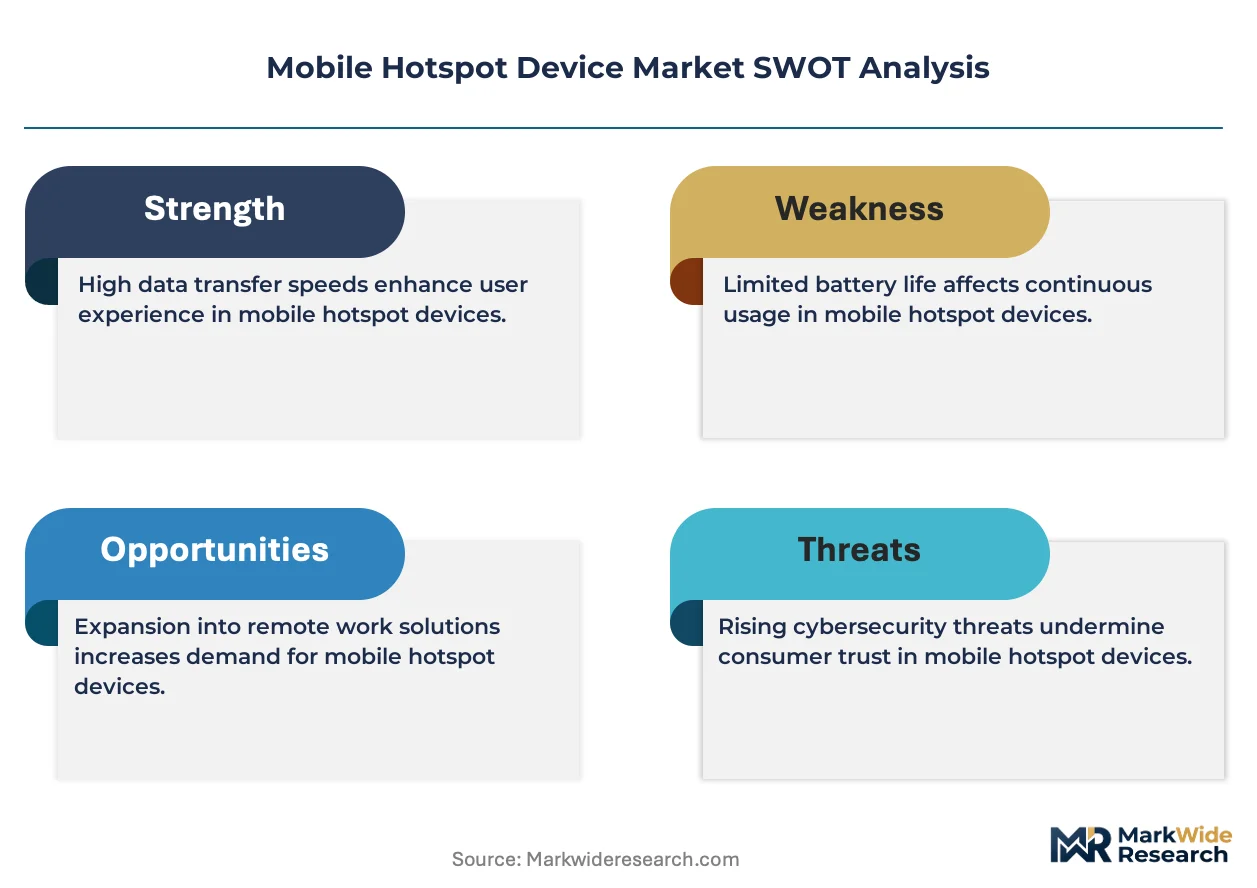
Carrier 5G NR network buildouts are compressing replacement cycles for legacy 4G LTE hardware, forcing manufacturers to accelerate modem certification timelines and recalibrate inventory positions across distribution channels.
Growth Catalysts
- TRAI equipment certification mandates:India's mandatory testing protocols at designated laboratories create formal entry barriers that reward established players with compliance infrastructure already in place.
- Remote workforce connectivity requirements:Enterprise IT departments now provision portable hotspots as standard equipment for distributed teams operating beyond fixed broadband coverage.
- Millimeter-wave spectrum deployment:US carriers expanding mid-band and mmWave coverage are creating addressable demand for premium 5G NR devices capable of multi-gigabit throughput.
Market Restraints
- Modem chipset supply concentration:Qualcomm and MediaTek control premium cellular baseband silicon, creating single-source dependency for tier-one manufacturers.
- FCC SAR testing costs:Specific absorption rate certification for 5G NR devices adds six-figure expenses per SKU, disproportionately burdening low-volume product lines.
- Smartphone tethering substitution:Native hotspot functionality in flagship handsets displaces standalone device demand among casual consumers.
Strategic Opportunities
- Rural digital inclusion programs:India's BharatNet and similar initiatives are expanding subsidy-eligible addressable markets for sub-$50 hardware configurations.
- Fixed wireless access convergence:Hybrid devices bridging portable hotspot and home CPE functions capture subscribers abandoning DSL in underserved US census tracts.
- Emergency responder procurement:FirstNet-certified ruggedized units command premium pricing through dedicated public safety spectrum allocations.
Industry Challenges
- Multi-band antenna engineering talent:Competent RF designers capable of optimizing 5G NR, LTE, and sub-6GHz coexistence command salaries exceeding hardware margin structures.
- Carrier certification queue delays:Major US operators require six-to-nine month validation cycles for network compatibility, freezing product launches behind announced coverage timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Hotspot Device Market |
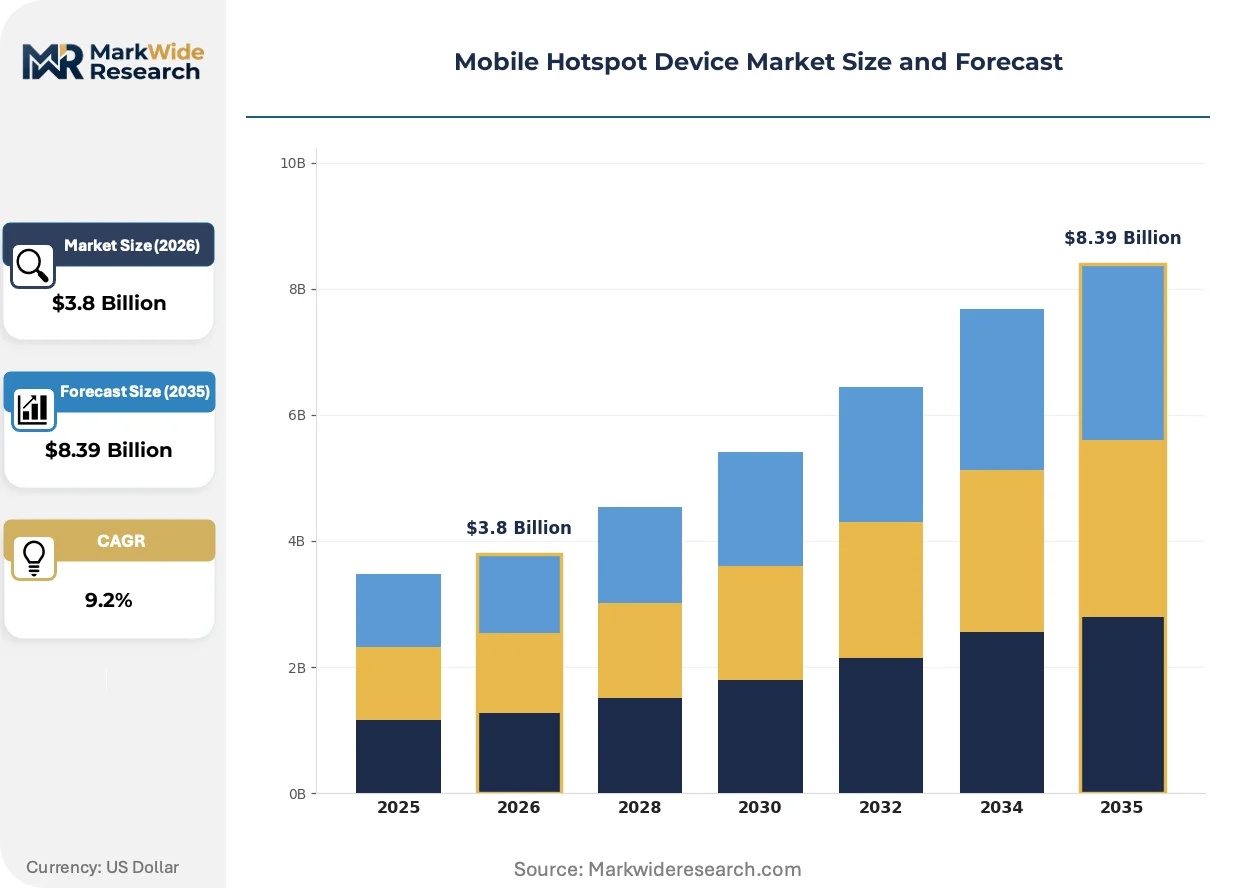
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, USB Dongle, In-Vehicle, Fixed Technology: 4G LTE, 5G NR, Wi-Fi 6, Satellite End User: Consumers, Enterprises, Government, Education Distribution Channel: Online Retail, Telecom Providers, Electronics Stores, B2B Distributors |
| Companies Covered | Huawei Technologies Co., Ltd., NETGEAR, TP-Link Technologies Co., Ltd., D-Link Corporation, Belkin International, Inc., Inseego Corp., Franklin Wireless Corp., Sierra Wireless, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Hotspot Device Market Trends and Innovations
eSIM technology is eliminating physical SIM logistics from device provisioning workflows, compressing time-to-activation from days to minutes and enabling over-the-air carrier switching without hardware replacement.
Embedded eSIM controllers are digitizing subscriber identity management across enterprise fleet deployments. Fortune 500 IT administrators now provision thousands of devices through centralized MDM platforms rather than handling physical SIM cards. This capability is digitizing procurement workflows and compressing operational overhead for distributed workforce connectivity programs.
CE marking under EU RoHS and RED directives now requires expanded documentation for 5G NR devices operating above 6GHz. Manufacturers must submit additional electromagnetic compatibility testing for millimeter-wave bands before accessing European Economic Area distribution channels. German and French national regulators are enforcing these requirements with heightened scrutiny for imported consumer electronics.
Enterprise buyers now specify outcome-based connectivity contracts rather than capital equipment purchases. Field service operators in logistics and utilities negotiate per-gigabyte service agreements where hardware costs are embedded in monthly data fees. This pattern is most pronounced in North American transportation verticals where fleet managers prioritize predictable operating expenditures over upfront device procurement.
Mobile Hotspot Device Market Segmentation
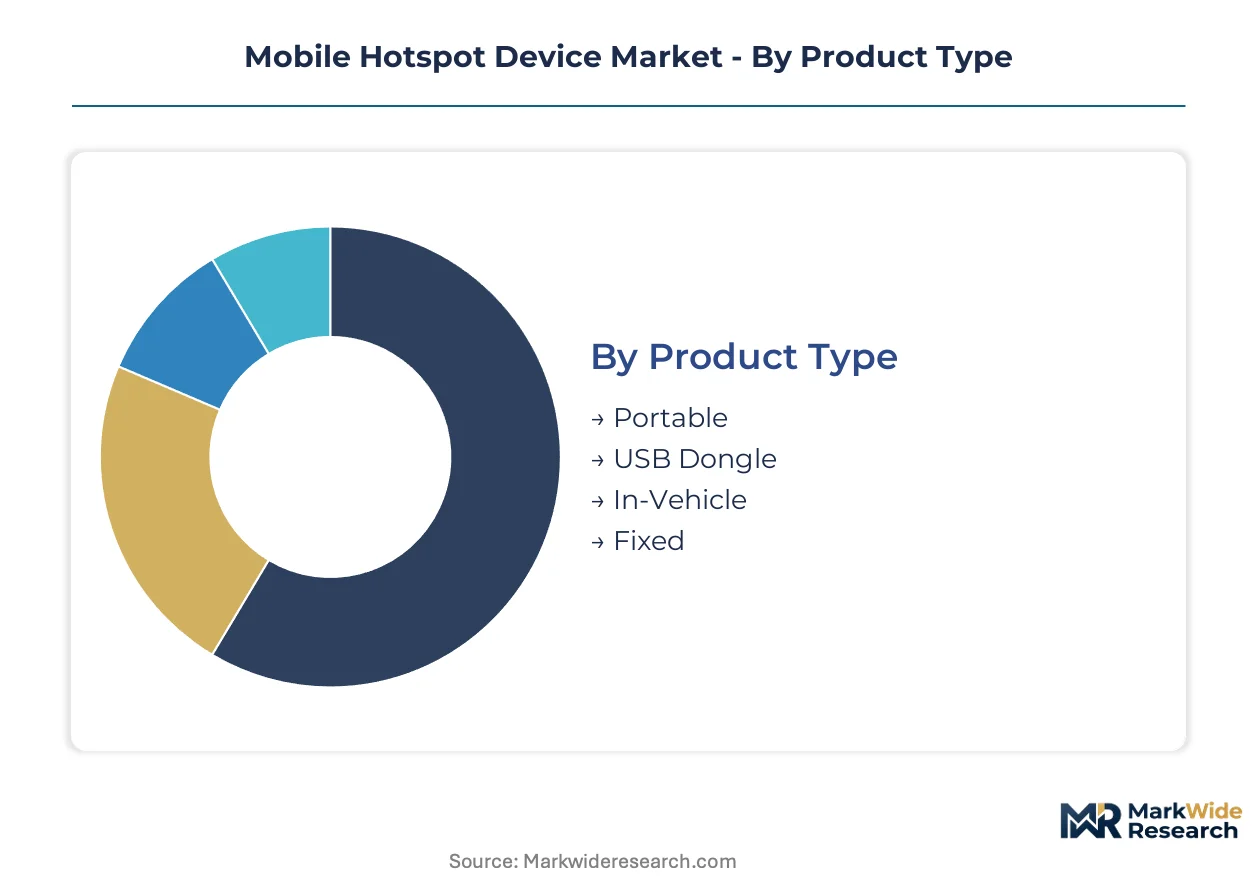
Mobile hotspot device segmentation reveals divergent engineering priorities across form factors and connectivity standards. Procurement patterns vary sharply between consumer impulse purchases and enterprise fleet deployments with centralized management requirements.
Product Type:
Mature pocket-sized configurations dominate consumer volume, while emerging fixed-wireless hybrids capture subscribers abandoning legacy broadband.
- Portable:Battery-powered units with integrated cellular modems support 5-15 simultaneous connections through pocket-sized enclosures. Demand concentrates among remote workers in the United States seeking backup connectivity beyond home broadband coverage, driven by hybrid work normalization and transit-based productivity requirements.
- Fixed:AC-powered desktop units bridge portable hotspot and home CPE functions with external antenna ports for signal optimization. Subscribers in rural US census tracts lacking fiber or cable infrastructure are driving uptake, constrained by carrier network buildout timelines that lag hardware availability.
- USB Dongle:Compact modems drawing power from host device USB ports enable single-user connectivity without battery management.
- In-Vehicle:Ruggedized units with automotive power integration serve fleet operators requiring persistent connectivity across transit routes.
Portable units handle the majority of throughput; Fixed is the fastest mover on share.
Technology:
Cost tiers separate legacy silicon from premium modem configurations capable of multi-gigabit throughput.
- 5G NR:Millimeter-wave and sub-6GHz modems deliver throughput exceeding 1 Gbps in premium configurations with carrier aggregation. Enterprise buyers in India prioritize these units for field service applications, constrained by Qualcomm and MediaTek chipset supply concentration that extends procurement lead times.
- 4G LTE:Mature Cat-6 through Cat-20 modems provide reliable connectivity across broader geographic coverage footprints. Consumer demand in price-sensitive Indian rural markets sustains volume, though carrier spectrum reallocation is compressing replacement cycles.
- Wi-Fi 6:802.11ax local networking interfaces reduce congestion in high-density connection environments.
- Satellite:L-band and Ku-band integration extends coverage beyond terrestrial cellular footprints for maritime and remote applications.
4G LTE handles the majority of throughput; 5G NR is expanding most quickly on share.
End User:
Application requirements dictate security specifications and procurement channel selection.
- Enterprises:Fleet deployments with MDM integration and VPN tunneling capabilities dominate commercial revenue pools. IT departments in North American logistics verticals now provision portable hotspots as standard equipment, driven by distributed workforce connectivity mandates and outcome-based service contract preferences.
- Consumers:Individual purchasers prioritize price accessibility and carrier flexibility through unlocked hardware. Indian digital inclusion programs are expanding subsidy-eligible addressable markets, constrained by TRAI equipment certification mandates that favor established compliance infrastructure.
- Government:FirstNet-certified ruggedized units command premium pricing through dedicated public safety spectrum allocations.
- Education:School district bulk purchases prioritize durability and centralized provisioning for student connectivity programs.
Enterprises handle the majority of throughput; Government is climbing the fastest on share.
Distribution Channel:
Customer type determines whether procurement flows through retail self-service or contracted B2B relationships.
- Telecom Providers:Carrier-branded devices with embedded SIM profiles dominate subscriber acquisition through installment billing integration. Verizon and AT&T retail channels in the United States capture consumers seeking seamless activation, constrained by six-to-nine month network certification queues that freeze product launches.
- B2B Distributors:Value-added resellers with technical integration capabilities serve enterprise fleet deployments requiring staging and configuration. Field service operators in utilities and transportation verticals prefer this channel for outcome-based connectivity contracts with embedded hardware costs.
- Online Retail:Marketplace platforms enable direct-to-consumer price comparison and unlocked device availability.
- Electronics Stores:Big-box retail provides immediate fulfillment for urgent connectivity needs and hands-on product evaluation.
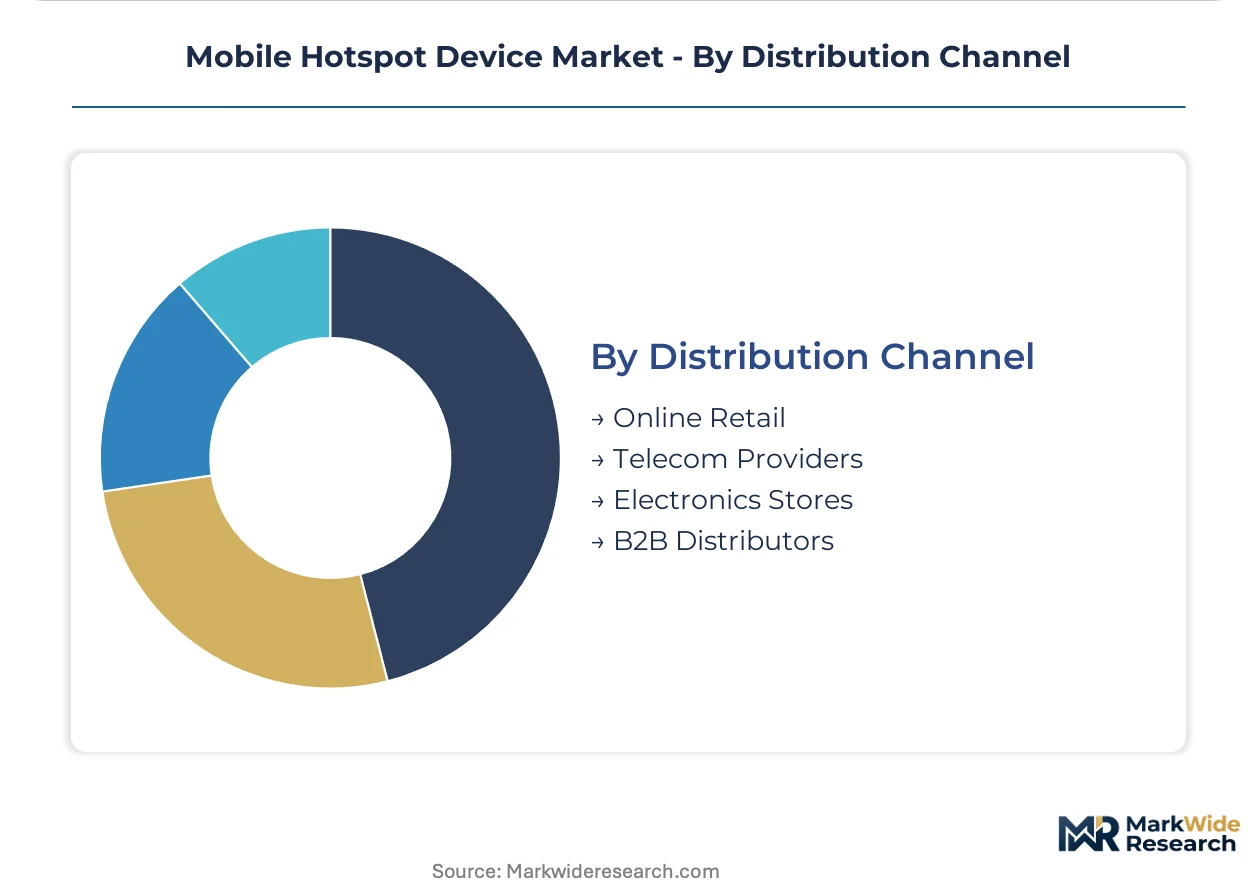
Telecom Providers handle the majority of throughput; B2B Distributors is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors the mobile hotspot device market through its extensive fiber backhaul infrastructure and carrier-grade millimeter-wave deployments. Dense urban corridors along the Northeast Corridor and California's tech clusters concentrate enterprise procurement. Submarine cable landing stations in Virginia Beach and Los Angeles underpin trans-Pacific data flows that sustain roaming-dependent device functionality.
United States
Enterprise fleet deployments and FirstNet public safety procurement drive commercial demand. FCC SAR testing mandates and 5G NR spectrum reallocation compress product launch timelines. Austin and San Jose host hardware engineering clusters where RF optimization talent commands premium compensation.
India
BharatNet rural connectivity initiatives and telecom infrastructure investments expand addressable markets for sub-$50 hardware. TRAI equipment certification at designated laboratories creates formal entry barriers favoring established compliance infrastructure. Bengaluru and Hyderabad concentrate device testing facilities and carrier integration engineering.
Germany
Industrial IoT deployments and automotive fleet connectivity sustain B2B demand for ruggedized units. CE marking under EU RoHS and RED directives governs 5G NR device market access with expanded documentation for millimeter-wave bands. Munich and Stuttgart anchor automotive OEM integration programs requiring embedded hotspot modules.
China
Domestic 5G base station density and export manufacturing capacity shape supply-side dynamics. MIIT equipment certification and GB standards compliance govern domestic market entry. Shenzhen and Dongguan concentrate PCB fabrication and antenna assembly operations serving global OEM brands.
Japan
Disaster resilience mandates and remote workforce connectivity sustain government and enterprise procurement. METI spectrum allocation and JIS standards certification structure device approval workflows. Tokyo and Osaka metropolitan areas concentrate carrier headquarters and enterprise IT decision-making.
Mobile Hotspot Device Market Competitive Landscape
On the supply side, the industry is moderately concentrated with distinct tiering between premium networking brands and price-focused hardware specialists. Tier-one players leverage established carrier relationships and certification infrastructure, while mid-tier competitors compete on cost through regional manufacturing partnerships. Two strategic archetypes dominate: diversified networking conglomerates with broad portfolio breadth, and cellular specialists with deep modem integration expertise. Competitive moves center on eSIM technology licensing and backward integration into RF component design.
Within the diversified networking tier, NETGEAR and TP-Link Technologies exemplify contrasting geographic and channel strategies. Sierra Wireless occupies a position representing the cellular-specialist archetype with enterprise-grade positioning. Shenzhen-based ZTE Corporation and Huawei Technologies anchor the Asia-Pacific supply base. Franklin Wireless and Inseego Corp. exemplify North American-focused modem integration specialists. D-Link Corporation and Belkin International represent mid-tier consumer networking brands competing through retail channel presence.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| NETGEAR |
| TP-Link Technologies Co., Ltd. |
| D-Link Corporation |
| Belkin International, Inc. |
| Inseego Corp. |
| Franklin Wireless Corp. |
| Sierra Wireless |
| ZTE Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Qualcomm and MediaTek baseband silicon fabrication feeds pricing power upstream while compressing margins for downstream OEMs assembling finished devices. This utilization squeeze forces manufacturers to absorb premium chipset costs or pass them to enterprise buyers with lower price elasticity.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet contracts from consumer retail transactions. Pricing stratifies across premium 5G NR configurations with millimeter-wave certification, standard LTE units for rural Indian markets, and economy-tier USB dongles. Cost compression in the economy tier intensifies because TRAI certification mandates disproportionately burden low-volume foreign entrants. Consumer segments in India exhibit highest price sensitivity, while North American logistics operators purchasing through B2B distributors demonstrate lowest sensitivity due to outcome-based contract structures.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for antenna assembly and PCB fabrication operations. Component sourcing centers on Shenzhen and Dongguan for PCB production, Taiwan for RF front-end modules, and South Korea for memory integration. The supply chain rests on concentrated baseband silicon from Qualcomm and MediaTek, creating single-source vulnerability for tier-one manufacturers. Distribution runs through carrier-branded retail channels, B2B value-added resellers, and direct-to-consumer marketplace platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward enterprise fleet operators as procurement concentrates through centralized IT departments negotiating outcome-based connectivity contracts.
For Market Incumbents: Pre-empt smartphone tethering substitution by embedding eSIM controllers that enable over-the-air carrier switching without hardware replacement. Secure backward integration into RF component design to reduce dependency on external antenna engineering talent. Defend against emerging price-focused competitors from Shenzhen by accelerating FirstNet certification for ruggedized public safety units. For New Entrants and Emerging Players: Rural Indian census tracts under BharatNet coverage expansion represent the most penetrable entry point for sub-$50 hardware configurations. Fixed-wireless hybrid devices bridging portable hotspot and home CPE functions capture subscribers abandoning DSL in underserved US markets. Pursue white-label partnerships with regional telecom providers to bypass six-to-nine month carrier certification queues. For Investors and Strategic Acquirers: Long-term, this sits as a connectivity-infrastructure play because enterprise mobility mandates are hardening into permanent IT budget lines rather than pandemic-era temporary measures. Target acquisition candidates with established TRAI compliance infrastructure and existing B2B distributor relationships. Monitor FCC spectrum auction outcomes as the inflection signal for 5G NR deployment velocity versus announced coverage targets.| Strategic Initiative | Industry Significance |
|---|---|
| eSIM Technology Licensing | Enables over-the-air provisioning for enterprise fleet deployments without physical SIM logistics. |
| FirstNet Certification Investment | Unlocks premium pricing through dedicated public safety spectrum allocations and procurement cycles. |
| Backward Integration into RF Design | Captures scarce antenna engineering talent and reduces dependency on external component suppliers. |
| Regional Warehousing Expansion | Compresses delivery timelines for Indian and Southeast Asian digital inclusion program participants. |
| Outcome-Based Service Contract Development | Aligns revenue models with enterprise buyer preferences for predictable operating expenditures. |
Research Methodology
Cross-validation between primary interviews with carrier procurement officers, enterprise IT administrators, and RF hardware engineers anchors the qualitative findings. Secondary validation draws from FCC equipment authorization databases, TRAI certification records, SEC filings of publicly traded networking equipment manufacturers, and carrier network buildout disclosures. Bottom-up demand modeling triangulates against top-down market sizing across portable, fixed, USB dongle, and in-vehicle form factors.
Calibration against historical replacement cycles and announced carrier coverage timelines shapes the projection framework. Segmentation dimensions span product type, connectivity technology, end-user category, and distribution channel, with additional modeling of carrier certification queue durations. CAGRs derive from installed base turnover rates and enterprise fleet penetration assumptions, incorporating millimeter-wave deployment velocity and rural subsidy program enrollment as industry-specific inputs.
Practitioners should monitor FCC spectrum auction outcomes, TRAI equipment certification backlog reports, and Qualcomm/MediaTek utilization rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Multefire Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Distributed Antenna System Market