
 Wireless Intercom Equipment Market | 2026-2036
Wireless Intercom Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Intercom Equipment Market Insights
Southeast Asia is narrowing the supply gap for wireless intercom components as contract manufacturers in Vietnam and Thailand expand RF assembly capacity. Motorola Solutions sustains dominant positioning in public safety-grade intercom systems through hardened encryption protocols and FirstNet compatibility. Panasonic Corporation leverages its broad electronics portfolio to integrate intercom functions with surveillance and access control platforms. Clear-Com, LLC specializes in matrix-based distributed intercom architectures that serve live event production and broadcast customers across North America and Europe.
Wireless intercom equipment comprises audio and video communication terminals that transmit signals via radio frequency, Wi-Fi, or Bluetooth protocols without dedicated copper infrastructure, typically operating in the 2.4 GHz, 5 GHz, or DECT frequency bands with latency thresholds under 50 milliseconds for real-time coordination. These systems enable instant two-way or group communication across security checkpoints, production floors, school campuses, and residential complexes where cabling proves impractical or cost-prohibitive. Digital intercom systems now command the strongest margin pools as AES67 and Dante networked audio standards displace analog matrix architectures in professional installations. Video intercom applications are expanding fastest among residential and commercial end users, driven by smartphone-based remote entry management and SIP protocol integration with unified communications platforms. Analog intercom persists in price-sensitive industrial and educational settings where basic voice functionality satisfies operational requirements without IP network dependency.
The FCC governs unlicensed spectrum allocation and emission limits for wireless intercom devices sold in the United States, while CE marking and the Radio Equipment Directive enforce RF safety and interoperability standards across European Economic Area member states. Japan's MIC and TELEC certifications impose additional spurious emission controls that filter lower-quality competitors from East Asian procurement channels. Stakeholders must monitor evolving spectrum reallocation decisions and cybersecurity labeling requirements that will determine which product architectures retain market access across major economies.
Market Dynamics
Digital audio networking standards are compressing product lifecycles across wireless intercom equipment as AES67 and Dante protocols displace legacy analog matrix architectures in professional installations, forcing manufacturers to reengineer hardware roadmaps and certification pipelines.
Growth Catalysts
- Healthcare facility modernization:Nurse call integration mandates and patient safety workflow digitization are pulling IP-based intercom systems into hospital infrastructure upgrades across Germany and the United States.
- FCC Part 15 spectrum access:Unlicensed 2.4 GHz and 5 GHz device certification frameworks lower market entry barriers for RF equipment manufacturers targeting North American commercial and residential verticals.
- Live event production recovery:Broadcast and entertainment venues are rebuilding distributed intercom infrastructure to support hybrid in-person and remote production coordination requirements.
Market Restraints
- RF component supply concentration:Power amplifier and low-noise amplifier module production clusters heavily in Taiwan and South Korea, exposing equipment manufacturers to single-source disruption risk.
- Copper-alternative material cost volatility:Lithium niobate and gallium nitride substrate prices fluctuate with semiconductor foundry utilization rates, compressing margins on high-performance RF front ends.
- Legacy analog infrastructure lock-in:Educational institutions and industrial facilities with sunk investment in two-wire party-line systems delay full IP migration despite superior digital feature sets.
Strategic Opportunities
- SIP protocol convergence:Session Initiation Protocol integration with unified communications platforms is opening residential and small commercial video intercom segments previously isolated from enterprise telecom ecosystems.
- Vietnam contract manufacturing expansion:RF assembly capacity growth in Ho Chi Minh City and Hanoi offers tariff-advantaged production alternatives for equipment serving ASEAN procurement channels.
- Smartphone-native entry management:Cloud-connected video intercom systems with mobile credentialing are penetrating multi-tenant housing developments where traditional hardwired panels dominated.
Industry Challenges
- AES67/Dante certification backlog:Professional audio networking compliance testing queues at certified laboratories extend product launch timelines by four to eight months.
- Embedded systems cybersecurity labeling:Emerging FCC and EU cybersecurity hardware certification requirements demand firmware architecture redesigns that strain legacy product platforms.
- RF engineer talent scarcity:Specialized microwave and antenna design expertise concentrates at defense contractors and telecom infrastructure vendors, limiting hiring pools for commercial intercom developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Intercom Equipment Market |
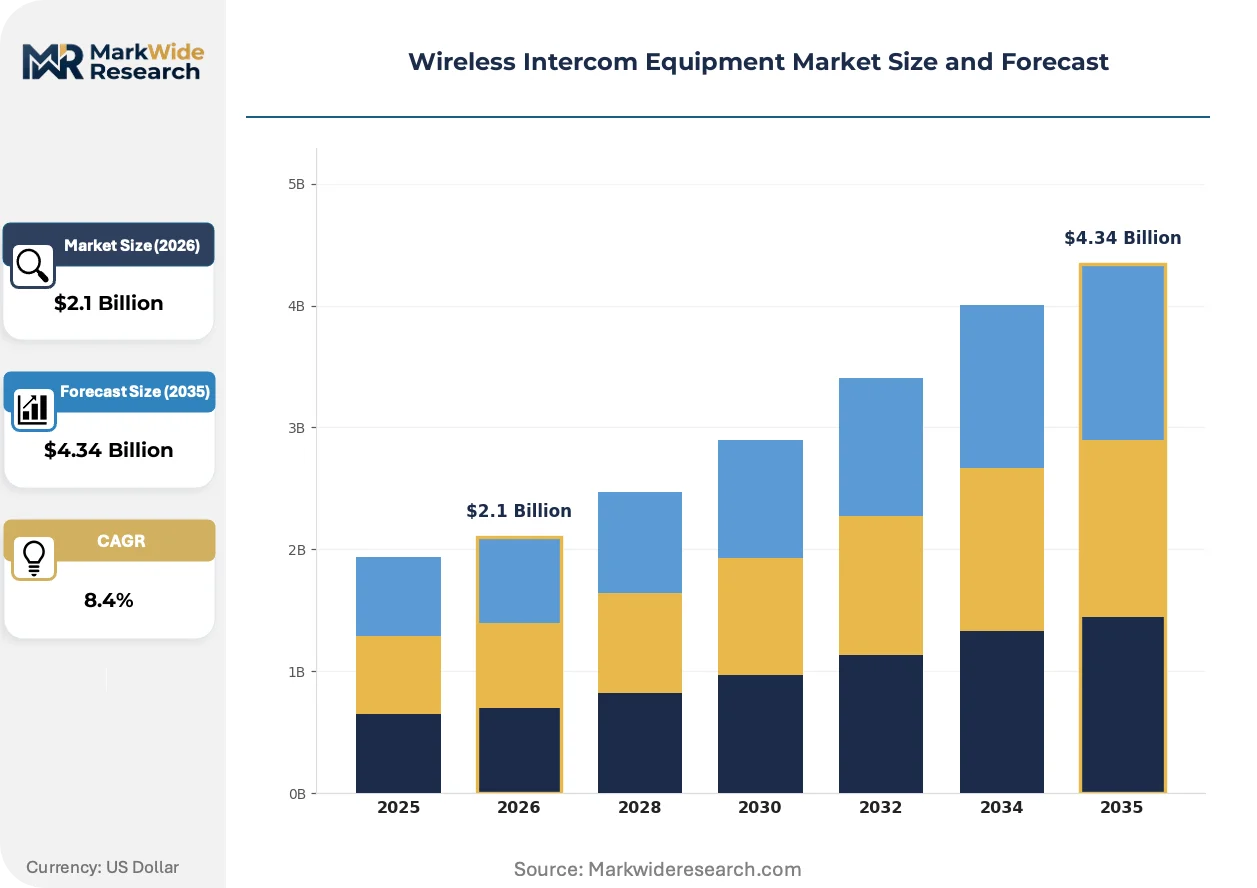
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Intercom, Digital Intercom, Video Intercom, Intercom Systems Technology: Wireless, Wired, Bluetooth, Wi-Fi Application: Residential, Commercial, Industrial, Educational End User: Households, Offices, Factories, Schools |
| Companies Covered | Panasonic Corporation, Motorola Solutions Inc., Clear-Com, LLC, Riedel Communications GmbH & Co. KG, Zenitel NV, Telephonics Corporation, Commend International GmbH, RTS Intercom Systems, Aiphone Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Intercom Equipment Market Trends and Innovations
Wireless intercom architectures are fragmenting across protocol layers as manufacturers balance latency performance against installation flexibility, with audio-over-IP standards, cloud management platforms, and edge AI processing each pulling product roadmaps in distinct directions.
Matrix intercom technology is hybridizing with IP network backbones to preserve sub-50 millisecond latency guarantees while enabling campus-scale deployment without dedicated copper trunking. Live event production houses and broadcast facilities are adopting these hybrid architectures fastest, consolidating previously separate party-line, point-to-point, and wireless beltpack systems onto unified Dante or AES67 network fabrics. This convergence is compressing demand for pure analog matrix frames while expanding attach rates for network edge devices and software-defined routing licenses.
Japan's MIC and TELEC certification regimes are tightening spurious emission limits for 2.4 GHz and 5 GHz wireless devices, filtering lower-quality RF designs from East Asian procurement channels. Equipment manufacturers must now submit to additional pre-scan testing and documentation review cycles that add six to ten weeks to product validation timelines. Professional broadcast and industrial intercom suppliers with established Tokyo testing relationships are absorbing these compliance costs more readily than emerging competitors, reinforcing quality-tier segmentation in Japanese market access.
Facility managers are unbundling intercom hardware procurement from long-term maintenance contracts, shifting toward modular component sourcing and cloud-managed service subscriptions. This purchasing pattern disrupts traditional integrator-dominated distribution channels in North American education and healthcare verticals, favoring direct manufacturer relationships and e-commerce procurement platforms. The shift is most visible in K-12 school district technology refresh cycles, where capital budget constraints and in-house IT staffing expansion enable self-directed system specification and installation.
Wireless Intercom Equipment Market Segmentation
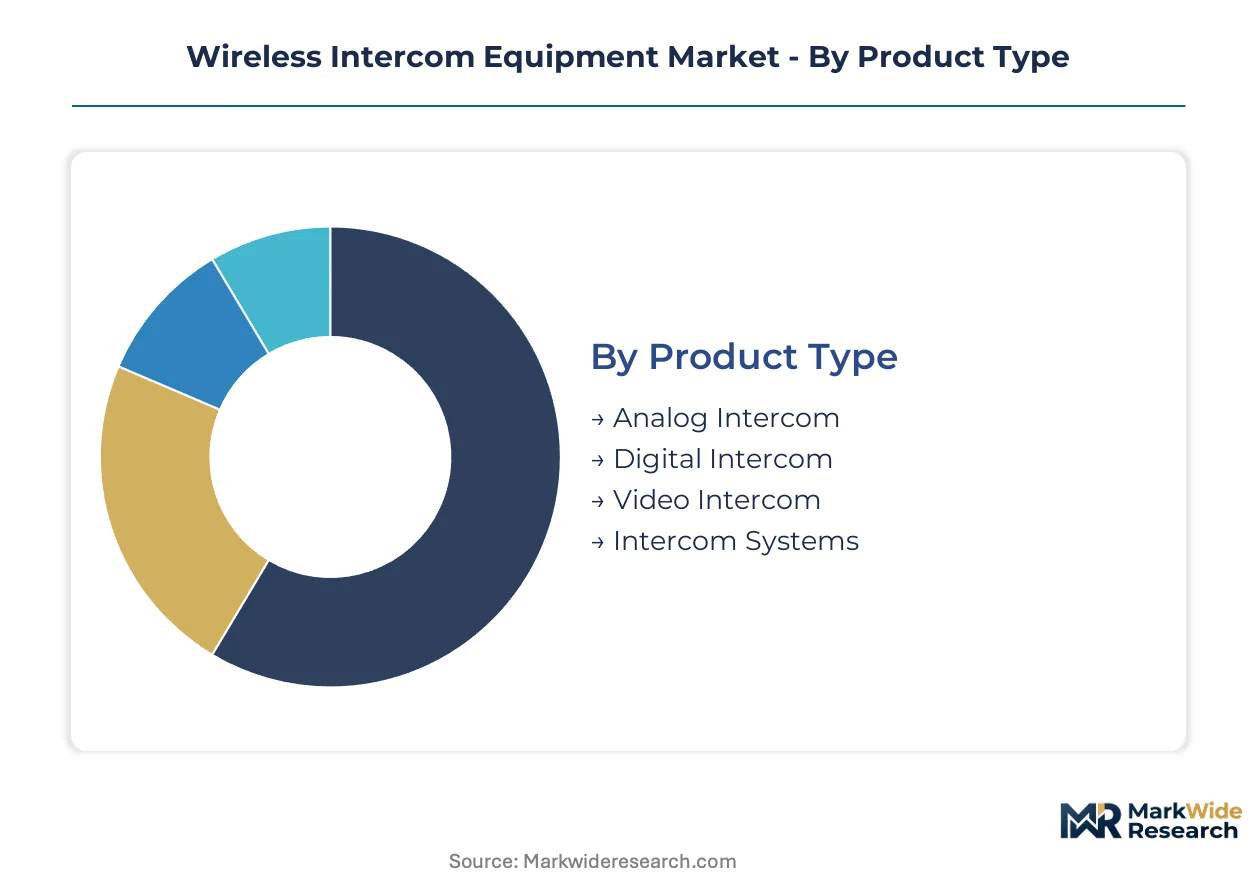
Wireless intercom equipment segments diverge sharply in service attachment rates, with professional installations demanding multi-year maintenance contracts while consumer-grade products ship with minimal post-sale support. Understanding these tiered service economics helps manufacturers calibrate channel strategies and warranty pricing across divergent buyer profiles.
Product Type:
After-sales-service intensity escalates dramatically from residential doorbell units to enterprise matrix systems, with digital platforms requiring firmware update subscriptions and analog hardware needing physical component replacement programs.
- Digital Intercom:AES67 and Dante networked audio architectures dominate professional broadcast and healthcare deployments. Hospital infrastructure upgrades in Germany and the United States pull IP-based systems into nurse call integration workflows, with firmware maintenance contracts extending across seven-to-ten year operational lifecycles.
- Video Intercom:Cloud-connected terminals with smartphone credentialing and SIP protocol integration are penetrating multi-tenant housing developments. Residential and commercial end users in North American and European cities drive specification shifts toward mobile-native entry management platforms.
- Analog Intercom:Two-wire party-line systems persist in price-sensitive educational and industrial settings where basic voice functionality satisfies requirements without IP network dependency.
- Intercom Systems:Integrated hardware-software bundles serving campus-scale deployments combine matrix frames, beltpacks, and base stations under unified management platforms.
Digital intercom holds the largest share; momentum sits with video intercom.
Technology:
Cost tier stratification separates licensed-spectrum professional gear from unlicensed consumer equipment, with RF component quality and certification depth determining pricing bands.
- Wireless:Radio frequency systems operating in 2.4 GHz, 5 GHz, and DECT bands deliver sub-50 millisecond latency for real-time coordination across security checkpoints and production floors. FCC Part 15 certification requirements shape North American market access for unlicensed device manufacturers.
- Wi-Fi:IEEE 802.11-based architectures enable smartphone-native management and cloud backend integration. Residential video intercom deployments in urban multi-tenant buildings favor Wi-Fi for existing infrastructure leverage.
- Bluetooth:Short-range protocols serve proximity-based access control and portable beltpack applications with simplified pairing workflows.
- Wired:Dedicated copper infrastructure persists in facilities requiring electromagnetic interference immunity and guaranteed latency floors.
Wireless technology commands the broadest installed base; Wi-Fi is climbing the fastest.
Application:
Customer type differentiation separates capital-constrained institutional buyers from performance-driven commercial operators, with procurement authority resting variously with facilities managers, IT directors, or security consultants.
- Healthcare:Nurse call integration mandates and patient safety workflow digitization pull IP-based systems into hospital infrastructure upgrades.
- Commercial:Office complexes and retail environments specify video intercom with unified communications platform integration.
- Industrial:Manufacturing floors and warehouses prioritize hardened enclosures and electromagnetic compatibility certification.
- Educational:K-12 districts and university campuses balance capital budget constraints against in-house IT staffing capabilities for self-directed installation.
Commercial application holds the largest share; healthcare is expanding most quickly.
End User:
Volume concentration varies enormously across these four endpoints, with factory deployments scaling to thousands of nodes while household purchases typically involve single-door installations.
- Factories:Industrial facilities require distributed coordination across production lines, warehousing zones, and safety checkpoints with integration into plant-wide communication networks.
- Offices:Corporate environments demand lobby-to-suite video verification and mobile credentialing for hybrid workforce access patterns.
- Schools:Educational institutions prioritize emergency broadcast capabilities and perimeter lockdown integration with district-wide security protocols.
- Households:Residential consumers select cloud-connected doorbell cameras with two-way audio and remote entry release via smartphone applications.
Factory end users represent the highest node counts per deployment; households are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF assembly capacity concentrates in East Asian contract manufacturing clusters, while end-use demand distributes across healthcare modernization programs in Germany, public safety infrastructure in the United States, and broadcast facility upgrades in Japan. Regulatory certification requirements fragment market access, with each major economy enforcing distinct emission limits and cybersecurity protocols.
United States
Healthcare facility modernization and public safety infrastructure renewal drive procurement of IP-based intercom systems with nurse call integration and FirstNet compatibility. FCC Part 15 rules governing unlicensed 2.4 GHz and 5 GHz devices shape product certification requirements and market entry barriers for RF equipment manufacturers. Dallas-Fort Worth and Chicago anchor dense integrator networks serving K-12 education and municipal security verticals with self-directed installation capabilities.
Germany
Hospital infrastructure digitization mandates and industrial facility safety compliance pull AES67-enabled intercom systems into nurse call workflows and manufacturing floor coordination. CE marking and the Radio Equipment Directive enforce RF safety and interoperability standards across European Economic Area procurement channels. Berlin and Munich host concentrated supplier ecosystems where Riedel Communications and Commend International anchor broadcast and industrial vertical service networks.
Japan
Broadcast facility hybridization and live event production recovery accelerate adoption of Dante-networked intercom architectures with sub-50 millisecond latency guarantees. MIC and TELEC certification regimes impose tightened spurious emission limits that filter lower-quality RF designs from procurement channels. Tokyo testing relationships and Osaka industrial electronics clusters concentrate compliance expertise and professional audio networking integration capabilities.
Vietnam
ASEAN procurement channel expansion and tariff-advantaged production positioning attract RF assembly migration from traditional East Asian manufacturing bases. Contract manufacturers in Ho Chi Minh City and Hanoi scale power amplifier and low-noise amplifier module production to serve regional equipment demand. Electronics manufacturing services clusters in the Red River Delta develop specialized capabilities for 2.4 GHz and 5 GHz device assembly.
South Korea
Semiconductor foundry utilization and gallium nitride substrate supply concentration expose equipment manufacturers to single-source disruption risk for high-performance RF front ends. National RF component production clusters in Suwon and Pyeongtaek supply power amplifier modules to wireless intercom equipment assemblers across Asia-Pacific. Domestic industrial safety regulations and smart factory initiatives sustain demand for hardened intercom systems with electromagnetic compatibility certification.
Wireless Intercom Equipment Market Competitive Landscape
Broad-based electronics conglomerates and specialized professional audio suppliers split the market across divergent capability requirements. The vendor base stratifies into three tiers: diversified technology holdings with surveillance and access control integration capabilities, dedicated intercom specialists with matrix-based distributed architectures, and regional component assemblers serving price-sensitive verticals. Strategic moves concentrate on AES67/Dante certification acceleration and Vietnam contract manufacturing expansion to capture ASEAN procurement growth.
Within the diversified technology tier, Panasonic Corporation represents integrated platform positioning across electronics portfolios, while Motorola Solutions exemplifies public safety-grade specialization through hardened encryption protocols. Among dedicated intercom specialists, Clear-Com, LLC occupies a position serving live event production and broadcast customers with matrix-based distributed architectures. Riedel Communications GmbH & Co. KG anchors German supplier ecosystem density in broadcast and industrial verticals. These archetype representatives illustrate the capability segmentation between broad integration platforms and focused professional audio networking expertise.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Motorola Solutions Inc. |
| Clear-Com, LLC |
| Riedel Communications GmbH & Co. KG |
| Zenitel NV |
| Telephonics Corporation |
| Commend International GmbH |
| RTS Intercom Systems |
| Aiphone Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Vietnam's RF assembly sector is compressing contract manufacturing rates while simultaneously enabling aggressive pricing postures among equipment vendors serving ASEAN procurement channels. This utilization dynamic feeds back into supplier selection, with buyers shifting volume toward tariff-advantaged production bases even as component costs in Taiwan and South Korea remain elevated.
Pricing Analysis
FCC Part 15 certification dictates the pricing tier structure across North American commercial and residential verticals, separating premium-grade professional equipment with full compliance documentation from economy-tier consumer devices with limited RF testing. Three-tier pricing structure across premium, standard, and economy levels aligns with AES67/Dante certification depth and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because educational institutions with capital constraints increasingly self-install unlicensed Wi-Fi intercom systems. Healthcare facilities exhibit the lowest price sensitivity due to nurse call integration mandates and patient safety liability exposure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for RF front-end components, accelerating migration toward Vietnam and Thailand contract manufacturing alternatives. Power amplifier and low-noise amplifier module production concentrates in Taiwan, South Korea, and Vietnam, with gallium nitride substrate supply anchored in Japanese and Korean semiconductor foundries. Single-source vulnerability in Taiwanese RF component supply creates disruption risk for professional intercom manufacturers with sub-50 millisecond latency requirements. Distribution runs through systems integrators in North American education and healthcare verticals, though direct manufacturer relationships are gaining share in K-12 self-installation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless intercom equipment markets are reconfiguring around service-attach economics, with firmware maintenance subscriptions and cloud-managed platform fees expanding faster than hardware unit sales across professional broadcast and healthcare installations.
For Market Incumbents: Pre-empt margin erosion in the analog intercom segment by accelerating AES67/Dante certification pipelines for legacy matrix architecture customers before IP-native competitors capture hospital infrastructure refresh cycles. Channel control through exclusive integrator relationships in German broadcast verticals remains defensible against emerging Asian suppliers with cost advantages but limited Tokyo testing relationships.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for Wi-Fi-native video intercom systems with smartphone credentialing, bypassing entrenched matrix specialists in professional audio. SIP protocol convergence with unified communications platforms offers a direct go-to-market angle through telecom channel partnerships rather than traditional security integrator networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-managed residential video intercom segments as software development displaces RF hardware engineering in value creation. Acquisition targets should emphasize firmware architecture capabilities and recurring revenue attachment rates rather than manufacturing scale. The signal to watch is cybersecurity labeling requirement progression by FCC and EU regulators, which will filter subscale competitors unable to absorb compliance redesign costs.
| Strategic Initiative | Industry Significance |
|---|---|
| AES67/Dante Certification Acceleration | Professional broadcast facilities in Japan and Germany require sub-50 millisecond latency guarantees for live production coordination. |
| Vietnam Contract Manufacturing Expansion | Ho Chi Minh City and Hanoi RF assembly clusters offer tariff-advantaged production for ASEAN procurement channel growth. |
| Cloud Platform Integration | Multi-tenant housing developments in North American cities demand smartphone-native entry management with remote credentialing. |
| Cybersecurity Firmware Redesign | Emerging FCC and EU hardware certification requirements strain legacy product platforms without embedded security architectures. |
| SIP Protocol Convergence | Unified communications platform integration opens residential and small commercial segments previously isolated from enterprise telecom ecosystems. |
Research Methodology
Desk research of FCC Part 15 certification databases, professional audio networking standards documentation, and hospital procurement records preceded structured interviews with RF systems engineers, healthcare technology directors, broadcast facility managers, and security integrators. Primary fieldwork with equipment manufacturers and contract manufacturing executives in Vietnam and Taiwan validated component cost assumptions and capacity utilization signals. Secondary sources included customs trade data, CE marking registration filings, and TELEC certification timelines. Bottom-up unit economics triangulated against top-down vertical spending estimates across healthcare, education, and broadcast end-use segments.
Fixed assumptions across the modeling period held spectrum allocation decisions constant and treated semiconductor foundry utilization as a demand-responsive variable rather than exogenous constraint. Segmentation dimensions included product architecture (digital matrix, IP-native, analog legacy), technology protocol (wireless RF, Wi-Fi, Bluetooth, wired), application vertical, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to installed base replacement cycles and greenfield deployment pipelines, with healthcare infrastructure modernization and live event production recovery serving as primary demand inflection inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or ASEAN tariff policy would shift the trajectory of contract manufacturing migration and component pricing. Forecasts reflect documented assumptions regarding regulatory certification timelines and spectrum reallocation risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Fixed LTE Wireless Broadband Market