
 Public Safety Wireless Communication and Municipal Wireless Communication Market | 2026-2036
Public Safety Wireless Communication and Municipal Wireless Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Public Safety Wireless Communication and Municipal Wireless Communication Market Intelligence
The replacement of proprietary hardware with open, software-defined architectures is shifting the product economics for municipal communication networks. Motorola Solutions leverages its deep incumbency in Land Mobile Radio (LMR) systems while expanding its software and services portfolio. AT&T, through its FirstNet contract, dominates the dedicated public safety broadband network segment in the United States. Cisco Systems competes by providing the underlying IP networking infrastructure and cybersecurity solutions for these networks.
Public safety and municipal wireless communication systems deliver secure voice and data connectivity for first responders. These networks are engineered for high availability, utilizing technologies like LTE and P25 to ensure interoperability. The technology segment is transitioning towards LTE for broadband data, although P25 and TETRA retain a significant installed base for voice communications. Law enforcement constitutes the largest end-user segment, driving investment in advanced communication tools.
Spectrum allocation by bodies such as the FCC in the United States and the MIIT in China directly governs network deployment and capacity. Concurrently, standards from organizations like the 3GPP for LTE and ETSI for TETRA dictate equipment interoperability and performance benchmarks. Stakeholder focus now turns to integrating 5G capabilities for enhanced mobile broadband and managing the cybersecurity risks inherent in IP-based networks.
Market Dynamics
The fundamental dynamic shaping the market is the technological migration from narrowband, voice-centric Land Mobile Radio systems to mission-critical broadband networks. This transition, driven by the need for real-time data, video, and IoT applications in public safety, is compelling a complete overhaul of legacy infrastructure.
Growth Catalysts
- Next-Generation Network Upgrades:The transition from LMR technologies like P25 and TETRA to 4G LTE and 5G-ready networks is a primary catalyst, enabling high-bandwidth applications such as real-time video streaming and biometric data access for law enforcement and first responders.
- Government Interoperability Mandates:Policies like the establishment of the FirstNet authority in the United States and similar initiatives in Europe and Asia compel agencies to adopt standardized communication platforms, ensuring seamless cross-jurisdictional cooperation during large-scale emergencies.
- Smart City Initiatives:The expansion of smart city projects globally drives demand for integrated municipal wireless networks that connect everything from traffic control systems and public utilities to emergency services, creating a unified communication fabric.
Market Restraints
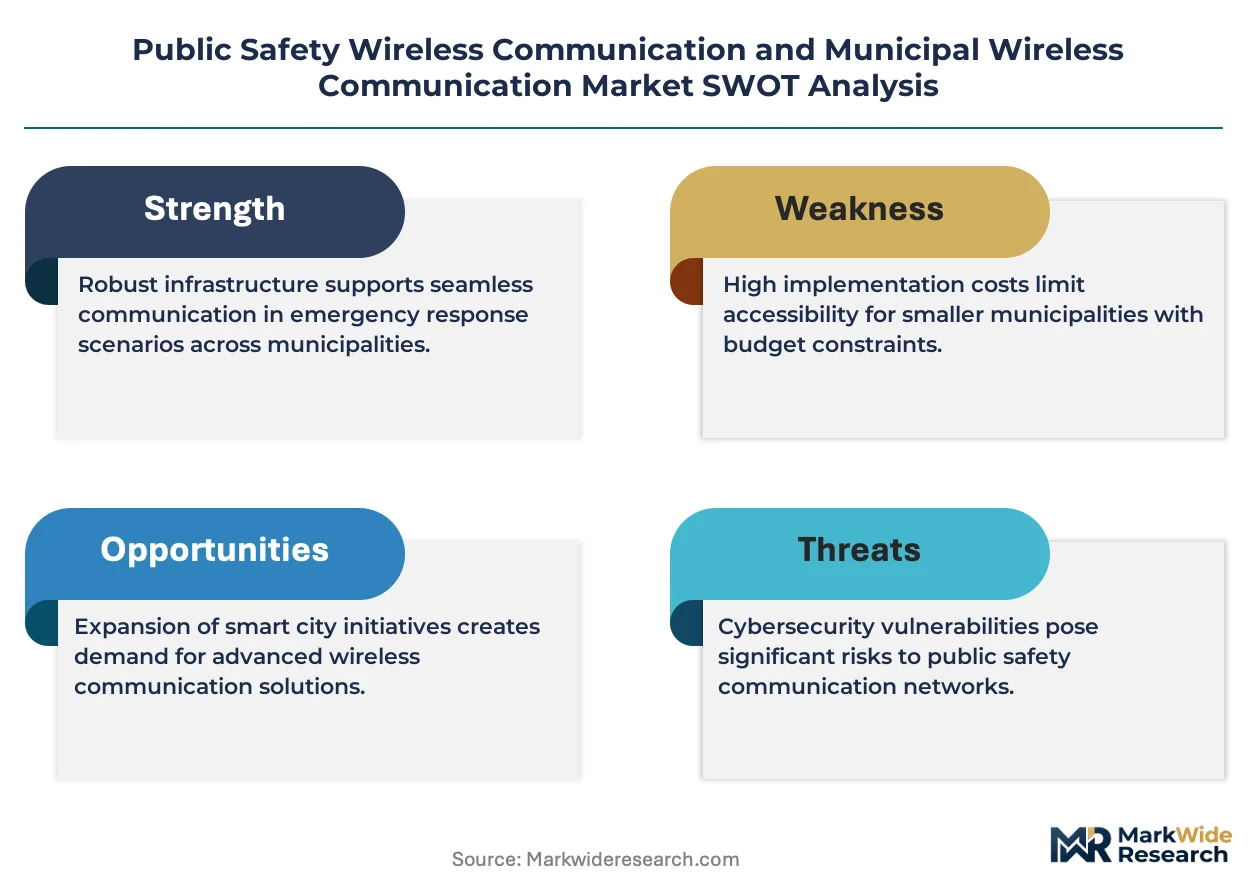
- High Capital Expenditure:The significant upfront investment required to deploy new nationwide or city-wide broadband networks, including cell sites, core network infrastructure, and ruggedized end-user devices, presents a major financial barrier for many municipalities.
- Spectrum Allocation Complexity:Limited availability of and competition for suitable radio frequency spectrum, governed by complex regulatory allocation processes from bodies like the FCC and MIIT, can delay or constrain network deployment and capacity.
- Legacy System Entrenchment:The vast installed base of reliable, long-lasting LMR systems creates inertia, as agencies face the financial and operational challenges of migrating from a proven technology to a new, IP-based architecture.
Strategic Opportunities
- Integration with IoT and AI:There is a significant opportunity to integrate public safety networks with city-wide IoT sensors, drone fleets, and AI-powered analytics platforms to provide predictive intelligence and enhanced situational awareness for first responders.
- Emerging Market Modernization:Nations across Latin America and Southeast Asia are in the early stages of modernizing their public safety communication infrastructure, representing a substantial greenfield opportunity for vendors of LTE and 5G-based systems.
- Mission-Critical Services on Commercial Networks:The development of Mission-Critical Push-to-Talk, Video, and Data (MCPTX) services that can operate securely over commercial mobile networks opens new service models and revenue streams for mobile network operators.
Industry Challenges
- Interoperability with Legacy Systems:A primary operational challenge is ensuring seamless communication between new LTE broadband networks and the extensive installed base of P25 and TETRA voice systems during the prolonged transition period.
- Cybersecurity for IP Networks:The shift to all-IP networks exposes public safety communications to a wider range of cybersecurity threats, demanding advanced encryption, intrusion detection, and continuous monitoring to protect mission-critical data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Safety Wireless Communication and Municipal Wireless Communication Market |
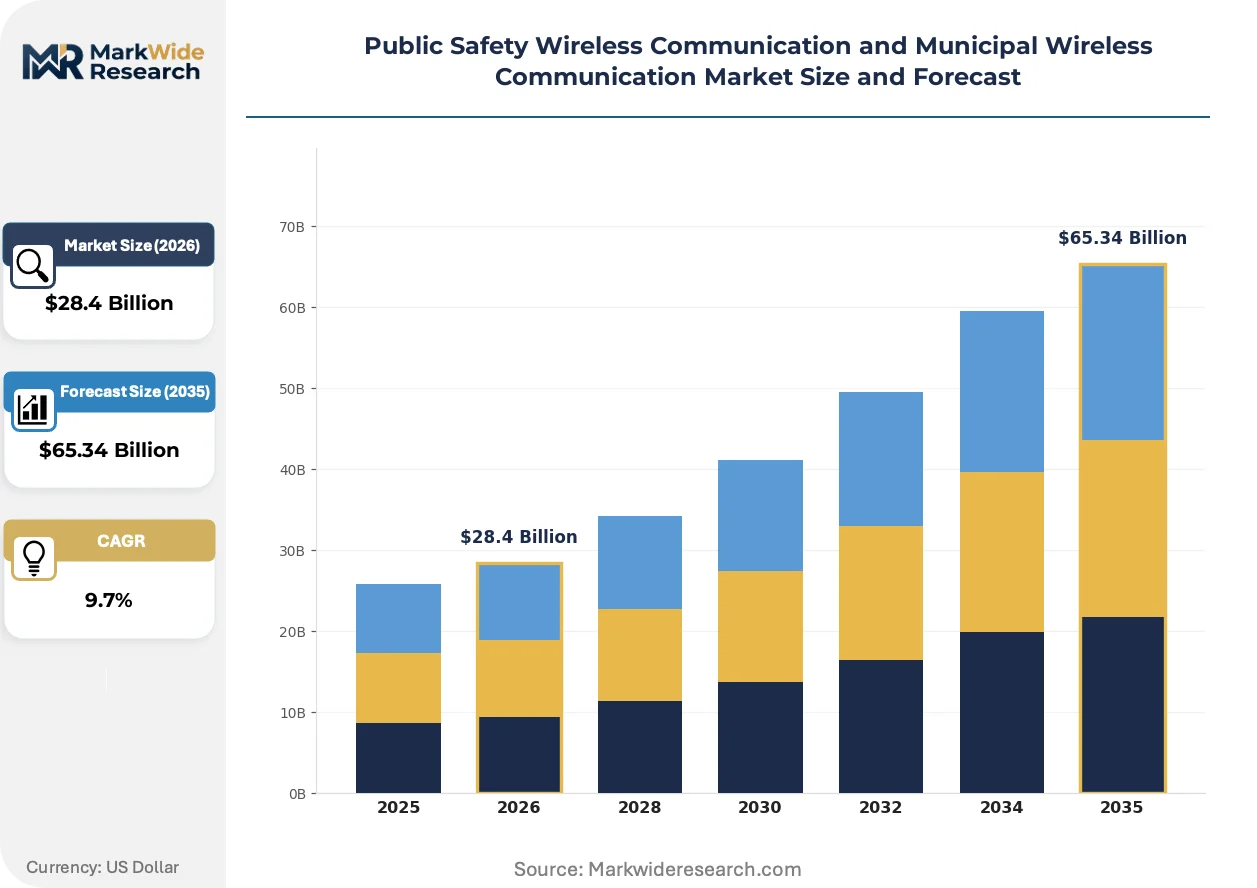
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $65.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, P25, DMR, TETRA End User: Law Enforcement, Fire Services, Emergency Medical Services, Public Works Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Application: Disaster Recovery, Routine Operations, Communication Network, Surveillance |
| Companies Covered | Motorola Solutions Inc., AT&T Inc., Cisco Systems Inc., Nokia Corporation, Ericsson AB, Verizon Communications Inc., Huawei, Aruba Networks, Hytera Communications Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Safety Wireless Communication and Municipal Wireless Communication Market Strategic Shifts & Innovations
The market is being redefined by the unbundling of hardware and software, moving away from proprietary, single-vendor ecosystems. This shift toward open, standards-based architectures is lowering barriers to entry and fostering innovation in applications and services for public safety and municipal agencies.
Software-defined networking (SDN) and network functions virtualization (NFV) are key technologies that separate network control logic from the physical hardware. Public safety network operators are adopting these architectures to increase agility, automate network management, and reduce dependency on specific hardware vendors. This transition from proprietary equipment to open software is electrifying the product economics of the entire ecosystem.
Regulatory frameworks are evolving to support next-generation public safety communications. Standards from the 3GPP for Mission-Critical Services over LTE, endorsed by bodies like ETSI in Europe, provide a global blueprint for interoperability. This standardization forces legacy LMR vendors to adapt their product strategies to compete in an open, LTE-centric environment. The TETRA-dominant European market is most affected, accelerating its transition to 3GPP-compliant solutions.
A notable behavioral shift involves the adoption of public-private partnership models for network deployment and operation. Instead of purchasing and managing their own infrastructure, government agencies are increasingly contracting with commercial carriers to provide dedicated public safety broadband services. This trend is most prominent in the United States through the FirstNet network, demonstrating a viable path for leveraging commercial scale and expertise.
Public Safety Wireless Communication and Municipal Wireless Communication Market Segmentation
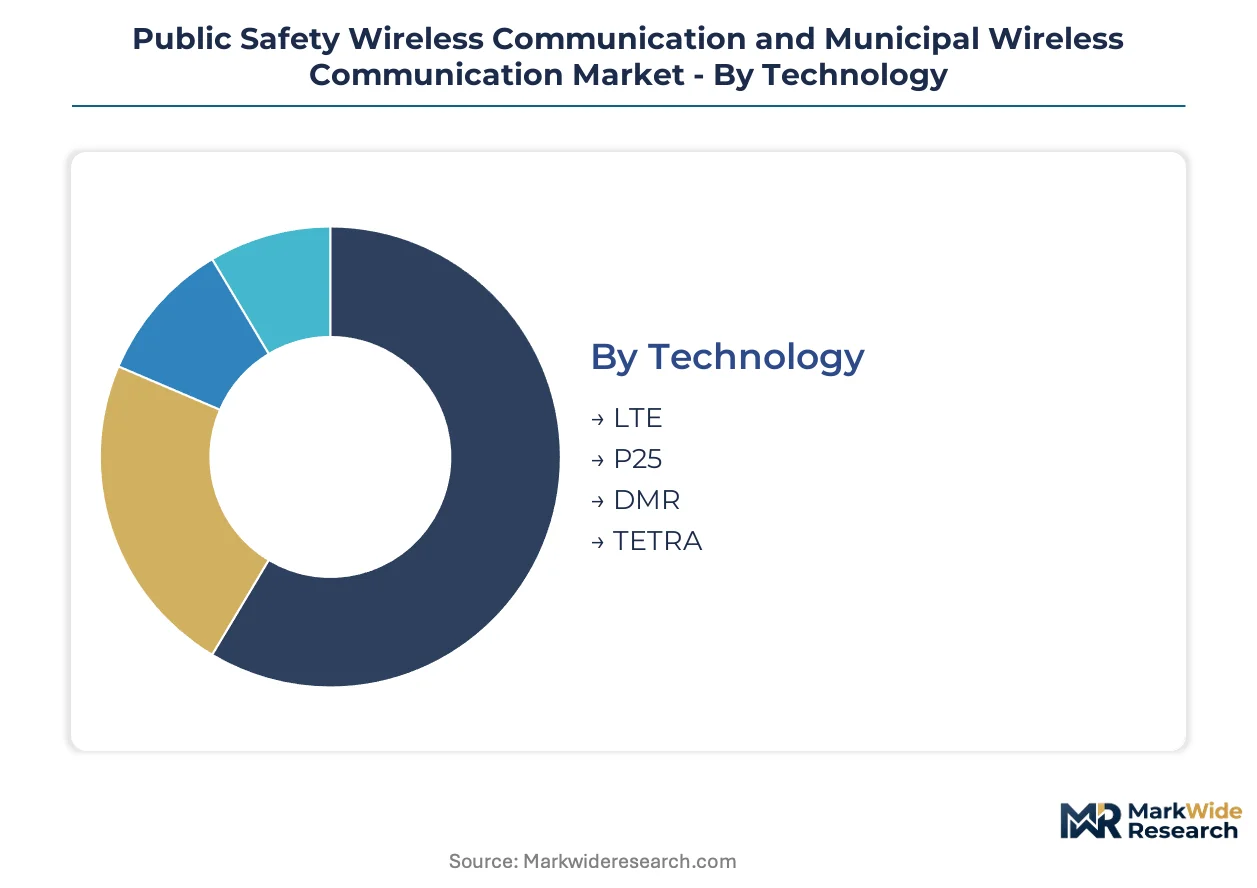
Market segmentation provides a granular view of the Public Safety Wireless Communication and Municipal Wireless Communication Market, highlighting the diverse technological preferences and operational needs of various end-users. Understanding these distinct segments is crucial for technology providers and service operators to tailor solutions effectively.
Technology:
The technological evolution of wireless communication systems defines distinct market segments.
- LTE:Long Term Evolution networks provide high-speed broadband data capabilities, enabling real-time video, mapping, and IoT applications for first responders. Demand is concentrating in the United States, driven by nationwide public safety network upgrades like FirstNet.
- P25:Project 25 systems offer secure, interoperable digital voice communications, primarily for land mobile radio users. Law enforcement agencies in North America heavily rely on P25 for mission-critical voice, driving continued investment in these established systems.
- DMR:Digital Mobile Radio provides cost-effective digital voice and data services, often favored by smaller municipal public works departments.
- TETRA:Terrestrial Trunked Radio systems deliver secure, reliable voice and data for public safety in Europe and Asia, maintaining a significant installed base.
P25 leads on installed base scale; LTE leads on technological momentum.
End User:
The market segments by customer type, reflecting the varied operational needs of public safety and municipal entities.
- Law Enforcement:Police departments and federal agencies constitute the largest end-user segment, requiring secure voice, real-time data, and video streaming for situational awareness. Investment is driven by the need for advanced communication tools to enhance operational efficiency and officer safety.
- Fire Services:Fire departments utilize wireless communication for incident command, coordination, and data exchange during emergencies and routine operations. These services demand highly reliable systems for critical voice and data transfer in challenging environments.
- Emergency Medical Services:EMS providers depend on robust networks for patient data transmission, dispatch coordination, and secure voice communication during medical emergencies.
- Public Works:Municipal public works departments use wireless systems for utility management, infrastructure monitoring, and field team coordination.
Law enforcement agencies represent the largest and most demanding user base for advanced communication tools.
Deployment:
Operational models for network infrastructure deployment differentiate communication solutions across the market.
- Cloud-Based:Cloud-based deployments offer scalability, reduced upfront capital expenditure, and simplified management for municipal communication networks. This model is gaining traction among smaller agencies seeking agile and cost-efficient solutions.
- On-Premise:On-premise deployments provide maximum control, security, and customization for large public safety organizations with specific infrastructure requirements. Agencies with strict data sovereignty mandates often prefer this traditional deployment approach.
- Hybrid:Hybrid models combine on-premise infrastructure with cloud services, offering a balance of control and flexibility for diverse operational needs.
- Mobile:Mobile deployment solutions include vehicle-mounted or portable communication units, providing connectivity in remote areas or temporary incident sites.
Cloud-based solutions are gaining traction due to their agility, while on-premise deployments retain importance for critical infrastructure.
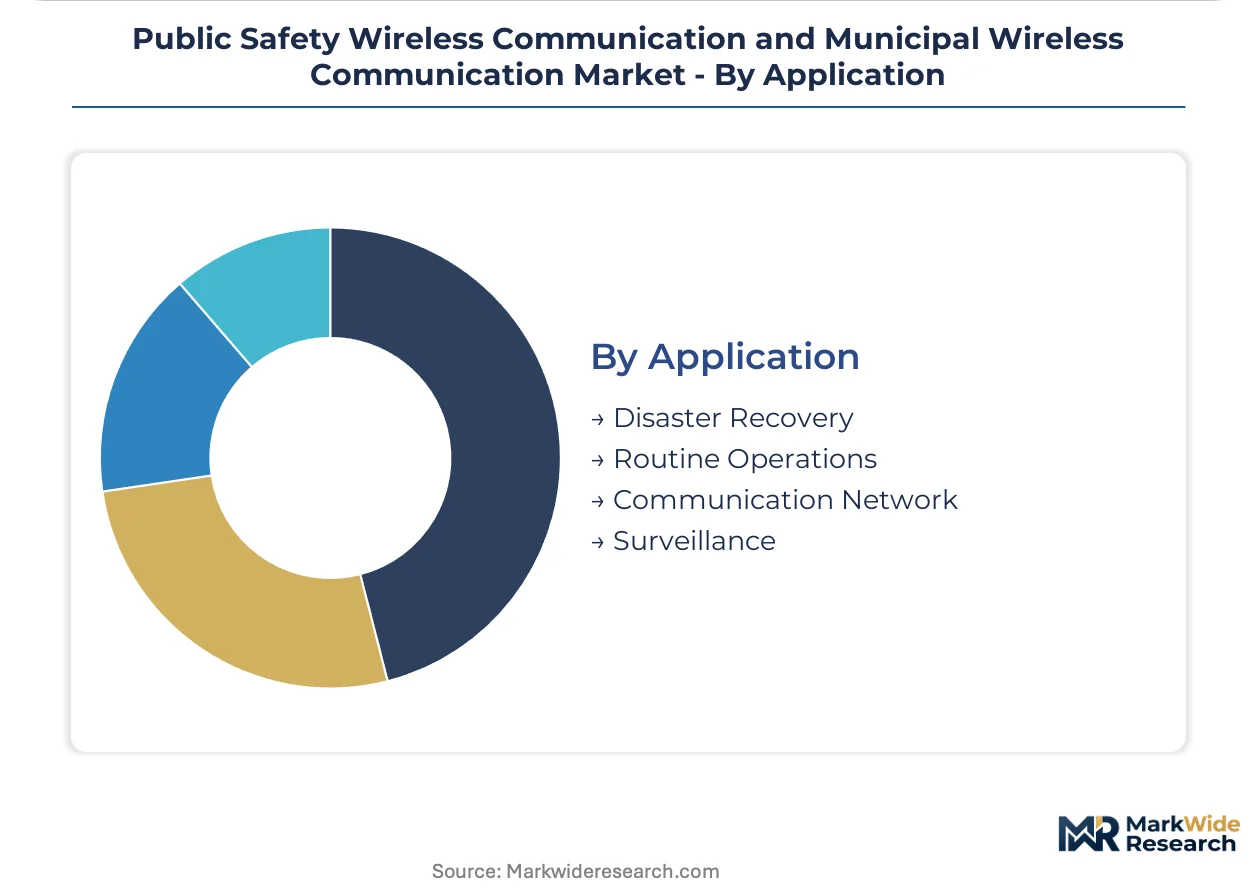
Application:
The functional utility of wireless communication systems for public safety and municipal agencies shapes application-based market segments.
- Routine Operations:This segment encompasses daily voice and data communications for public safety and municipal personnel, including dispatch, administrative tasks, and field coordination. The consistent demand for reliable connectivity underpins this foundational application.
- Disaster Recovery:Communication systems for disaster recovery ensure continuous operation during large-scale emergencies, natural disasters, or network outages. These applications prioritize resilience, redundancy, and interoperability for critical incident management.
- Communication Network:This application focuses on the underlying infrastructure for secure, interoperable voice and data exchange across various public safety entities.
- Surveillance:Surveillance applications leverage wireless networks for real-time video feeds, sensor data, and remote monitoring to enhance public safety and security.
Routine operations drive consistent demand, whereas disaster recovery applications demand the highest levels of network resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States market for public safety wireless communication leads global demand, propelled by significant government investment in next-generation networks. This region demonstrates the most advanced transition from legacy LMR systems to broadband LTE for first responders. Other nations are also modernizing their communication infrastructure, driven by similar needs for enhanced data capabilities and interoperability.
United States
Nationwide public safety network upgrades and the demand for real-time data applications drive significant investment in the United States. The Federal Communications Commission (FCC) allocates critical spectrum for public safety, enabling services like FirstNet. Major metropolitan areas such as New York City and Los Angeles are early adopters of advanced broadband communication tools, enhancing emergency response capabilities.
Germany
German public safety agencies prioritize secure voice and data communications, maintaining a strong installed base of TETRA systems. ETSI standards for TETRA and evolving 3GPP standards for mission-critical LTE guide network development. Cities like Berlin and Munich are actively exploring hybrid solutions to integrate broadband data with existing voice platforms.
China
China's smart city initiatives and expanding public safety requirements fuel demand for advanced municipal wireless networks. The Ministry of Industry and Information Technology (MIIT) directs spectrum allocation and promotes domestic technological development. Major urban centers such as Shanghai and Shenzhen are investing in integrated communication platforms for public services and emergency management.
United Kingdom
The United Kingdom is transitioning its public safety communication from legacy Airwave TETRA to a new Emergency Services Network (ESN) based on LTE technology. Ofcom manages spectrum licensing to ensure sufficient capacity for critical services. London and other major cities are integrating advanced data applications to improve situational awareness for emergency responders.
Brazil
Brazil represents a significant greenfield opportunity for modernizing public safety communication infrastructure across Latin America. ANATEL, the national telecommunications agency, regulates spectrum usage and network deployment. Urban areas like São Paulo and Rio de Janeiro are beginning to adopt LTE-based systems to enhance operational efficiency for law enforcement and emergency services.
Public Safety Wireless Communication and Municipal Wireless Communication Market Key Industry Players
Global majors compete with regional champions across technological innovation and market reach within the public safety and municipal wireless communication market. The landscape features a mix of established LMR system providers, dedicated broadband network operators, and core infrastructure suppliers. Companies are increasingly diversifying their portfolios into software and services, forming strategic partnerships to offer integrated solutions.
Specialists in dedicated public safety broadband networks, such as AT&T Inc., exemplify the shift towards commercial carrier partnerships for mission-critical services. Legacy Land Mobile Radio (LMR) vendors like Motorola Solutions Inc. maintain a strong presence, leveraging their deep incumbency while expanding into software and services. Meanwhile, Cisco Systems Inc. occupies a position as a critical underlying IP networking and cybersecurity infrastructure provider for these evolving communication ecosystems.
| Leading Market Players |
|---|
| Motorola Solutions Inc. |
| AT&T Inc. |
| Cisco Systems Inc. |
| Nokia Corporation |
| Ericsson AB |
| Verizon Communications Inc. |
| Huawei |
| Aruba Networks |
| Hytera Communications Corporation |
| Others |
Cost & Logistics Intelligence
Global semiconductor pricing trends directly influence component costs for network infrastructure, cascading into the final pricing tiers for public safety and municipal wireless communication systems. This market's supply chain is characterized by a reliance on global component manufacturing, creating specific pricing dynamics.
Pricing Analysis
Input cost pass-through from critical electronic components significantly impacts the final pricing of public safety communication equipment and services. The dominant pricing model is a hybrid of project-based infrastructure deployments and subscription-based software and service agreements. Price differentiation stems from the customization level required for agency-specific deployments and the comprehensiveness of after-sales service and support. Pricing pressure stems from technological convergence, as open, standards-based solutions challenge proprietary system costs. Federal law enforcement agencies demonstrate the least price sensitivity, prioritizing mission-critical reliability, while smaller municipal agencies are most price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements are increasingly mandated by public safety agencies to mitigate risks in the supply chain for critical communication systems. Geographic supply concentration for essential electronic components, such as semiconductor chips and specialized RF modules, primarily resides in countries like China, Taiwan, and South Korea. This market's raw material dependencies include rare earth elements for advanced electronics and ruggedized materials for end-user devices. Geopolitical tensions impacting critical component manufacturing represent a significant structural risk. Distribution runs through a combination of direct sales to large government entities and specialized system integrators serving municipal clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, driven by continuous public safety modernization efforts and the imperative for enhanced interoperability. Strategic positioning can leverage the ongoing technological transition from legacy systems to broadband networks.
For Market Incumbents: Deploy software-defined architecture integration to maintain market relevance against the emergence of open, standards-based solutions. Incumbents should focus on expanding software and services portfolios, leveraging deep customer relationships. Forming strategic partnerships for LTE and 5G integration helps bridge the technology gap. R&D investment in mission-critical broadband features reinforces competitive advantage.
For New Entrants and Emerging Players: Smaller municipal agencies represent an underserved buyer archetype, offering white-space opportunities for agile providers. Focusing on cost-effective cloud-based solutions can penetrate this segment, alongside integrated IoT platforms for smart city applications. Emerging markets in Latin America and Southeast Asia offer significant greenfield potential. Leveraging commercial mobile networks for Mission-Critical Push-to-Talk (MCPTX) services presents a viable go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software and cybersecurity providers, given the shift to IP-based networks. Long-term viability is underpinned by sustained government investment in critical infrastructure modernization over the next decade. Acquisition targets should include companies offering AI-powered analytics or secure 5G communication solutions. Acceleration of 5G deployment in public safety networks serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Portfolio Expansion | Enhances recurring revenue streams and diversifies offerings beyond hardware for established vendors. |
| 5G Capability Integration | Future-proofs networks for enhanced mobile broadband and real-time data applications for first responders. |
| Cybersecurity Solution Development | Addresses increasing threats to IP-based public safety networks, critical for data integrity. |
| Public-Private Partnership Models | Leverages commercial infrastructure for cost-effective deployment of nationwide public safety broadband. |
| Mission-Critical IoT Integration | Expands situational awareness through connected sensors and devices for emergency services. |
Research Approach
Coverage spans the United States, Germany, China, United Kingdom, and Brazil, with primary inputs from each region informing the analysis. This study combines insights from primary interviews with industry stakeholders and rigorous secondary validation. Public safety communication directors, municipal IT managers, network engineers, and regulatory officials contributed qualitative data. Secondary sources included FCC filings, ETSI standards documents, MIIT policy papers, and 3GPP specifications, ensuring comprehensive data triangulation through bottom-up and top-down approaches.
The analytical framework employs a rate-of-change decomposition to project market trajectories across the analysis window. Segmentation dimensions modeled include technology, end-user, deployment model, application, and regional regulatory frameworks. Compound annual growth rates were derived through historical trend extrapolation and future scenario modeling. Key industry-specific forecast inputs include government spending on infrastructure upgrades and evolving spectrum allocation policies.
Underlying measurement precision varies by segment; LTE and P25 technologies carry tighter precision than others due to established deployment metrics. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Deviation in government funding priorities or unforeseen technological disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Wimax Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wireless Communication Equipment Market