
 Wireless Connectivity Market | 2026-2036
Wireless Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Connectivity Market Intelligence
Platform licensing revenue is rewriting how telecom infrastructure providers monetize network intelligence. Verizon Communications Inc. leverages its millimeter-wave spectrum position to anchor enterprise private network deployments. Deutsche Telekom competes through vertical integration into Open RAN software layers. T-Mobile US Inc. dominates mid-band 5G coverage expansion across metropolitan markets.
Wireless connectivity encompasses radio-frequency communication systems operating across licensed and unlicensed spectrum bands from sub-1 GHz to 71 GHz, employing modulation schemes including OFDM and QAM to transmit data between devices without physical cabling. These systems enable real-time data exchange for IoT sensors, autonomous systems, and cloud-native applications requiring sub-10 millisecond latency. Wi-Fi and Bluetooth technologies lead consumer-facing deployments where interoperability standards govern device certification. Private network and hybrid network architectures capture expanding margin pools as manufacturing facilities and logistics hubs reject public network dependency. LoRaWAN specializes in low-power wide-area telemetry for agricultural and utility metering applications where battery life spans multiple years.
The FCC governs spectrum auctions and device certification in the United States, while ETSI harmonizes interoperability standards across European member states and the EU AI Act imposes risk-classification requirements on autonomous wireless systems. REACH and RoHS directives restrict hazardous substances in radio hardware sold within European markets, compelling component suppliers to reformulate solder alloys and antenna substrates. Stakeholders must monitor spectrum reallocation proceedings and Open RAN interoperability mandates to anticipate infrastructure procurement cycles.
Market Dynamics
Private 5G network deployments are fragmenting demand away from public carrier infrastructure as manufacturing and logistics operators pursue deterministic latency guarantees and localized data sovereignty controls.
Growth Catalysts
- Industrial IoT proliferation:Factory automation systems in Germany and Japan are mandating sub-10 millisecond latency for robotic coordination, pulling fiber-backhauled cellular infrastructure into brownfield facilities.
- REACH and RoHS compliance:European hazardous substance directives are accelerating substrate material innovation, compelling antenna manufacturers to reformulate solder alloys and PCB laminates ahead of certification deadlines.
- Mid-band spectrum liberalization:The FCC's auction of 3.45 GHz and 2.5 GHz licenses in the United States is unlocking capacity for fixed wireless access competition against incumbent cable operators.
Market Restraints
- Gallium nitride substrate costs:RF power amplifier foundry capacity concentrates in Taiwan and Japan, exposing module vendors to input price volatility and 26-week lead times for high-electron-mobility transistors.
- Open RAN interoperability friction:ETSI harmonization timelines lag vendor-specific implementations by 18-24 months, forcing operators into single-source radio unit commitments despite architectural preferences for disaggregation.
- Millimeter-wave propagation limits:Rain attenuation and non-line-of-sight blockage constrain 28 GHz and 39 GHz deployments to dense urban corridors, excluding suburban and rural enterprise applications.
Strategic Opportunities
- Indian manufacturing corridors:The country's PLI scheme for telecom equipment is attracting radio unit assembly investments, creating captive supply options for European and North American system integrators.
- Cellular V2X convergence:Automotive OEMs in Germany and South Korea are integrating C-V2X modules with sensor fusion stacks, opening software-defined radio licensing revenue streams.
- EU AI Act risk classification:Autonomous wireless systems for healthcare and transport face mandatory conformity assessments, generating compliance service demand for testing laboratories and certification bodies.
Industry Challenges
- Embedded RF engineering talent scarcity:Compound semiconductor design expertise concentrates among veteran engineers at Texas and Bavaria-based firms, constraining startup scaling and product iteration velocity.
- Multi-band certification complexity:Devices spanning sub-6 GHz and millimeter-wave frequencies must satisfy FCC, CE marking, and MIC Japan testing regimes simultaneously, extending time-to-market by 8-14 months.
- Legacy SCADA integration:Industrial facilities running Modbus and Profinet protocols require protocol translation gateways, adding integration cost and cybersecurity audit burden to private network deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Connectivity Market |
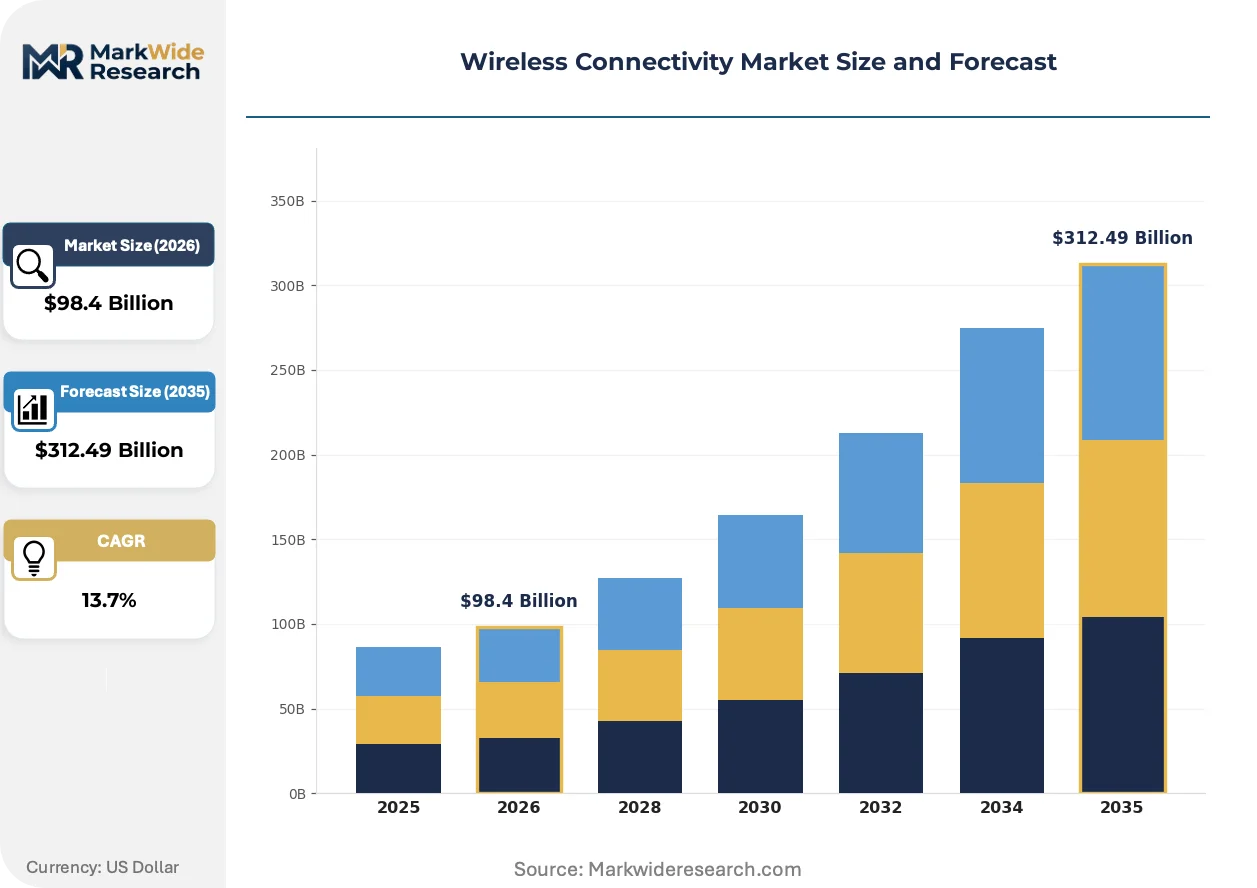
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $312.49 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, Zigbee, LoRaWAN Deployment: Public Network, Private Network, Hybrid Network, Mesh Network Application: Smart Home, Industrial Automation, Wearable Devices, Healthcare Monitoring End User: Telecommunications, Consumer Electronics, Automotive, Healthcare |
| Companies Covered | Deutsche Telekom, Telus Corporation, Verizon Communications Inc., American Tower Corporation, BCE Inc., T-Mobile US Inc., Rogers Communications Inc., U.S. Cellular Corporation, AT&T Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Connectivity Market Strategic Shifts & Innovations
Open RAN software disaggregation is redistributing value capture from integrated hardware vendors to specialized radio unit and distributed unit suppliers, compressing incumbent margin structures.
AI-native beamforming algorithms are rendering obsolete fixed-pattern antenna arrays in dense urban small cell deployments. Korean and U.S. carriers are deploying these systems across stadium and transit hub networks. The technology is rendering obsolete the traditional three-year radio refresh cycles by enabling software-defined coverage optimization.
The EU AI Act's risk-classification framework for autonomous wireless systems is imposing conformity assessment mandates on industrial robotics and healthcare telemetry devices. Manufacturers must document algorithmic transparency and fail-safe protocols before CE marking approval. Medical device OEMs in Germany and the Netherlands are restructuring quality management systems to accommodate notified body scrutiny.
Enterprise procurement teams are consolidating radio access network vendor relationships from four to two suppliers per operating region, demanding unified service level agreements spanning macro, small cell, and private network infrastructure. System integrators are capturing this consolidation by offering managed network-as-a-service contracts. This concentration is most visible in U.S. healthcare and German automotive verticals where IT-security governance mandates single-throat accountability.
Wireless Connectivity Market Segmentation
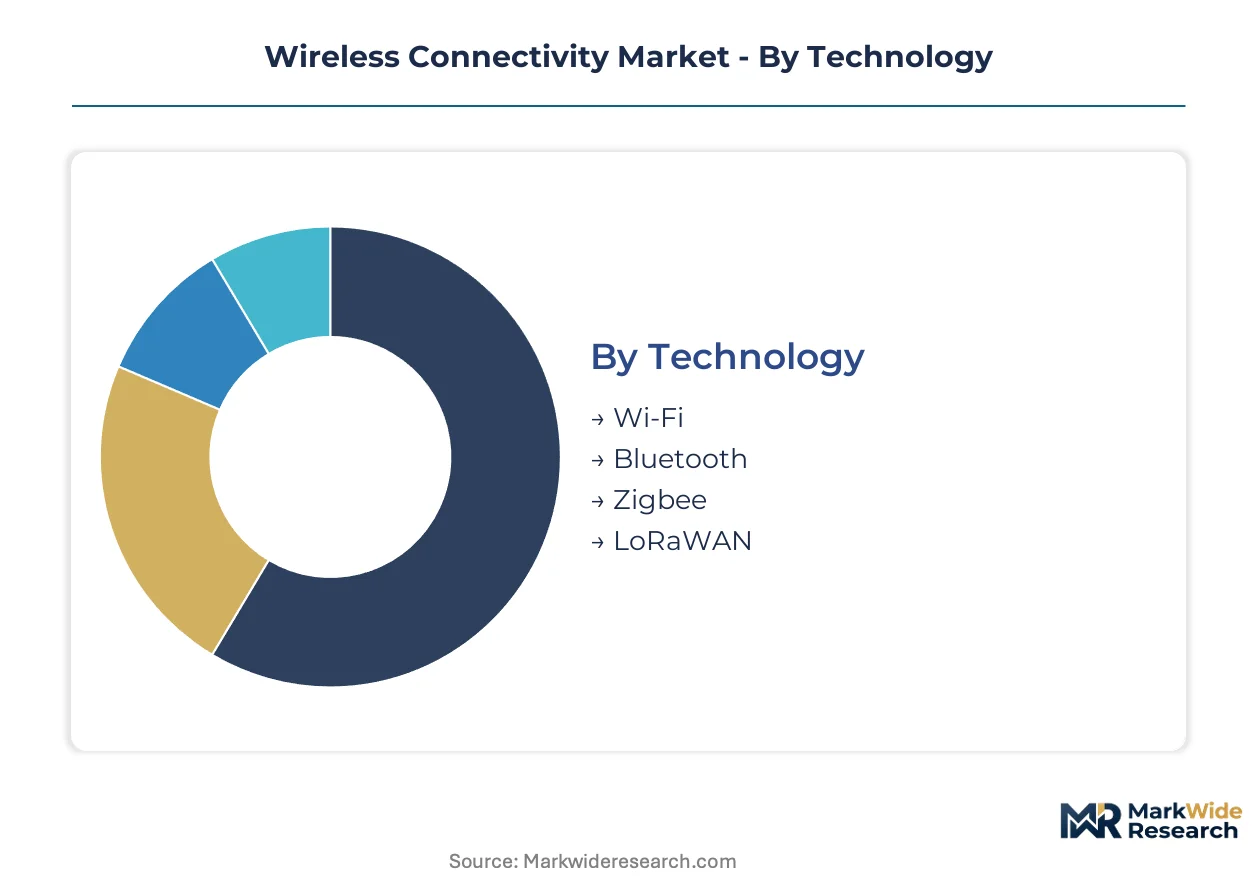
Wireless connectivity markets fragment along technology maturity curves and deployment economics. Each segment carries distinct service lifecycle requirements and margin profiles that reshape vendor positioning.
Technology:
After-sales-service intensity varies sharply across protocol generations, with legacy standards demanding sustained interoperability support while emerging technologies require intensive field optimization.
- Wi-Fi:OFDM-based local area networking operating across 2.4 GHz, 5 GHz, and 6 GHz bands with IEEE 802.11ax/be certification requirements. Enterprise demand concentrates in U.S. healthcare campuses and German manufacturing facilities where IT-security governance mandates WPA3-Enterprise encryption and centralized policy management. Service intensity peaks during roaming optimization and spectrum coexistence troubleshooting.
- Bluetooth:Short-range protocol stack employing frequency-hopping spread spectrum for audio streaming and device pairing. Wearable OEMs in South Korea and consumer electronics assemblers in China drive module procurement, with qualification testing against Bluetooth SIG interoperability profiles extending certification timelines. Post-deployment support focuses on firmware update orchestration across fragmented device ecosystems.
- Zigbee:Mesh-capable IEEE 802.15.4 standard for low-power home automation and building control systems.
- LoRaWAN:Sub-GHz wide-area protocol optimized for agricultural telemetry and utility metering with multi-year battery life.
Wi-Fi holds the largest share; momentum sits with LoRaWAN as utility operators accelerate smart grid deployments.
Deployment:
Cost tier differentiation separates capital-intensive private infrastructure from subscription-based public alternatives, with hybrid architectures capturing mid-market facilities seeking gradual migration paths.
- Public Network:Carrier-operated macro and small cell infrastructure delivering wide-area coverage through licensed spectrum leases. German automotive OEMs and U.S. logistics operators rely on public 5G for mobile workforce connectivity, though data sovereignty concerns push manufacturing toward alternatives. Service models emphasize SLA-backed latency guarantees and priority access tiers.
- Private Network:Dedicated radio access infrastructure deployed within facility boundaries with localized core functions. Japanese semiconductor fabs and Bavarian automotive plants mandate sub-10 millisecond latency for robotic coordination, justifying fiber-backhauled cellular deployment despite higher capital intensity. Post-installation support demands RF optimization and security patch management.
- Hybrid Network:Architectures combining private on-premise coverage with public network fallback for wide-area mobility.
- Mesh Network:Self-healing multi-hop topologies eliminating single points of failure in challenging RF environments.
Public Network dominates volume; Hybrid Network is climbing the fastest as facilities balance control with capital efficiency.
Application:
Customer type stratification separates consumer self-installation from industrial systems integration, with healthcare presenting the most stringent compliance overlay.
- Smart Home:Residential automation encompassing lighting, climate, and security device ecosystems. U.S. and European consumers drive hub and speaker integration, though interoperability fragmentation across Amazon, Google, and Apple ecosystems complicates technical support. Installation assistance and troubleshooting represent primary service touchpoints.
- Industrial Automation:Factory-floor connectivity for programmable logic controllers, robotic arms, and automated guided vehicles. German automotive stamping plants and Japanese electronics assembly lines require deterministic latency for safety-critical motion control, pulling specialized integrators into long-term maintenance contracts. Service intensity spans protocol translation gateway management and predictive RF maintenance.
- Wearable Devices:Body-worn sensors and augmented reality headsets for fitness and enterprise productivity.
- Healthcare Monitoring:Continuous patient telemetry and remote diagnostic systems subject to FDA and EMA device regulations.
Industrial Automation holds the largest share; momentum sits with Healthcare Monitoring as reimbursement codes expand for remote patient monitoring.
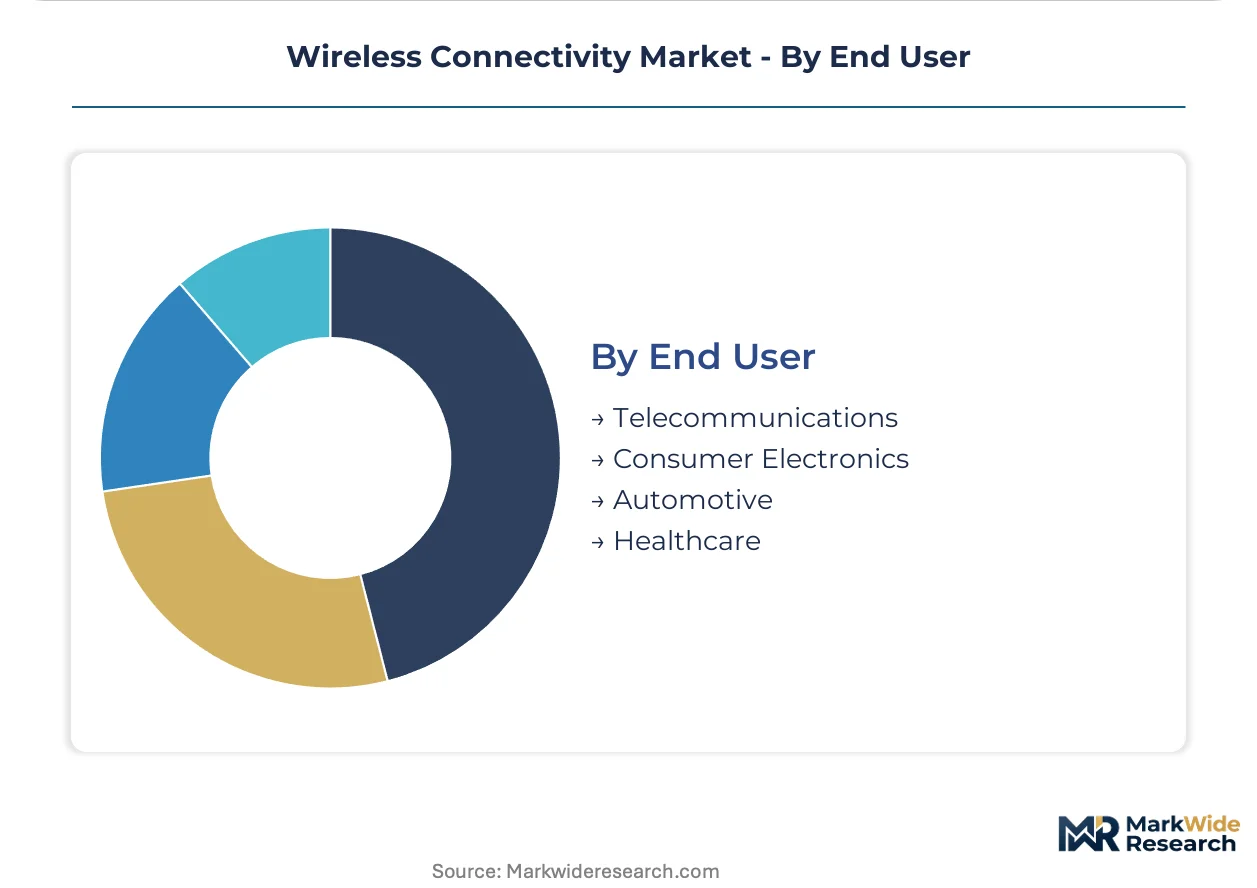
End User:
Volume concentration varies across verticals, with automotive and telecommunications presenting divergent procurement cycles and technical specification requirements.
- Telecommunications:Carrier infrastructure procurement spanning macro base stations, small cells, and core network functions. Verizon, Deutsche Telekom, and T-Mobile US drive equipment refresh cycles, with Open RAN disaggregation redistributing value from integrated vendors to specialized radio unit suppliers. Service contracts emphasize network performance guarantees and multi-vendor interoperability support.
- Consumer Electronics:Smartphone, tablet, and peripheral OEM integration of connectivity modules. South Korean and Chinese device assemblers dominate procurement volume, with certification against FCC, CE marking, and MIC Japan regimes extending time-to-market. Post-sales support concentrates on firmware distribution and interoperability patch management.
- Automotive:Cellular V2X module integration for vehicle-to-everything communication and over-the-air update capability.
- Healthcare:Medical device connectivity subject to FDA 510(k) and EMA MDR conformity assessments.
Telecommunications holds the largest share; Automotive is gaining share fastest as C-V2X mandates proliferate across German and South Korean vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF power amplifier foundry capacity concentrates in Taiwan and Japan, exposing module vendors to input price volatility. This geographic concentration shapes procurement patterns across downstream assembly hubs in Germany, the United States, South Korea, and India.
United States
Verizon Communications Inc. leverages millimeter-wave spectrum positions to anchor enterprise private network deployments. The FCC's auction of 3.45 GHz and 2.5 GHz licenses unlocks capacity for fixed wireless access competition against incumbent cable operators. T-Mobile US Inc. dominates mid-band 5G coverage expansion across metropolitan markets including New York and Los Angeles.
Germany
Automotive OEMs integrate cellular V2X modules into next-generation vehicle platforms, pulling specialized component demand. ETSI harmonizes interoperability standards across European member states while REACH and RoHS directives restrict hazardous substances in radio hardware. Bavarian automotive plants mandate sub-10 millisecond latency for robotic coordination, justifying fiber-backhauled cellular deployment.
South Korea
AI-native beamforming algorithms deploy across stadium and transit hub networks in Seoul and Busan. The country's national telecom regulator governs spectrum allocation for 28 GHz and 39 GHz small cell densification. Korean carriers partner with device OEMs to render obsolete traditional three-year radio refresh cycles through software-defined coverage optimization.
Japan
Semiconductor fabs and electronics assembly lines require deterministic latency for safety-critical motion control. METI governs industrial spectrum allocation and Open RAN interoperability mandates that anticipate infrastructure procurement cycles. The Kyushu and Chubu regions concentrate high-electron-mobility transistor foundry capacity with 26-week lead times for gallium nitride substrates.
India
The PLI scheme for telecom equipment attracts radio unit assembly investments, creating captive supply options for European and North American system integrators. TRAI governs spectrum pricing and network security mandates for foreign vendor participation. Manufacturing corridors in Maharashtra and Tamil Nadu emerge as assembly hubs for export-oriented radio access network components.
Wireless Connectivity Market Key Industry Players
Integrated telecom carriers and specialized infrastructure providers split the market along spectrum ownership versus equipment supply lines. The structure tilts toward consolidation at the carrier tier while fragmenting across radio unit and distributed unit suppliers. Three archetypes dominate: spectrum-anchored national carriers, tower-focused neutral hosts, and Open RAN software specialists. Competitive moves center on vertical integration into software layers and geographic expansion through managed network-as-a-service contracts.
Among North American carriers, Verizon Communications Inc., T-Mobile US Inc., and AT&T Inc. occupy positions defined by spectrum portfolio differentiation and enterprise private network penetration. These entities exemplify the spectrum-anchored archetype through licensed mid-band and millimeter-wave positions. Deutsche Telekom represents the integrated European model with backward integration into Open RAN software layers. Specialist infrastructure positions include American Tower Corporation as a neutral-host tower operator and U.S. Cellular Corporation as a regional coverage-focused carrier.
| Leading Market Players |
|---|
| Deutsche Telekom |
| Telus Corporation |
| Verizon Communications Inc. |
| American Tower Corporation |
| BCE Inc. |
| T-Mobile US Inc. |
| Rogers Communications Inc. |
| U.S. Cellular Corporation |
| AT&T Inc. |
| Others |
Cost & Logistics Intelligence
Kyushu and Chubu's gallium nitride foundry clusters in Japan anchor global RF power amplifier supply, translating 26-week substrate lead times into pricing leverage that propagates through module vendors and system integrators. This geographic concentration compresses margin pools at each downstream tier while amplifying volatility exposure for buyers lacking captive supply arrangements.
Pricing Analysis
FCC device certification tiers dictate the pricing tier structure for radio hardware entering U.S. markets, separating premium-grade millimeter-wave modules from standard sub-6 GHz and economy unlicensed-band alternatives. Price differentiation hinges on certification grade and volume scale, with automotive OEMs absorbing premium positioning for C-V2X modules while agricultural telemetry buyers prioritize economy LoRaWAN configurations. Cost compression in standard-tier radio units is intensifying because Open RAN disaggregation fragments vendor margins. Healthcare systems exhibit least price sensitivity due to FDA 510(k) compliance burdens, whereas consumer electronics assemblers drive hardest bargain through multi-source procurement.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk planning for RF component procurement. Taiwan, Japan, and South Korea concentrate high-electron-mobility transistor foundry capacity, drawing from gallium nitride substrates, ceramic packaging materials, and precision antenna laminates. Single-source vulnerability concentrates in Taiwanese wafer fabrication for compound semiconductors. Distribution runs through tier-one module integrators in Germany and South Korea before reaching system-level deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound semiconductor design expertise concentrates among veteran engineering cohorts at Texas and Bavaria-based firms, constraining product iteration velocity and inflating compensation costs for specialized RF talent acquisition.
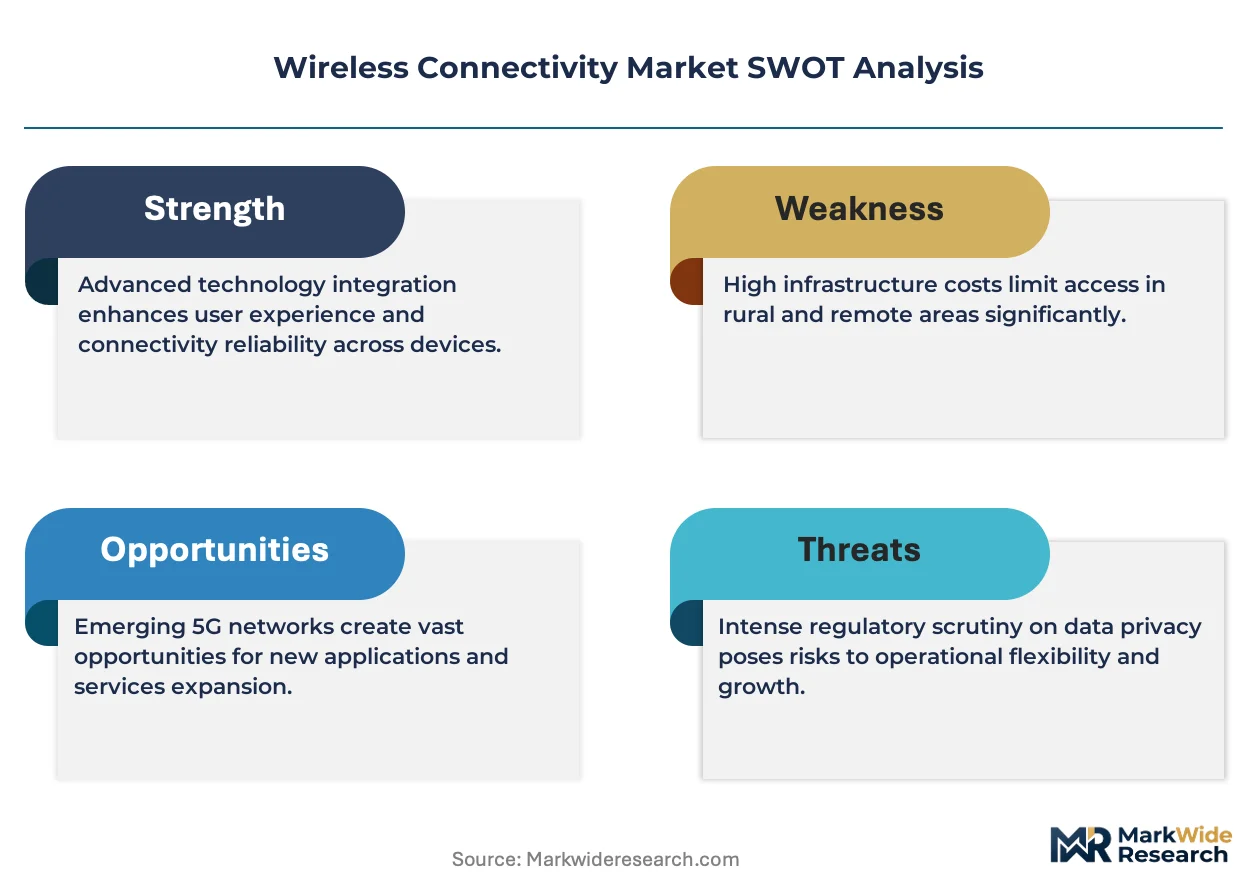
For Market Incumbents: Entrench spectrum portfolio positions through accelerated mid-band 5G coverage densification in metropolitan corridors where T-Mobile US has established density advantages. Prioritize backward integration into Open RAN software layers to defend against disaggregation-driven margin compression from specialized radio unit suppliers. Secure captive gallium nitride substrate supply through long-term offtake commitments with Japanese foundries to neutralize 26-week lead time volatility. For New Entrants and Emerging Players: Private network deployments for mid-market manufacturing facilities in India's Maharashtra and Tamil Nadu corridors represent the most penetrable entry point, bypassing incumbent carrier relationships in saturated North American and European markets. Target protocol translation gateway development for legacy SCADA integration as a service wedge, capturing retrofit demand from brownfield industrial automation sites. Pursue managed network-as-a-service contracting models to overcome capital intensity barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Open RAN software specialists with demonstrated interoperability certification against ETSI harmonization timelines. Long-term viability across the next decade rests on architectural control points shifting from integrated hardware to disaggregated radio unit and distributed unit layers. Acquisition target archetype: radio unit suppliers with Indian PLI scheme qualification and European automotive OEM validation. Signal to watch: FCC spectrum reallocation proceedings that would unlock fixed wireless access capacity and reshape infrastructure procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Network Deployment | Manufacturing facilities in Germany and Japan mandate deterministic latency guarantees through fiber-backhauled cellular infrastructure. |
| Open RAN Software Integration | Deutsche Telekom's backward integration into distributed unit layers redistributes value capture from integrated hardware vendors. |
| Cellular V2X Module Certification | Automotive OEMs in South Korea and Germany require C-V2X integration with sensor fusion stacks for next-generation platforms. |
| Gallium Nitride Substrate Securement | Japanese foundry capacity concentration exposes module vendors to input price volatility without captive supply arrangements. |
| AI-Native Beamforming Deployment | Korean carriers deploy software-defined coverage optimization across Seoul stadium networks to compress traditional radio refresh cycles. |
Research Approach
A spread of perspectives from RF engineering directors at semiconductor fabs, procurement leads at German automotive OEMs, regulatory affairs specialists at telecom carriers, and network architects at system integrators converged on the working assumptions. Primary field engagement combined with secondary validation against FCC spectrum auction records, ETSI harmonization documentation, METI industrial spectrum allocation filings, and TRAI security mandate circulars. Bottom-up equipment shipment analysis and top-down infrastructure capex triangulation anchored volume estimates.
Demand-supply balance modeling across technology generations, deployment architectures, application verticals, and end-user segments structured the projection framework. Segmentation dimensions included protocol maturity curves, facility ownership models, latency requirement tiers, and regional regulatory clusters. CAGRs emerged from equipment replacement cycle analysis and infrastructure procurement pipeline assessment. Forecast inputs incorporated private network penetration assumptions and Open RAN interoperability timeline progressions.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, spectrum auction pricing trajectories, or industrial automation investment rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization schedules and substrate foundry capacity expansion plans. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Wireless Mesh Networking Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Wigig Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Industrial Wireless Transmitter Market