
 Mesh Wifi System Market | 2026-2036
Mesh Wifi System Market Size, Share, and Industry Trends Forecast 2026-2036
Mesh Wifi System Market Insights
Wi-Fi Alliance certification for Wi-Fi 6 and Wi-Fi 6E is bifurcating vendor eligibility between premium-tier suppliers and cost-focused challengers. Netgear leverages its Orbi ecosystem to sustain brand loyalty among high-end residential buyers. Cisco Systems anchors enterprise mesh deployments through Meraki cloud management. TP-Link competes aggressively on price while extending distribution through retail and e-commerce channels.
A mesh wifi system deploys multiple interconnected nodes that share a single network identifier and automatically route traffic across radio backhaul links, typically operating across 2.4 GHz, 5 GHz, and 6 GHz bands with throughput exceeding 5 Gbps in tri-band configurations. The architecture eliminates dead zones in structures where single-router coverage fails, serving both consumer homes and commercial facilities requiring seamless roaming. Tri-band product types command margin premiums due to dedicated backhaul channels that reduce client-facing congestion. Residential end users dominate unit volumes, though hospitality and educational deployments generate higher per-site revenue through professional installation and cloud-based management subscriptions. Ethernet connectivity options retain share in commercial settings where wired backhaul reliability outweighs wireless convenience.
The FCC governs unlicensed spectrum access and power limits in the United States, while the EU Radio Equipment Directive mandates CE marking and harmonized frequency use across member states. China's MIIT issues network access licenses that foreign mesh vendors must obtain before commercial sale. ETSI standards in Europe and IEEE 802.11be development for Wi-Fi 7 are raising performance baselines that stakeholders must track to avoid product obsolescence.
Market Dynamics
The FCC's Wi-Fi 6E spectrum allocation is compressing upgrade cycles across enterprise and residential segments, forcing incumbent router vendors to accelerate tri-band hardware roadmaps while cloud-managed platforms absorb management complexity.
Growth Catalysts
- Dense urban construction:Multi-dwelling residential complexes in Germany and China require seamless coverage across concrete structures that defeat single-router deployments.
- MIIT network access licenses:China's streamlined foreign vendor certification is expanding channel availability for international mesh suppliers seeking commercial scale.
- Smart building integration:Building automation systems in hospitality and education verticals demand unified network backbones that mesh architectures provision without cabling retrofits.
Market Restraints
- Semiconductor supply concentration:RF front-end components for 6 GHz operation source primarily from Taiwan and South Korea foundries, creating geographic vulnerability.
- Copper and rare earth input costs:Antenna arrays and power amplifiers depend on neodymium and copper pricing that fluctuates with commodity markets.
- Legacy 802.11n infrastructure:Installed base of single-band equipment in price-sensitive residential segments slows replacement velocity.
Strategic Opportunities
- India smart city mandates:Municipal Wi-Fi projects under the Smart Cities Mission create bulk procurement channels for cloud-managed mesh systems.
- Wi-Fi 7 pre-standard deployment:IEEE 802.11be draft equipment offers early-mover positioning for high-throughput enterprise campus upgrades.
- Direct-to-installer distribution:Bypassing retail markup through certified installer networks captures margin in commercial verticals requiring professional deployment.
Industry Challenges
- RF engineering talent scarcity:Tri-band optimization and interference mitigation require specialized skills concentrated among legacy telecom suppliers.
- Wi-Fi Alliance certification timelines:Multi-band interoperability testing extends product launch windows by four to six months versus proprietary solutions.
- Cloud platform integration complexity:Enterprise buyers demand API compatibility with existing network management stacks, fragmenting vendor development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesh Wifi System Market |
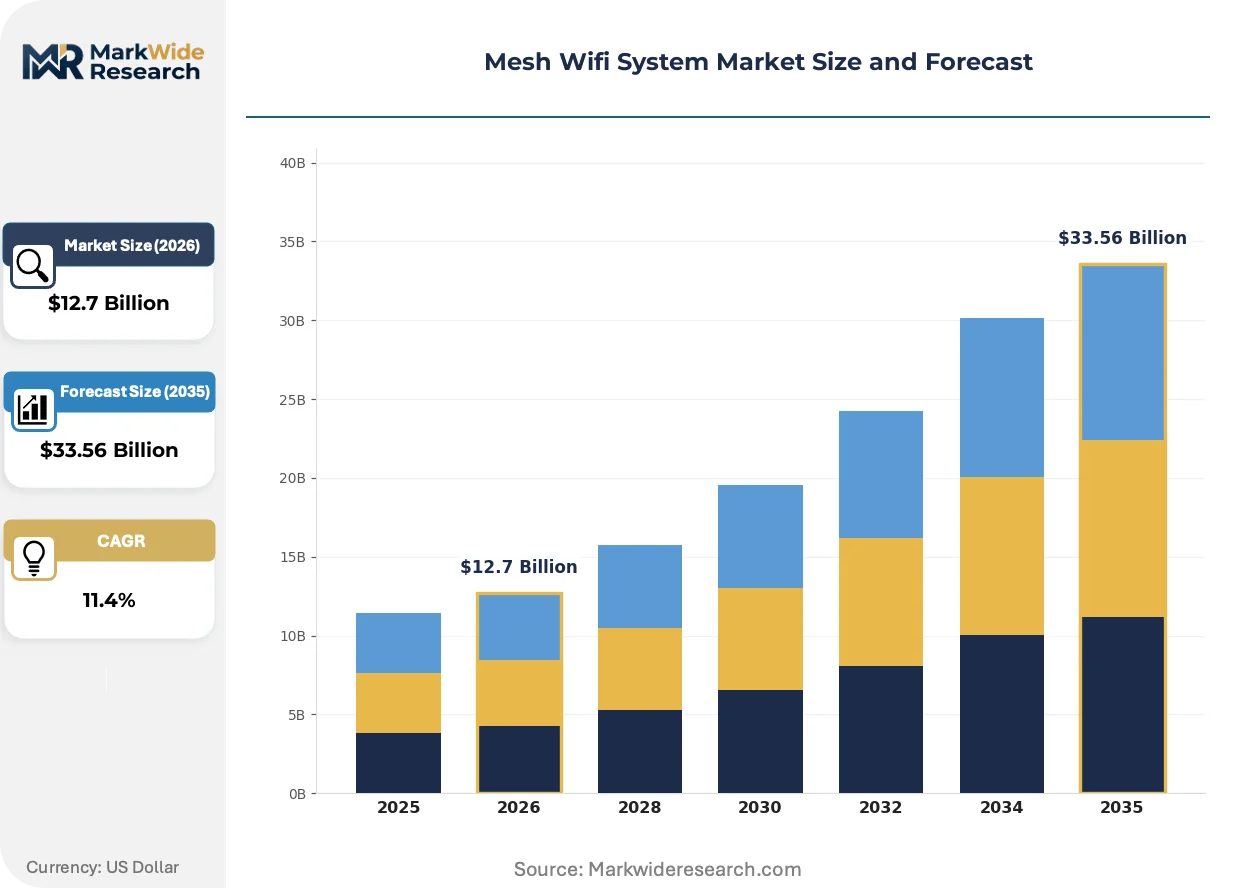
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Dual-Band, Tri-Band Connectivity: Wireless, Ethernet, Powerline, Hybrid End User: Residential, Commercial, Educational, Hospitality Installation: Self-Install, Professional Install, Cloud-Based, Plug-and-Play |
| Companies Covered | Netgear, Cisco Systems, Hewlett Packard Enterprise, Qualcomm Technologies, Ruckus Networks, TP-Link, ASUS, Google, Amazon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesh Wifi System Market Trends and Innovations
Radio frequency engineering and spectrum policy are converging to reshape hardware form factors and procurement patterns simultaneously, compressing the traditional three-year enterprise refresh cycle.
Multi-radio node designs is miniaturizing physical enclosures while maintaining tri-band throughput above 5 Gbps. Enterprise facilities managers are specifying ceiling-mounted and in-wall units that disappear into architectural finishes. This form factor compression is enabling mesh deployment in heritage buildings where surface-mounted equipment violates preservation codes.
ETSI harmonized spectrum rules across EU member states are standardizing 6 GHz power limits and channel widths, reducing SKU fragmentation for vendors serving multiple European markets. Industrial consequence includes accelerated CE marking convergence that collapses country-specific testing regimes. German commercial real estate developers are responding fastest, embedding mesh infrastructure into new construction specifications ahead of occupancy.
Subscription-based network management is displacing perpetual-license procurement in mid-market enterprise segments. Value-added resellers are bundling hardware with multi-year cloud monitoring contracts that capture recurring revenue. This shift is most visible in United States hospitality chains standardizing on unified platforms across franchise properties.
Mesh Wifi System Market Segmentation
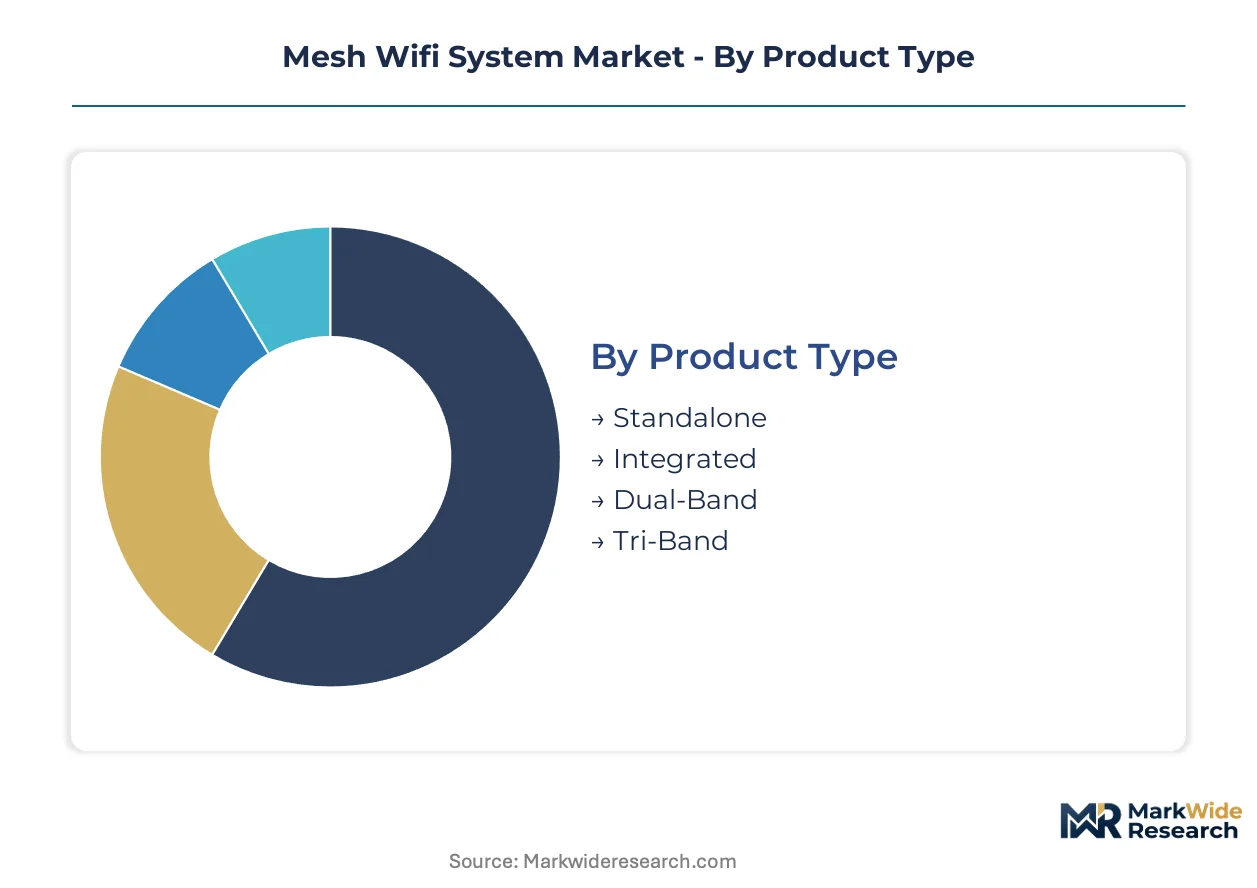
Mesh system segmentation reveals divergent channel economics across hardware tiers and deployment complexity. Product type and connectivity choices dictate margin structure, while installation mode determines whether vendors capture value through retail markup or recurring service revenue.
Product Type:
Standalone units flow through retail and e-commerce channels targeting consumer self-installation. Integrated systems bundle with ISP routers and smart home platforms. Dual-band hardware dominates mass-market shelf space. Tri-band configurations command professional installer and direct enterprise procurement channels.
- Standalone:Discrete nodes purchased separately from router infrastructure, typically featuring two radios and basic mesh handoff protocols. Demand concentrates in United States suburban single-family homes where consumers prioritize flexibility over ISP bundling, constrained by price sensitivity that caps average selling prices.
- Tri-Band:Dedicated 5 GHz or 6 GHz backhaul radio eliminates client-facing congestion, enabling sustained throughput above 5 Gbps across multi-node deployments. German commercial real estate developers specify these for new construction smart building infrastructure, driven by ETSI harmonized spectrum rules that standardize 6 GHz power limits.
- Integrated:Mesh functionality embedded within ISP-provided gateway devices, reducing consumer equipment decisions. China MIIT network access licenses favor domestic vendors for this channel.
- Dual-Band:Shared 2.4 GHz and 5 GHz radios for client and backhaul traffic, sufficient for sub-100 Mbps broadband tiers. Volume leadership in India municipal Wi-Fi projects under Smart Cities Mission procurement.
By volume, Dual-Band leads. By growth pace, Tri-Band is climbing the fastest.
Connectivity:
Connectivity choice reflects the reliability-cost tradeoff that shapes procurement in commercial versus residential contexts. Wireless backhaul minimizes installation labor. Ethernet and powerline alternatives appeal where building construction defeats radio propagation.
- Wireless:Radio backhaul between nodes using 5 GHz or 6 GHz dedicated channels, eliminating cable pulls. United States hospitality chains standardize on wireless mesh for franchise property retrofits where Ethernet infrastructure is absent, constrained by FCC unlicensed spectrum power limits that reduce range in concrete structures.
- Ethernet:Wired backhaul via Cat5e/Cat6 cabling delivers deterministic latency and immunity from RF interference. German educational facilities mandate Ethernet for administrative network segments under federal data protection requirements.
- Powerline:Electrical wiring carries network signals between nodes, bridging gaps where coaxial or Ethernet is unavailable. Niche demand in European heritage buildings where surface cabling violates preservation codes.
- Hybrid:Automatic selection between wireless and wired backhaul based on link quality metrics. Emerging preference among United States mid-market enterprises seeking deployment flexibility without pre-surveying every site.
Ethernet captures the highest per-site revenue. Wireless dominates unit shipments.
End User:
End-user segmentation separates high-volume consumer markets from commercial verticals where professional installation and cloud management subscriptions generate recurring revenue. Residential buyers prioritize plug-and-play simplicity. Commercial and institutional segments demand API integration and centralized policy enforcement.
- Residential:Single-family homes and multi-dwelling units where consumers self-select hardware through retail and e-commerce. China urban residential towers drive dense node deployment, constrained by MIIT certification timelines that delay product launches.
- Hospitality:Hotels, resorts, and extended-stay properties requiring seamless guest roaming and captive portal authentication. United States franchise standardization on unified cloud platforms accelerates procurement velocity.
- Commercial:Enterprise campuses and branch offices with IT-managed infrastructure. Germany leads European adoption through embedded new construction specifications.
- Educational:K-12 and higher education institutions with high-density device loads and content filtering requirements. India Smart Cities Mission creates bulk procurement channels for municipal school connectivity.
Residential generates the largest unit volumes. Hospitality produces the steepest expansion trajectory in revenue terms.
Installation:
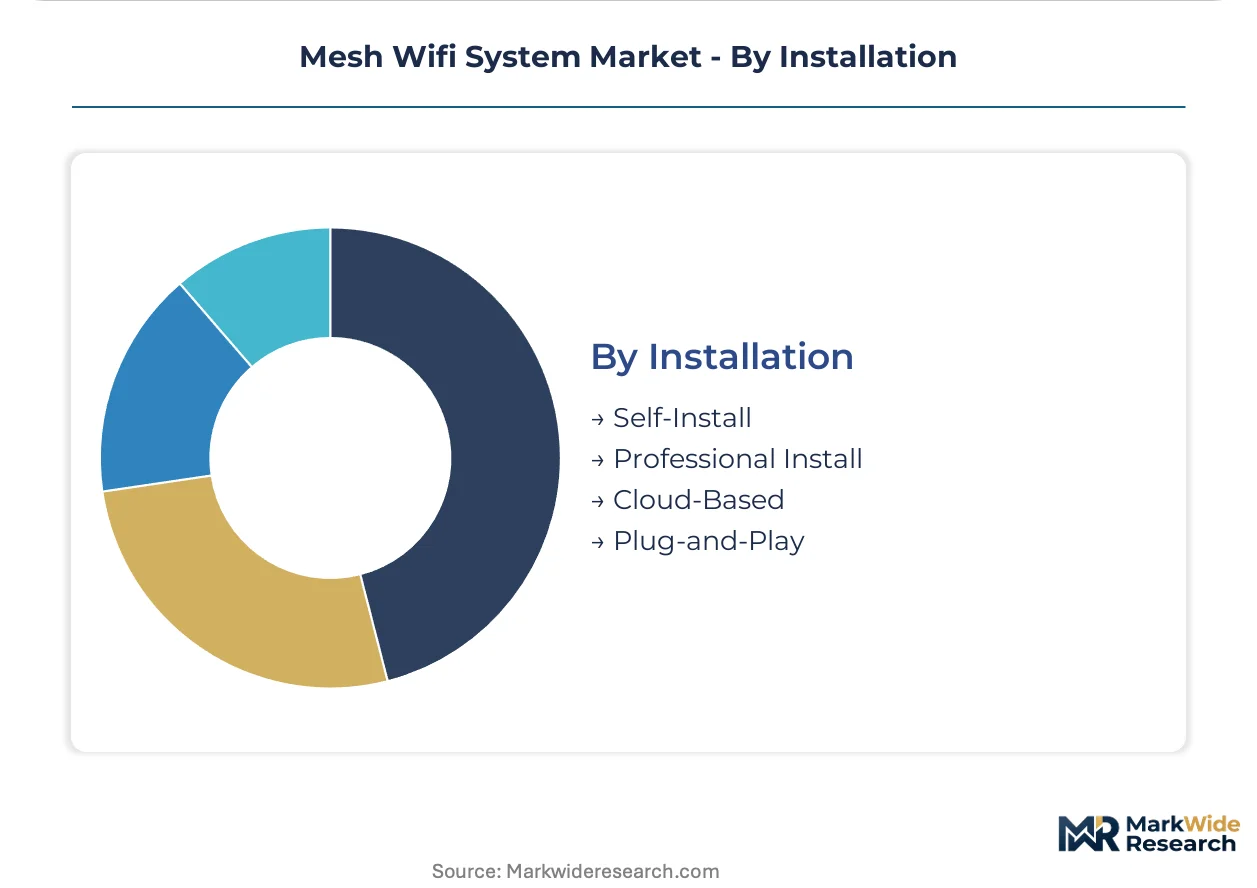
Installation modality determines whether vendors capture margin through hardware markup or ongoing service contracts. Self-install and plug-and-play options minimize customer acquisition cost. Professional and cloud-based approaches enable recurring revenue capture.
- Cloud-Based:Remote provisioning, monitoring, and policy management through vendor-hosted platforms. United States mid-market enterprises adopt this model to reduce on-site IT headcount, driven by subscription economics that displace perpetual license procurement.
- Professional Install:Certified technician deployment with site survey, optimal node placement, and post-installation validation. German commercial real estate developers bundle this into construction contracts to ensure coverage guarantees.
- Self-Install:Consumer-guided setup through mobile applications with automated network optimization. Dominates United States retail channel where price transparency pressures hardware margins.
- Plug-and-Play:Pre-paired nodes that activate without configuration steps. Preferred in India municipal deployments where technical literacy varies across installation sites.
Self-Install leads in units shipped. Cloud-Based is gaining share fastest in revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's 6 GHz spectrum allocation underwrites United States dominance in tri-band hardware deployment, while China's MIIT licensing framework and Germany's ETSI harmonization anchor regional procurement patterns across three distinct regulatory environments.
United States
Hospitality chains and multi-dwelling residential towers drive dense node deployment across urban corridors. FCC unlicensed spectrum rules govern 6 GHz power limits that shape equipment range in concrete structures. Silicon Valley cloud management vendors and Austin smart building developers accelerate subscription-based procurement models.
China
Urban residential complexes in tier-one cities require seamless coverage across high-rise construction that defeats single-router solutions. MIIT network access licenses create regulatory gates that favor certified domestic and foreign vendors. Shenzhen hardware ecosystems and Beijing enterprise campuses concentrate manufacturing and deployment expertise.
Germany
Commercial real estate developers embed mesh infrastructure into new construction specifications ahead of occupancy. ETSI harmonized spectrum rules standardize 6 GHz power limits across EU member states. Munich and Frankfurt smart building clusters lead European adoption of ceiling-mounted and in-wall form factors.
India
Municipal Wi-Fi projects under the Smart Cities Mission create bulk procurement channels for cloud-managed systems. TRAI broadband policy frameworks shape public infrastructure deployment timelines. Bangalore and Hyderabad technology corridors concentrate system integrator capacity for educational and hospitality verticals.
Japan
Enterprise campuses and hospitality properties demand high-density coverage with deterministic latency for building automation integration. METI industrial standards guide procurement specifications for commercial facilities. Tokyo and Osaka metropolitan areas concentrate premium-tier deployment expertise.
Mesh Wifi System Market Competitive Landscape
Listed leaders compete with private specialists across cloud management platforms and hardware tiers, producing a bifurcated structure where premium-tier suppliers anchor enterprise procurement while cost-focused challengers capture residential volume. Three archetypes dominate: ecosystem integrators bundling mesh with broader networking portfolios, cloud-native specialists monetizing through subscription management layers, and semiconductor licensors enabling third-party hardware roadmaps. Consolidation pressure manifests through strategic partnerships for API interoperability and geographic expansion into smart city verticals.
Among networking equipment incumbents, Netgear and Cisco Systems exemplify divergent strategic positioning within the premium tier, while TP-Link occupies a position as the cost-focused challenger extending retail and e-commerce distribution. Netgear represents the ecosystem integrator archetype through its Orbi residential platform, Cisco Systems anchors enterprise cloud-managed deployment, and TP-Link exemplifies aggressive price competition without ecosystem lock-in.
| Leading Market Players |
|---|
| Netgear |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Qualcomm Technologies |
| Ruckus Networks |
| TP-Link |
| ASUS |
| Amazon |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Taiwan and South Korea foundries lock in RF front-end component access while stabilizing unit cost visibility for tri-band hardware vendors navigating FCC and ETSI certification timelines. These arrangements concentrate pricing power among incumbent mesh suppliers with established foundry relationships, while cost-focused challengers absorb spot-market volatility in 6 GHz power amplifier procurement.
Pricing Analysis
Certification level creates the primary spread between premium-tier and cost-focused offerings, with Wi-Fi Alliance tri-band interoperability certification adding four to six months to product launch windows. Pricing stratifies across premium, standard, and economy tiers based on backhaul radio configuration and cloud management bundling. Cost compression in dual-band residential segments intensifies because TP-Link and retail-channel competitors prioritize volume share over margin retention. Hospitality and education verticals show least price sensitivity due to professional installation requirements and multi-year service contract structures.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose mesh hardware vendors to concentrated RF semiconductor sourcing from Taiwan and South Korea foundries. Antenna arrays and power amplifiers draw from neodymium rare earth feedstock anchored in Chinese processing facilities and copper cathode supplies from Chilean and Peruvian mining operations. Single-source vulnerability in 6 GHz RF front-end components creates procurement risk if geopolitical friction disrupts cross-strait logistics. Distribution runs through certified installer networks in commercial verticals and retail-electronics chains in residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mesh wifi infrastructure is approaching a platform-economics inflection where cloud management APIs and smart building integration protocols determine vendor viability, with ETSI harmonization and FCC spectrum allocation accelerating interoperability demands across enterprise procurement.
For Market Incumbents: Secure API interoperability certifications with leading building automation platforms before new construction specifications harden around preferred vendor lists. Defend against cloud-native specialists by deepening captive supply of 6 GHz RF components through foundry partnership extensions. Certification investment in Wi-Fi 7 pre-standard equipment represents the critical lever for maintaining premium positioning. For New Entrants and Emerging Players: FCC streamlined equipment authorization offers fastest path to United States commercial deployment for challengers lacking legacy certification infrastructure. Target India municipal Wi-Fi procurement under Smart Cities Mission where technical specifications favor plug-and-play simplicity over ecosystem lock-in. Direct-to-installer distribution bypasses retail margin compression while capturing recurring cloud management revenue. For Investors and Strategic Acquirers: Cloud-native mesh management specialists with established hospitality vertical penetration present attractive acquisition profiles as franchise standardization accelerates. Long-term viability hinges on subscription revenue share exceeding hardware margin dependency within a five-to-ten year transition window. Monitor Wi-Fi Alliance certification timeline compression as signal for vendor consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Pre-Standard Deployment | IEEE 802.11be draft equipment captures early-mover positioning in enterprise campus upgrades. |
| Cloud Management Platform Integration | API compatibility with Cisco Meraki and competitor stacks fragments vendor development resources. |
| Direct-to-Installer Distribution | Certified installer networks capture margin in commercial verticals requiring professional deployment. |
| Foundry Capacity Reservation | Long-term contracts with Taiwan and South Korea suppliers stabilize RF component cost visibility. |
| Smart Building Specification Embedding | German commercial real estate developers integrate mesh infrastructure into new construction ahead of occupancy. |
Research Methodology
Operator-level perspectives from network infrastructure procurement officers, RF engineering directors, smart building facilities managers, and hospitality IT executives anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, ETSI harmonized standards documentation, and MIIT network access license registries. Bottom-up shipment estimates by product tier triangulated against top-down market sizing from broadband infrastructure deployment disclosures across the analysis window.
Sensitivity analysis around Wi-Fi 6E adoption velocity and enterprise refresh cycle compression informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity mode, end-user vertical, and installation modality alongside regional regulatory cluster variations. CAGRs derived from installed base replacement dynamics and greenfield smart building penetration rates, with inputs from semiconductor foundry capacity announcements and copper-neodymium commodity price trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained FCC 6 GHz spectrum stability and ETSI harmonization continuity; material deviation in Taiwan Strait logistics or MIIT licensing timelines would warrant model refresh. Practitioners should keep alternative scenarios live as Wi-Fi 7 standardization and India Smart Cities Mission procurement pacing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
5G Spectrum Market