
 Wireless LAN Controller Market | 2026-2036
Wireless LAN Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless LAN Controller Market Intelligence
Subscription-based network-as-a-service financing is reshaping how mid-market enterprises procure wireless infrastructure, shifting capital expenditure to operational budgets and lowering barriers for vendor entry. Cisco leverages its channel density to sustain recurring revenue from cloud-managed controller platforms. Huawei anchors its position through integrated silicon-to-software stacks that reduce third-party dependency. Juniper Networks differentiates via AI-native operations that automate radio frequency optimization across distributed controller architectures.
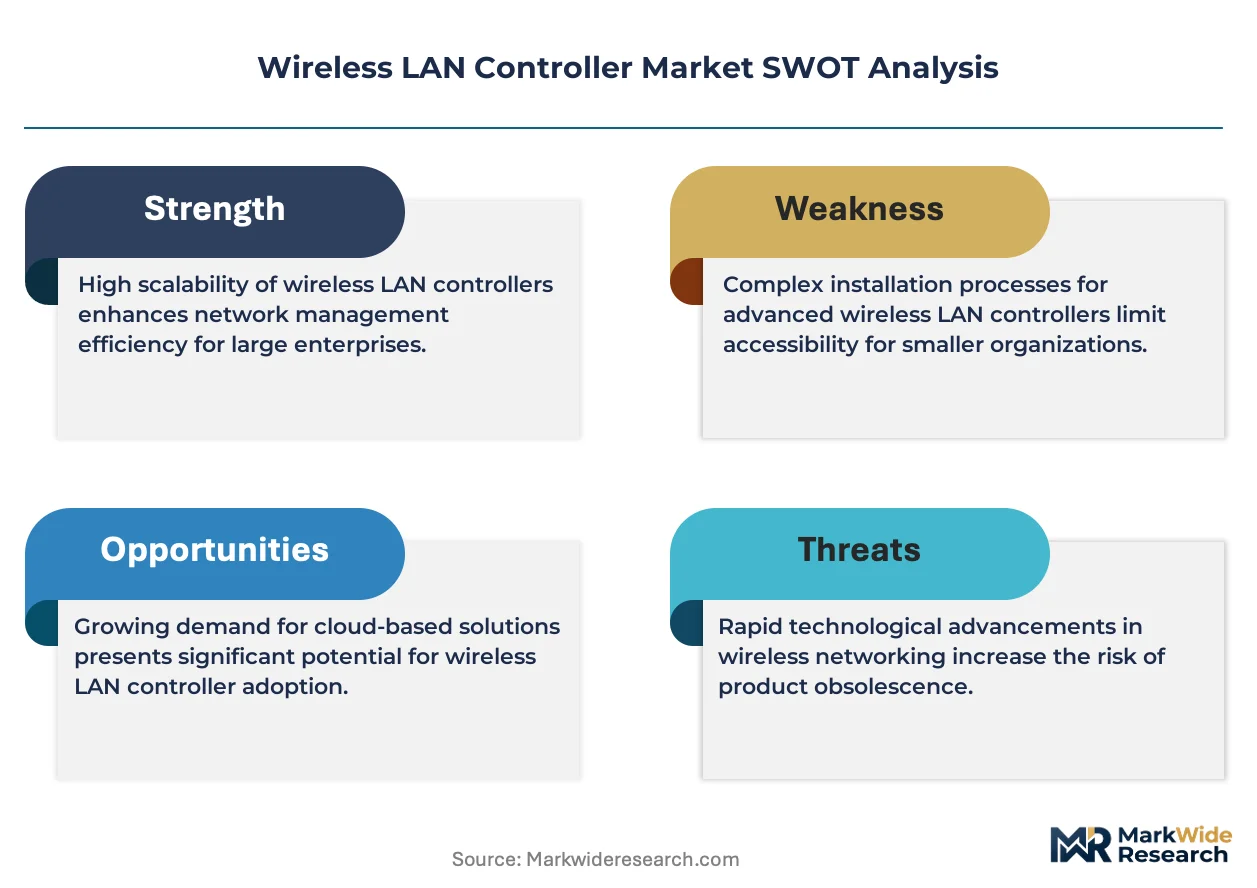
A wireless LAN controller is a centralized network device that manages multiple access points through protocols such as CAPWAP, enforcing security policies, roaming handoffs, and quality-of-service rules across enterprise airspace. Hardware controllers maintain dominance in latency-sensitive environments such as manufacturing floors and healthcare operating suites where local breakout remains mandatory. Cloud-based controllers represent the fastest-expanding deployment category as distributed workforces push management planes toward elastic SaaS architectures. Enterprise networks command the largest application share, though hospitality venues and transportation hubs are emerging as high-volume segments where guest access density drives controller clustering requirements.
FCC Part 15 rules govern unlicensed spectrum use in the United States, directly shaping radio hardware designs that controllers must coordinate, while the EU AI Act and GDPR impose automated decision-making and data residency constraints on cloud-managed platforms serving European endpoints. China's MIIT enforces domestic encryption standards that foreign controller vendors must localize to achieve network equipment type approval. Stakeholders must monitor spectrum reallocation proceedings and cross-border data governance evolution to align controller roadmaps with compliance trajectories.
Market Dynamics
Wi-Fi 7 certification mandates from the FCC and equivalent spectrum regulators are compressing hardware refresh cycles and forcing enterprise networks to replace controller infrastructure ahead of traditional depreciation schedules.
Growth Catalysts
- Wi-Fi 7 Spectrum Allocation:FCC Part 15 expansion into the 6 GHz band enables wider channel bonding that demands new controller coordination capabilities, pushing campus networks toward hardware upgrades.
- Healthcare Operating Suites:Latency-sensitive medical environments require local controller breakout for real-time patient monitoring systems, sustaining demand for on-premise appliance deployments.
- Cloud-Managed SaaS Migration:Distributed workforces are accelerating adoption of elastic controller architectures that centralize policy management across fragmented endpoint locations.
Market Restraints
- Silicon Supply Concentration:Advanced networking chip fabrication concentrates among Taiwan-based foundries, exposing controller vendors to single-point-of-failure risks during geopolitical disruptions.
- GDPR Data Residency Friction:EU-mandated local storage requirements for automated network decision-making complicate cloud controller deployments serving European endpoints.
- Power Amplifier Cost Volatility:Gallium nitride substrate prices fluctuate with defense sector demand, pressuring radio hardware margins that propagate into controller bundling economics.
Strategic Opportunities
- India Smart City Infrastructure:Municipal Wi-Fi densification programs under the Digital India initiative create greenfield controller deployments across transportation hubs and public venues.
- AI-Native Radio Optimization:Machine learning convergence with RF management enables predictive interference mitigation that differentiates next-generation controller platforms.
- Network-as-a-Service Channel Expansion:Managed service providers are building subscription controller offerings that bypass traditional VAR distribution and capture mid-market procurement budgets.
Industry Challenges
- CAPWAP-to-OpenFlow Migration Complexity:Enterprise IT teams face skill gaps in software-defined networking protocols when transitioning from legacy tunneling architectures to programmable controller fabrics.
- Multi-Vendor Interoperability Certification:Fragmented implementation of Wi-Fi 7 pre-standard features forces extended testing cycles before heterogeneous access point and controller combinations achieve production stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless LAN Controller Market |
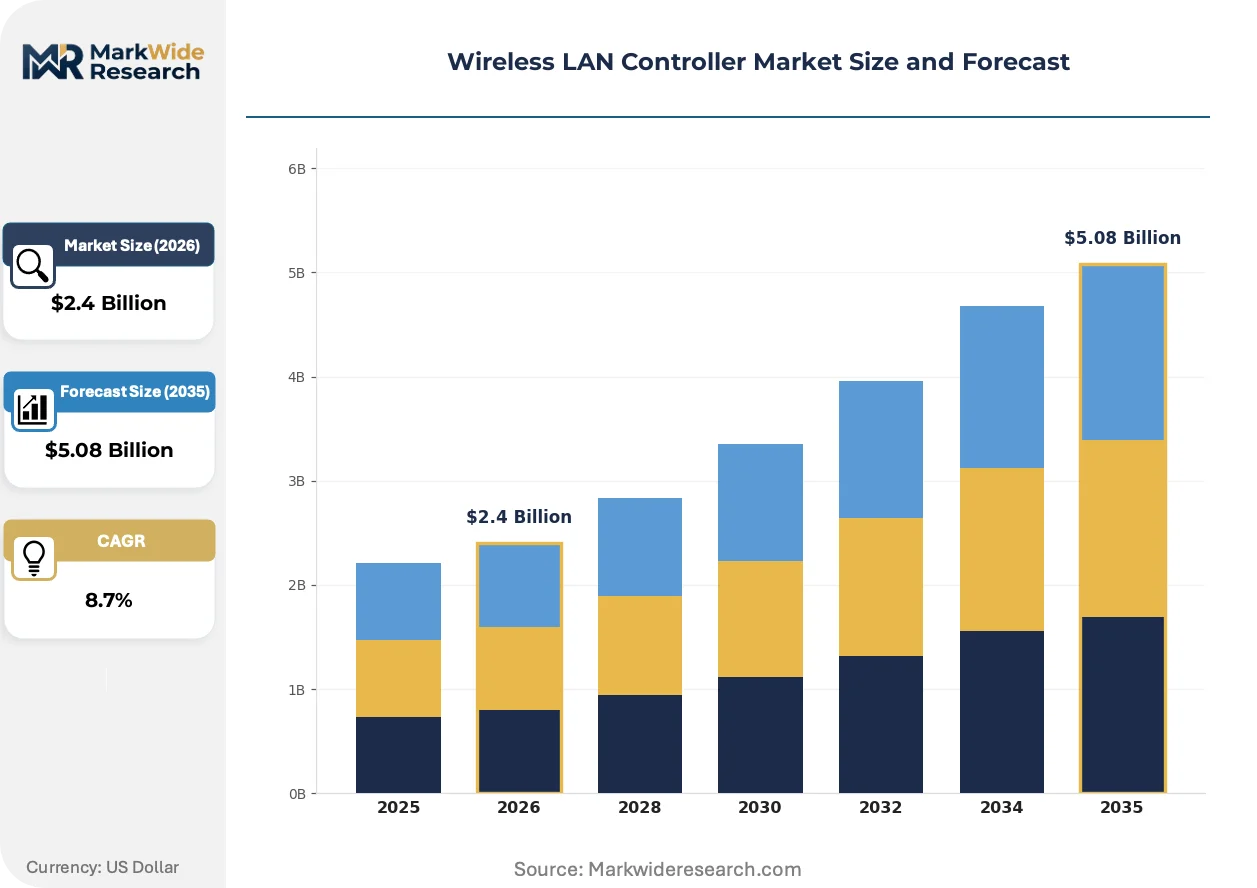
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Controllers, Hardware Controllers, Hybrid Controllers, Virtual Controllers Deployment Mode: On-Premises, Remote Managed, Hosted Services, Managed Services Application: Enterprise Networks, Education Facilities, Hospitality Venues, Government Institutions, Transportation Hubs End User: Telecommunications Providers, Data Centers, Managed Service Providers, System Integrators |
| Companies Covered | Aruba, Broadcom, Cisco, Ruckus Networks, Juniper Networks, Huawei, Clarinox Technologies, Extreme Networks, NETGEAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless LAN Controller Market Strategic Shifts & Innovations
Controller intelligence is migrating from dedicated hardware appliances toward disaggregated software layers that run on commodity compute, reshaping how vendors monetize radio management capabilities.
Containerized controller software is virtualizing network functions that previously required proprietary silicon, allowing hyperscale data center operators to consolidate wireless management onto existing server infrastructure. Financial services firms with distributed branch footprints are piloting these deployments to collapse networking hardware sprawl. This shift is compressing addressable revenue per site for traditional appliance vendors while expanding total controller instance counts.
EU AI Act algorithmic transparency requirements are mandating explainable automation in cloud-managed platforms that use machine learning for client steering and band selection. Vendors serving European enterprise networks must now document decision logic that was previously opaque neural network inference. Healthcare and government verticals in Germany and France are demanding these disclosures as procurement prerequisites.
Buyers are unbundling hardware procurement from ongoing management services, treating controllers as interchangeable infrastructure while selecting managed Wi-Fi operators for operational execution. Hospitality chains in the United States are leading this pattern, sourcing access points and controllers through distribution while contracting separate NOC providers for guest experience monitoring. This bifurcation fragments vendor relationships and compresses attach rates for premium support tiers.
Wireless LAN Controller Market Segmentation
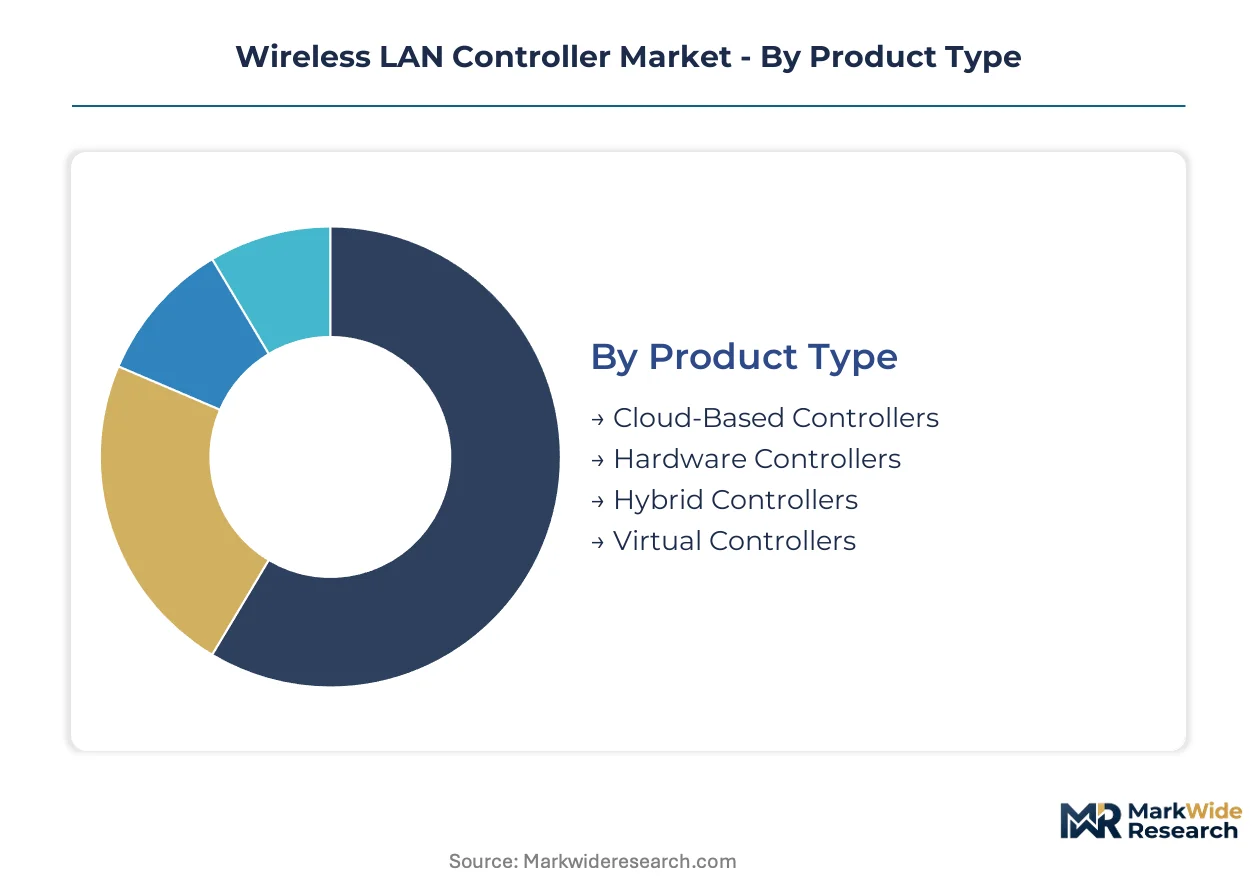
Wireless LAN controller procurement patterns diverge sharply across deployment architectures and buyer constituencies. Understanding these fault lines clarifies why cloud-native platforms capture mid-market budgets while hardware appliances retain mission-critical installations.
Product Type:
Use-case spectrum spans latency-sensitive local breakout to elastic multi-tenant orchestration.
- Cloud-Based Controllers:SaaS-delivered management planes centralize policy enforcement across distributed access points without on-site hardware. Hospitality chains in the United States favor these platforms for rapid venue provisioning and guest analytics integration.
- Hardware Controllers:Dedicated appliance form factors process CAPWAP tunnels with deterministic latency for manufacturing floors and healthcare operating suites where local breakout remains non-negotiable.
- Hybrid Controllers:Split-plane architectures keep data forwarding local while pushing management intelligence to cloud instances, addressing GDPR data residency constraints for European enterprise networks.
- Virtual Controllers:Software-only distributions run on commodity servers or hyperconverged infrastructure, appealing to hyperscale data center operators consolidating network functions onto existing compute.
The dominant share belongs to Hardware Controllers, while Cloud-Based Controllers are closing the gap fastest.
Deployment Mode:
Control over operational cadence and capital allocation drives selection across the ownership spectrum.
- On-Premises:Enterprises retain full hardware and software custody, absorbing depreciation schedules and staffing burdens in exchange for customization latitude and air-gapped security postures.
- Remote Managed:Vendors operate controller infrastructure from centralized NOCs while customers maintain physical site presence, splitting accountability for uptime and firmware maintenance.
- Hosted Services:Single-tenant controller instances run in vendor or third-party data centers, delivering dedicated capacity without customer-managed hardware procurement cycles.
- Managed Services:End-to-end operational responsibility transfers to MSPs including RF planning, client onboarding, and tier-3 support, converting wireless infrastructure to subscription opex.
On-Premises deployments retain the largest installed base, though Managed Services are expanding most quickly among mid-market enterprises.
Application:
Density requirements and mobility patterns reshape controller clustering architectures by vertical.
- Enterprise Networks:Campus environments with thousands of access points demand high-availability controller pairs and seamless roaming across buildings, driving investment in redundant hardware stacks.
- Education Facilities:Universities balance open guest policies with research network segmentation, requiring policy engines that distinguish student, faculty, and IoT device traffic streams.
- Hospitality Venues:Hotels and conference centers prioritize guest experience monitoring and captive portal monetization, favoring cloud controllers with built-in analytics and marketing integrations.
- Government Institutions:Classified and unclassified network separation mandates FIPS-validated encryption and domestic supply chain attestation, constraining vendor eligibility.
- Transportation Hubs:Airports and rail terminals combine high-density passenger Wi-Fi with operational technology networks for baggage handling and signaling, necessitating multi-SSID controller configurations.
Enterprise Networks command the greatest controller expenditure, while Transportation Hubs are gaining share fastest as municipal densification programs accelerate.
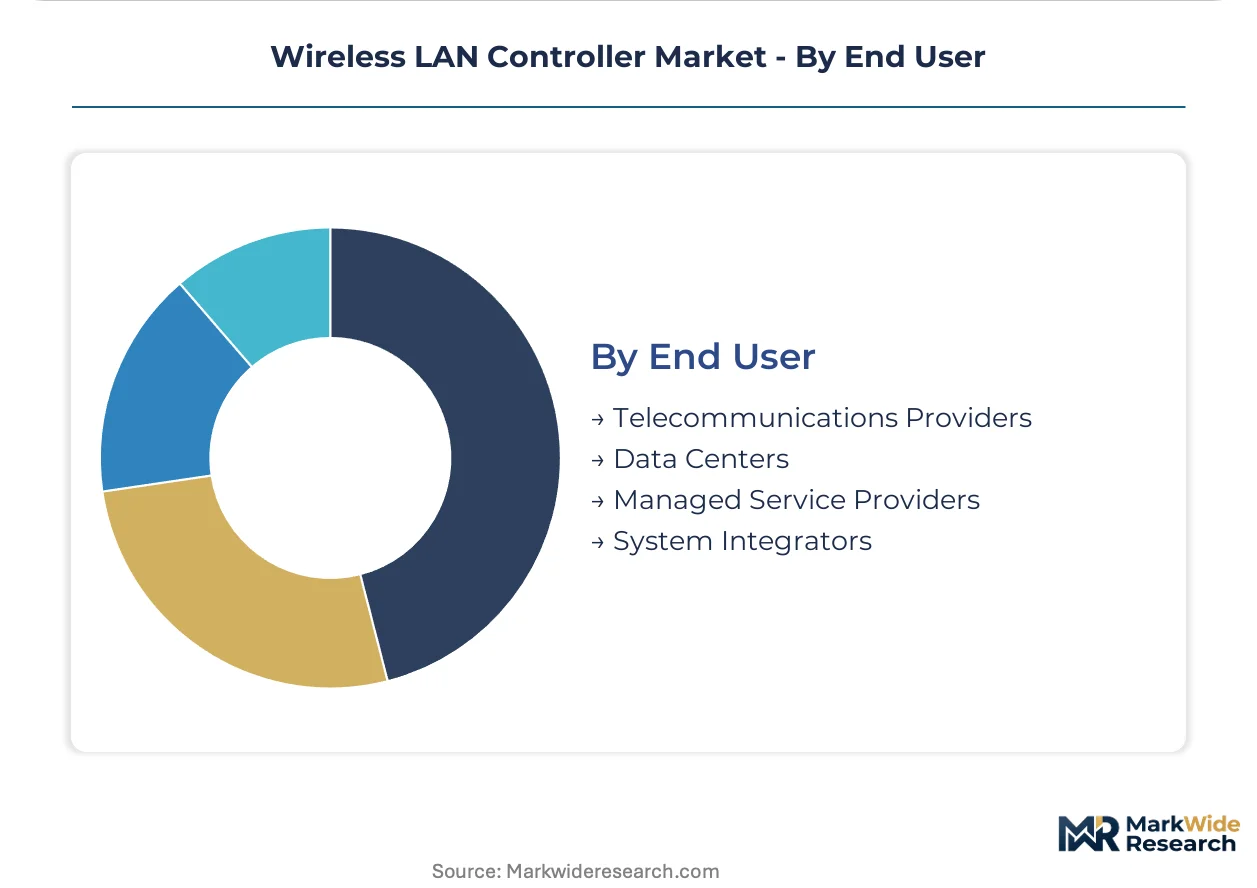
End User:
Procurement authority concentrates with entities that aggregate wireless demand across multiple downstream organizations.
- Telecommunications Providers:Carriers bundle managed Wi-Fi with broadband and mobile services, deploying controllers at scale to support residential and SMB subscriber bases.
- Data Centers:Colocation and cloud operators extend connectivity services to cage tenants and edge locations, treating wireless as a facility utility rather than customer-facing product.
- Managed Service Providers:MSPs white-label wireless services to distributed enterprises, standardizing on multi-tenant controller platforms that isolate customer configurations.
- System Integrators:SIs specify controllers within broader digital transformation engagements, favoring vendors with robust APIs and professional services ecosystems.
Telecommunications Providers absorb the highest controller volumes, while Managed Service Providers are climbing the fastest as NaaS adoption reshapes channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 rules governing 6 GHz spectrum access have accelerated hardware refresh cycles across enterprise networks, compressing traditional depreciation schedules and redirecting procurement budgets toward Wi-Fi 7-ready infrastructure.
United States
Enterprise campus densification and healthcare operating suite deployments sustain demand for low-latency controller appliances. FCC certification mandates for Wi-Fi 7 radio coordination push federal contractors toward compliant hardware upgrades. Dallas-Fort Worth and Raleigh-Durham clusters concentrate hospitality and technology sector procurement activity.
China
Smart city infrastructure programs and manufacturing floor automation generate multi-thousand access point deployments requiring localized controller breakout. MIIT domestic encryption standards compel foreign vendors to localize software stacks for network equipment type approval. Shenzhen and Shanghai metropolitan regions anchor cloud-managed controller development for Asia-Pacific distribution.
Germany
Industrial automation networks and automotive production facilities prioritize deterministic latency through on-premise controller architectures. EU AI Act algorithmic transparency requirements constrain cloud-managed platform deployments serving automated RF optimization use cases. Munich and Stuttgart engineering clusters drive demand for FIPS-validated encryption in government-adjacent installations.
India
Municipal Wi-Fi densification under the Digital India initiative creates greenfield controller deployments across transportation hubs and public venues. TRAI spectrum allocation proceedings for 6 GHz unlicensed use shape vendor localization strategies. Bangalore and Hyderabad technology corridors concentrate hyperscale data center operator demand for virtualized controller software.
United Kingdom
Financial services branch consolidation and distributed workforce connectivity accelerate managed service provider adoption of subscription-based controller platforms. GDPR data residency constraints complicate cloud controller deployments serving European endpoints from UK-based infrastructure. London metropolitan financial district and Manchester technology cluster sustain hybrid controller architecture procurement.
Wireless LAN Controller Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement pathways, creating tiered competitive dynamics where scale advantages clash with vertical integration depth. The vendor base spans three strategic archetypes: networking incumbents with silicon-to-software stacks, cloud-native challengers with SaaS delivery models, and regional specialists with localized certification expertise. Consolidation pressure concentrates among mid-market appliance vendors as subscription financing reshapes customer relationships. Dominant competitive moves include strategic partnerships with managed service providers and portfolio diversification into AI-native operations automation.
Within the networking incumbent tier, Cisco Systems Inc. and Huawei Technologies Co., Ltd. exemplify divergent approaches to vertical integration and geographic market access. Juniper Networks, Inc. occupies a position emphasizing AI-native differentiation across distributed controller architectures. These three anchors illustrate how vendor archetypes map to distinct procurement channel strategies and compliance jurisdiction requirements.
| Leading Market Players |
|---|
| Aruba |
| Broadcom |
| Cisco |
| Ruckus Networks |
| Juniper Networks |
| Huawei |
| Clarinox Technologies |
| Extreme Networks |
| NETGEAR |
| Others |
Cost & Logistics Intelligence
Taiwan-based foundry concentration for advanced networking silicon concentrates margin capture upstream, forcing controller vendors to absorb cost volatility through bundling strategies while downstream buyers unbundle hardware from management services.
Pricing Analysis
Certification level creates the primary spread across controller tiers, with FCC Part 15 Wi-Fi 7 compliance and FIPS-validated encryption commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by latency tolerance, with healthcare operating suites and manufacturing floors least sensitive while hospitality chains drive cost compression through volume procurement. Price differentiation intensifies as cloud-managed SaaS platforms displace appliance models, compressing upfront hardware margins while expanding recurring revenue pools. Mid-market enterprises exhibit highest price sensitivity, gravitating toward subscription financing that converts capital expenditure to operational budgets.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit capacity expansion for networking chip fabrication, constraining supply elasticity for controller vendors dependent on leading-edge process nodes. Taiwan, South Korea, and the United States anchor advanced silicon production, with gallium nitride substrates for radio power amplifiers drawing from defense-linked supply chains. Controller hardware rests on captive foundry relationships and multi-source qualification programs to mitigate single-point-of-failure exposure. Distribution runs through authorized value-added resellers for enterprise accounts, while cloud-managed platforms bypass traditional channels through direct MSP partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment architectures and buyer procurement models creates specialized niches for differentiated entrants, as unbundling of hardware from management services fragments incumbent channel control.
For Market Incumbents: Entrench cloud-managed platform adoption through API ecosystem depth and MSP certification programs, countering containerized software challengers that virtualize controller functions onto commodity compute. Deepen backward integration into radio silicon design to reduce foundry dependency exposure, while accelerating AI-native RF optimization roadmaps to differentiate against software-only competitors.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where legacy controller refresh cycles lag North American and European adoption curves. Virtualized controller software for hyperscale data center operators offers second white-space opportunity, collapsing wireless management onto existing server infrastructure without proprietary appliance procurement. Go-to-market execution should anchor on managed service provider channel partnerships rather than direct enterprise sales.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with localized certification expertise in MIIT-compliant China or BIS-aligned India markets, where foreign vendor eligibility constraints create acquisition scarcity value. Long-term viability hinges on software subscription revenue mix exceeding hardware transactional exposure. Watch for spectrum reallocation proceedings in major economies as inflection indicator forcing controller hardware refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native RF Optimization Platform | Machine learning convergence with radio management automates interference mitigation for distributed controller architectures. |
| Multi-Tenant Cloud Controller Deployment | Elastic SaaS architectures centralize policy enforcement across fragmented endpoint locations for distributed workforces. |
| Wi-Fi 7 Hardware Certification Acceleration | FCC Part 15 compliance mandates compress refresh cycles and redirect procurement budgets toward compliant infrastructure. |
| Regional Supply Chain Localization | MIIT domestic encryption standards and BIS certification requirements compel foreign vendors to establish local software stacks. |
| Managed Service Provider Channel Expansion | Subscription network-as-a-service financing bypasses traditional VAR distribution and captures mid-market procurement budgets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wireless network architects, data center infrastructure directors, MSP operations leads, and hospitality technology procurement officers. Secondary validation drew from FCC equipment authorization databases, TRAI spectrum allocation proceedings, EU AI Act implementation guidance, and hyperscaler capital expenditure disclosures. Bottom-up controller shipment estimates by deployment mode were triangulated against top-down enterprise networking spend analysis.
Calibration across historical adoption curves and regulatory mandate timelines shaped projection frameworks across the analysis window. Segmentation dimensions modeled include controller architecture type, deployment ownership model, end-use vertical density requirements, and regional compliance jurisdiction. CAGRs were derived from installed base growth rates adjusted for hardware refresh compression effects, with Wi-Fi 7 certification mandates and cloud-managed SaaS migration patterns serving as primary forecast inputs.
Stress conditions across foundry capacity utilization, gallium nitride substrate price volatility, and cross-border data governance enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spectrum allocation stability and encryption standard harmonization. Material shifts in semiconductor export control regimes or major economy spectrum reallocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Wi-Fi Booster Market