
 Wireless Communication Technologies in Healthcare Market | 2026-2036
Wireless Communication Technologies in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Communication Technologies in Healthcare Market Outlook
Multi-source procurement of wireless chipsets and connectivity modules is restructuring how healthcare technology vendors secure supply. Qualcomm Technologies dominates baseband and radio-frequency component supply for medical-grade wearables. Cisco Systems anchors enterprise networking infrastructure across major hospital systems. Philips Healthcare differentiates through integrated diagnostic-to-connectivity platforms that reduce interoperability friction.
Wireless communication technologies in healthcare encompass radio-frequency systems, short-range protocols, and cellular networks engineered to transmit clinical data with latency below 250 milliseconds and uptime exceeding 99.9%. These systems enable real-time patient monitoring, clinician alerts, and decentralized care delivery without hardwired infrastructure. Wi-Fi and Bluetooth together command the largest installed base, though Zigbee is gaining traction in smart implant applications where ultra-low power draw extends device longevity. Telemedicine and remote monitoring represent the fastest-expanding application cluster, driven by reimbursement codes that now cover connected chronic disease management. Service-type revenue pools concentrate in system integration, where hospitals pay premium rates to merge legacy electronic health records with new wireless endpoints.
FDA premarket guidance for wireless medical devices, FCC spectrum allocation rules for healthcare bands, and HIPAA security requirements collectively determine which products reach commercial deployment. The FDA's cybersecurity premarket expectations have lengthened development timelines for unconnected legacy devices seeking wireless upgrades. Stakeholders must monitor whether emerging FDA software-as-a-medical-device pathways will accelerate or complicate clearance for AI-enabled wireless diagnostics.
Market Dynamics
Hospital system consolidation is compressing vendor selection cycles and mandating interoperability certifications that smaller wireless device manufacturers struggle to meet, forcing wholesale restructuring of go-to-market strategies across the medical connectivity sector.
Growth Catalysts
- Reimbursement alignment:CMS and commercial payers in the United States now cover connected chronic disease management through discrete billing codes, converting remote monitoring from pilot expenditure to reimbursed standard of care.
- FDA cybersecurity premarket guidance:The agency's 2023 and 2024 updates to wireless medical device submissions are accelerating clearance timelines for products designed with security-by-architecture rather than retrofitted compliance.
- Wi-Fi 6E and private 5G:These protocols are expanding into surgical suites and emergency departments where deterministic low-latency transmission enables real-time imaging and robotic instrument control.
Market Restraints
- Semiconductor supply concentration:Advanced radio-frequency components for medical-grade wearables depend on fabrication capacity concentrated in Taiwan and South Korea, exposing procurement to geopolitical disruption.
- HIPAA technical safeguard complexity:Encryption and access control requirements for wireless transmission create compliance friction that extends development cycles by 8-14 months for first-time entrants.
- Legacy infrastructure lock-in:Hospital systems with 15-20 year-old wired telemetry networks face capital-intensive replacement decisions that delay wireless endpoint deployment.
Strategic Opportunities
- Home-based acute care:CMS's Hospital at Home waiver programs in the United States are creating demand for cellular-enabled vital sign monitors that operate outside institutional network perimeters.
- AI-enabled edge diagnostics:Convergence of on-device machine learning with low-power wide-area networks permits diagnostic-grade ECG and glucose analysis without cloud dependency.
- EU Medical Device Regulation harmonization:MDR's expanded software classification is creating first-mover advantage for wireless platforms with pre-certified cybersecurity documentation.
Industry Challenges
- Embedded systems security engineering:Scarce talent pools for firmware-level cryptography and secure boot implementation are constraining product pipeline velocity across mid-tier device manufacturers.
- Multi-protocol integration testing:Validating simultaneous Wi-Fi, Bluetooth, and cellular operation in clinical environments requires capital-intensive anechoic chambers and spectrum analyzers that smaller vendors cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Communication Technologies in Healthcare Market |
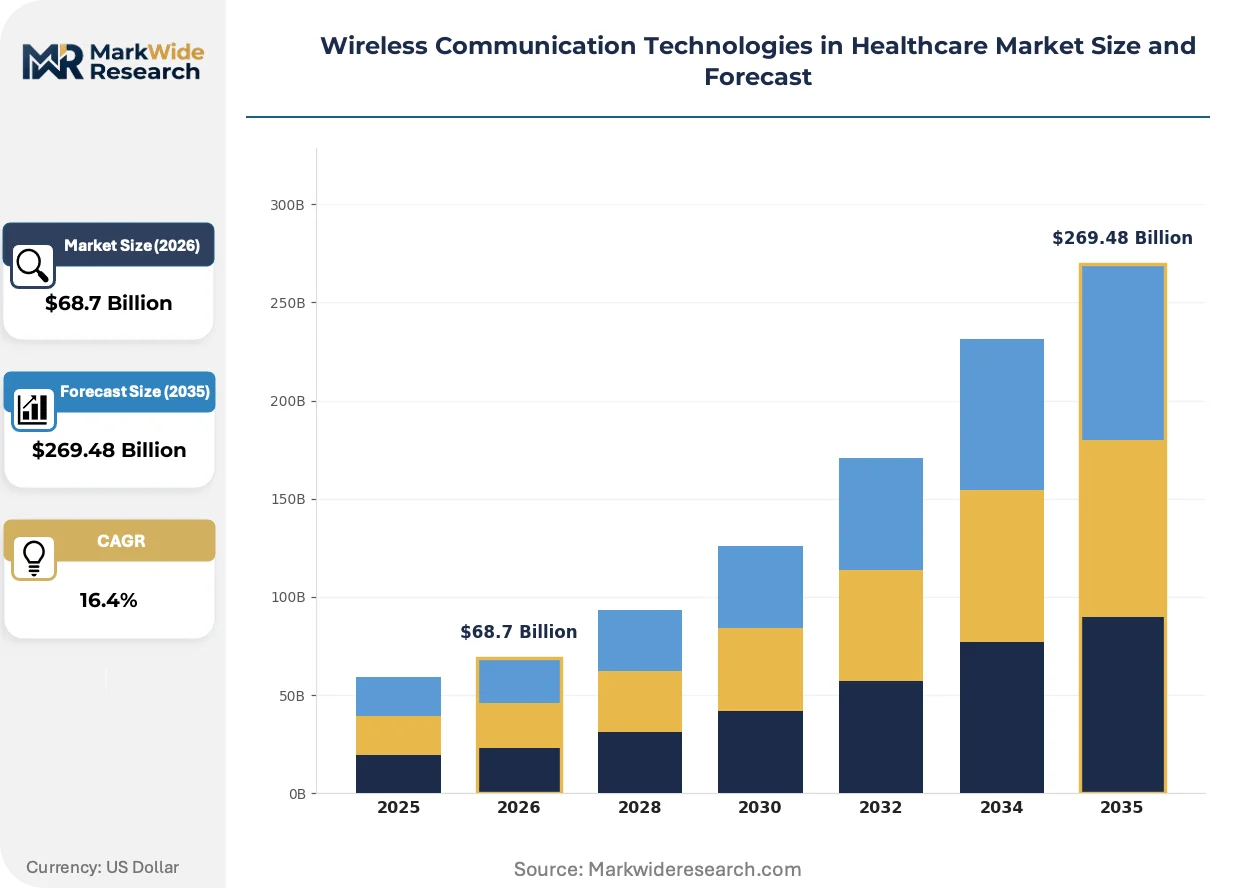
| Market Size in 2026 | $68.7 Billion |
| Market Size in 2035 | $269.48 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, Zigbee, RFID Application: Remote Monitoring, Telemedicine, Wearable Devices, Smart Implants End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Service Type: Consulting, System Integration, Maintenance, Support |
| Companies Covered | GE Healthcare, Philips Healthcare, Medtronic, Siemens Healthineers, Cisco Systems, Qualcomm Technologies, AT&T, IBM, Verizon Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Communication Technologies in Healthcare Market Strategic Shifts
Wireless medical connectivity is undergoing protocol diversification as single-standard deployments prove insufficient for mixed-criticality environments where life-safety telemetry coexists with administrative data traffic.
Ultra-wideband positioning is expanding into operating rooms and intensive care units where centimeter-level asset tracking reduces nurse search time for mobile equipment. Academic medical centers in Germany and the United States are piloting these systems at scale. The technology is expanding into revenue-cycle applications by automating procedure documentation through precise location correlation.
REACH restrictions on persistent organic pollutants are forcing redesign of antenna substrates and encapsulation materials for implantable wireless devices. European manufacturers are accelerating substitution of halogenated compounds with ceramic-filled polymers that maintain dielectric performance. Cardiac rhythm management devices face the steepest reformulation timelines due to long regulatory recertification cycles.
Health system procurement departments are consolidating vendor panels and mandating open API architectures that prevent proprietary wireless protocol lock-in. Integrated delivery networks in the United States are replacing point-solution contracts with enterprise connectivity frameworks. This consolidation is most visible in Texas and Florida health systems where multi-hospital standardization reduces training and interoperability testing overhead.
Wireless Communication Technologies in Healthcare Market Segmentation
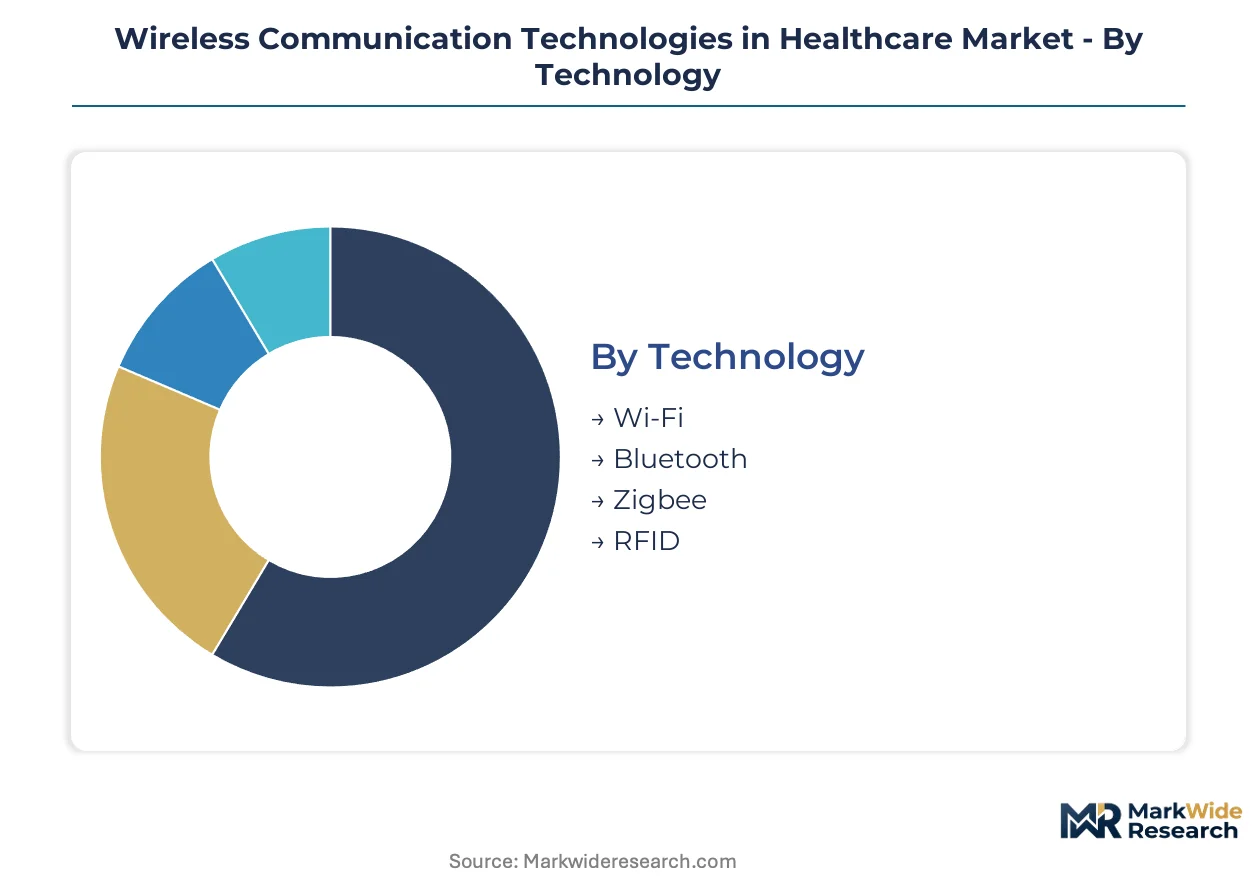
Wireless healthcare markets fragment across protocol layers, clinical settings, and service delivery models. Buyers prioritize latency tolerance, power budgets, and regulatory clearance pathways when selecting connectivity solutions. Segmentation reveals where procurement concentrates versus where emerging demand is reshaping vendor priorities.
Technology:
Procurement teams weigh spectral efficiency against device battery life and institutional infrastructure compatibility when selecting wireless protocols.
- Wi-Fi:Operates in 2.4 GHz and 5 GHz bands with throughput exceeding 1 Gbps under Wi-Fi 6E implementations. Hospital systems in the United States deploy this for real-time imaging transmission and EMR synchronization, though dense RF environments require careful channel planning to avoid interference.
- Bluetooth:Low-energy variants draw under 15 mA during active transmission, enabling multi-day wearable operation. Demand concentrates in continuous glucose monitors and cardiac event recorders where patients require unobtrusive form factors.
- Zigbee:Mesh networking architecture supports thousands of nodes per gateway with sub-50 mW power draw.
- RFID:Passive ultrahigh-frequency tags operate without onboard power for asset tracking and patient identification workflows.
Volume sits with Wi-Fi; growth tilts toward Zigbee.
Application:
Reimbursement codes and clinical workflow integration determine which use cases attract capital investment versus pilot funding.
- Remote Monitoring:Cellular-enabled devices transmit physiologic data through cloud platforms to centralized nursing stations. Medicare reimbursement for remote patient monitoring in the United States has converted this from experimental deployment to standard-of-care infrastructure for chronic heart failure and diabetes management.
- Telemedicine:Synchronous video consultation platforms require 150 ms maximum latency for acceptable clinician-patient interaction. Rural health systems in Texas and Florida expanded deployment following CMS parity mandates for virtual visit reimbursement.
- Wearable Devices:Patch-style biosensors measure single-lead ECG, SpO2, and accelerometry for ambulatory diagnostic capture.
- Smart Implants:Orthopedic and cardiac devices with embedded transceivers enable post-operative surveillance without clinic visits.
Telemedicine captures current procurement volume; remote monitoring shows the steepest expansion trajectory.
End User:
Capital availability and technical staffing depth create distinct purchasing patterns across care delivery settings.
- Hospitals:Enterprise wireless infrastructure investments exceed $2 million per 500-bed facility for private 5G and Wi-Fi 6E upgrades. Academic medical centers in Germany and the United States lead deployment of ultra-wideband positioning for surgical asset tracking.
- Home Care:CMS Hospital at Home waiver programs in the United States are driving demand for cellular-enabled vital sign monitors that operate outside institutional network perimeters.
- Clinics:Federally qualified health centers prioritize low-cost Bluetooth peripherals for point-of-care documentation.
- Rehabilitation Centers:Wireless motion capture systems track recovery metrics for stroke and orthopedic patients.
Hospitals dominate absolute spending; home care is gaining share fastest.
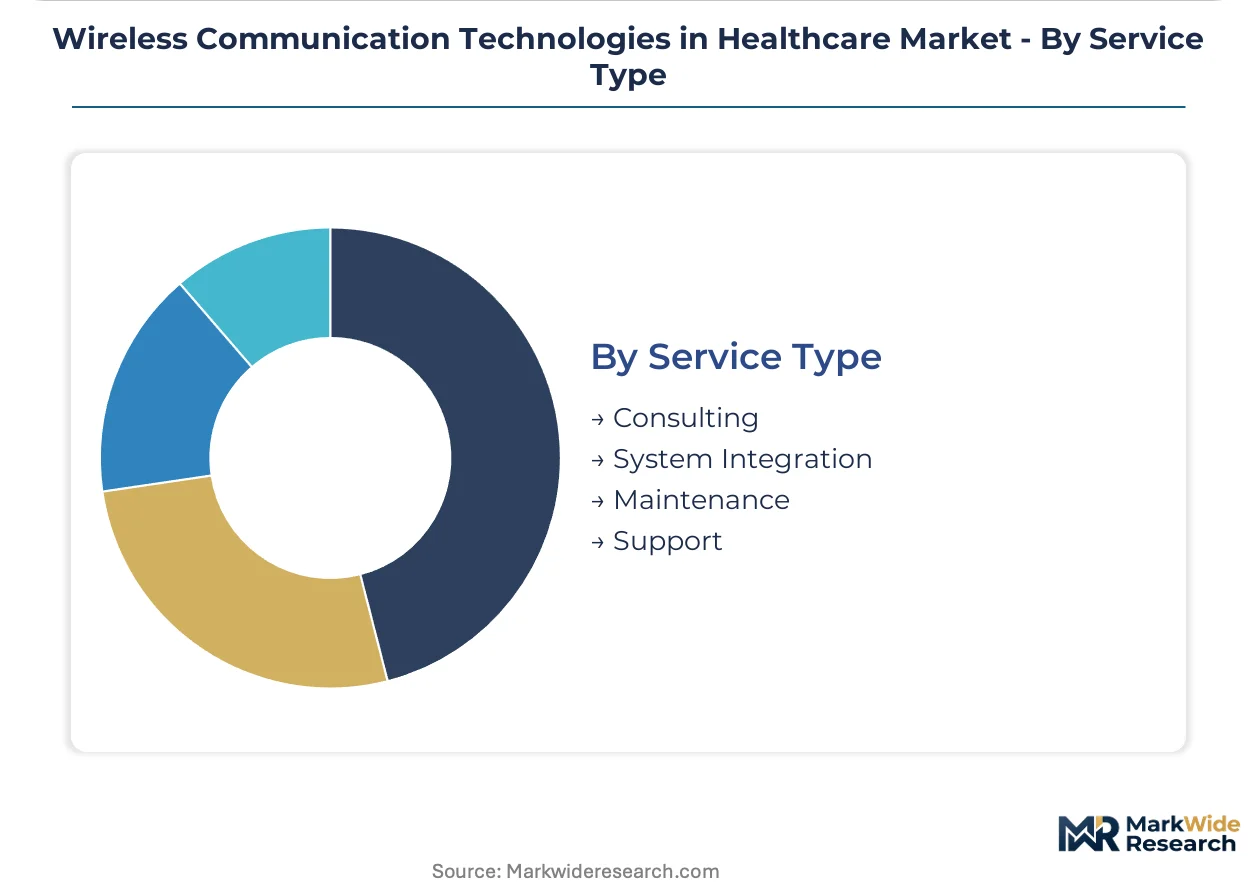
Service Type:
Internal IT capacity gaps determine whether healthcare organizations self-integrate wireless endpoints or outsource deployment complexity.
- System Integration:Merging wireless device streams with legacy EMR architectures requires HL7 FHIR expertise and custom middleware development. Hospital systems pay premium rates for vendors who assume interoperability risk.
- Consulting:RF site surveys and spectrum analysis guide infrastructure planning for dense clinical environments.
- Maintenance:Firmware update management and security patch distribution for deployed device fleets.
- Support:Help desk services for clinician connectivity troubleshooting and patient device onboarding.
System integration commands the largest contract values; consulting shows the strongest pricing momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital system digitization and reimbursement alignment for connected care concentrate procurement volume in the United States, while regulatory harmonization efforts in Europe and infrastructure buildouts in Asia-Pacific reshape competitive entry patterns.
United States
Federal reimbursement codes from CMS now cover remote patient monitoring and Hospital at Home programs, converting wireless connectivity from capital expenditure to reimbursed standard of care. The FDA's cybersecurity premarket guidance for wireless medical devices accelerates clearance timelines for security-by-architecture designs. Texas and Florida health systems lead multi-hospital standardization efforts that reduce training overhead through enterprise connectivity frameworks.
Germany
Academic medical centers in Berlin and Munich pilot ultra-wideband positioning systems for surgical asset tracking and automated procedure documentation. The EU Medical Device Regulation's expanded software classification creates first-mover advantage for wireless platforms with pre-certified cybersecurity documentation. Bavaria's medical technology cluster concentrates development of private 5G infrastructure for deterministic low-latency surgical applications.
China
NMPA regulatory pathways for AI-enabled wireless diagnostics reshape product certification timelines as domestic manufacturers accelerate edge-computing medical device development. The MIIT spectrum allocation for healthcare-specific bands supports hospital system deployment of cellular-enabled remote monitoring outside tier-one cities. Shanghai and Shenzhen anchor manufacturing ecosystems for low-power wide-area network components used in chronic disease management wearables.
Japan
METI funding programs for aging-in-place infrastructure drive demand for cellular-enabled vital sign monitors in rural prefectures with limited institutional network coverage. PMDA guidance on software-as-a-medical-device clarifies clearance pathways for wireless diagnostic platforms with on-device machine learning. The Kansai region's medical device manufacturers focus on ultra-low power Zigbee implementations for implantable cardiac monitors.
United Kingdom
NHS England's procurement frameworks mandate open API architectures that prevent proprietary wireless protocol lock-in across integrated care systems. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with FDA cybersecurity expectations to maintain transatlantic market access. London's health technology cluster concentrates system integration vendors that merge legacy electronic health records with new wireless endpoints.
Wireless Communication Technologies in Healthcare Market Competitive Environment
Strategic partnerships dominate the current landscape as infrastructure vendors and medical device manufacturers merge complementary capabilities. The market structures around three tiers: diversified healthcare conglomerates with integrated diagnostic-to-connectivity platforms, specialized wireless component suppliers with medical-grade certification expertise, and telecommunications carriers with private network deployment capabilities. Two competitive moves define positioning: technology licensing agreements that accelerate regulatory clearance for new entrants, and backward integration into radio-frequency component supply to reduce exposure to semiconductor concentration risk.
Within the diversified healthcare technology tier, GE Healthcare and Philips Healthcare exemplify integrated platform strategies that reduce interoperability friction through captive connectivity architectures. Qualcomm Technologies anchors the specialized component tier with medical-grade wearable baseband supply. These three companies occupy positions that span the value chain from semiconductor fabrication through hospital system integration, representing distinct archetypes for competitive positioning in reimbursement-aligned markets.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Medtronic |
| Siemens Healthineers |
| Cisco Systems |
| Qualcomm Technologies |
| AT&T |
| IBM |
| Verizon Communications |
| Others |
Value Chain & Pricing Dynamics
Wi-Fi 6E and private 5G infrastructure rollouts across United States hospital systems are compressing hardware procurement cycles while elevating service-bundling premiums, concentrating margin capture among vendors with captive integration capabilities. This technology transition simultaneously raises capital barriers for new entrants and rewards incumbents who can amortize certification costs across multi-protocol product portfolios.
Pricing Analysis
Extended warranty and cybersecurity update bundling separates premium-tier contracts from unbundled hardware transactions in hospital procurement. Pricing stratifies across FDA-cleared premium platforms, CE-marked standard devices, and economy-tier consumer-grade peripherals with limited clinical validation. Cost compression in the economy tier is intensifying because home care providers face reimbursement caps under CMS remote monitoring codes. Federally qualified health centers exhibit the highest price sensitivity, while academic medical centers prioritize interoperability certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced radio-frequency baseband fabrication, exposing medical-grade wearable manufacturers to geopolitical disruption. Component sourcing draws from Chinese substrate suppliers for antenna materials, Japanese ceramic encapsulation specialists, and German precision connector manufacturers. Tariff exposure on semiconductor imports from Taiwan threatens margin stability for mid-tier device makers. Distribution runs through healthcare group purchasing organizations that aggregate demand across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
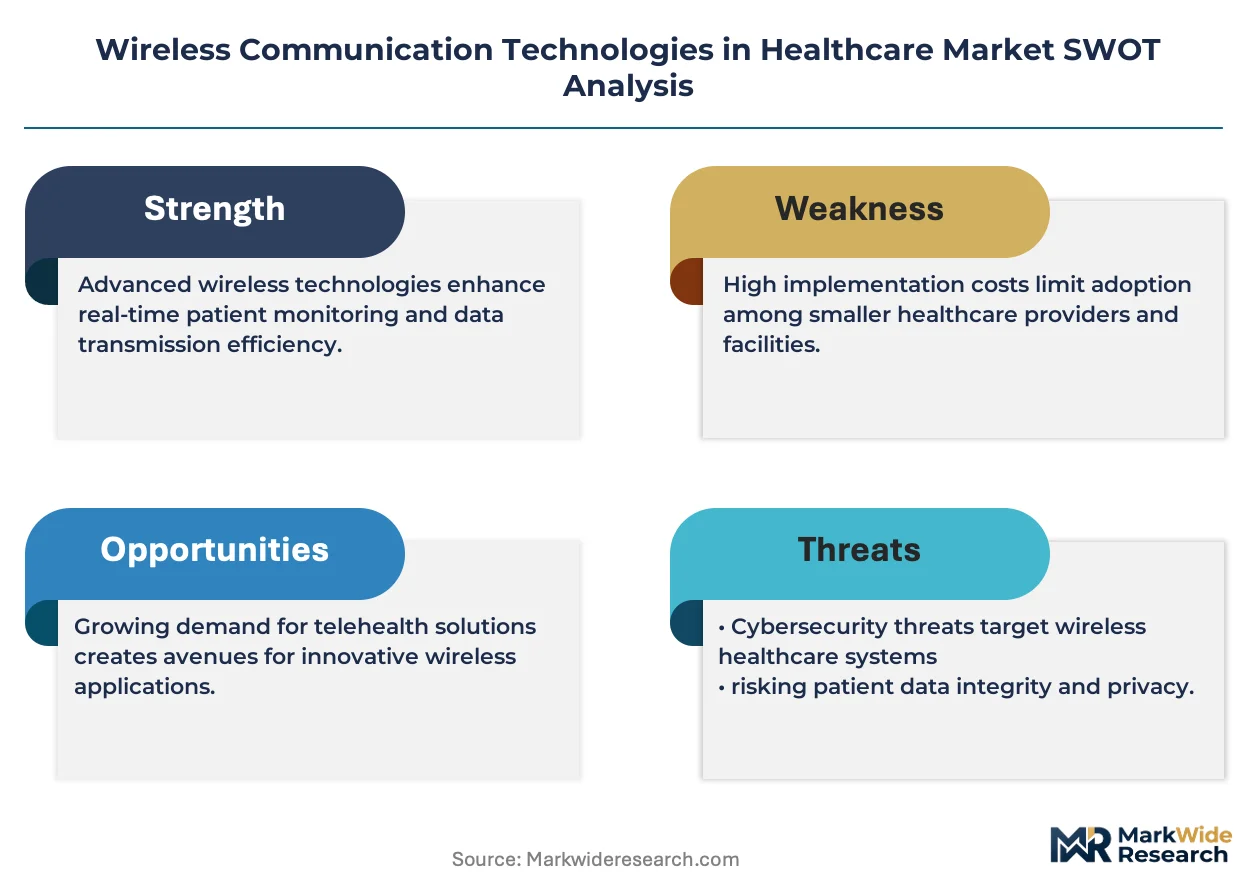
The wireless medical connectivity sector is becoming a vertical-integration race as vendors pursue backward control over radio-frequency component supply to escape semiconductor concentration risk.
For Market Incumbents: Deepen captive supply agreements with Taiwanese foundries to secure fabrication slots for medical-grade baseband chips, insulating against capacity allocation shifts toward consumer electronics. Fortify cybersecurity documentation libraries to accelerate FDA premarket submissions for AI-enabled diagnostics, preempting emerging entrants with security-by-architecture designs.
For New Entrants and Emerging Players: Enter via CMS Hospital at Home waiver programs in Texas and Florida, where reimbursement alignment creates immediate revenue visibility without enterprise sales cycles. Target home care agencies with cellular-enabled vital sign monitors that bypass hospital IT procurement committees. Pursue white-label partnerships with established system integrators to bypass interoperability certification barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified healthcare conglomerates seeking wireless connectivity capabilities. Long-term viability hinges on regulatory moat depth rather than technology differentiation alone. Acquisition targets should demonstrate pre-certified cybersecurity documentation under FDA or MDR pathways. The signal to watch is FDA software-as-a-medical-device guidance evolution, which will either accelerate or complicate clearance timelines for AI-enabled diagnostics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Premarket Submission | Accelerates clearance timelines for devices designed with security-by-architecture under 2023-2024 guidance updates. |
| Private 5G Infrastructure Deployment | Enables deterministic low-latency surgical applications in Bavaria and Texas academic medical centers. |
| Hospital System Partnership | Locks in enterprise connectivity frameworks that reduce interoperability friction across multi-facility networks. |
| Software Companion Development | Extends hardware margins through recurring revenue streams for firmware updates and security patches. |
| Reimbursement Strategy Alignment | Converts remote monitoring from pilot expenditure to reimbursed standard of care under CMS billing codes. |
Study Parameters
Multi-period observation of FDA 510(k) submission volumes, CMS reimbursement code utilization, and hospital capital expenditure disclosures anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and connectivity platform executives. Secondary validation drew from FDA premarket notification databases, CMS Medicare claims data, hospital procurement registries, and FCC spectrum allocation filings. Bottom-up device shipment estimates triangulated against top-down health system IT spending surveys.
Segment-weighted modeling applied differential growth assumptions across Wi-Fi, Bluetooth, Zigbee, and cellular protocol layers, with separate trajectories for remote monitoring, telemedicine, wearable, and implantable applications. End-user splits between hospitals, home care, clinics, and rehabilitation centers incorporated capital availability and staffing depth variations. CAGRs were derived from logistic diffusion curves fitted to reimbursement policy inflection points and technology substitution patterns. Forecast inputs included semiconductor fabrication capacity projections and regulatory clearance pipeline velocities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA cybersecurity guidance revisions or Taiwan semiconductor supply disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Wigig Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Mesh Wifi System Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Multefire Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market