
 Global WLAN Market | 2026-2036
Global WLAN Market Size, Share, and Industry Trends Forecast 2026-2036
Global WLAN Market Foresight
Market Context
Wi-Fi Alliance certification cycles is rotating competitive advantage toward vendors with pre-certified silicon roadmaps. Cisco Systems leverages its enterprise channel density to sustain recurring controller revenue across Fortune 500 campuses. Huawei Technologies anchors Asia-Pacific supply through captive semiconductor fabrication and government-backed spectrum allocation. Juniper Networks competes on cloud-native management stacks that reduce on-premises hardware dependency.
Technical Definition and Segment Structure
Wireless LAN denotes a local area network using radio frequency transmission—typically 2.4 GHz, 5 GHz, or 6 GHz bands—instead of wired Ethernet cabling, with throughput specifications now exceeding 9.6 Gbps under Wi-Fi 7 PHY layer designs. Its primary purpose is untethered IP connectivity for high-density environments including factories, stadiums, and medical campuses. Access Points capture the dominant hardware margin pool as enterprises refresh toward Wi-Fi 6E and Wi-Fi 7 platforms with embedded IoT radios. Mesh Networking extends fastest in smart home and outdoor venue deployments where wired backhaul proves cost-prohibitive. Enterprise Networks remains the most mature application segment, though Educational Institutions show accelerated refresh cycles post-pandemic.
Regulatory Frame and Outlook
The FCC governs 6 GHz unlicensed access in the United States, while the EU AI Act and GDPR impose data governance obligations on WLAN analytics platforms processing user location data. China's MIIT allocates domestic spectrum bands through GB standards that diverge from IEEE 802.11be global specifications, fragmenting chipset design requirements. Stakeholders must monitor spectrum auction outcomes and cybersecurity labeling mandates as primary determinants of regional product viability and certification cost structures.
Market Dynamics
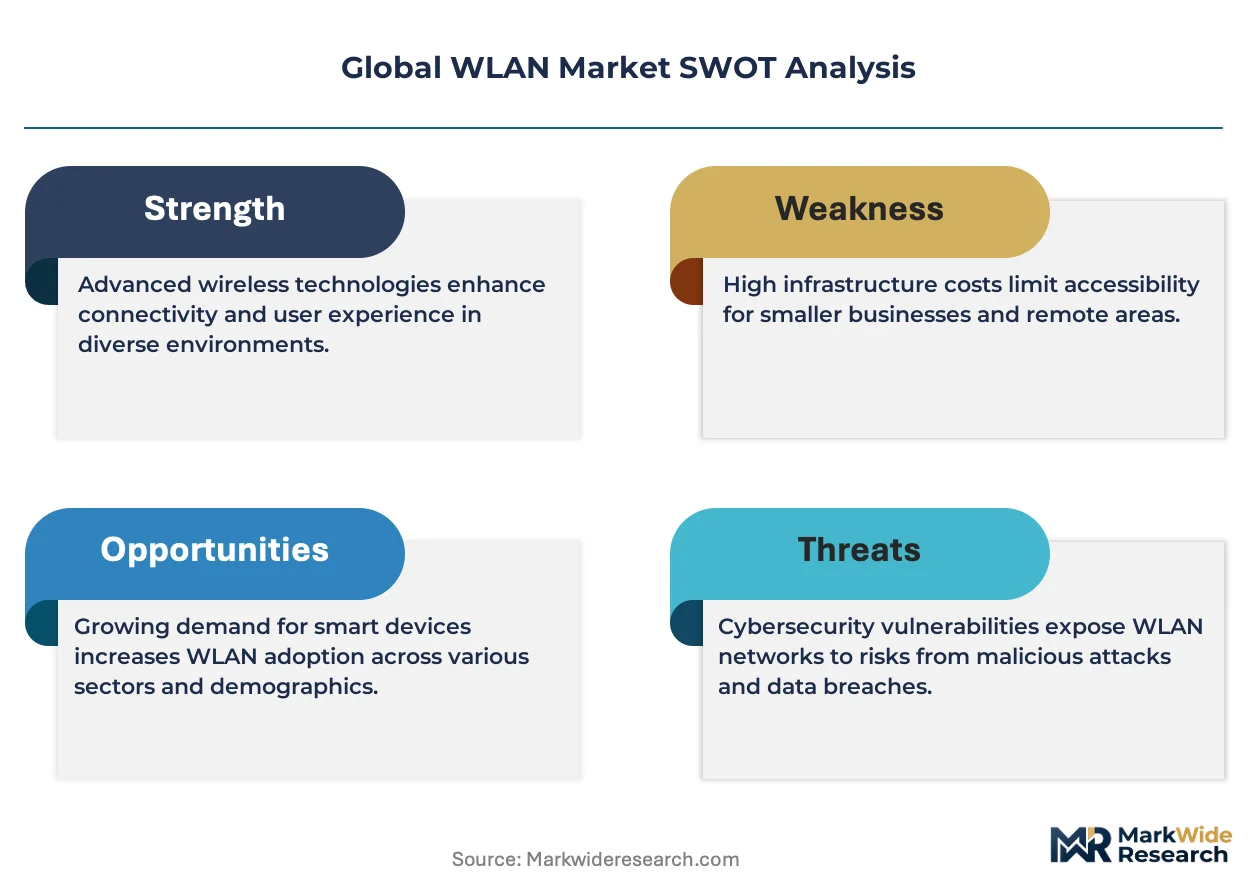
Wi-Fi 7 silicon roadmaps are compressing enterprise refresh cycles while spectrum fragmentation across regulatory jurisdictions forces dual-sku inventory strategies for access point vendors.
Growth Catalysts
- Industrial IoT densification:Factory automation in Germany, China, and India is driving multi-radio access point deployments that combine 6 GHz Wi-Fi with private 5G and BLE positioning.
- FCC 6 GHz expansion:The FCC's additional 1.2 GHz of unlicensed spectrum in the United States is unlocking greenfield campus builds and stadium retrofits previously blocked by congestion.
- EU cybersecurity labeling:The EU Cybersecurity Act's forthcoming WLAN certification scheme is creating replacement demand as enterprises pre-empt compliance deadlines with certified hardware.
Market Restraints
- Compound semiconductor supply:GaN and SiGe RF front-end components face concentrated sourcing from Taiwan and South Korean foundries, exposing lead times to geopolitical friction.
- MIIT spectrum divergence:China's GB 15629.11 standards for 6 GHz channelization force chipset redesigns that fragment economies of scale for global silicon vendors.
- Passive optical LAN substitution:Fiber-to-the-desk deployments in Japanese and South Korean commercial real estate are displacing Wi-Fi for stationary high-bandwidth endpoints.
Strategic Opportunities
- Private 5G convergence:Enterprises in Brazil and Saudi Arabia are piloting unified Wi-Fi 7 and private 5G cores that collapse separate radio management stacks into single policy engines.
- Healthcare RTLS mandate:The FDA's Unique Device Identification enforcement is accelerating Wi-Fi-based asset tracking in US medical campuses, opening attach-rate opportunities for BLE and UWB-integrated access points.
- Cloud-managed SMB channel:MSP-focused subscription models are penetrating underpenetrated mid-market verticals in Mexico and Indonesia where on-premises controller expertise remains scarce.
Industry Challenges
- RF engineer scarcity:The transition to 6 GHz and 320 MHz channel planning requires expertise in coexistence algorithms and interference mitigation that outpaces university pipeline output.
- Legacy WPA2 integration:Medical devices and industrial controllers with decade-old security stacks demand bridge architectures that complicate zero-trust segmentation rollouts.
- Wi-Fi Alliance certification queuing:Pre-certification testing backlogs for Wi-Fi 7 and Wi-Fi 6E are extending product launch windows by 4-6 months for second-tier vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global WLAN Market |
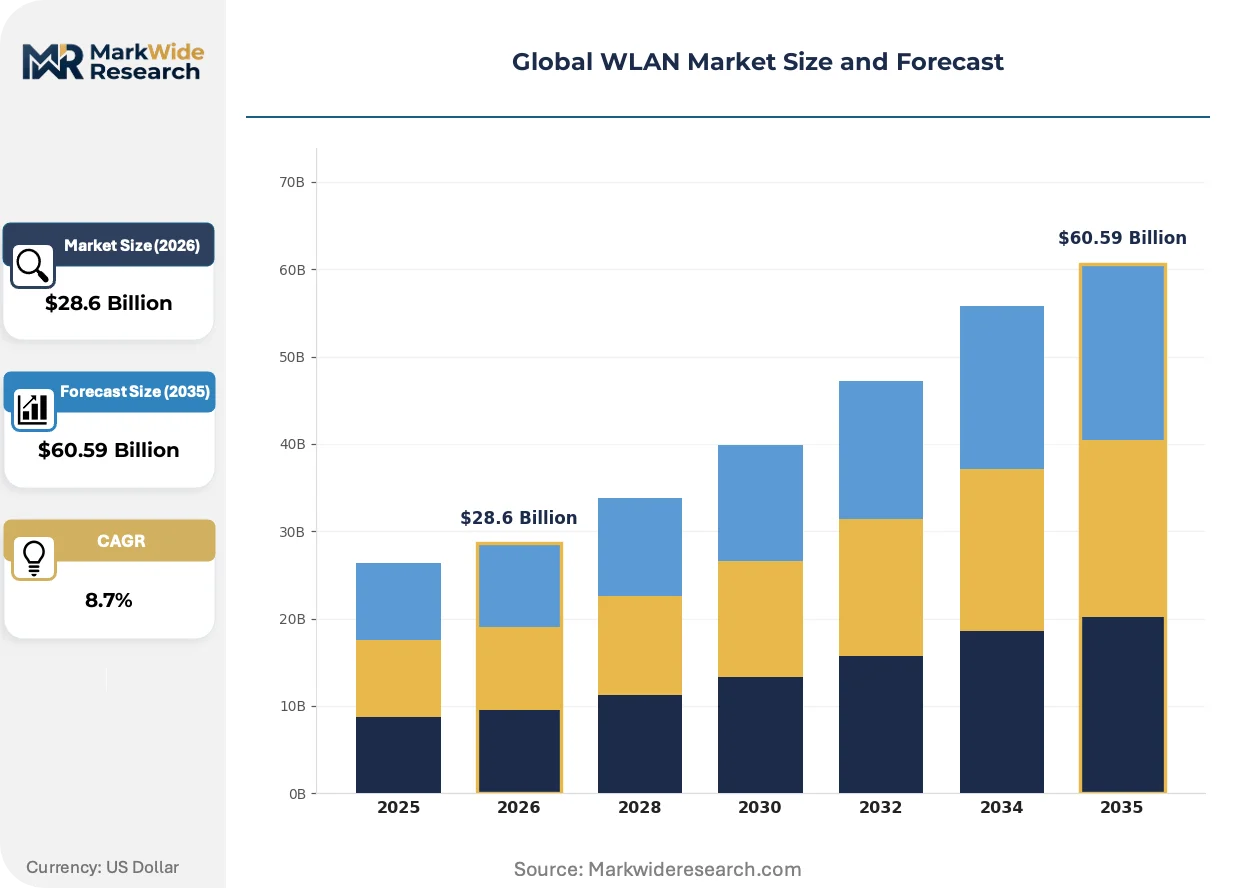
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
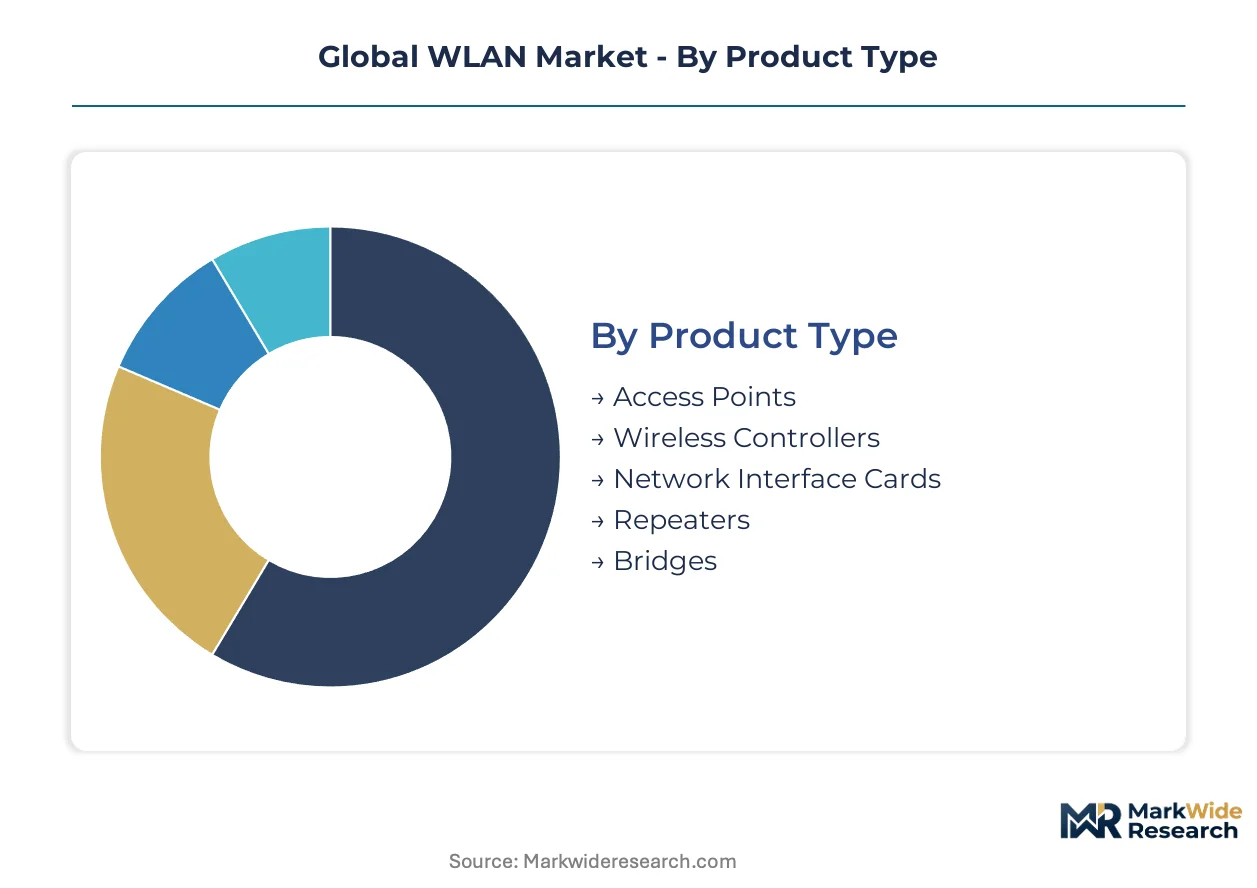
| Segmentation | Product Type: Access Points, Wireless Controllers, Network Interface Cards, Repeaters, Bridges Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7, Mesh Networking Application: Enterprise Networks, Educational Institutions, Public Venues, Hospitality, Smart Homes End User: Small & Medium Enterprises, Large Corporations, Telecom Operators, Government Agencies |
| Companies Covered | Juniper Networks, CommScope, Cisco Systems, Fortinet, Dell Technologies, Hewlett Packard Enterprise, Extreme Networks, Ubiquiti Inc., Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global WLAN Market Shifts & Advancements
Radio integration patterns are collapsing discrete component boundaries while regulatory bandwidth releases and procurement model fragmentation are rewriting vendor-customer relationships.
Multi-protocol system-on-chip designs are consolidating Wi-Fi 7, Bluetooth 5.4, and 802.15.4/Zigbee radios onto single die architectures. Medical device manufacturers and smart building integrators in the United States and Netherlands are adopting these consolidated platforms to reduce BOM complexity and PCB footprint. The structural consequence is that discrete radio module suppliers are miniaturizing their addressable market as silicon vendors capture attach-rate value previously distributed across separate chipsets.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on WLAN analytics platforms that process user location and behavior data. Vendors selling into German and French enterprise campuses must now document automated decision-making logic for heat-mapping and presence-detection features. This is compressing R&D timelines as engineering teams rearchitect cloud inference pipelines to satisfy documentation and audit obligations before Q3 certification deadlines.
Enterprise buyers are unbundling hardware procurement from management software subscriptions, reversing the bundled controller-access point model that dominated the 2010s. Fortune 500 IT departments in the United States are negotiating separate SaaS contracts for cloud-native network management while sourcing access points through distribution on spot-buy terms. This is most visible in financial services verticals where CapEx/OpEx flexibility outweighs single-vendor integration convenience.
Global WLAN Market Segmentation
WLAN procurement patterns diverge sharply across deployment scales and spectrum regimes. Regulatory certification timelines and radio integration complexity create asymmetric margin pools that reward vendors with pre-certified silicon roadmaps.
Product Type:
FCC 6 GHz expansion and EU cybersecurity labeling mandates are fragmenting hardware procurement strategies across enterprise tiers.
- Access Points:Multi-radio units combining 6 GHz Wi-Fi with BLE and Zigbee radios dominate campus refresh cycles. Fortune 500 IT departments in the United States are unbundling hardware from controller software, creating spot-buy dynamics for high-density indoor venues.
- Wireless Controllers:Cloud-native management stacks are displacing on-premises appliances as enterprises prioritize OpEx flexibility. Financial services verticals in Germany and France are negotiating separate SaaS contracts while sourcing access points through distribution.
- Network Interface Cards:Embedded modules for industrial IoT gateways face GB standards divergence in China.
- Repeaters:Consumer-grade units are losing share to mesh node architectures in smart home deployments.
- Bridges:Point-to-point 60 GHz links serve outdoor venue backhaul where fiber trenching proves cost-prohibitive.
Access Points handles the majority of throughput; Mesh Networking is the fastest mover on share.
Technology:
Silicon vendor roadmaps and spectrum allocation timelines are compressing intergenerational refresh windows.
- Wi-Fi 7:320 MHz channel bonding and 4K-QAM modulation push theoretical PHY rates beyond 9.6 Gbps. Early enterprise pilots in Saudi Arabia and Brazil are testing unified policy engines that collapse Wi-Fi 7 and private 5G management stacks.
- Wi-Fi 6E:6 GHz spectrum access unlocked greenfield stadium builds and campus retrofits previously blocked by congestion. FCC unlicensed expansion in the United States is accelerating procurement timelines for North American enterprises.
- Wi-Fi 6:Mass-market saturation is pushing margin compression into enterprise bulk contracts.
- Wi-Fi 5:Legacy WPA2 integration burdens persist in medical device and industrial controller deployments.
- Mesh Networking:Self-healing node architectures are displacing repeaters in residential and outdoor venue segments where wired backhaul remains uneconomical.
Wi-Fi 7 commands the premium tier; Wi-Fi 6E is expanding most quickly among enterprise refreshes.
Application:
Post-pandemic occupancy patterns and RTLS mandates are rewiring vertical-specific procurement priorities.
- Enterprise Networks:Zero-trust segmentation rollouts demand bridge architectures for decade-old security stacks. FDA Unique Device Identification enforcement in US medical campuses is accelerating Wi-Fi-based asset tracking attach rates.
- Educational Institutions:Accelerated refresh cycles following remote learning infrastructure builds are concentrating demand in India and China. K-12 and university campuses are prioritizing cloud-managed stacks to compensate for scarce on-premises controller expertise.
- Public Venues:Stadium retrofits and transit hub deployments leverage 6 GHz spectrum for high-density spectator connectivity.
- Hospitality:Boutique hotel chains in Indonesia and Mexico are adopting MSP-focused subscription models.
- Smart Homes:Consolidated system-on-chip designs are reducing BOM complexity for device manufacturers in the Netherlands and United States.
Enterprise Networks dominates installed base value; Educational Institutions is climbing the fastest on procurement velocity.
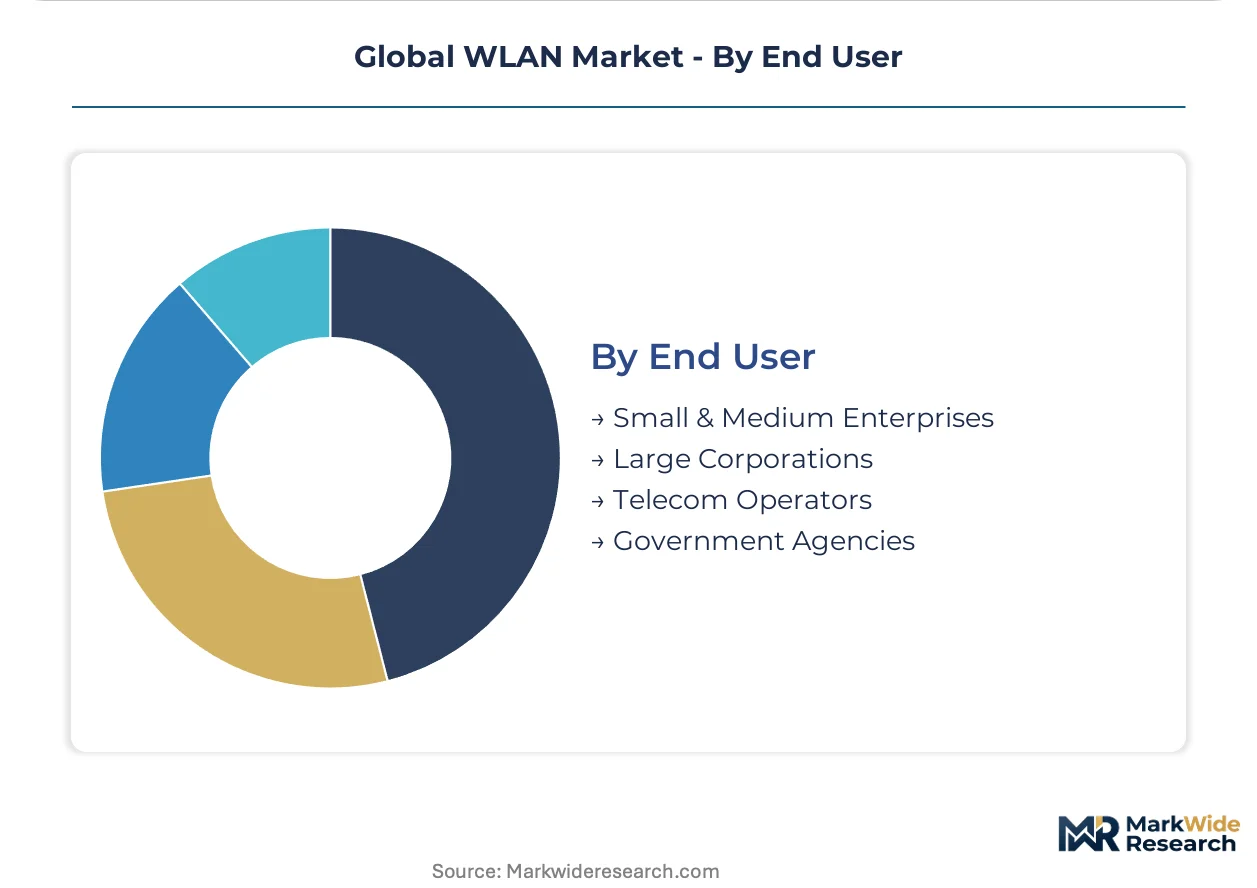
End User:
Scale-dependent capabilities and regulatory compliance burdens are stratifying vendor engagement models.
- Large Corporations:Dedicated RF engineering teams manage 320 MHz channel planning and coexistence algorithms. Wi-Fi Alliance certification queuing extends product launch windows, favoring incumbent vendors with pre-certified silicon relationships.
- Small & Medium Enterprises:Cloud-managed SMB channels penetrate underpenetrated mid-market verticals where controller expertise remains scarce. MSP subscription models in Mexico and Indonesia are collapsing upfront CapEx barriers.
- Telecom Operators:Private 5G convergence pilots require unified radio management policy engines.
- Government Agencies:EU Cybersecurity Act certification schemes are creating replacement demand as compliance deadlines approach.
Large Corporations absorb the bulk of premium-tier shipments; Small & Medium Enterprises is gaining share fastest through SaaS displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum expansion and EU cybersecurity mandates are accelerating hardware refresh cycles across enterprise campuses. National regulators are fragmenting certification requirements, forcing dual-sku inventory strategies for access point vendors.
United States
Industrial IoT densification in manufacturing hubs drives multi-radio access point deployments. The FCC governs 6 GHz unlicensed access with additional spectrum releases. Dallas-Fort Worth and Austin tech corridors host enterprise pilot programs testing Wi-Fi 7 and private 5G convergence.
Germany
Factory automation in automotive and machinery sectors demands high-density wireless infrastructure. The EU Cybersecurity Act's forthcoming WLAN certification scheme creates replacement demand. Munich and Stuttgart industrial clusters are accelerating campus refreshes to pre-empt compliance deadlines.
China
Smart building integration and educational institution rollouts concentrate procurement volume. MIIT allocates domestic spectrum bands through GB standards diverging from IEEE specifications. Shenzhen and Shanghai semiconductor corridors are adapting chipset designs for fragmented channelization requirements.
India
Educational institution infrastructure builds and mid-market enterprise expansion drive cloud-managed stack adoption. TRAI spectrum policies influence unlicensed band availability for commercial deployments. Bangalore and Hyderabad tech parks are witnessing accelerated refresh cycles post-pandemic.
Saudi Arabia
Smart city initiatives and stadium infrastructure projects unlock greenfield deployment opportunities. The national regulator oversees spectrum allocation for private network pilots. Riyadh and Jeddah urban development zones are testing unified Wi-Fi 7 and private 5G policy engines.
Global WLAN Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native management and silicon integration vectors. The vendor base stratifies into three tiers: incumbents with pre-certified silicon roadmaps, cloud-native challengers unbundling hardware from software, and regional specialists serving compliance-heavy procurement. Dominant competitive moves include strategic partnerships for multi-protocol radio integration and geographic expansion through MSP-focused subscription channels.
Within the enterprise infrastructure tier, Cisco Systems and Hewlett Packard Enterprise exemplify incumbents with channel density advantages. Juniper Networks occupies a position among cloud-native challengers reducing on-premises hardware dependency. Huawei Technologies anchors the Asia-Pacific supply archetype through government-backed spectrum relationships.
| Leading Market Players |
|---|
| Juniper Networks |
| CommScope |
| Cisco Systems |
| Fortinet |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Extreme Networks |
| Ubiquiti Inc. |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day lead times for GaN RF front-end components concentrate pricing power among Taiwanese and South Korean foundries, while dual-sku inventory strategies for MIIT-compliant variants inflate working capital requirements for access point vendors serving fragmented regulatory jurisdictions.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with Wi-Fi Alliance pre-certified silicon commanding substantial premiums over uncertified alternatives. Pricing stratifies across Wi-Fi 7, Wi-Fi 6E, and legacy Wi-Fi 6 tiers based on spectrum band support and embedded IoT radio configurations. Cost compression in Wi-Fi 6 mass-market contracts is intensifying because enterprise bulk procurement concentrates volume among Fortune 500 buyers. Small and medium enterprises exhibit highest price sensitivity, driven by MSP subscription model penetration, while large corporations absorb premium-tier shipments with limited negotiation leverage on pre-certified roadmaps.
Supply Chain Analysis
Extended certification queuing at Wi-Fi Alliance testing facilities has stretched finished goods inventory cycles, forcing vendors to pre-position dual-sku stocks ahead of regional regulatory approvals. Manufacturing concentrates in Taiwan, South Korea, and China, with compound semiconductor fabrication for GaN and SiGe components drawing from concentrated foundry capacity. Raw material dependencies span gallium nitride substrates, silicon germanium wafers, and 6 GHz-compliant RF filters. Single-source vulnerability in Taiwanese foundry capacity represents the dominant structural risk. Distribution runs through enterprise channel partners and MSP-focused subscription platforms for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FCC's 1.2 GHz spectrum expansion and Wi-Fi 7 silicon roadmaps constitute a dual inflection disrupting procurement patterns across enterprise campuses, compressing refresh cycles while fragmenting certification requirements.
For Market Incumbents: Compound channel density advantages through pre-certified silicon partnerships that lock out second-tier vendors facing Wi-Fi Alliance certification backlogs. Deepen captive semiconductor relationships with Taiwanese foundries to secure GaN RF front-end allocation against geopolitical friction. Prioritize cloud-native management stack development as enterprise buyers unbundle hardware from software subscriptions. For New Entrants and Emerging Players: EU Cybersecurity Act fast-track certification offers entry into German and French enterprise campuses ahead of compliance deadlines. Target cloud-managed SMB channels in Mexico and Indonesia where on-premises controller expertise remains scarce and MSP subscription models collapse upfront CapEx barriers. Pursue attach-rate opportunities in healthcare RTLS through BLE and UWB-integrated access point designs. For Investors and Strategic Acquirers: Long-term, this sits as a connectivity infrastructure play because industrial IoT densification and private 5G convergence create durable demand for multi-radio platforms. Acquisition targets should display pre-certified silicon roadmaps and cloud-native management capabilities. The signal to watch is FCC spectrum auction outcomes and EU cybersecurity labeling mandate timelines as inflection indicators for regional product viability.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Silicon Roadmap Acceleration | Compresses enterprise refresh cycles while favoring vendors with pre-certified IEEE 802.11be platforms. |
| Cloud-Native Management Stack Development | Captures unbundled software subscriptions as Fortune 500 IT departments separate SaaS from hardware procurement. |
| Multi-Protocol Radio Integration | Consolidates Wi-Fi 7, Bluetooth 5.4, and Zigbee onto single die architectures to reduce BOM complexity for medical device manufacturers. |
| EU Cybersecurity Certification Pre-Positioning | Creates replacement demand in German automotive and machinery clusters ahead of forthcoming compliance deadlines. |
| Private 5G Convergence Pilot Investment | Enables unified policy engines in Saudi Arabian and Brazilian enterprise trials collapsing separate radio management stacks. |
Research Methodology
A spread of perspectives from enterprise IT procurement officers, RF engineering directors, semiconductor foundry planners, and MSP channel managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC spectrum allocation records, Wi-Fi Alliance certification databases, EU Cybersecurity Act documentation, and MIIT GB standard filings. Bottom-up triangulation across access point shipment data and top-down reconciliation against enterprise CapEx disclosures anchored volume estimates.
Segmentation dimensions modeled include product type, technology generation, application vertical, end-user scale, and regional regulatory cluster across the projection horizon. CAGRs derived from weighted average of historical refresh cycle compression, spectrum release timelines, and industrial IoT attachment rates. Forecast inputs incorporate Wi-Fi 7 silicon availability curves and EU cybersecurity labeling enforcement schedules without specific year anchoring.
Decision-makers should treat outputs as directional under assumptions of sustained FCC spectrum expansion and stable Taiwan-South Korea foundry capacity; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Femtocell Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Global Wireless Data Communication Market