
 Europe Cloud Managed Networking Market | 2026-2036
Europe Cloud Managed Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cloud Managed Networking Market Intelligence
The Corporate Sustainability Reporting Directive (CSRD) is realigning the cost-of-entry calculus for cloud providers in Europe by mandating disclosures on IT infrastructure energy use. This forces a new level of transparency for data center operators. Cisco Systems leverages its extensive hardware portfolio to offer integrated solutions across the continent. Deutsche Telekom anchors its offering with deep network infrastructure and sovereignty-focused cloud services across Germany. French provider OVHcloud competes on data sovereignty and sustainable data center operations, appealing to GDPR-conscious clients.
Cloud managed networking refers to the centralized management of network infrastructure, including switches, access points, and routers, through a cloud-based platform. This approach simplifies network deployment and monitoring, often utilizing multi-tenant dashboards that provide real-time visibility into network performance and security events. Within service types, Network as a Service (NaaS) represents the fastest-growing category, shifting capital expenditure to an operational model. The retail and manufacturing end-user segments are mature adopters, while the education sector shows significant potential for expansion.
Compliance with the General Data Protection Regulation (GDPR) is a fundamental requirement, dictating data residency and processing standards for all providers operating within the EU. Concurrently, the upcoming EU AI Act and the existing CE marking framework for network hardware components shape both service offerings and the underlying equipment specifications. Vendor selection for enterprises will increasingly balance performance metrics against verifiable data sovereignty and sustainability credentials.
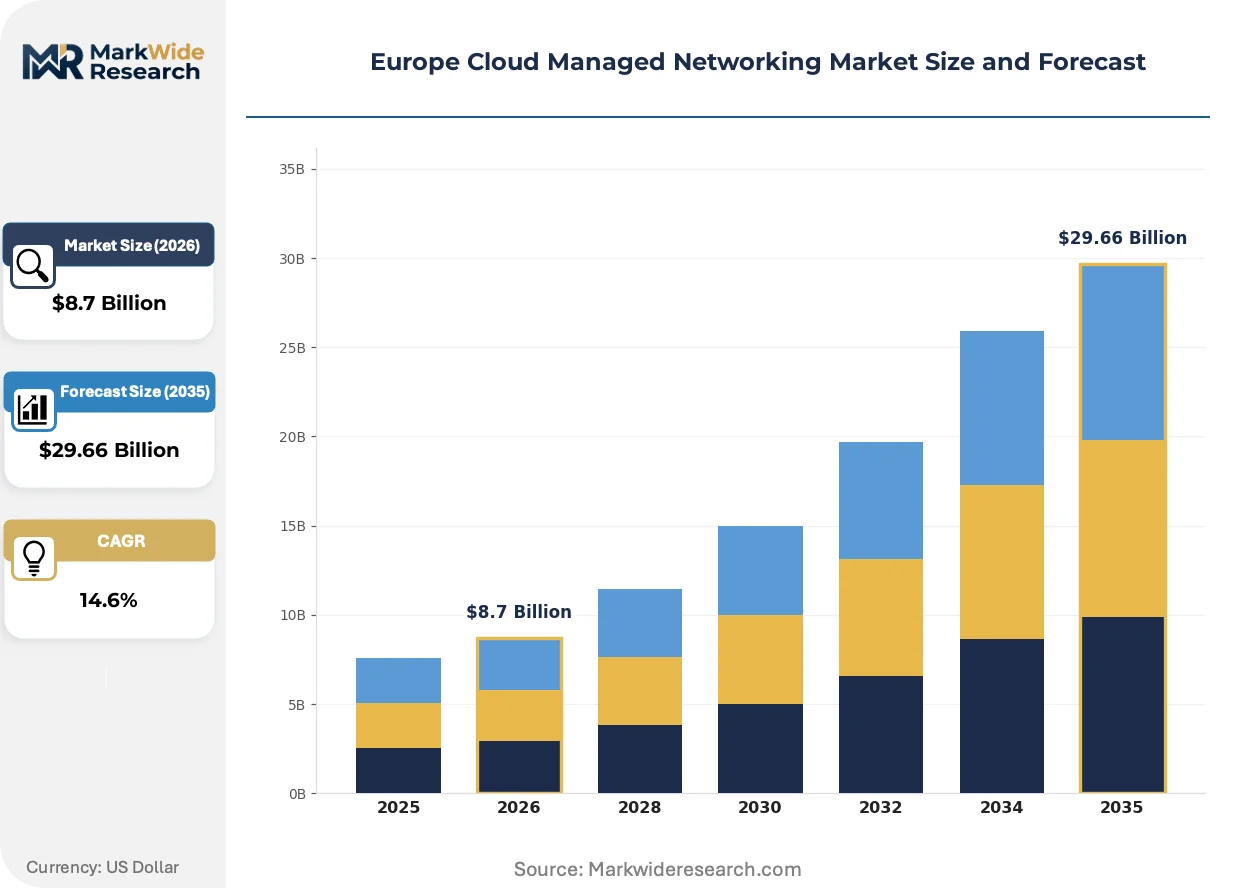
Market Dynamics
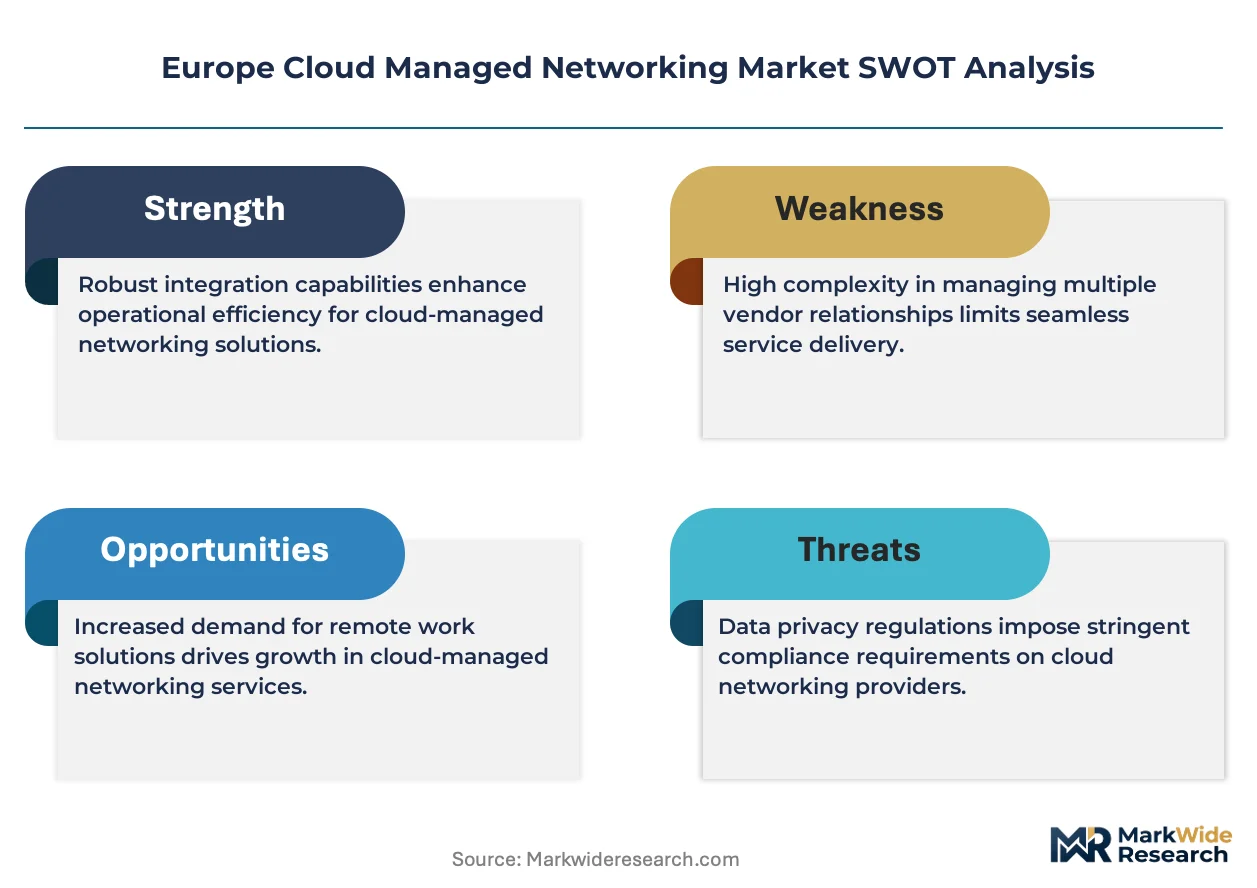
The imperative for data sovereignty across Europe is the central force shaping the cloud managed networking market. Compliance with GDPR and the upcoming EU AI Act dictates where data resides and how it is processed, influencing enterprise platform choices and provider architecture.
Growth Catalysts
- Healthcare Sector Modernization:The European healthcare industry's push to manage vast amounts of patient data and an increasing number of connected medical devices securely drives the adoption of centralized, compliant cloud networking solutions.
- Network as a Service (NaaS) Model:The shift from capital expenditure to an operational expenditure model through NaaS subscriptions lowers the barrier to entry for small and medium-sized enterprises seeking advanced networking capabilities without large upfront hardware investments.
- CSRD Mandates:The Corporate Sustainability Reporting Directive compels cloud providers and data centers to disclose IT infrastructure energy consumption, creating a competitive advantage for providers with verifiable green credentials and efficient operations.
Market Restraints
- Data Localization Complexities:Navigating the patchwork of national data protection laws in addition to the overarching GDPR framework creates significant compliance overhead and can limit the seamless delivery of services across EU member states.
- Legacy System Inertia:The high cost and operational disruption associated with migrating entrenched, on-premise network infrastructure deter many large enterprises, particularly in the industrial sector, from adopting cloud-managed alternatives.
- Performance Latency Concerns:For mission-critical applications in sectors like manufacturing and logistics, particularly within Germany's Mittelstand, concerns about potential network latency and reliability of off-premise management remain a significant barrier.
Strategic Opportunities
- Education Sector Upgrades:Universities and school systems across Europe represent an underpenetrated segment with a growing need to modernize campus-wide Wi-Fi and network security infrastructure, creating a substantial new market for cloud-managed platforms.
- AI-Powered Network Operations:Integrating artificial intelligence and machine learning into management dashboards to enable predictive analytics, automated threat detection, and self-healing networks offers a clear path for service differentiation and premium offerings.
- Eastern Europe Infrastructure Build-Out:As countries in Eastern Europe continue to invest heavily in digital transformation and infrastructure modernization, there is a significant opportunity for providers to establish a foothold in these developing markets.
Industry Challenges
- Specialized Skills Shortage:A persistent talent gap for network engineers who possess a combination of cloud architecture, cybersecurity, and automation skills hampers the ability of enterprises and service providers to deploy and manage advanced networking solutions.
- Interoperability with Legacy IT:Ensuring seamless integration and interoperability between modern cloud-managed networking platforms and a diverse array of existing, often proprietary, legacy systems is a major technical and operational hurdle for enterprise IT teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cloud Managed Networking Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Network as a Service End User: Retail, Manufacturing, Healthcare, Education Pricing Model: Subscription, Pay-as-You-Go, Tiered Pricing, Freemium |
| Companies Covered | Cisco Systems, Aruba (Hewlett Packard Enterprise), Extreme Networks, Deutsche Telekom, OVHcloud, Orange, NTT Europe, Capgemini, Atos, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cloud Managed Networking Market Strategic Shifts & Innovations
Automation and embedded security intelligence are becoming the defining features of cloud managed networking platforms. This evolution is a direct response to the dual pressures of increasing network complexity and a stringent European regulatory environment demanding greater operational transparency and data protection.
Secure Access Service Edge (SASE) architecture combines wide area networking with a suite of cloud-native security functions. European enterprises, especially those in finance and professional services with distributed workforces, are adopting this model to simplify IT infrastructure. SASE architecture is expanding into the core of enterprise network design, challenging the dominance of traditional hub-and-spoke models built on MPLS technology.
The EU's Corporate Sustainability Reporting Directive (CSRD) is formalizing environmental accountability. This regulation requires large companies to report on their energy consumption and carbon footprint, which extends to their digital infrastructure and cloud service usage. Consequently, data center operators and cloud providers in Europe are now under pressure to deliver verifiable sustainability reporting as a standard component of their service offerings.
A notable behavioral change is the move away from fixed, multi-year hardware refresh cycles toward more flexible, on-demand network service consumption. This trend disrupts the business model of traditional value-added resellers and favors providers that offer scalable, subscription-based NaaS platforms. This shift is particularly prominent within the European retail and hospitality sectors, which require network agility to adapt to seasonal demand fluctuations and pop-up locations.
Europe Cloud Managed Networking Market Segmentation
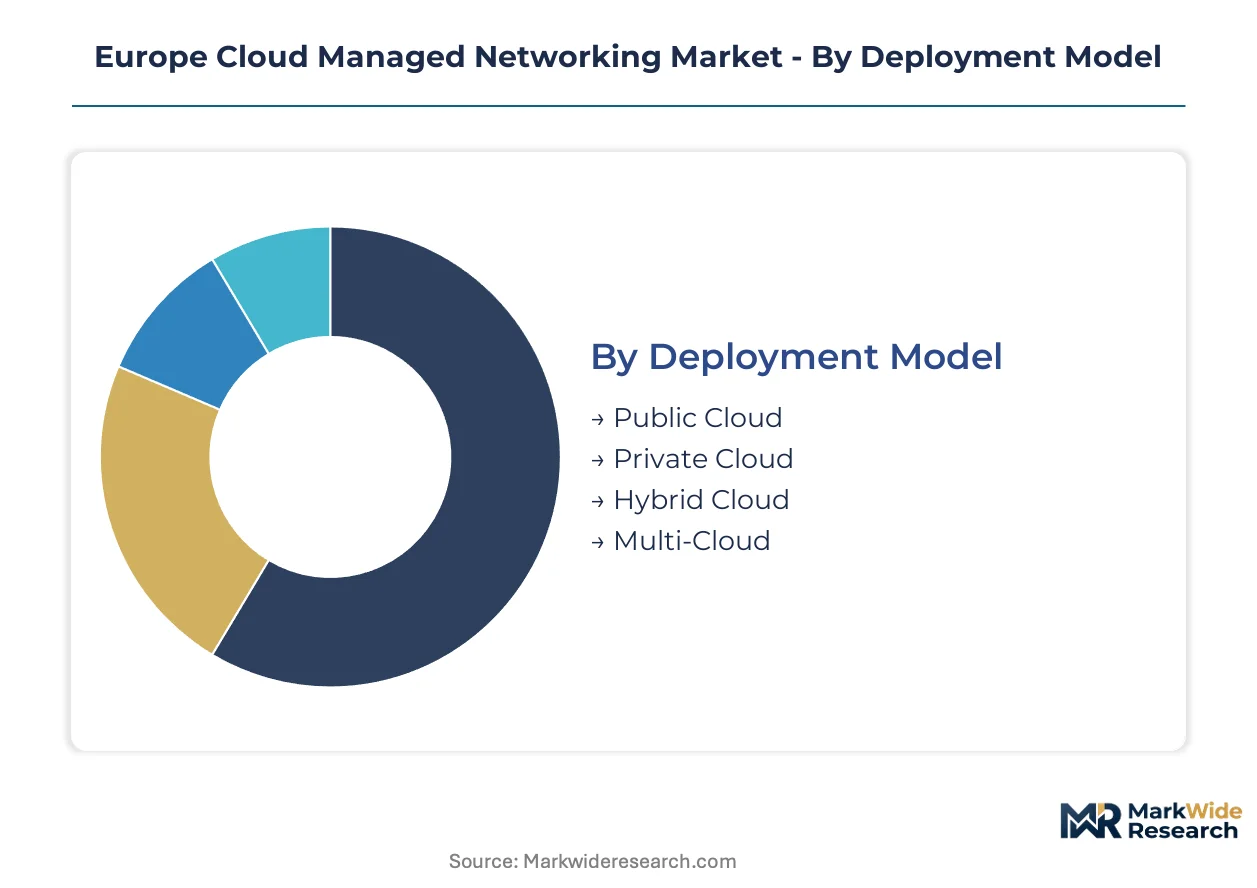
The Europe cloud managed networking market segments across various dimensions, reflecting diverse operational needs and technological preferences of enterprises. Understanding these distinctions helps providers tailor offerings to specific client requirements, ensuring optimal performance and compliance within the European regulatory framework.
Deployment Model:
The choice of deployment model influences data sovereignty and operational control for European organizations, with some models offering greater integration depth into existing IT infrastructures while others function more as standalone services.
- Public Cloud:This model delivers networking services over the public internet, shared among multiple tenants, offering high scalability and cost efficiency. Demand concentrates in small and medium-sized enterprises across Europe seeking agile, low-overhead network management.
- Hybrid Cloud:Combining on-premise infrastructure with public cloud resources, this model enables flexible workload placement and data management. European financial services firms and healthcare providers utilize hybrid setups for sensitive data handling and regulatory compliance under GDPR.
- Private Cloud:Dedicated cloud infrastructure, either on-premise or hosted by a third party, provides exclusive access and enhanced security. Large German manufacturing companies often favor private cloud deployments to maintain stringent control over their operational technology networks.
- Multi-Cloud:Utilizing multiple cloud services from different providers, this approach enhances resilience and avoids vendor lock-in. Enterprises across the EU adopt multi-cloud strategies to optimize performance and comply with diverse regional data residency requirements.
Volume placements concentrate in Public Cloud; the faster expansion belongs to Hybrid Cloud.
Service Type:
Service types delineate the scope of managed networking functionalities, from foundational infrastructure to comprehensive software solutions, impacting how organizations consume and integrate network capabilities.
- Network as a Service:This model provides networking capabilities on demand, abstracting the underlying hardware and software into a subscription-based offering. NaaS solutions are expanding most quickly as European businesses shift from capital expenditure to operational expenditure models.
- Software as a Service:SaaS delivers cloud-based software applications over the internet, including network management tools and security solutions. European professional services firms widely adopt SaaS for streamlined network monitoring and policy enforcement.
- Infrastructure as a Service:IaaS offers virtualized computing resources, including virtual networks, storage, and servers, as a service. Data centers across Europe leverage IaaS to provision scalable network environments for their clients.
- Platform as a Service:PaaS provides a platform allowing customers to develop, run, and manage applications without the complexity of building and maintaining infrastructure. Developers within the EU utilize PaaS for rapid deployment of network-dependent applications.
The largest share of deployments falls within Software as a Service; Network as a Service exhibits the steepest expansion trajectory.
End User:
Different end-user segments exhibit distinct requirements for network performance, security, and compliance, driving specialized cloud managed networking solutions across Europe.
- Healthcare:This sector requires robust, secure networks for managing patient records, medical imaging, and connected devices, adhering to strict data protection regulations like GDPR. European healthcare institutions prioritize highly compliant cloud networking for secure data exchange and remote diagnostics.
- Manufacturing:Manufacturing operations, particularly Germany's Mittelstand, demand low-latency, reliable networks for industrial control systems and IoT deployments. Cloud managed networking supports factory automation and supply chain integration across the continent.
- Retail:Retailers use cloud managed networks for point-of-sale systems, inventory management, and customer Wi-Fi, requiring scalable and flexible solutions. European retail chains deploy these networks to manage distributed store locations and seasonal demand fluctuations.
- Education:Educational institutions need high-bandwidth, secure networks for campus-wide Wi-Fi, e-learning platforms, and administrative systems. Universities and schools across Europe represent a growing segment for network modernization.
The most mature adoption patterns are observed in Retail; the education sector shows significant potential for new implementations.
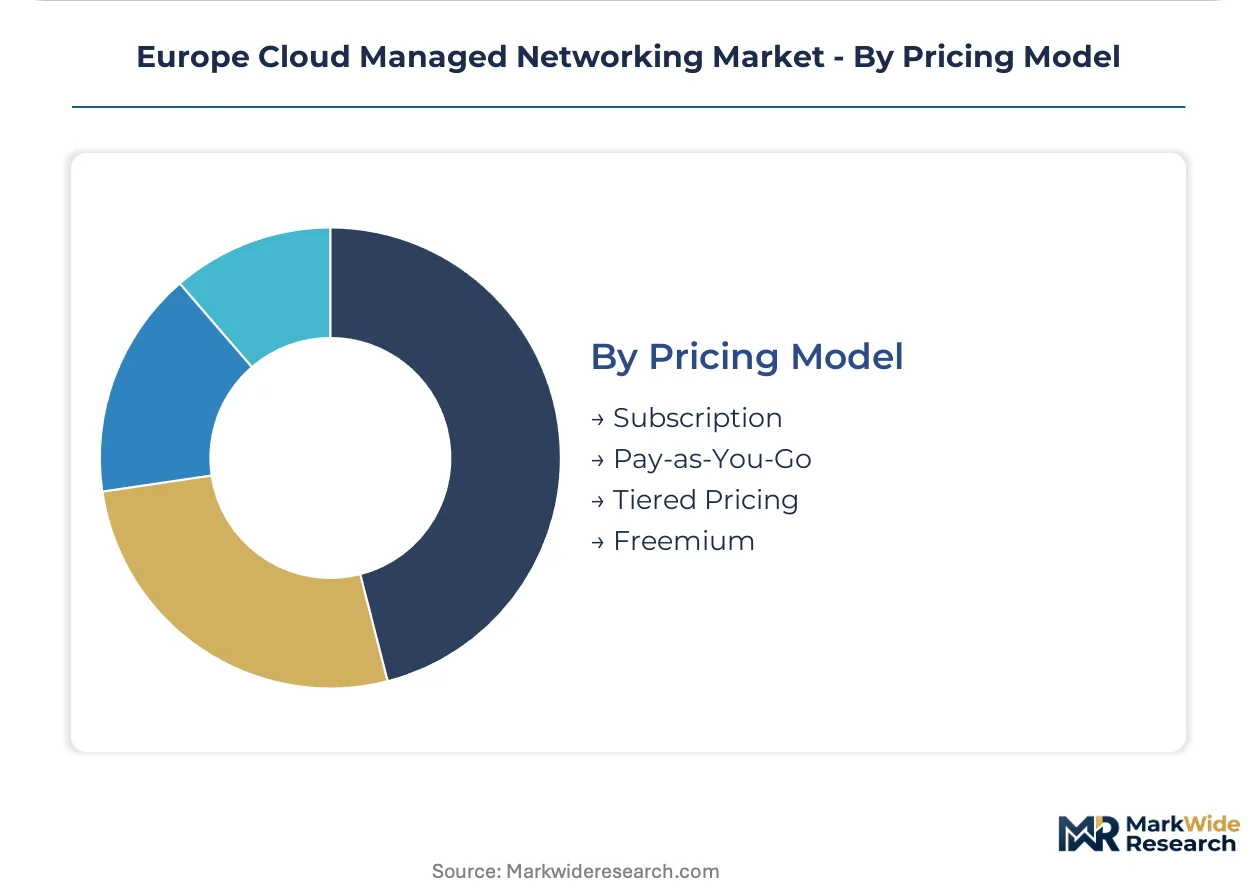
Pricing Model:
Pricing models determine how customers pay for cloud managed networking services, influencing budget allocation and long-term financial planning for European enterprises.
- Subscription:Customers pay a recurring fee for access to cloud managed networking services, typically on a monthly or annual basis. This model offers predictable costs and simplifies budgeting for businesses across the EU.
- Pay-as-You-Go:Charges are based on actual resource consumption, such as data transfer or network usage, providing flexibility for variable demand. Startups and small businesses in Europe often prefer pay-as-you-go for its cost efficiency and scalability.
- Tiered Pricing:Services are offered in different packages or tiers, each with a specific set of features and pricing. Enterprises select tiers based on their required service levels and network complexity.
- Freemium:A basic version of the service is offered for free, with advanced features available through paid subscriptions. This model helps attract new users and allows them to experience service capabilities before committing financially.
The most common payment structure is Subscription; Pay-as-You-Go offers greater flexibility for fluctuating network demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Mittelstand manufacturing base concentrates demand for cloud managed networking solutions. This sector seeks to modernize operations and integrate advanced technologies. Data sovereignty and sustainable IT infrastructure also shape regional adoption patterns across Europe.
Germany
German enterprises, particularly Mittelstand manufacturers, prioritize secure and low-latency cloud networking for operational technology. The EU AI Act introduces new compliance requirements for cloud services. The Rhine-Ruhr industrial region invests heavily in cloud-managed solutions for factory automation and supply chain integration.
France
French organizations emphasize data sovereignty and sustainable data center operations. Compliance with GDPR dictates data residency and processing standards for all EU operators. Paris and Lyon are emerging as key hubs for cloud innovation, with strong demand from professional services and public sector entities.
United Kingdom
United Kingdom businesses increasingly adopt cloud managed networking for flexible, scalable IT infrastructure. UK data protection laws impose stringent requirements for data handling and residency. London's financial district and technology clusters drive significant demand for advanced network solutions and SASE architectures.
Netherlands
Dutch enterprises demonstrate a strong inclination towards hybrid cloud deployments, balancing public cloud agility with on-premise control. The Corporate Sustainability Reporting Directive (CSRD) compels cloud providers to disclose IT infrastructure energy consumption. Amsterdam's robust digital infrastructure supports cloud-managed services adoption.
Poland
Poland represents a growing market for cloud managed networking as the country invests heavily in digital transformation. The EU AI Act and GDPR are fundamental compliance requirements for cloud services deployed within Poland. Warsaw and Krakow are experiencing rapid growth in IT and business process outsourcing, fueling demand for scalable network solutions.
Europe Cloud Managed Networking Market Key Industry Players
European producers anchor one tier, specializing in regional compliance and data sovereignty; global technology providers hold another, offering extensive portfolios. The market structure is tiered, with established network hardware vendors competing with cloud-native software specialists. Strategic archetypes include integrated infrastructure providers, pure-play NaaS vendors, and regional telecommunication operators. Dominant competitive moves involve strategic partnerships to expand solution ecosystems and portfolio diversification into AI-powered network operations.
Among leading providers, Cisco Systems exemplifies the integrated hardware and software approach, leveraging its extensive portfolio to offer comprehensive solutions across the continent. Deutsche Telekom, a German telecommunications company, anchors its offering with deep network infrastructure and sovereignty-focused cloud services across Germany. French provider OVHcloud, a cloud computing company, represents the sustainable data center archetype, appealing specifically to GDPR-conscious clients seeking verifiable green credentials. These companies illustrate the diverse strategies employed to capture market share within Europe's evolving regulatory landscape.
| Leading Market Players |
|---|
| Cisco Systems |
| Aruba (Hewlett Packard Enterprise) |
| Extreme Networks |
| Deutsche Telekom |
| OVHcloud |
| Orange |
| NTT Europe |
| Capgemini |
| Atos |
| Others |
Cost & Logistics Intelligence
The transition to cloud-based managed networking platforms fundamentally reshapes cost economics for European enterprises, shifting capital expenditure to operational models. This evolution also reconfigures the supply base towards software-centric providers and specialized cloud infrastructure.
Pricing Analysis
Premium pricing for immediate deployments or highly customized cloud managed networking solutions often reflects short lead times and specialized integration efforts. The subscription model dominates, offering predictable costs for European businesses, while pay-as-you-go provides flexibility. Price differentiation stems from verifiable data sovereignty, stringent compliance with GDPR, and sustainability credentials mandated by CSRD. Pricing softness stems from intense competition and the shift to operational expenditure models, with small and medium-sized enterprises exhibiting the highest price sensitivity.
Supply Chain Analysis
Logistics and freight costs influence the delivery of physical network hardware components for hybrid cloud deployments across Europe. Geographic supply concentration for core networking hardware components centers on established manufacturing hubs, while cloud infrastructure services rely on major data center clusters in Germany, France, and the Netherlands. The supply chain draws from specialized software licenses and underlying cloud infrastructure, creating single-source vulnerabilities from reliance on limited global hardware component manufacturers. Distribution runs through direct sales channels from major vendors and extensive networks of channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe cloud managed networking market is fundamentally a cost-of-compliance story, where adherence to regulations like GDPR creates a significant barrier to entry. This regulatory environment favors established providers capable of navigating complex data residency and processing standards.
For Market Incumbents: Anchor existing client relationships by deepening integrated hardware and software offerings, particularly for hybrid cloud solutions. Expand regional data center footprints to address data localization complexities and reinforce compliance with GDPR and the EU AI Act. Invest in AI-powered network operations to differentiate offerings against emerging cloud-native specialists. Leverage extensive channel partner networks to counter performance latency concerns and address the specialized skills shortage.
For New Entrants and Emerging Players: Begin with a focus on underpenetrated segments such as the European education sector, offering tailored cloud-managed Wi-Fi and security solutions. Target Eastern Europe infrastructure build-out with agile, subscription-based Network as a Service (NaaS) platforms. Differentiate through verifiable sustainability credentials aligned with CSRD mandates. A go-to-market angle emphasizing rapid deployment and cost-efficient operational models will appeal to small and medium-sized enterprises.
For Investors and Strategic Acquirers: Exit pathways concentrate in pure-play NaaS vendors and AI-powered network operations specialists over a five-to-ten-year horizon. Target acquisition profiles include regional providers with deep compliance expertise in GDPR and the EU AI Act. Long-term viability favors entities capable of delivering verifiable data sovereignty and sustainability reporting. The signal to watch is the accelerated adoption of Secure Access Service Edge (SASE) architectures across diverse European enterprises.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines cloud management with SASE architecture, simplifying IT for European enterprises. |
| Strategic Partnership | Leverages local telecommunication infrastructure, extending reach and compliance across member states. |
| Acquisition of Specialist Firm | Integrates AI/ML network analytics capabilities, enhancing predictive maintenance and security. |
| Geographic Expansion | Establishes early market presence in developing Eastern European digital transformation markets. |
| Green Certification Program | Attracts GDPR-conscious clients seeking verifiable sustainability credentials under CSRD. |
Research Approach
Document review covered EU Commission reports, national regulatory body publications, and corporate sustainability reports, complemented by interviews with IT procurement officers, network architects, and cloud solution providers. Primary research involved discussions with CTOs and regulatory compliance leads across European enterprises. This approach ensured a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation validated data points, enhancing accuracy.
Historical data was cross-referenced against expert panel input to construct the forecast framework across the analysis window. The analytical framework modeled segmentation dimensions including deployment model, service type, end-user, and regional adoption patterns. Compound Annual Growth Rates were derived through regression analysis. Digital transformation investment rates and regulatory compliance expenditure served as key forecast inputs.
Underlying measurement precision varies by segment; public cloud and SaaS deployments carry tighter precision than emerging niche applications. Forecasts reflect assumptions regarding the evolving regulatory landscape and geopolitical stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Cloud Database Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Global Cloud-Native Software Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Cloud Managed Networking Market