
 Global Bluetooth Audio Codec Market | 2026-2036
Global Bluetooth Audio Codec Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bluetooth Audio Codec Market Analysis
Direct-to-consumer online retail is reshaping how Bluetooth audio codecs reach end users, bypassing traditional electronics distributors that once controlled shelf placement. Qualcomm Technologies leverages its Snapdragon Sound platform to anchor premium tier positioning across Android ecosystems. Samsung Electronics competes through in-house Exynos chipset integration with its Galaxy Buds lineup. Sony Corporation specializes in proprietary LDAC transmission to differentiate its audiophile-grade hardware.
Bluetooth audio codecs are compression-decompression algorithms that encode digital audio streams for wireless transmission over Bluetooth protocols, typically operating at bit rates from 279 kbps to 990 kbps depending on codec variant. These codecs enable real-time audio delivery with minimal perceptible latency for consumer and professional applications. AptX dominates premium headphone configurations where low latency matters for gaming and video sync, while LC3 is gaining fastest adoption as the Bluetooth SIG mandates its inclusion in LE Audio specifications. Earbuds command the deepest margin pools among product types due to replacement cycles and accessory attach rates.
FCC certification in the United States governs radio frequency emissions for all Bluetooth audio devices entering North American channels, while CE marking under EU Radio Equipment Directive mandates interoperability and safety standards for European market access. China's MIIT enforces SRRC radio type approval for products sold domestically, creating a three-regulator compliance landscape that vendors must navigate simultaneously. Stakeholders should monitor LE Audio specification maturity and LC3 royalty structures as these will determine next-generation codec investment priorities.
Market Dynamics
LE Audio specification rollout with mandatory LC3 codec inclusion is compressing legacy codec licensing revenue streams while fragmenting hardware certification timelines across regional regulators.
Growth Catalysts
- EU Green Deal energy efficiency mandates:Battery-powered audio devices face tightening standby power limits, accelerating demand for low-energy codec variants in earbuds and wearables sold across European markets.
- Shenzhen-Dongguan manufacturing concentration:Contract manufacturers in these Chinese clusters achieve 40-60% faster prototyping cycles for Bluetooth audio modules, compressing OEM time-to-market.
- LE Audio broadcast audio:Public venues and hearing aid applications are pulling Auracast-enabled hardware through specification mandates issued by the Bluetooth SIG.
Market Restraints
- Royalty stack accumulation:Patent licensing for aptX, LDAC, and LC3 creates cumulative cost burdens that squeeze margin on sub-premium hardware tiers.
- MIIT SRRC type approval delays:China's radio certification backlog extends product launch timelines by 8-14 weeks for brands without established local testing partnerships.
- Sub-6 GHz spectrum congestion:Bluetooth 5.3 coexistence with Wi-Fi 6E in dense urban environments degrades effective throughput for high-bitrate audio streams.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for mobile phone and component assembly are pulling codec module sourcing toward Noida and Chennai corridors.
- Over-the-counter hearing aid deregulation:FDA 2022 rulemaking creates a new device category where LE Audio and LC3 integration satisfies prescription-grade audio quality requirements at consumer price points.
- Gaming peripheral low-latency specialization:AptX Adaptive and LC3 Plus variants enable sub-40ms end-to-end latency that differentiates premium headset positioning in esports hardware.
Industry Challenges
- Multiregional certification parallelism:Simultaneous FCC, CE marking, and SRRC submissions require dedicated regulatory affairs headcount that mid-tier vendors struggle to maintain.
- Firmware update fragmentation:Post-launch codec optimization patches must propagate across Android OEM skin variants, iOS version gates, and proprietary chipset SDKs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bluetooth Audio Codec Market |
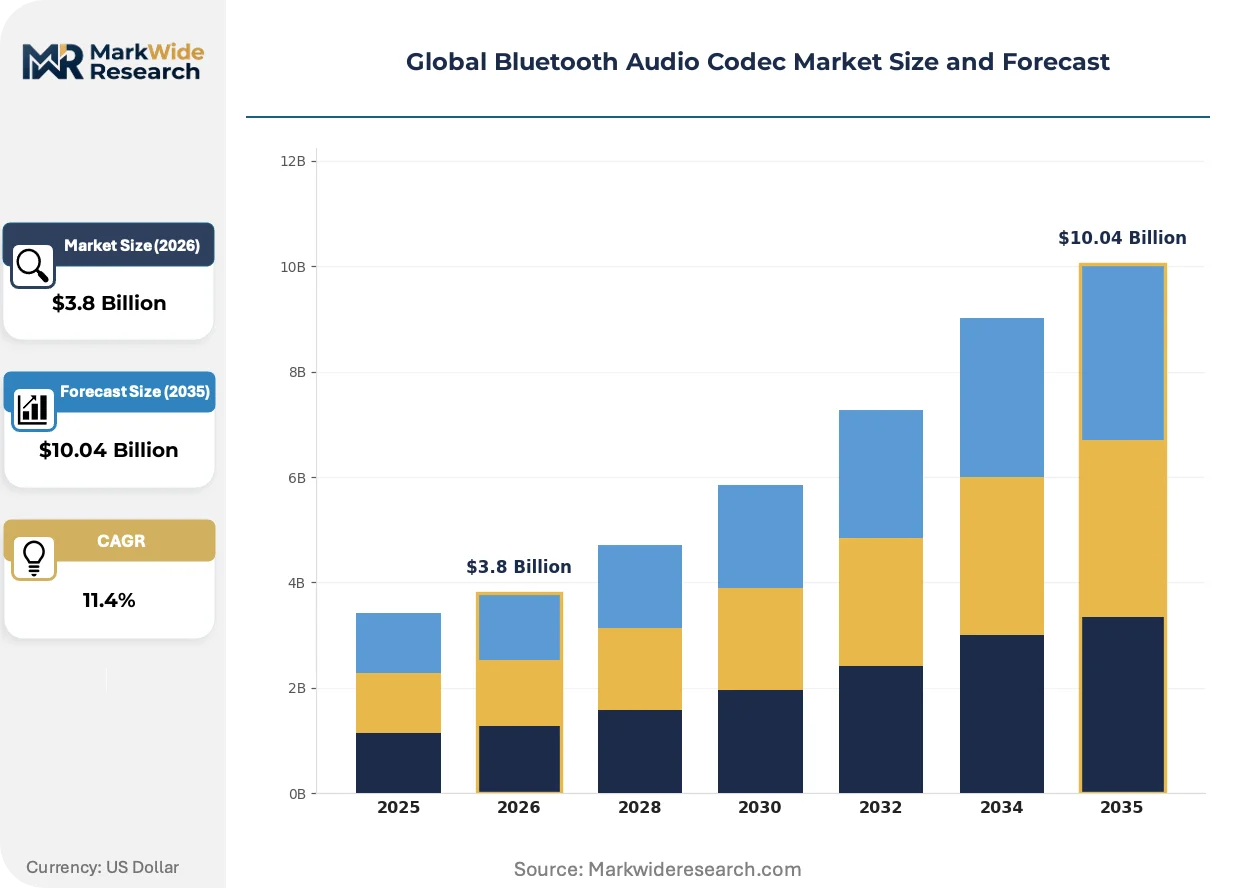
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AptX, SBC, AAC, LC3 Product Type: Headphones, Speakers, Soundbars, Earbuds End User: Consumers, Enterprises, Tech Developers, Audiophiles Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Samsung Electronics, Cirrus Logic, Qualcomm Technologies, Analog Devices, Realtek Semiconductor Corp., Sony Corporation, MediaTek, STMicroelectronics, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bluetooth Audio Codec Market Emerging Trajectories
Codec hardware is shifting from discrete DSP chips toward integrated SoC blocks, compressing bill-of-materials complexity while embedding machine-learning inference for adaptive bitrate selection.
LC3 codec implementation is rendering obsolete standalone aptX and SBC hardware decoders in mid-tier earbuds. Smartphone OEMs are stripping legacy codec support from base-model chipsets to reduce licensing overhead. The structural consequence is a bifurcation between premium-tier multi-codec hardware and LC3-only economy configurations.
CE marking under the EU Radio Equipment Directive now mandates interoperability testing for LE Audio broadcast reception, forcing hearing aid and public address hardware vendors to redesign RF front ends. German and French notified bodies have published divergent testing protocols, creating compliance fragmentation despite shared regulatory parentage.
Direct-to-consumer audio brands are bypassing electronics distributors that previously controlled retail shelf placement and technical support. Shenzhen-based OEMs now sell codec-optimized earbuds through proprietary apps and social commerce channels, compressing traditional wholesale margin capture. This channel shift is most visible in Southeast Asian markets where TikTok Shop and Shopee Live dominate discovery.
Global Bluetooth Audio Codec Market Segmentation
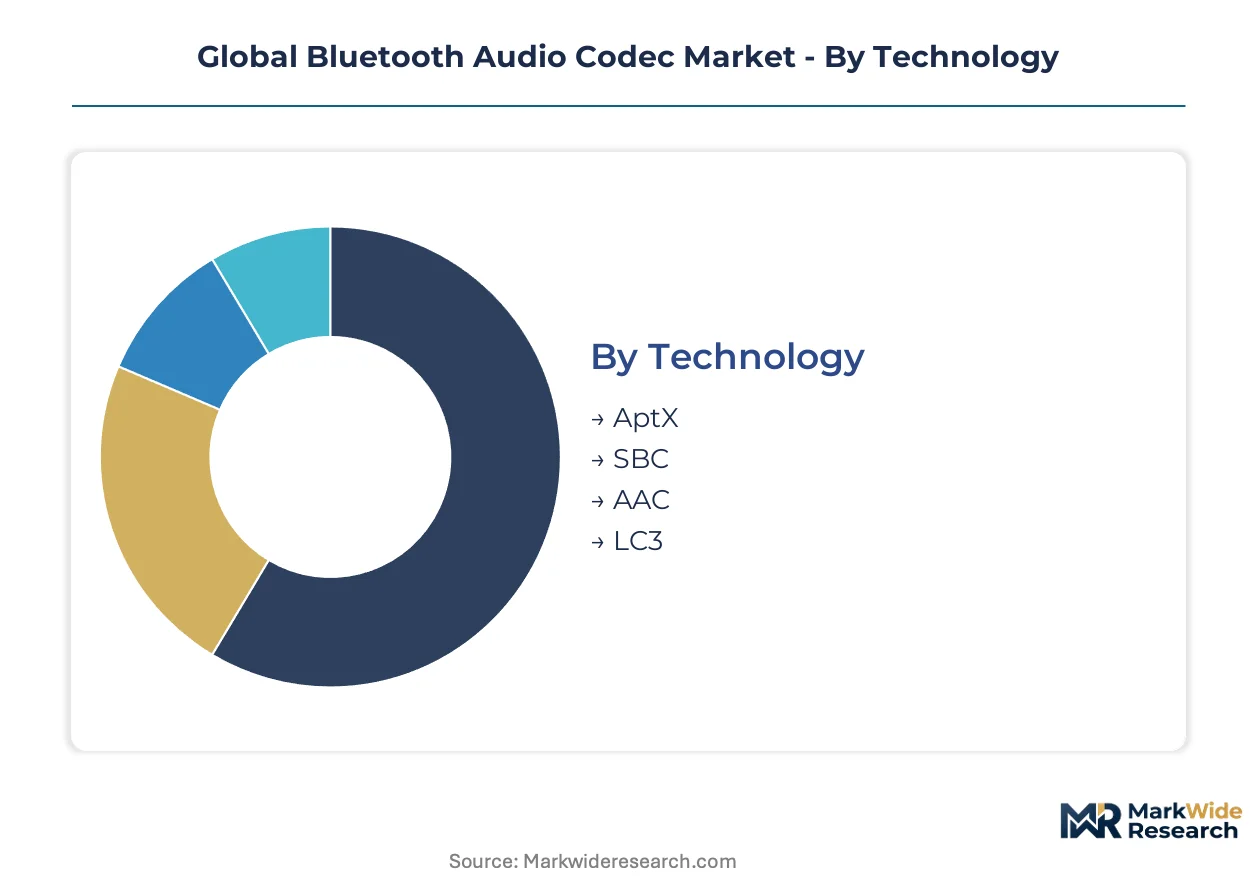
Bluetooth audio codec adoption patterns diverge sharply across compression algorithms, hardware form factors, and buyer sophistication tiers. Technology selection drives licensing cost structures, while product type determines power budgets and latency tolerances that shape codec implementation choices.
Technology:
Compression efficiency and royalty structures differentiate how each codec variant penetrates cost tiers and performance segments.
- AptX:Qualcomm's proprietary algorithm achieves 352 kbps transmission with sub-40ms latency. Gaming peripherals and premium headphone lines in the United States and Germany concentrate demand here, driven by video synchronization requirements and Qualcomm's Snapdragon Sound platform bundling.
- LC3:The Bluetooth SIG-mandated LE Audio codec operates at half the bitrate of SBC for equivalent perceptual quality. Hearing aid manufacturers and Auracast-enabled public venue hardware in France and Japan are pulling volume fastest as LE Audio specifications mature.
- SBC:The mandatory baseline codec specified in A2DP profiles. Entry-level earbuds and automotive infotainment systems in India and Brazil default to this royalty-free option, constrained by 200+ ms latency unsuitable for interactive applications.
- AAC:Apple's preferred codec for iOS ecosystem synchronization. Consumer headphones targeting iPhone users and podcast-focused hardware in the United States and United Kingdom standardize on this 250 kbps format, limited by Android implementation fragmentation.
LC3 commands the established base for next-generation hardware. The steepest expansion runs through AptX Adaptive variants targeting sub-40ms latency applications.
Product Type:
Form factor constraints on battery capacity and antenna placement create divergent codec optimization priorities across hardware categories.
- Earbuds:Tightest power budgets in the category—typically 35-50 mAh per bud—force aggressive codec efficiency tradeoffs. Shenzhen and Dongguan contract manufacturers are integrating LC3 hardware decoders into reference designs for European and North American OEMs, compressing time-to-market for CE-marked products.
- Headphones:Larger battery envelopes accommodate multi-codec DSP implementations. Gaming headsets and studio monitoring equipment in Germany and the United States specify AptX Low Latency and LDAC support, with over-ear designs absorbing higher silicon costs.
- Speakers:Mains-powered or large-battery configurations prioritize bitrate over efficiency. Portable Bluetooth speakers for outdoor use in Australia and South Africa default to SBC or AAC, with premium home audio in Japan and France adding LDAC for high-resolution source compatibility.
- Soundbars:Home theater applications demand lip-sync precision below 40ms. Living room installations in the United States and United Kingdom are standardizing on AptX Adaptive, while CE marking requirements for EU Green Deal standby power limits are accelerating LC3 migration in German and Italian markets.
Earbuds anchor volume concentration. The fastest climb is occurring in soundbars as television manufacturers bundle LE Audio transmitters.
End User:
Buyer technical sophistication and use case specificity determine codec feature premiums and support requirements.
- Consumers:Price-sensitive mass market prioritizing compatibility over specification sheets. Smartphone bundle earbuds and entry-level replacements in India and Indonesia concentrate here, with LC3-only hardware displacing legacy codec support in sub-premium tiers.
- Audiophiles:Bitrate-maximizing enthusiasts demanding lossless-equivalent transmission. High-resolution portable players and aftermarket DACs in Japan and Germany specify LDAC and LHDC, accepting premium pricing for 990 kbps capability.
- Enterprises:Call center headsets and unified communications hardware prioritizing microphone quality and multi-point connectivity. Office deployments in the United States and United Kingdom standardize on AAC and SBC for broad device compatibility.
- Tech Developers:Prototype and integration-focused buyers evaluating codec performance for product integration. Shenzhen-based OEMs and Bangalore hardware startups drive early LC3 Plus adoption for gaming peripheral development.
Consumers represent the volume foundation. Audiophiles deliver the steepest technology premium capture.
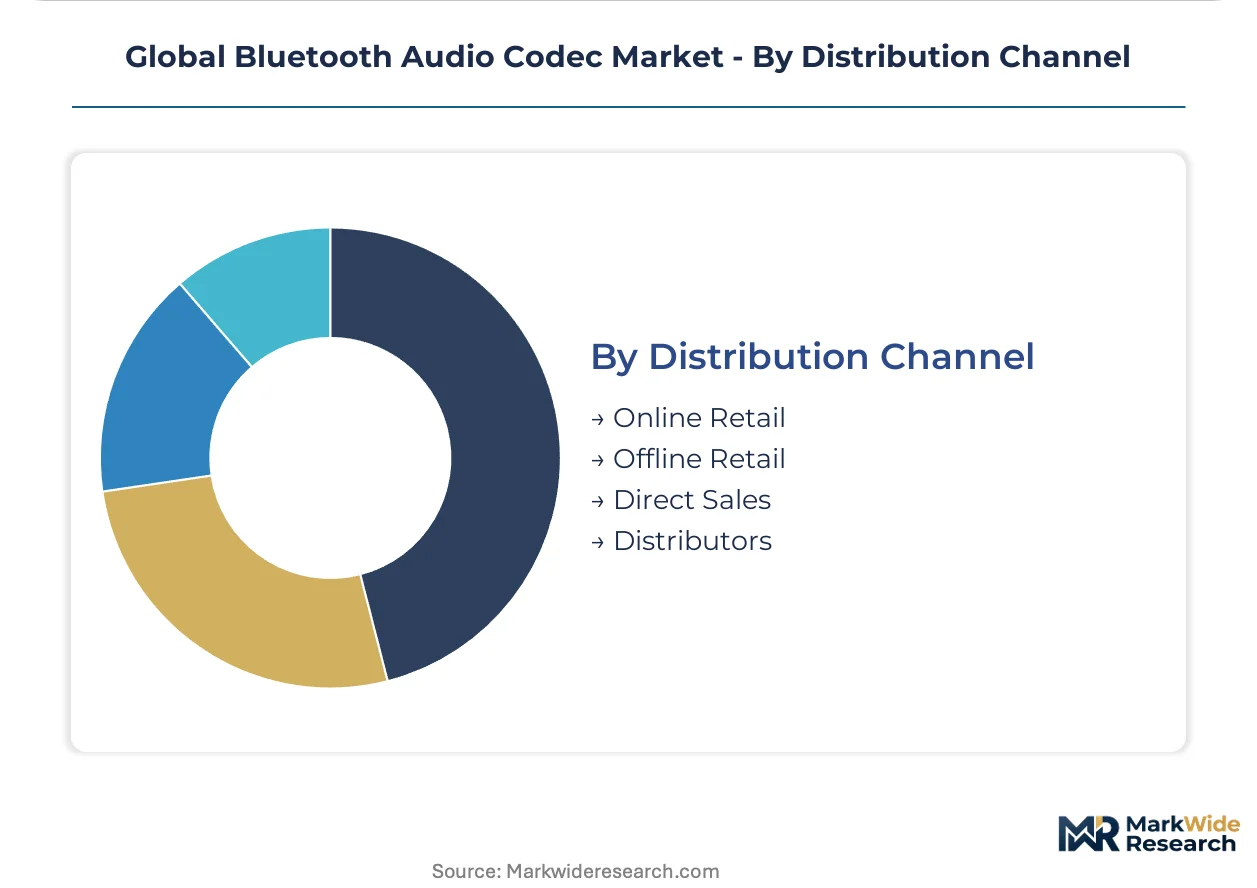
Distribution Channel:
Channel economics and buyer journey length reshape which codec variants reach which customer segments.
- Online Retail:Direct-to-consumer platforms enabling specification-transparent comparison. Amazon and proprietary brand stores in the United States and Germany are concentrating AptX and LDAC-enabled premium hardware, with detailed codec compatibility matrices driving conversion.
- Direct Sales:B2B procurement and enterprise fleet purchasing bypassing retail markup. Hearing aid manufacturers and corporate headset rollouts in France and the United States contract directly with codec licensors for volume pricing.
- Offline Retail:Big-box electronics and carrier stores where staff expertise varies. Mass-market earbuds in India and Brazil sell through this channel with minimal codec differentiation at point of sale.
- Distributors:Traditional electronics wholesalers losing share to direct channels. Regional distributors in Southeast Europe and Latin America still intermediate for mid-tier Chinese OEMs lacking local sales infrastructure.
Online retail commands the volume trajectory. Direct sales capture the steepest expansion in enterprise and hearing aid verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT anchors the regulatory landscape for Bluetooth audio devices through SRRC type approval requirements that shape market entry timelines. FCC certification governs North American radio frequency emissions. CE marking under the EU Radio Equipment Directive enforces interoperability and energy efficiency standards across European markets.
United States
FCC Part 15 certification mandates govern Bluetooth radio emissions for all devices entering North American distribution. The FDA's 2022 over-the-counter hearing aid rulemaking creates a new device category where LE Audio integration satisfies prescription-grade requirements. Austin and San Diego host hardware engineering clusters where codec optimization firms cluster near semiconductor design centers.
China
MIIT enforces SRRC radio type approval with certification backlogs extending product launches by 8-14 weeks for brands lacking local testing partnerships. The country's dual carbon goals accelerate demand for low-energy codec variants in battery-powered audio hardware. Shenzhen and Dongguan manufacturing clusters achieve 40-60% faster prototyping cycles for Bluetooth audio modules, compressing OEM time-to-market for export markets.
Germany
CE marking under the EU Radio Equipment Directive mandates interoperability testing for LE Audio broadcast reception, with German notified bodies publishing divergent protocols from French counterparts. The EU Green Deal's standby power limits accelerate LC3 migration in soundbars and home audio equipment. Munich and Stuttgart anchor automotive infotainment engineering where Bluetooth 5.3 coexistence with Wi-Fi 6E receives intensive testing.
Japan
METI oversees radio equipment compliance through technical standards alignment with Bluetooth SIG specifications. High-resolution audio culture drives LDAC adoption in premium portable players and aftermarket DACs. Tokyo and Osaka metropolitan areas concentrate audiophile retail channels where codec specification transparency drives purchasing decisions.
India
BIS certification and the PLI scheme for electronics manufacturing pull codec module sourcing toward Noida and Chennai corridors. TRAI regulations govern spectrum allocation affecting Bluetooth coexistence with cellular bands in dense urban deployments. Bangalore hardware startups drive early LC3 Plus adoption for gaming peripheral development targeting export markets.
Global Bluetooth Audio Codec Market Vendor Landscape
Platform licensors and discrete semiconductor suppliers split the market into vertically integrated and merchant-silicon camps. Samsung Electronics and Apple anchor the integrated-device archetype through captive chipset design. Qualcomm Technologies and MediaTek exemplify the platform-licensor model bundling codec IP with baseband processors. Cirrus Logic and Analog Devices occupy the analog-front-end specialist tier. Competitive moves concentrate on strategic partnerships for LE Audio certification acceleration and geographic expansion into Indian manufacturing corridors.
Within the platform-licensor tier, Qualcomm Technologies and MediaTek exemplify divergent approaches to Android ecosystem penetration. Samsung Electronics anchors the vertically integrated archetype through Exynos chipset deployment across Galaxy Buds hardware. Sony Corporation occupies the proprietary-codec specialist position through LDAC transmission technology. STMicroelectronics and Realtek Semiconductor Corp. sit within the merchant-silicon tier supplying reference designs to contract manufacturers.
| Leading Market Players |
|---|
| Samsung Electronics |
| Cirrus Logic |
| Qualcomm Technologies |
| Analog Devices |
| Realtek Semiconductor Corp. |
| Sony Corporation |
| MediaTek |
| STMicroelectronics |
| Apple |
| Others |
Supply Flow & Price Mechanics
MIIT SRRC certification backlogs spanning 8-14 weeks compress both margin structures and sourcing geography for brands lacking Shenzhen testing partnerships, forcing a bifurcation between premium multi-codec hardware and LC3-only economy configurations.
Pricing Analysis
Configured-to-order pricing for AptX Adaptive and LDAC-enabled hardware commands substantial premiums over standard LC3-only SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE marking and FCC Part 15 compliance adding measurable cost layers. Cost compression in the sub-premium tier intensifies because smartphone OEMs strip legacy codec support from base-model chipsets. Enterprise procurement teams exhibit lowest price sensitivity due to unified communications compatibility requirements, while mass-market consumers in India and Indonesia drive aggressive economy-tier negotiation.
Supply Chain Analysis
Foxconn, Goertek, and Luxshare Precision anchor contract-manufacturing capacity for Bluetooth audio modules across Shenzhen and Dongguan clusters. Component sourcing draws from Taiwan for DSP silicon, South Korea for advanced packaging, and Japan for high-precision acoustic components. Single-source vulnerability concentrates in Qualcomm's AptX licensing dominance for low-latency gaming applications. Distribution runs through direct-to-consumer platforms and proprietary brand apps, compressing traditional electronics distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LE Audio specification maturity with mandatory LC3 inclusion constitutes a regulatory-technology inflection that will displace legacy codec hardware within the projection window.
For Market Incumbents: Insulate royalty revenue streams by accelerating LC3 Plus development for gaming peripheral specialization while securing Auracast certification partnerships with hearing aid manufacturers. Threat from MediaTek's merchant-silicon bundling demands defensive patent portfolio reinforcement. Priority lever rests on backward integration into reference design ownership. For New Entrants and Emerging Players: India's Noida and Chennai manufacturing corridors offer geographic underpenetration for codec module assembly under PLI scheme incentives. White-space targets include over-the-counter hearing aid hardware and esports peripheral sub-40ms latency configurations. Go-to-market angle should emphasize direct social commerce channels through TikTok Shop and Shopee Live for Southeast Asian discovery. For Investors and Strategic Acquirers: The market sits at a specification-transition phase that favors platform-licensor archetypes with LE Audio certification acceleration capabilities. Long-term viability centers on royalty structure negotiation leverage and geographic expansion into Indian manufacturing corridors. Signal to watch involves LC3 royalty disclosure patterns from Bluetooth SIG as adoption thresholds cross inflection.| Strategic Initiative | Industry Significance |
|---|---|
| LE Audio Certification Acceleration | Bluetooth SIG mandate timelines compress hardware redesign cycles for Auracast-enabled products. |
| LC3 Plus Gaming Specialization | Sub-40ms latency specifications differentiate premium headset positioning in esports hardware. |
| India Manufacturing Footprint Expansion | PLI scheme incentives pull codec module sourcing toward Noida and Chennai corridors. |
| Direct-to-Consumer Channel Development | Proprietary apps and social commerce bypass traditional electronics distributor margin capture. |
| Over-the-Counter Hearing Aid Integration | FDA 2022 rulemaking creates new device category requiring LE Audio compliance investment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor platform engineers, contract manufacturing procurement leads, Bluetooth SIG working group participants, and consumer audio brand product managers. Secondary validation drew from FCC equipment authorization databases, MIIT SRRC certification records, EU Radio Equipment Directive notified body publications, and Bluetooth SIG specification releases. Bottom-up volume estimates triangulated against top-down royalty flow analysis.
Calibration against historical codec adoption curves and chipset shipment disclosures anchored the analytical framework across the analysis window. Segmentation dimensions modeled include compression algorithm technology, hardware form factor constraints, end-user sophistication tiers, and regional regulatory cluster patterns. CAGRs derived from logistic diffusion curves fitted to LE Audio specification rollout timelines, with inputs from energy efficiency mandate compliance cost modeling.
The forecast holds incumbent behavior within observed patterns; aggressive moves by merchant-silicon entrants or regulatory acceleration by EU notified bodies would shift outcomes substantially. Quarterly review of LC3 royalty disclosure patterns, MIIT certification backlog durations, and Auracast deployment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
North America in-Building Wireless Market