
 Wireless Infrastructure Market | 2026-2036
Wireless Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Infrastructure Market Intelligence
South Korea's nationwide 5G densification program is narrowing the gap between urban capacity and rural coverage targets. Ericsson leverages its radio access portfolio to sustain leadership in massive MIMO deployments across Northeast Asian markets. Nokia anchors European supply security through in-house silicon development for baseband units. American Tower Corporation dominates tower colocation economics in the United States by controlling zoning-premium real estate in top metropolitan statistical areas.
Wireless infrastructure comprises the physical and virtualized equipment enabling radio frequency signal transmission, reception, and network management, including base stations operating across sub-6 GHz and millimeter-wave spectrum bands with carrier aggregation supporting bandwidths exceeding 400 MHz. Its primary commercial purpose is delivering scalable, low-latency connectivity to mobile subscribers and fixed-wireless access customers. Base stations capture the largest share of product-type revenue pools due to semiconductor and power amplifier content density, while antennas face margin compression from commoditization in emerging markets. The 5G technology segment leads absolute spending, though microwave backhaul retains structural importance in terrain-constrained deployments where fiber trenching costs prove prohibitive.
The Federal Communications Commission shapes United States market access through spectrum auction design and infrastructure siting rules, while the European Telecommunications Standards Institute coordinates interoperability mandates that equipment vendors must satisfy for CE marking eligibility. India's Telecom Regulatory Authority of India influences carrier capex timing through spectrum pricing and rollout obligation frameworks. China's Ministry of Industry and Information Technology governs base station certification under national GB standards, directly affecting vendor qualification timelines. Stakeholders must monitor evolving national security review thresholds for foreign equipment participation in core network elements.
Market Dynamics
Carrier aggregation across sub-6 GHz and millimeter-wave bands is compressing equipment refresh cycles while spectrum scarcity in dense urban clusters forces infrastructure sharing agreements between competing operators.
Growth Catalysts
- India's TRAI spectrum allocation framework:Rollout obligations tied to spectrum pricing accelerate base station deployment timelines across tier-2 and tier-3 cities.
- Smart city infrastructure mandates:South Korean government programs fund microwave backhaul upgrades linking municipal IoT sensors to centralized command centers.
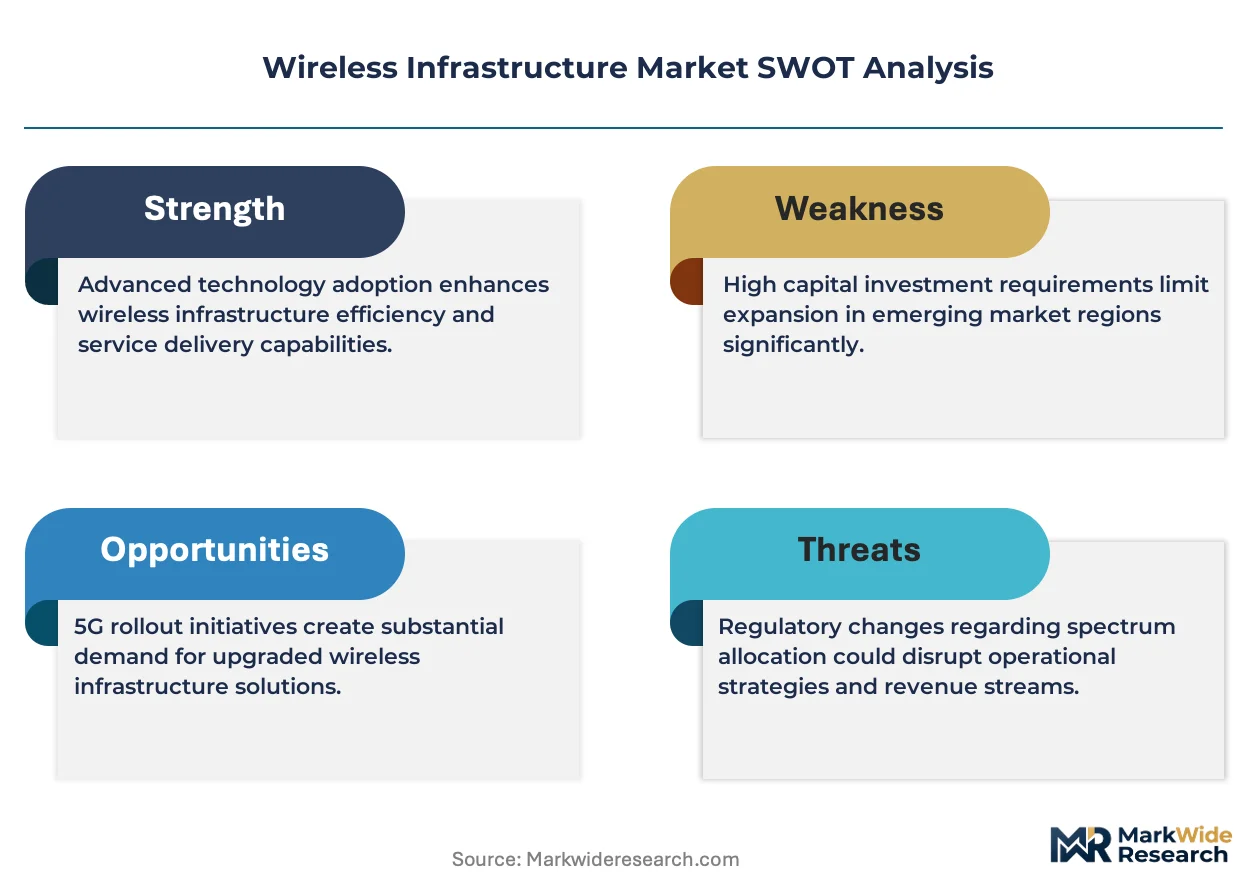
- Open RAN architecture adoption:Disaggregated hardware-software stacks reduce vendor lock-in and lower total cost of ownership for neutral host operators.
Market Restraints
- Gallium nitride substrate concentration:Power amplifier supply chains cluster in East Asian foundries, exposing procurement to geopolitical friction and export control risk.
- Millimeter-wave propagation physics:Signal attenuation through vegetation and precipitation limits rural coverage economics despite high spectral efficiency.
- Local zoning ordinances:Municipal siting restrictions in US metropolitan statistical areas extend tower permitting timelines and inflate lease escalation clauses.
Strategic Opportunities
- Private 5G networks for manufacturing:Industrial automation in German automotive plants creates demand for localized baseband units with deterministic latency guarantees.
- Federal Communications Commission rural digital opportunity fund:Subsidized fixed-wireless access deployments incentivize infrastructure buildout in underserved census blocks.
- Edge computing co-location:Convergence of radio access networks with distributed cloud nodes enables low-latency content delivery for augmented reality applications.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in massive MIMO beamforming algorithms commands premium compensation and constrains vendor scaling.
- Legacy 2G/3G decommissioning complexity:Spectrum refarming requires maintaining dual-mode base stations during migration windows, inflating operational expenditure.
- GB standard certification timelines:China's Ministry of Industry and Information Technology testing protocols create qualification bottlenecks for new equipment entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Infrastructure Market |
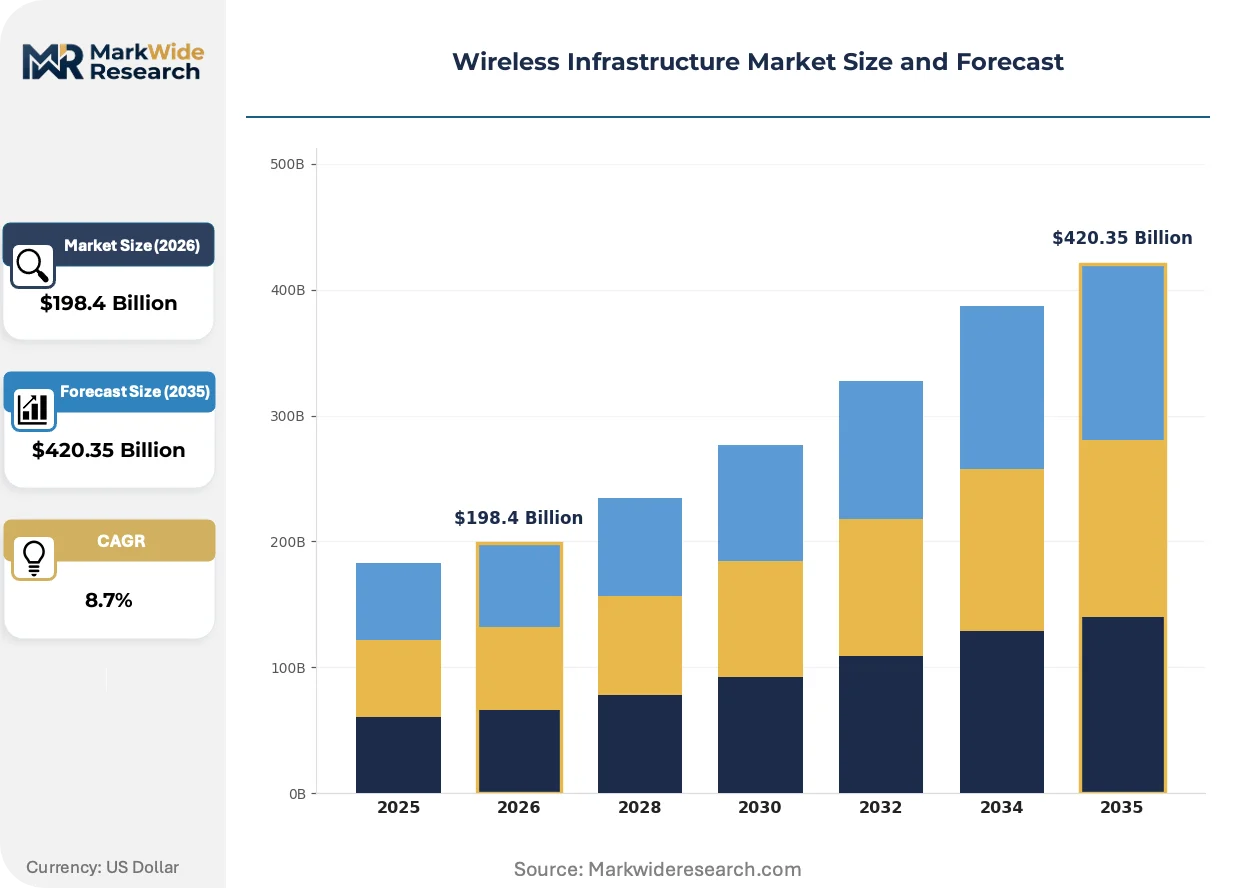
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $420.35 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Stations, Antennas, Repeaters, Controllers Technology: 5G, LTE, Wi-Fi, Microwave End User: Telecom Operators, Enterprises, Government, Utilities Application: Smart Cities, IoT, Public Safety, Industrial Automation |
| Companies Covered | T-Mobile US, AT&T, American Tower Corporation, Ericsson, Nokia, Crown Castle, Verizon Communications, Diamond Communications, Vertical Bridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Infrastructure Market Strategic Shifts & Innovations
Virtualized radio access network functions are decoupling hardware from software control planes, enabling cloud-native deployment models that reshape capital allocation across the infrastructure stack.
Massive MIMO antenna arrays with 64+ transceiver elements are collapsing the cost-per-bit economics of urban capacity expansion. Tier-1 mobile network operators in Japan and South Korea deploy these systems at 3.5 GHz mid-band spectrum to serve dense pedestrian zones. The technology is collapsing traditional macro cell site counts by delivering equivalent coverage from fewer locations with higher spectral reuse.
The European Telecommunications Standards Institute's Open RAN security specifications create mandatory interoperability testing for baseband unit suppliers seeking CE marking eligibility. Equipment vendors must disclose firmware architectures and supply chain provenance to satisfy these mandates. European operators delay procurement decisions until certification completion, compressing vendor revenue recognition timelines.
Neutral host business models are displacing traditional carrier-owned infrastructure in US commercial real estate. Property developers pre-install distributed antenna systems and lease capacity to multiple operators through managed service agreements. This pattern concentrates most visibly in Las Vegas hospitality corridors and Manhattan office towers where tenant density justifies shared capital expenditure.
Wireless Infrastructure Market Segmentation
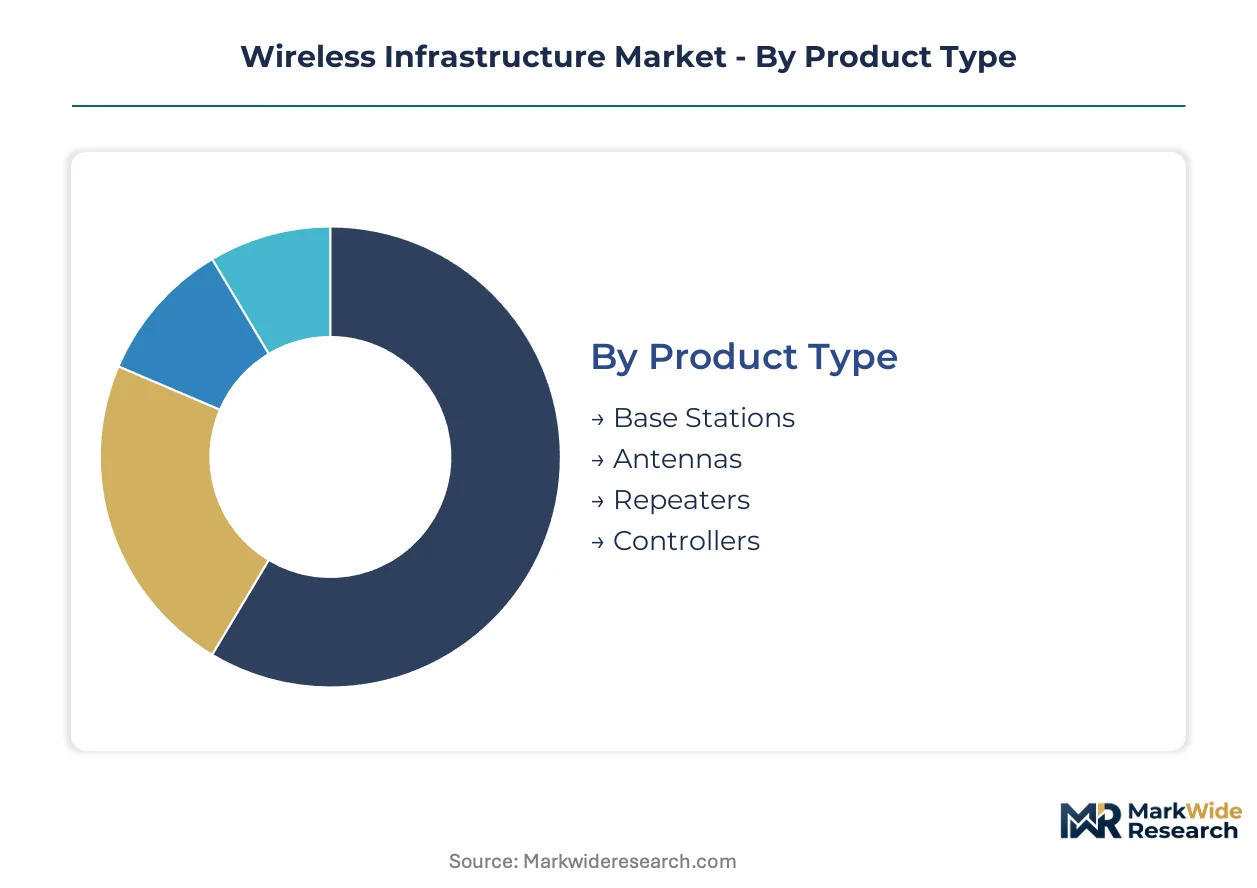
Wireless infrastructure segmentation reveals distinct procurement patterns across hardware categories, air interface standards, and buyer constituencies. Equipment vendors configure product portfolios differently for carrier macro deployments versus enterprise private networks. Understanding these segment boundaries clarifies where margin concentration and competitive intensity diverge.
Product Type:
Radio access hardware spans the full cost spectrum from semiconductor-dense active base stations to passive antenna arrays with minimal processing content.
- Base Stations:Active radio units integrate power amplifiers, baseband processors, and massive MIMO transceiver arrays operating across sub-6 GHz and millimeter-wave bands. India's TRAI-mandated rollout obligations concentrate demand in tier-2 and tier-3 urban corridors where fiber backhaul availability varies. Gallium nitride substrate scarcity constrains amplifier output power scaling.
- Antennas:Passive radiating elements with beamforming networks support carrier aggregation across 400+ MHz contiguous bandwidth. South Korean smart city densification programs drive volume for 3.5 GHz mid-band panel antennas. Commoditization pressure from Chinese suppliers compresses margin pools in emerging markets.
- Repeaters:Bi-directional amplifiers extend coverage into terrain-shadowed zones without fiber backhaul.
- Controllers:Centralized network management platforms orchestrate handovers and traffic engineering across multi-vendor radio access layers.
The dominant share belongs to Base Stations, while Antennas is closing the gap fastest.
Technology:
Air interface generations determine spectral efficiency targets and hardware refresh cadence across installed infrastructure bases.
- 5G:New radio specifications enable network slicing and ultra-reliable low-latency communication through beamformed millimeter-wave and mid-band massive MIMO. South Korea's nationwide densification program sustains Northeast Asian deployment leadership. Signal attenuation through vegetation limits rural coverage economics despite high spectral efficiency.
- LTE:Existing 4G infrastructure supports voice-over-LTE fallback and capacity layering during 5G non-standalone transition phases. Indian operators maintain dual-mode base stations to satisfy TRAI rollout obligations while spectrum refarming proceeds. Legacy 2G/3G decommissioning complexity inflates operational expenditure during migration windows.
- Wi-Fi:Unlicensed spectrum access points offload macro traffic in dense indoor venues.
- Microwave:Point-to-point radio links backhaul cell traffic where fiber trenching costs prove prohibitive in terrain-constrained deployments.
5G captures the largest absolute spending commitment, though Microwave retains structural importance in fiber-scarce topographies.
End User:
Buyer categories diverge sharply in procurement scale, technical specification authority, and vendor relationship structures.
- Telecom Operators:Licensed spectrum holders deploy macro and small cell infrastructure at national scale with multi-billion capital allocation cycles. American Tower Corporation's zoning-premium real estate concentration shapes colocation economics in top US metropolitan statistical areas. Open RAN architecture adoption reduces vendor lock-in and lowers total cost of ownership.
- Enterprises:Manufacturing and logistics facilities procure localized 5G networks for deterministic industrial automation. German automotive plants demand baseband units with guaranteed latency thresholds for robotic control systems. RF engineering talent scarcity constrains vendor scaling for specialized deployments.
- Government:Public sector agencies fund rural coverage mandates and emergency communications infrastructure.
- Utilities:Grid operators deploy private wireless for substation monitoring and distribution automation.
Telecom Operators command the dominant procurement volume, while Enterprises is expanding most quickly through private network adoption.
Application:
Use case requirements reshape radio access network design priorities from coverage-centric to latency-deterministic architectures.
- Smart Cities:Municipal sensor networks and traffic management systems demand ubiquitous connectivity with edge computing co-location. South Korean government programs fund microwave backhaul upgrades linking IoT sensors to centralized command centers. Neutral host business models displace carrier-owned infrastructure in US commercial real estate corridors.
- IoT:Massive machine-type communication specifications support low-power wide-area sensor density at reduced device cost points. European ETSI Open RAN security specifications mandate interoperability testing that delays procurement decisions until certification completion. Firmware disclosure requirements compress vendor revenue recognition timelines.
- Public Safety:Mission-critical voice and data services require hardened infrastructure with priority access mechanisms.
- Industrial Automation:Factory floor robotics and process control demand sub-10 millisecond latency with 99.999% reliability guarantees.
Smart Cities holds the leading deployment share, while Industrial Automation is gaining share fastest on manufacturing reshoring priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless infrastructure consumption varies sharply by geography: South Korea pursues nationwide 5G densification, India prioritizes tier-2 city coverage obligations, and Germany emphasizes industrial private networks. Each market deploys distinct spectrum strategies and vendor qualification frameworks.
United States
The Federal Communications Commission's Rural Digital Opportunity Fund subsidizes fixed-wireless access buildouts in underserved census blocks. Local zoning ordinances in metropolitan statistical areas extend tower permitting timelines and inflate lease escalation clauses. American Tower Corporation controls zoning-premium real estate in top US metros, dominating colocation economics.
South Korea
Government-backed smart city initiatives accelerate microwave backhaul upgrades linking municipal IoT sensors to centralized command centers. The Ministry of Science and ICT coordinates spectrum allocation for nationwide 5G densification programs. Seoul's urban corridors deploy massive MIMO arrays at 3.5 GHz mid-band to serve dense pedestrian zones.
India
Telecom operators expand 5G base station deployments under TRAI's spectrum allocation framework with rollout obligations tied to pricing. Tier-2 and tier-3 cities concentrate procurement where fiber backhaul availability varies. Mumbai and Delhi-NCR anchor carrier capex timing through dense subscriber clusters and enterprise demand.
Germany
Industrial automation in automotive plants creates demand for localized baseband units with deterministic latency guarantees. The Federal Network Agency enforces security requirements for critical infrastructure components. Bavaria's manufacturing corridors host private 5G network deployments for robotic control systems.
China
The Ministry of Industry and Information Technology governs base station certification under national GB standards, directly affecting vendor qualification timelines. National security review thresholds constrain foreign equipment participation in core network elements. Yangtze River Delta clusters concentrate domestic supplier manufacturing and testing protocols.
Wireless Infrastructure Market Key Industry Players
Capability concentration sits with integrated equipment vendors possessing radio access portfolios and in-house silicon development; scale advantage sits with tower operators controlling zoning-premium real estate and colocation economics. The market structures around three archetypes: telecom carriers with licensed spectrum holdings, infrastructure real estate owners, and network equipment manufacturers. Consolidation pressures intensify through Open RAN disaggregation and national security review thresholds. Strategic moves center on vertical integration into semiconductor supply chains and geographic diversification beyond concentrated East Asian foundries.
Among integrated equipment vendors, Ericsson and Nokia exemplify the capability-intensive tier with radio access portfolios spanning massive MIMO and baseband silicon. American Tower Corporation anchors the infrastructure real estate archetype through metropolitan zoning control. These three entities occupy positions that reflect the market's bifurcation between hardware-software integration and physical site economics.
| Leading Market Players |
|---|
| T-Mobile US |
| AT&T |
| American Tower Corporation |
| Ericsson |
| Nokia |
| Crown Castle |
| Verizon Communications |
| Diamond Communications |
| Vertical Bridge |
| Others |
Cost & Logistics Intelligence
Undercapacity in gallium nitride foundry capacity across East Asian semiconductor hubs is forcing equipment vendors into long-term offtake commitments that lock in component costs while compressing margin flexibility on base station deliveries to price-sensitive Indian and Southeast Asian carriers.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-1 carriers and integrated equipment vendors, insulating buyers from gallium nitride substrate volatility while exposing suppliers to fixed-price risk. Price differentiation rests on massive MIMO transceiver density and CE marking certification tier, with premium configurations commanding substantial uplifts over standard mid-band deployments. Cost compression in passive antenna arrays is intensifying because Chinese suppliers flood emerging markets with commoditized panel products. Enterprise private network buyers exhibit lowest price sensitivity due to deterministic latency requirements, while neutral host operators in US commercial real estate corridors negotiate aggressively on volume-based leasing structures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for baseband unit suppliers seeking FCC certification without triggering national security review thresholds. Manufacturing concentrates in China, South Korea, and Taiwan, with Yangtze River Delta clusters anchoring domestic vendor testing protocols for MIIT GB standard compliance. Raw material dependencies center on gallium nitride substrates, high-frequency laminates for antenna boards, and specialized baseband processors. Single-source vulnerability in East Asian foundry capacity for power amplifiers creates procurement bottlenecks during spectrum auction-driven deployment surges. Distribution runs through carrier-direct channels for macro deployments and systems integrators for enterprise private networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering expertise in massive MIMO beamforming algorithms commands premium compensation that constrains vendor scaling, creating persistent capability gaps between integrated equipment suppliers and modular Open RAN challengers.
For Market Incumbents: Insulate amplifier supply chains through captive gallium nitride foundry investments or strategic offtake partnerships with Taiwanese substrate specialists. Deepen backward integration into baseband silicon development to satisfy ETSI Open RAN security specifications and compress certification timelines. Defend against neutral host displacement by pre-installing distributed antenna systems in zoning-premium US commercial real estate corridors. For New Entrants and Emerging Players: Tier-2 Indian cities with TRAI-mandated rollout obligations and variable fiber backhaul availability represent the most penetrable entry point for disaggregated radio unit suppliers. German automotive private 5G networks for robotic control systems offer white-space demand for baseband units with deterministic latency guarantees. Pursue managed service partnerships with property developers rather than carrier-direct sales to bypass incumbent procurement lock-in. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tower operators controlling zoning-premium metropolitan real estate with long-term lease escalation clauses. Long-term viability favors infrastructure real estate owners over equipment vendors facing Open RAN margin compression and national security review barriers. Monitor FCC Rural Digital Opportunity Fund disbursement velocity as inflection signal for fixed-wireless access infrastructure buildout intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Investment | Captive substrate supply insulates Ericsson and Nokia from export control disruptions. |
| Open RAN Certification Acceleration | ETSI security specification compliance compresses European operator procurement delays. |
| Neutral Host Tower Pre-Installation | American Tower Corporation's zoning control locks in multi-tenant leasing economics. |
| Private 5G Systems Integration Partnership | Bavarian automotive corridor deployments create recurring service revenue streams. |
| Rural Digital Opportunity Fund Capture | FCC subsidies de-risk fixed-wireless access infrastructure capex in underserved census blocks. |
Research Approach
Desk research of FCC spectrum auction records, MIIT GB standard certification databases, and ETSI interoperability test reports preceded structured interviews with carrier network planning executives, base station procurement managers, tower operator leasing directors, and Open RAN systems integrators. Primary fieldwork validated vendor shipment data and deployment timelines against secondary trade flow analysis and regulatory filing disclosures. Bottom-up unit economics triangulated with top-down carrier capex allocation surveys to anchor market size estimates.
Assumptions held spectrum auction schedules, national security review thresholds, and gallium nitride foundry capacity expansion plans fixed across the projection horizon while varying carrier aggregation adoption rates and Open RAN penetration by operator archetype. Segmentation modeling spanned product type, air interface generation, buyer category, and application use case with regional regulatory cluster overlays. CAGRs derived from logistic diffusion curves fitted to historical deployment patterns and spectrum release cadence. Forecast inputs incorporated TRAI rollout obligation compliance rates and smart city infrastructure mandate funding trajectories.
Macroeconomic conditions sit as an overlay; deviation in carrier capex cycles, semiconductor capital equipment investment, or cross-border technology transfer restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding spectrum availability timelines and equipment certification protocol stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Global Optical Transport Network (OTN) Equipment Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
OTN Equipment Market