
 Global App Store Optimization Software Market | 2026-2036
Global App Store Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global App Store Optimization Software Market Foresight
The capability gap between cloud-native platforms and legacy on-premise toolkits is reorganizing competitive hierarchies across the ASO software landscape. AppTweak leverages proprietary keyword intelligence engines to anchor its position among mid-market app publishers seeking granular competitor benchmarking. Gummicube differentiates through specialized creative testing workflows that extend its reach into mobile gaming studios with high-volume release cycles. Sensor Tower dominates enterprise-grade market intelligence, sustaining pricing power through integrated app economy datasets that span both iOS and Android ecosystems.
App store optimization software encompasses algorithm-driven platforms engineered to improve mobile application visibility, conversion rates, and organic download velocity through metadata refinement, creative asset testing, and competitive intelligence aggregation. These systems process platform-specific ranking signals—including keyword relevance scores, user retention proxies, and review sentiment trajectories—to generate actionable recommendations for app publishers and marketing teams. Cloud-based deployment configurations lead the solution architecture landscape due to their native integration with real-time app store APIs and lower total cost of ownership for distributed development teams. Keyword research and A/B testing modules represent the fastest-expanding solution type categories as publishers prioritize systematic creative iteration over static metadata optimization. Mobile games command disproportionate ASO investment intensity among application segments, driven by compressed launch windows and lifetime value-dependent user acquisition economics.
The Federal Trade Commission scrutinizes misleading app store metadata claims in the United States, while the EU Digital Services Act imposes transparency obligations on platform operators that indirectly elevate ASO compliance complexity for publishers targeting European markets. China's MIIT enforces mobile app pre-approval requirements that create additional optimization layers for developers seeking visibility on domestic Android storefronts. Stakeholders must monitor evolving platform algorithm disclosures and fragmented regulatory disclosure requirements to calibrate tool investments against jurisdictional compliance exposure.
Market Dynamics
Platform algorithm opacity from Apple and Google is forcing ASO vendors to rebuild intelligence architectures around proxy signals rather than disclosed ranking factors, compressing margins for tool providers dependent on historical API access patterns.
Growth Catalysts
- Mobile gaming studios:Compressed launch windows and escalating paid user acquisition costs are redirecting marketing budgets toward systematic organic optimization workflows.
- EU Digital Services Act transparency mandates:Platform disclosure obligations are creating compliance-driven demand for automated metadata audit and monitoring capabilities among publishers targeting European markets.
- Real-time app store API integration:Cloud-native deployment architectures are lowering total cost of ownership for distributed development teams and accelerating vendor switching from on-premise legacy stacks.
Market Restraints
- Platform API access volatility:Unilateral changes to Apple App Store Connect and Google Play Console data feeds are disrupting tool reliability and forcing costly engineering pivots.
- Keyword intelligence commoditization:Proprietary ranking signal databases are losing differentiation as open-source alternatives and reverse-engineered methodologies proliferate.
- Regulatory fragmentation:Divergent pre-approval requirements from China's MIIT versus FTC metadata scrutiny in the United States are multiplying compliance architecture costs for multi-territory publishers.
Strategic Opportunities
- Creative asset automation:Generative AI pipelines for screenshot and video variant production are opening new module categories beyond static metadata optimization.
- India's domestic Android storefronts:Fragmented distribution through Samsung Galaxy Store, Amazon Appstore, and indigenous platforms is creating demand for multi-storefront optimization tooling absent in mature markets.
- Subscription app cohorts:Lifetime value-dependent publishers in fintech and health verticals are prioritizing retention-proxy optimization over pure download velocity, shifting ASO value metrics.
Industry Challenges
- Cross-functional talent scarcity:Bridging data science, platform policy expertise, and creative production workflows within single ASO teams remains structurally difficult for mid-market publishers.
- Attribution methodology disputes:Platform restrictions on device-level tracking are degrading organic install source identification and complicating ROI demonstration for ASO tool procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global App Store Optimization Software Market |
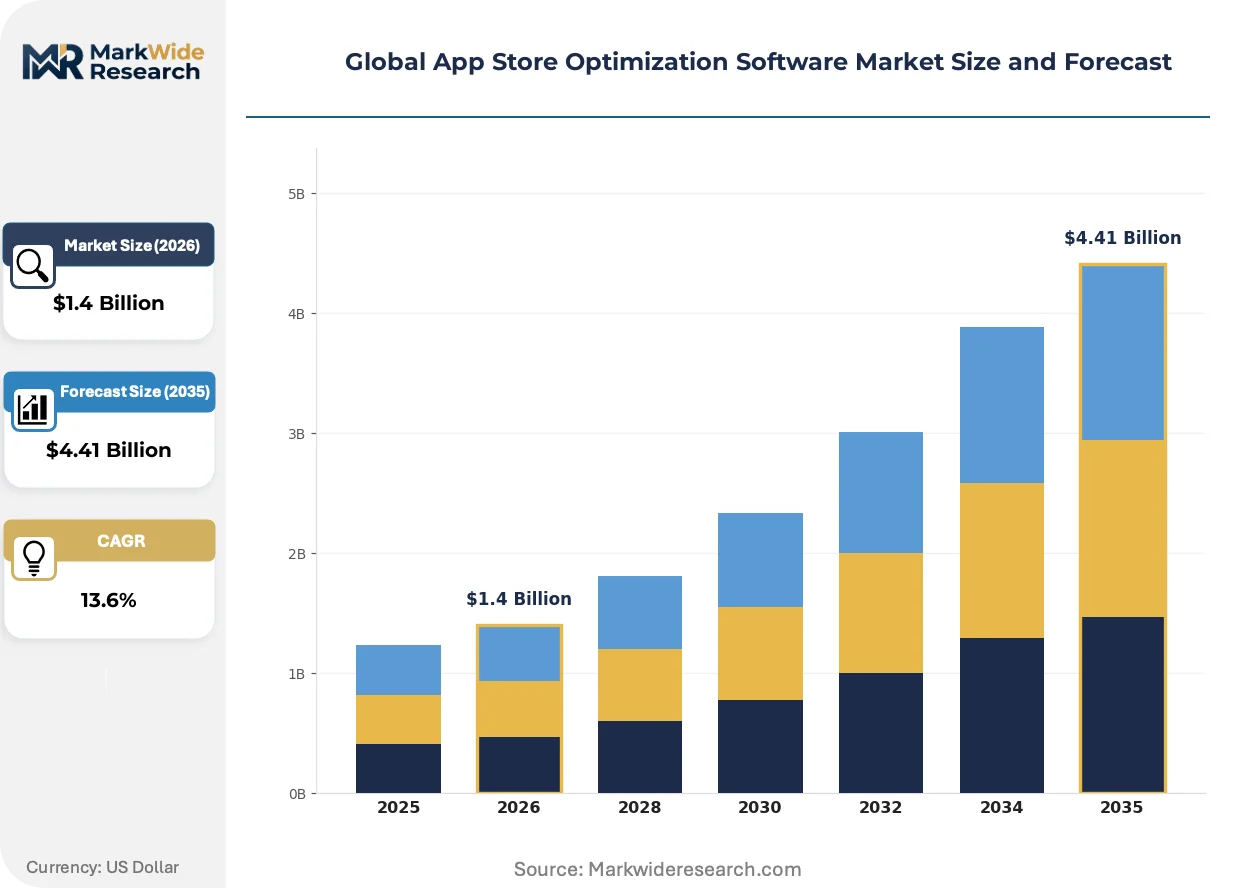
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Type: Keyword Research, Competitor Analysis, Review Management, A/B Testing, Performance Tracking Application: Mobile Games, Lifestyle Apps, Utility Apps, Education Tools, E-Commerce Platforms Customer Type: App Developers, Marketing Agencies, Independent Publishers, Startups, Technology Firms |
| Companies Covered | AppTweak, Adjust, Gummicube, AppFollow, Moburst, Sensor Tower, Mobile Action, Phiture, RankMyApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global App Store Optimization Software Market Shifts & Advancements
Generative AI is restructuring creative production pipelines while regulatory disclosure mandates and buyer procurement model evolution are simultaneously reshaping competitive positioning and vendor selection criteria.
Machine learning-driven creative variant generation is displacing manual screenshot and video production workflows in high-volume release environments. Mobile gaming studios with weekly or biweekly update cycles are adopting these systems fastest, compressing creative iteration timelines from days to hours and reducing dependency on specialized design headcount.
The EU Digital Services Act's algorithm transparency provisions are forcing platform operators to disclose ranking signal categories previously treated as proprietary. This regulatory pressure is fragmenting competitive advantage for ASO vendors that built moats around reverse-engineered signal inference, while creating new compliance tooling opportunities for automated disclosure alignment.
Enterprise procurement of ASO capabilities is consolidating from point-solution subscriptions toward integrated marketing intelligence platforms. Mid-market app publishers in the United States are bundling ASO with user acquisition and product analytics spend under single vendor relationships, compressing standalone tool pricing power and favoring providers with adjacent capability depth.
Global App Store Optimization Software Market Segmentation
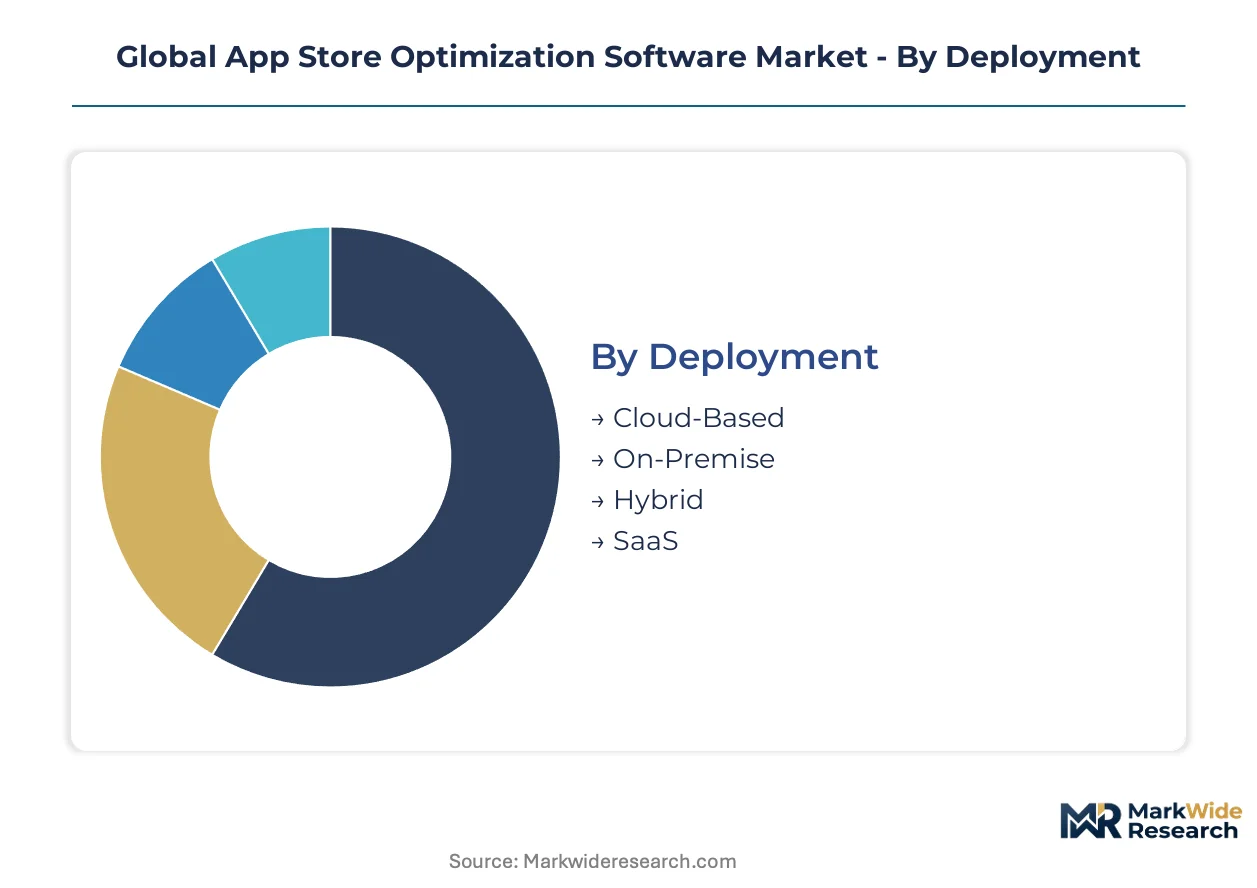
ASO software procurement patterns diverge sharply across deployment architectures and customer maturity levels. Platform algorithm opacity and compliance fragmentation are compressing viable solution configurations while elevating specialized module demand.
Deployment:
Substitution pressure from API-native architectures is accelerating obsolescence among legacy on-premise installations as real-time ranking signal processing becomes non-negotiable.
- Cloud-Based:Native integration with Apple App Store Connect and Google Play Console APIs enables continuous metadata synchronization without infrastructure overhead. Mobile gaming studios in the United States cluster procurement here due to compressed release cycles and distributed development teams.
- SaaS:Subscription pricing with tiered feature access lowers procurement friction for mid-market publishers. European marketing agencies facing EU Digital Services Act compliance deadlines are migrating toward these configurations for automated audit trails.
- Hybrid:Combines cloud-based processing with localized data residency for sensitive competitive intelligence. China's MIIT pre-approval workflows drive domestic publisher preference for this architecture.
- On-Premise:Legacy toolkit retention among risk-averse enterprise publishers with historical capital investments in data center infrastructure.
Cloud-Based deployments retain volume leadership; SaaS holds the steepest expansion curve.
Solution Type:
Cost tier stratification separates commoditized keyword databases from premium creative automation modules with generative AI integration.
- A/B Testing:Systematic screenshot and video variant experimentation with statistical significance testing for conversion rate optimization. Mobile gaming studios with weekly update cadences in San Francisco and New York concentrate demand here.
- Keyword Research:Proprietary ranking signal inference engines processing keyword relevance scores and search volume estimates. Independent publishers facing FTC metadata scrutiny in the United States prioritize these capabilities for compliance risk mitigation.
- Competitor Analysis:Benchmarking dashboards aggregating rival metadata strategies and creative asset rotations across iOS and Android storefronts.
- Review Management:Sentiment analysis pipelines and automated response workflows for user feedback at scale.
- Performance Tracking:Organic download attribution and retention-proxy monitoring against paid acquisition baselines.
A/B Testing commands premium pricing tiers; Keyword Research faces the steepest commoditization pressure.
Application:
Customer type concentration varies by lifetime value economics and launch velocity requirements across verticals.
- Mobile Games:Compressed launch windows and paid user acquisition cost escalation drive disproportionate ASO investment intensity. Studios in the United States deploy comprehensive module stacks across keyword, creative, and competitive intelligence functions.
- E-Commerce Platforms:Seasonal campaign synchronization with inventory systems and promotional calendar optimization. Retailers targeting India's fragmented Android storefronts require multi-platform tooling absent in mature markets.
- Lifestyle Apps:Subscription retention optimization through metadata iteration tied to cohort behavior analysis.
- Utility Apps:Functional utility positioning with minimal creative asset complexity and keyword-centric optimization.
- Education Tools:Institutional procurement cycles with compliance requirements from multiple jurisdictional education regulators.
Mobile Games retains revenue concentration; E-Commerce Platforms are expanding most quickly in emerging storefront fragmentation.
Customer Type:
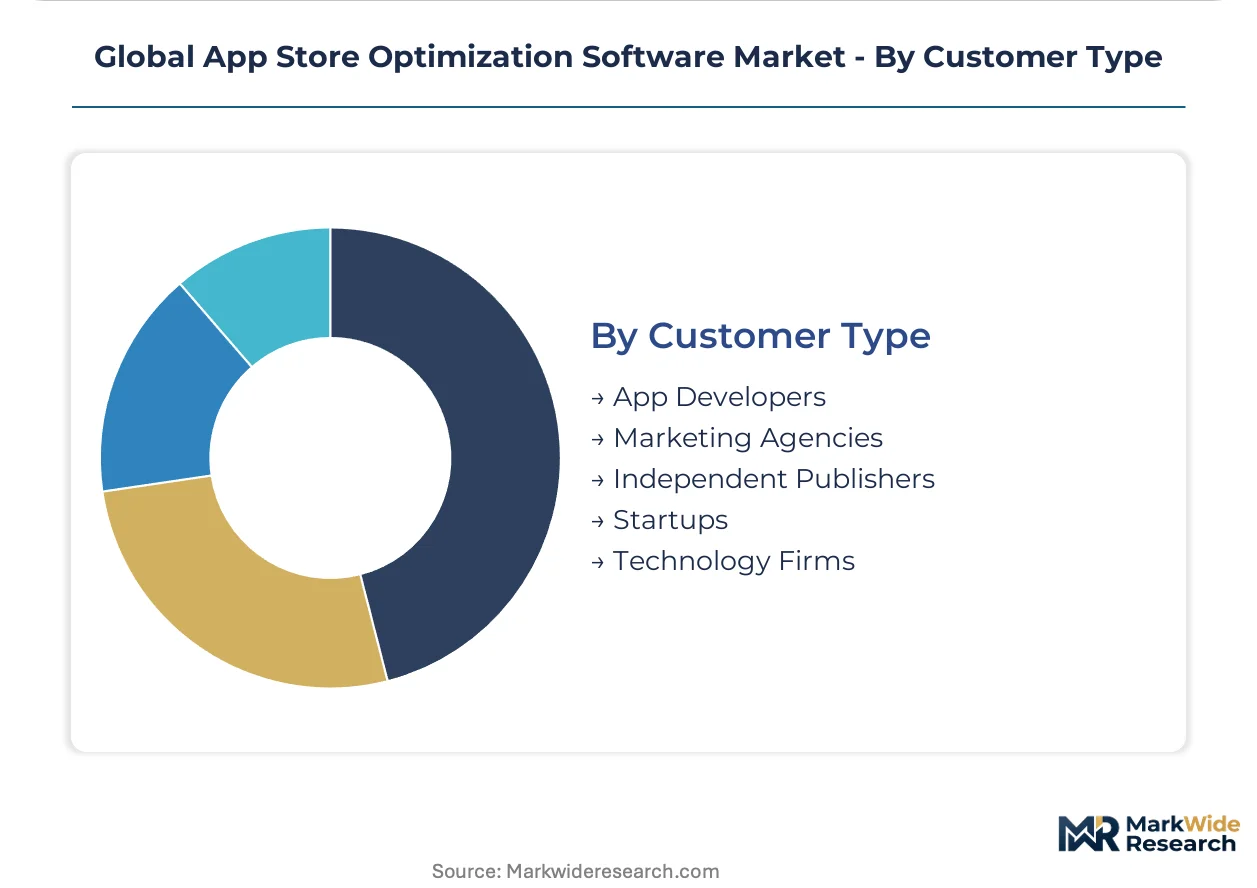
Volume scale separates enterprise technology firms with captive ASO capabilities from agency-mediated procurement among smaller publishers.
- Marketing Agencies:Multi-tenant platform configurations serving portfolio clients across verticals with standardized reporting frameworks. Agencies in New York cluster around integrated marketing intelligence bundling ASO with user acquisition spend.
- App Developers:Direct procurement of point solutions with API integration into continuous deployment pipelines. San Francisco-based developers lead adoption of generative AI creative automation.
- Technology Firms:In-house platform development or enterprise licensing of comprehensive intelligence suites.
- Independent Publishers:Cost-sensitive procurement of standalone modules with limited integration requirements.
- Startups:Freemium-tier entry with upgrade pathways contingent on funding milestones and user acquisition scaling.
Marketing Agencies retain client volume leadership; App Developers hold the steepest technology adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASO software consumption patterns diverge sharply by geography. The United States concentrates enterprise-grade platform procurement, while China and India prioritize fragmented Android storefront tooling. European markets emphasize compliance-automation capabilities driven by regulatory transparency mandates.
United States
San Francisco and New York host the densest clusters of app publishers and ASO service providers. The FTC scrutinizes misleading metadata claims, elevating audit and documentation requirements for domestic publishers. Mobile gaming studios in California deploy comprehensive module stacks across keyword research, creative testing, and competitive intelligence functions.
China
Domestic Android storefront fragmentation drives demand for multi-platform optimization tooling absent in iOS-dominant markets. MIIT enforces mobile app pre-approval requirements that create additional optimization layers for developers seeking visibility on domestic storefronts. Beijing and Shanghai-based publishers favor hybrid deployment architectures combining cloud processing with localized data residency.
India
Subscription pricing models attract mid-market publishers and marketing agencies serving portfolio clients across verticals. Samsung Galaxy Store, Amazon Appstore, and indigenous platforms fragment distribution, creating demand for multi-storefront tooling. Mumbai and Bangalore clusters concentrate developer talent and agency service delivery capabilities.
Germany
EU Digital Services Act transparency obligations elevate compliance-driven demand for automated metadata audit capabilities. GDPR alignment requirements intersect with platform disclosure mandates, complicating tool procurement for publishers targeting pan-European distribution. Berlin hosts marketing agencies migrating toward SaaS configurations for automated audit trail generation.
United Kingdom
London-based marketing agencies bundle ASO with user acquisition and product analytics spend under single vendor relationships. Post-Brexit regulatory divergence from EU frameworks creates parallel compliance architecture requirements for multi-territory publishers. The capital's fintech app publishers prioritize retention-proxy optimization over pure download velocity metrics.
Global App Store Optimization Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capability depth separating pricing power tiers. Enterprise-grade market intelligence providers sustain premium positioning through integrated app economy datasets spanning both iOS and Android ecosystems. Mid-market keyword intelligence specialists compete on granularity and competitor benchmarking workflows. Cloud-native deployment architectures and generative AI creative automation represent the dominant competitive moves reshaping vendor positioning.
Within the integrated intelligence tier, Sensor Tower exemplifies enterprise-grade platform positioning through comprehensive dataset integration. AppTweak and Gummicube occupy differentiated specialist positions—AppTweak anchoring keyword intelligence depth for competitor benchmarking, Gummicube representing creative testing workflow specialization for high-volume release environments. These three companies illustrate the archetype spectrum from horizontal platform breadth to vertical workflow depth.
| Leading Market Players |
|---|
| AppTweak |
| Adjust |
| Gummicube |
| AppFollow |
| Moburst |
| Sensor Tower |
| Mobile Action |
| Phiture |
| RankMyApp |
| Others |
Supply & Pricing Matrix
Three-to-five-day API provisioning cycles for cloud-native ASO platforms concentrate vendor engineering capacity in the United States and Ireland, compressing margin structures for providers dependent on real-time Apple and Google data feeds while elevating pricing power for those with captive infrastructure.
Pricing Analysis
Annual subscription contracts with tiered feature access dominate enterprise procurement, while project-based engagements serve mobile gaming studios with compressed release windows. Three-tier pricing structure across premium, standard, and economy levels separates Sensor Tower's integrated intelligence from AppTweak's keyword-specialist mid-market positioning and freemium entry points for independent publishers. Pricing pressure stems from keyword intelligence commoditization as open-source alternatives proliferate. Independent publishers exhibit highest price sensitivity; enterprise technology firms with bundled marketing intelligence spend demonstrate lowest.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure provisioning for ASO platforms, while India concentrates engineering talent for SaaS development and customer success functions. Proprietary ranking signal inference engines draw from Apple App Store Connect APIs, Google Play Console data feeds, and third-party competitive intelligence aggregators. Single-source vulnerability around unilateral API access changes from Apple and Google disrupts tool reliability without warning. Distribution runs through direct sales teams for enterprise accounts, self-service portals for mid-market publishers, and agency-mediated procurement for portfolio clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASO software procurement is consolidating toward integrated marketing intelligence platforms as interoperability requirements between user acquisition, product analytics, and organic optimization tools harden. This platform-economics inflection favors vendors with adjacent capability depth over standalone point solutions.
For Market Incumbents: Compound defensive positioning through backward integration into generative AI creative pipelines and geographic capacity expansion in India for engineering cost arbitrage. Keyword intelligence commoditization from open-source alternatives threatens margin structures; certification investment in EU Digital Services Act compliance automation creates switching costs for European agency clients. For New Entrants and Emerging Players: Creative asset automation for India's fragmented Android storefronts represents the most penetrable white-space opportunity, as Samsung Galaxy Store, Amazon Appstore, and indigenous platforms lack mature tooling. Subscription app cohorts in fintech and health verticals prioritize retention-proxy optimization over download velocity, opening consultative go-to-market angles absent in gaming-centric incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a vertical-SaaS consolidation play because enterprise procurement is bundling ASO with adjacent marketing intelligence spend under single vendor relationships. Acquisition targets should display cloud-native architecture, generative AI creative automation capabilities, and established agency channel relationships. Watch for Apple or Google algorithm transparency disclosures as inflection indicators that would revalue reverse-engineered signal inference moats.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Creative Automation | Machine learning pipelines compress screenshot production timelines from days to hours for mobile gaming studios. |
| Multi-Storefront Optimization Expansion | India's fragmented Android distribution creates tooling demand absent in iOS-dominant mature markets. |
| EU Compliance Automation Suite | Digital Services Act transparency mandates elevate automated metadata audit capabilities for European publishers. |
| Retention-Proxy Analytics Integration | Lifetime value-dependent subscription apps shift optimization metrics beyond pure download velocity. |
| Agency Channel Partnership Program | Marketing agencies in New York and London consolidate procurement under bundled vendor relationships. |
Research Methodology
Operator-level perspectives from ASO platform product managers, mobile gaming studio marketing directors, agency account leads, and app store policy specialists anchored the qualitative base. Secondary validation drew from Apple App Store Connect documentation, Google Play Console developer guidelines, SEC filings of public marketing intelligence firms, and EU Digital Services Act regulatory texts. Bottom-up sizing of module-level demand and top-down cross-checks against aggregate publisher spend established volume and value outputs.
Sensitivity analysis across deployment model, customer maturity tier, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included cloud versus on-premise architecture, solution type modularity, and vertical application concentration. CAGRs were derived from trend extrapolation of publisher tool procurement patterns and platform algorithm update frequencies. Forecast inputs incorporated Apple and Google API access policy trajectories and EU transparency mandate implementation timelines.
Forecasts assume regulatory continuity in FTC metadata scrutiny, EU Digital Services Act disclosure requirements, and China's MIIT pre-approval regimes; material policy shifts would require re-modeling. Platform algorithm opacity, API access volatility, and attribution methodology disputes constitute specific revision risks. Recalibration cycles align with material shifts in platform disclosure policies and enterprise procurement bundling behaviors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Driving School Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Online Lottery Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Warranty Management Software Market
Software & Services
Feedback Management Software Market
Software & Services
App Uninstall Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Global Guidewire Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Global Architecture Design Software Market
Software & Services
Machine Translation Software Market
Software & Services
Global Referral Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Online Paint Editor App Market