
 ASEAN Mobile Virtual Network Operator (MVNO) Market | 2026-2036
ASEAN Mobile Virtual Network Operator (MVNO) Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Mobile Virtual Network Operator (MVNO) Market Outlook
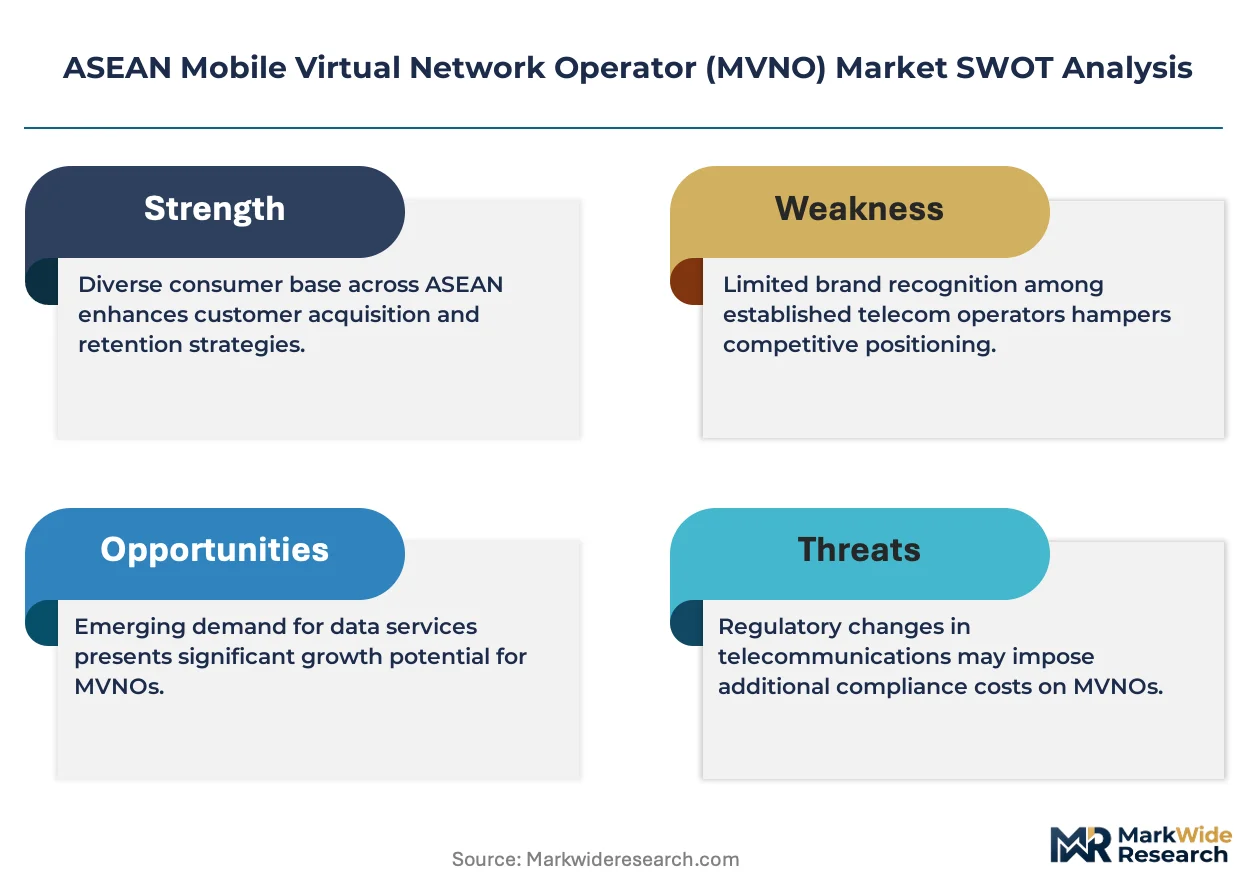
The gap between premium data-heavy postpaid tiers and bare-bones prepaid voice offerings is realigning competitive strategy across the ASEAN MVNO landscape. Circles.Life leverages cloud-native billing architecture to target urban millennials with customizable data pools. redONE Network Sdn Bhd anchors its position in Malaysia through aggressive dealer networks serving price-sensitive migrant worker segments. GOMO competes on simplicity, stripping retail overhead to deliver app-only plans in Singapore and the Philippines.
A Mobile Virtual Network Operator leases wholesale network capacity from licensed mobile network operators rather than owning physical radio infrastructure, typically operating through commercial agreements that specify minimum revenue guarantees and quality-of-service thresholds including latency below 50ms for 4G LTE and sub-10ms for 5G slices. The model exists primarily to extend mobile service penetration into underserved demographics and vertical enterprise use cases without requiring spectrum auction participation. Prepaid plans dominate volume across ASEAN due to thin credit infrastructure and high cash economy participation, while IoT connectivity represents the fastest-expanding service type as fleet operators and smart-city contractors seek cellular-enabled sensors. Enterprise clients command superior unit economics despite lower subscriber counts, since wholesale host networks offer volume-tiered data rates that improve MVNO margins on bulk connectivity contracts.
Malaysian Communications and Multimedia Commission licensing frameworks mandate wholesale access pricing transparency, while Indonesia's Ministry of Communication and Informatics enforces domestic data residency rules that shape MVNE partner selection. Singapore's Infocomm Media Development Authority imposes strict service-quality benchmarks that filter out undercapitalized entrants. Stakeholders must monitor spectrum refarming timelines in Thailand and the Philippines to anticipate 5G wholesale rate resets before committing to long-term host network agreements.
Market Dynamics
5G spectrum refarming across member states is compressing wholesale access costs and forcing host network operators to renegotiate legacy MVNO agreements ahead of 2030 renewal cycles.
Growth Catalysts
- TRAI-style numbering reforms:Indonesia's Ministry of Communication and Informatics is implementing mobile number portability frameworks that reduce subscriber switching friction and accelerate MVNO customer acquisition in Southeast Asia's largest prepaid market.
- Enterprise fleet digitization:Manufacturing and logistics operators in Vietnam are replacing fixed-line factory networks with cellular-enabled IoT sensors, creating bulk connectivity contracts that improve MVNO unit economics through volume-tiered wholesale rates.
- Cloud-native billing platforms:Containerized charging systems are enabling real-time plan customization that matches prepaid digital-first offerings to unbanked consumer cash-flow patterns across ASEAN urban corridors.
Market Restraints
- Host network concentration:Wholesale capacity in Thailand and the Philippines concentrates among three incumbent MNOs, limiting MVNO negotiating leverage on minimum revenue guarantees and quality-of-service thresholds.
- Domestic data residency mandates:Indonesia's data localization rules constrain MVNE partner selection to locally certified infrastructure providers, extending platform deployment timelines by 6-12 months.
- Fixed wireless substitution:Fiber-to-the-home rollout in Singapore and Malaysia urban centers is capturing high-ARPU postpaid subscribers who would otherwise upgrade to premium MVNO data tiers.
Strategic Opportunities
- Myanmar connectivity gap:Underdeveloped mobile infrastructure in secondary cities creates first-mover potential for MVNOs leasing excess capacity from Thai border host networks.
- Embedded SIM convergence:eSIM provisioning combined with travel-wallet apps is eliminating physical SIM logistics for regional migrant worker segments who maintain dual-country subscriptions.
- Malaysian wholesale transparency:MCMC-mandated access pricing disclosure is enabling new entrants to model unit economics before committing to host network agreements.
Industry Challenges
- Legacy billing integration:MVNOs acquiring regional competitors face 18-24 month system consolidation timelines to harmonize prepaid voucher redemption across incompatible charging platforms.
- 5G slice certification:Sub-10ms latency guarantees for enterprise IoT contracts require host network API access that remains technically unstandardized across ASEAN member state implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Mobile Virtual Network Operator (MVNO) Market |
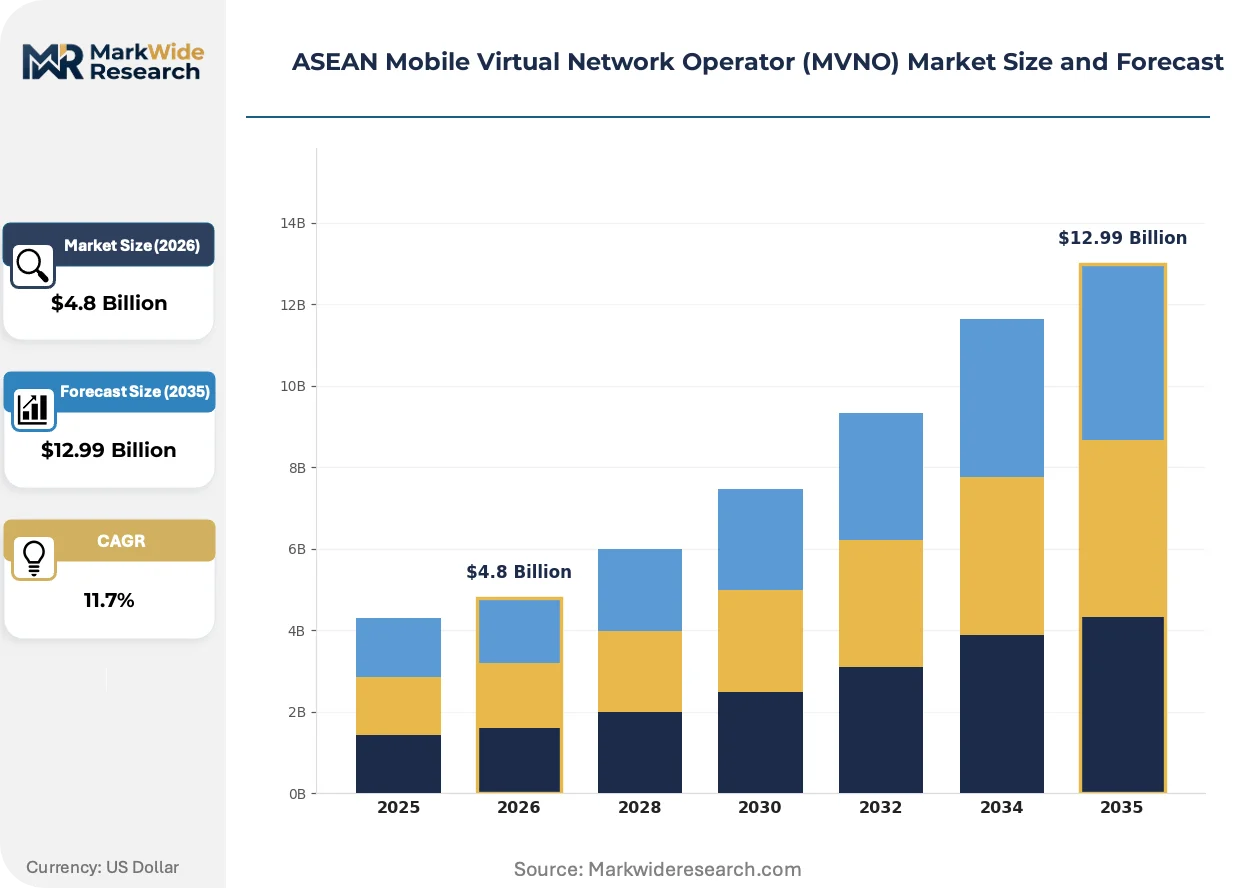
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Postpaid, Prepaid, Hybrid, IoT Connectivity Customer Type: Retail Consumers, Enterprise Clients, Resellers, Wholesale Technology: 4G LTE, 5G, VoLTE, Cloud-based Services Offering: Data-only Plans, Voice Plans, Bundled Services, MVNE Support |
| Companies Covered | Circles.Life, GOMO, redONE Network Sdn Bhd, Tune Talk Sdn Bhd, XOX Mobile Sdn Bhd, MyRepublic Limited, Ansar Mobile Sdn Bhd, Merchantrade Asia Sdn Bhd, One XOX Sdn Bhd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Mobile Virtual Network Operator (MVNO) Market Strategic Shifts
Cloud-native operational models are displacing traditional telecom infrastructure dependencies across the ASEAN MVNO landscape, compressing time-to-market for new service launches from years to months.
Containerized network function virtualization is electrifying core network deployment for MVNOs operating without physical radio assets. Indonesian and Vietnamese entrants are adopting Kubernetes-orchestrated charging systems within 90-day implementation windows. This architecture is compressing capital requirements for national-scale launches from legacy telecom norms.
Malaysian Communications and Multimedia Commission wholesale pricing transparency mandates are forcing host network operators to publish standardized access rate cards. Industrial consequence includes accelerated MVNO entry in Johor and Penang manufacturing corridors. Enterprise connectivity segments are responding by consolidating multi-site contracts under single MVNO umbrellas.
App-only distribution is displacing retail dealer networks as the primary subscriber acquisition channel across ASEAN prepaid markets. GOMO and comparable digital-first operators are stripping physical storefront overhead to fund data-heavy plan subsidies. This channel compression is most visible in Singapore and Metro Manila where smartphone penetration exceeds 85 percent.
ASEAN Mobile Virtual Network Operator (MVNO) Market Segmentation
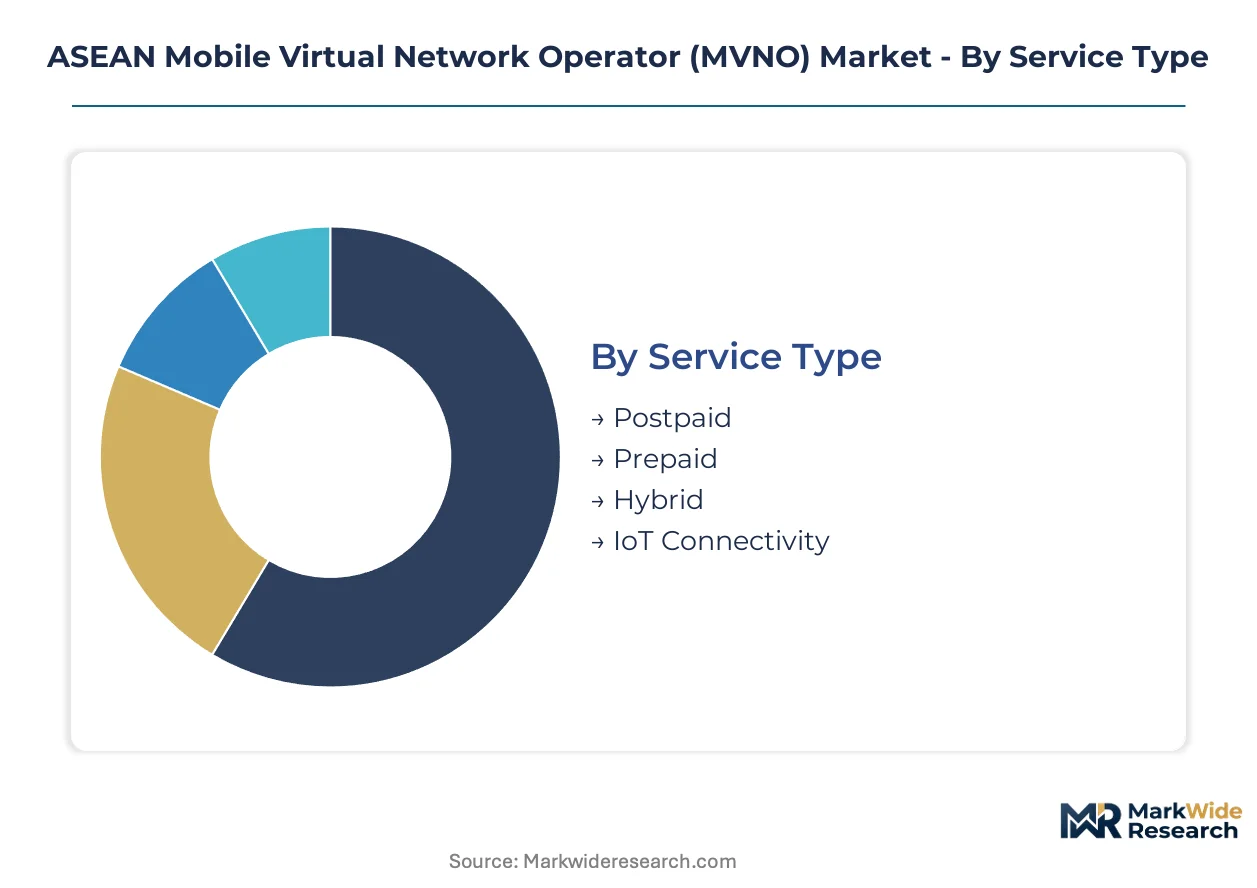
ASEAN MVNOs slice their addressable market through four intersecting dimensions that determine wholesale access negotiations and customer acquisition economics. Service type and customer category dictate margin structure, while technology generation and plan architecture shape operational complexity.
Service Type:
Prepaid-to-postpaid upgrade cycles and IoT contract renewals drive revenue timing across this dimension, with cash-flow patterns diverging sharply between consumer and machine-to-machine segments.
- Prepaid:Digital voucher redemption dominates across Indonesia and Vietnam where unbanked populations favor cash-based top-ups. Thin credit infrastructure and migrant worker mobility sustain this as the volume anchor.
- Postpaid:Monthly billing with credit checks attracts urban professionals in Singapore and Kuala Lumpur. Higher ARPU justifies customer acquisition costs, though subscriber bases remain concentrated in Tier-1 cities.
- Hybrid:Pay-as-you-go buckets with automatic rollover appeal to price-sensitive segments seeking flexibility without full prepaid friction. Malaysian dealer networks push these plans to factory workers near Johor manufacturing zones.
- IoT Connectivity:Fleet operators in Vietnam and Thai logistics corridors purchase bulk sensor data pools. Volume-tiered wholesale rates from host networks improve unit economics despite lower per-connection revenue.
Volume placements concentrate in Prepaid; the faster expansion belongs to IoT Connectivity.
Customer Type:
Enterprise procurement cycles stretch 12-18 months but lock in multi-year connectivity commitments, while retail churn rates exceed 25% annually in price-competitive prepaid corridors.
- Enterprise Clients:Manufacturing and logistics operators replace fixed-line factory networks with cellular-enabled sensors. Bulk contracts spanning multiple sites command superior wholesale rates from host MNOs.
- Retail Consumers:Urban millennials in Metro Manila and Jakarta select customizable data pools through app-only interfaces. Digital-first distribution strips retail overhead to fund competitive pricing.
- Resellers:Dealer networks in Malaysian border states serve migrant worker segments with dual-country SIM requirements. Physical storefronts maintain relevance where smartphone penetration lags.
- Wholesale:Smaller MVNOs and international operators lease aggregated capacity for regional expansion. Minimum revenue guarantees and quality-of-service thresholds structure these commercial agreements.
Retail Consumers generate the highest subscriber counts; Enterprise Clients deliver the steepest margin expansion.
Technology:
4G-to-5G migration timelines vary across member states, with spectrum refarming in Thailand and the Philippines resetting wholesale rate negotiations ahead of contract renewals.
- 4G LTE:Latency guarantees below 50ms support current voice and data services across all ASEAN markets. Legacy infrastructure remains the default for cost-sensitive prepaid offerings.
- 5G:Sub-10ms network slices enable enterprise IoT contracts requiring real-time sensor feedback. Host network API access remains technically unstandardized across national implementations.
- VoLTE:Voice-over-LTE improves spectral efficiency and enables simultaneous voice-data sessions. Singapore's IMDA mandates this as baseline for new service launches.
- Cloud-based Services:Containerized charging systems compress MVNO launch timelines from years to months. Kubernetes-orchestrated platforms deploy within 90-day windows in Indonesia and Vietnam.
4G LTE still carries the majority of connections; 5G is climbing the fastest as enterprise contracts migrate.
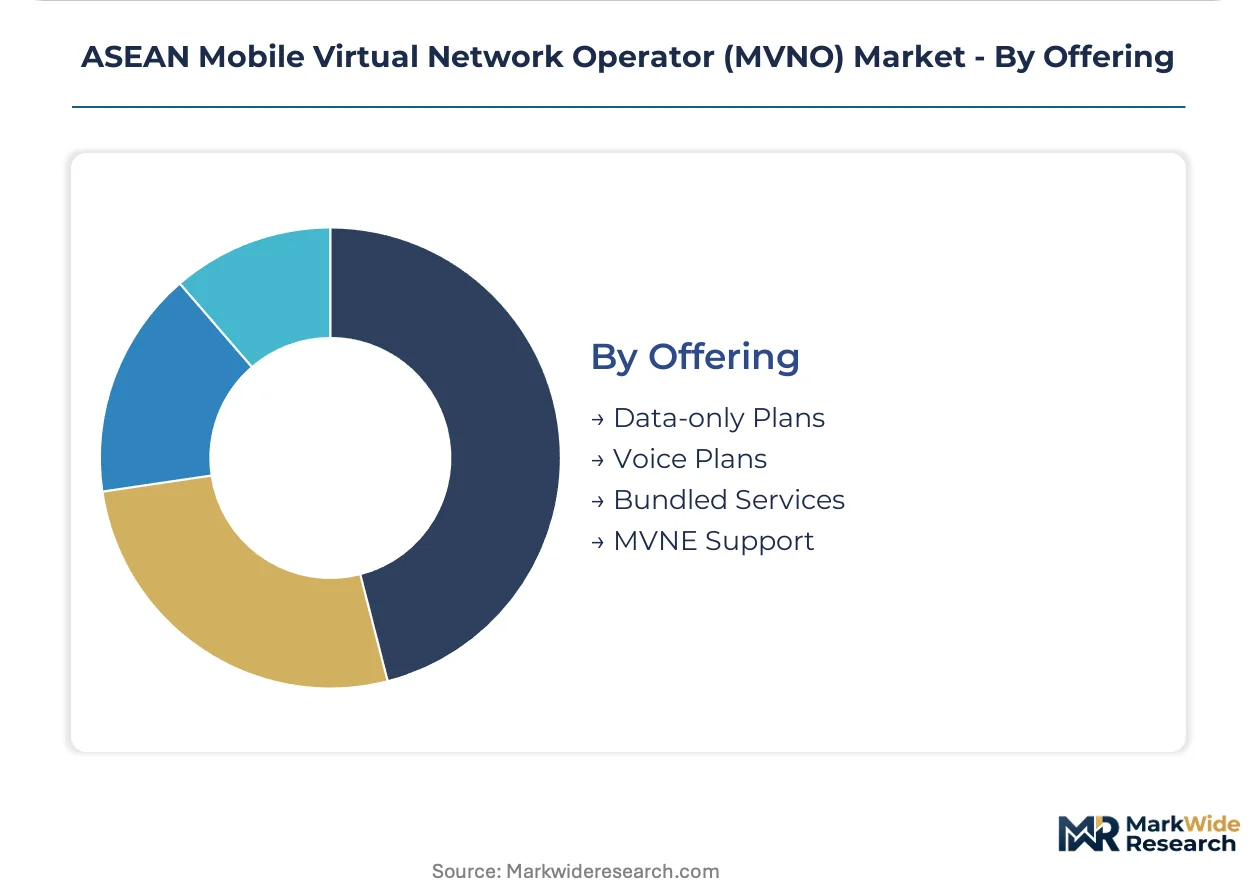
Offering:
Plan architecture determines customer lifetime value, with bundled services reducing churn while data-only offerings maximize appeal to tablet and IoT device owners.
- Data-only Plans:Target tablet users, mobile hotspots, and secondary device owners. GOMO and comparable digital operators strip voice infrastructure to fund heavier data allocations.
- Voice Plans:Basic talk-and-text offerings retain price-sensitive segments in rural Indonesia and secondary Vietnamese cities. Thin margins limit host network negotiating leverage.
- Bundled Services:Combined voice, data, and content subscriptions reduce subscriber acquisition costs through stickier relationships. Circles.Life customizes these pools for urban professional segments.
- MVNE Support:Infrastructure-as-a-service enables rapid market entry without proprietary billing platform investment. Indonesia's data residency rules constrain partner selection to locally certified providers.
Data-only Plans dominate new subscriber additions; Bundled Services show the strongest retention economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors MVNO activity across Southeast Asia, hosting the region's largest prepaid subscriber base and driving cloud-native platform adoption among digital-first operators.
Indonesia
Urban millennials in Jakarta and Surabaya demand customizable data pools through app-only interfaces. The Ministry of Communication and Informatics enforces domestic data residency rules that constrain MVNE partner selection to locally certified providers. Manufacturing corridors in Batam and Bekasi are replacing fixed-line factory networks with cellular-enabled IoT sensors.
Vietnam
Logistics operators in Ho Chi Minh City and Hai Phong purchase bulk sensor data pools for fleet digitization. The national telecommunications regulator mandates mobile number portability frameworks that reduce subscriber switching friction. Industrial zones in Binh Duong and Dong Nai are consolidating multi-site connectivity contracts under single MVNO umbrellas.
Singapore
High smartphone penetration in the city-state drives app-only distribution models that strip retail overhead. The Infocomm Media Development Authority imposes strict service-quality benchmarks including sub-10ms latency guarantees for 5G slices. Marina Bay and Jurong East financial districts command premium postpaid tiers with bundled content subscriptions.
Malaysia
Price-sensitive migrant worker segments in Johor and Penang sustain dealer network distribution for dual-country SIM requirements. The Malaysian Communications and Multimedia Commission mandates wholesale access pricing transparency that accelerates new entrant modeling. Manufacturing zones near the Singapore border are capturing enterprise fleet contracts through volume-tiered wholesale rates.
Philippines
Metro Manila's dense urban population supports digital-first prepaid plans with heavy data allocations. The national telecommunications commission monitors spectrum refarming timelines that reset 5G wholesale rate negotiations. Cebu and Davao secondary cities present expansion targets as fiber-to-the-home rollout remains uneven.
ASEAN Mobile Virtual Network Operator (MVNO) Market Competitive Environment
Capital-heavy host network operators compete with asset-light digital MVNOs for subscriber relationships across ASEAN prepaid corridors. The vendor base concentrates around three strategic tiers: cloud-native app-only operators, dealer-network-dependent traditionalists, and enterprise-focused IoT specialists. Consolidation pressure is mounting as spectrum refarming forces wholesale agreement renegotiations ahead of renewal cycles. Dominant competitive moves include M&A-driven subscriber base consolidation and strategic partnerships with containerized billing platform providers.
Within the cloud-native tier, Circles.Life and GOMO exemplify asset-light positioning through customizable data pools and stripped retail overhead. Among dealer-network operators, redONE Network Sdn Bhd anchors traditional distribution models serving price-sensitive segments. These three entities represent divergent responses to the same underlying pressure: compressing customer acquisition costs while maintaining service quality thresholds mandated by national regulators.
| Leading Market Players |
|---|
| Circles.Life |
| GOMO |
| redONE Network Sdn Bhd |
| Tune Talk Sdn Bhd |
| XOX Mobile Sdn Bhd |
| MyRepublic Limited |
| Ansar Mobile Sdn Bhd |
| Merchantrade Asia Sdn Bhd |
| One XOX Sdn Bhd |
| Others |
Value Chain & Pricing Dynamics
Wholesale spectrum lease rates in Thailand and the Philippines cascade through MVNO cost structures into prepaid voucher pricing tiers, compressing margins for digital-first operators while dealer-network traditionalists absorb friction through physical distribution overhead.
Pricing Analysis
Throughput-based data pooling anchors MVNO pricing architecture, with enterprise IoT contracts commanding premium rates for sub-10ms latency guarantees while prepaid voice plans compete on per-minute transactional economics. Price differentiation rests on quality-of-service thresholds and volume-scale commitments, with host network API access tiers separating premium enterprise slices from economy consumer data buckets. Cost compression in prepaid corridors intensifies as GOMO-style app-only operators strip retail overhead to fund heavier data allocations. Migrant worker segments in Malaysian border states exhibit highest price sensitivity, while Singapore financial district enterprises show least elasticity for bundled 5G services.
Supply Chain Analysis
Dual-sourcing requirements for cloud-native billing platforms mandate MVNE qualification across both Indonesian and Vietnamese infrastructure providers, extending procurement timelines. Geographic supply concentration centers on Singapore for containerized network function virtualization software, Malaysia for dealer network logistics, and Thailand for excess wholesale capacity. Raw material dependencies include Kubernetes-orchestrated charging systems, eSIM provisioning infrastructure, and spectrum lease agreements. Single-source vulnerability concentrates in host network API access for 5G network slices, where technical standardization remains fragmented. Distribution runs through app-only interfaces in high-smartpenetration markets and dealer networks where cash economies persist.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN MVNO landscape is becoming a vertical-integration race, with players pursuing backward control over cloud-native billing infrastructure to escape MVNE margin extraction.
For Market Incumbents: Anticipate spectrum refarming timelines in Thailand and the Philippines to renegotiate wholesale agreements before renewal cycles lock in legacy rate structures. Consolidate subscriber bases through targeted acquisitions of regional competitors facing 18-24 month billing system consolidation delays. Defensive moves should prioritize certification investment for sub-10ms latency guarantees that enterprise IoT contracts demand. For New Entrants and Emerging Players: The gap between premium postpaid tiers and bare-bones prepaid voice offerings opens white-space targeting for hybrid pay-as-you-go buckets with automatic rollover. Manufacturing corridors in Batam and Bekasi present the most penetrable enterprise segment, with fleet digitization contracts consolidating under single MVNO umbrellas. Go-to-market execution should leverage Malaysian Communications and Multimedia Commission-mandated wholesale pricing transparency to model unit economics before host network commitment. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native app-only operators with containerized billing platforms in Indonesia, where domestic data residency rules constrain MVNE partner selection and extend deployment timelines for undercapitalized entrants. Long-term viability hinges on enterprise IoT contract share rather than retail subscriber scale. Watch host network API standardization progress across ASEAN member states as the inflection indicator for 5G slice monetization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Billing Migration | Kubernetes-orchestrated platforms compress MVNO launch timelines from years to months in Jakarta and Ho Chi Minh City. |
| Enterprise IoT Contract Consolidation | Volume-tiered wholesale rates from host MNOs improve unit economics for Vietnamese logistics fleet operators. |
| eSIM Provisioning Integration | Travel-wallet app convergence eliminates physical SIM logistics for regional migrant worker dual-country subscriptions. |
| Wholesale Agreement Renegotiation | 5G spectrum refarming in Thailand and the Philippines resets rate structures ahead of legacy contract renewals. |
| Dealer Network Optimization | Johor and Penang physical storefronts retain relevance where smartphone penetration lags behind Singapore levels. |
Study Parameters
Independent corroboration across host network wholesale pricing disclosures, national regulatory filings, and enterprise connectivity contract documentation underwrites the qualitative findings. Primary interviews with MVNO platform engineers, host network commercial officers, enterprise fleet procurement managers, and cloud infrastructure architects combined with secondary validation from MCMC access rate cards, Indonesian Ministry of Communication and Informatics data residency certifications, and Singapore IMDA service quality benchmarks. Bottom-up subscriber modeling and top-down spectrum lease revenue triangulation anchored market sizing.
Comparable-period anchoring to prepaid voucher redemption cycles and IoT contract renewal seasons structured the forecast window across the projection horizon. Segmentation dimensions modeled include service type, customer category, technology generation, and plan architecture, with additional granularity on domestic data residency compliance tiers. CAGRs derived from volume-weighted wholesale rate trajectories and enterprise contract penetration curves. Industry-specific inputs incorporated spectrum refarming timelines and containerized billing platform adoption velocities.
Inputs from host network wholesale agreements and national regulatory filings were available through the study window; gaps in standardized 5G network slice API specifications introduce uncertainty bands around enterprise IoT revenue projections. Forecasts reflect assumptions on mobile number portability implementation pace and cloud-native platform deployment timelines. Deviation in spectrum refarming coordination across Thailand and the Philippines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Malaysia Telecom Market
Telecommunications
Indonesia Telecom Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
5G Connections Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
5G Transport Networks Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Cloud RAN Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
GSM Mobile Phone Market