
 Light Fidelity Market | 2026-2036
Light Fidelity Market Size, Share, and Industry Trends Forecast 2026-2036
Light Fidelity Market Outlook
A shift from outsourced component procurement to in-house photonic chip fabrication is hardening among established Li-Fi vendors. pureLiFi sustains its early-mover advantage through captive semiconductor design capabilities in Scotland. Oledcomm anchors European demand by specializing in aviation-certified visible light communication systems for Airbus assembly lines. Signify Holding leverages its installed base of LED luminaires to bundle Li-Fi modules into commercial lighting retrofits.
Light Fidelity denotes a wireless communication technology that transmits data through modulated visible light, typically operating at wavelengths between 400 and 800 nanometers and achieving theoretical speeds exceeding 224 gigabits per second under laboratory conditions. Its primary purpose is to deliver high-bandwidth, low-latency connectivity in environments where radio frequency interference must be eliminated or spectrum congestion demands alternative carriers. Indoor Networking applications currently command the largest revenue share as enterprises replace Wi-Fi in secure conference facilities and hospital operating theaters. Smart Cities represents the fastest-expanding application segment as municipalities embed Li-Fi transceivers into streetlight infrastructure for traffic management and public safety networks. The Transportation end-user category is attracting concentrated R&D investment from rail operators seeking continuous connectivity through tunnels where cellular signals degrade.
The FCC governs unlicensed visible light spectrum usage in the United States, while ETSI and the IEEE 802.11bb task group establish interoperability standards across European and Asian markets. These frameworks determine which hardware configurations achieve market access and influence procurement specifications for defense and healthcare buyers. Stakeholders must monitor how national spectrum allocations for 6 GHz Wi-Fi will compete with or complement Li-Fi deployment strategies in enterprise settings.
Market Dynamics
Li-Fi deployment is absorbing capital from radio-frequency infrastructure budgets as enterprises confront electromagnetic interference constraints in medical and manufacturing environments. Semiconductor fabrication capabilities are concentrating among vendors who control photonic chip design in-house.
Growth Catalysts
- IEEE 802.11bb standardization:The task group's interoperability framework is eliminating fragmentation across Asian and European procurement specifications. Defense contractors now specify compliant hardware in secure facility tenders.
- Healthcare electromagnetic sensitivity:Hospital operating theaters in Germany and the United States are mandating RF-free zones for surgical robotics. Li-Fi satisfies these requirements without cable installation.
- LED luminaire retrofit cycles:Commercial building owners are bundling communication modules into lighting upgrades. This piggybacks on existing electrical contractor relationships and accelerates deployment velocity.
Market Restraints
- III-V semiconductor supply concentration:Gallium nitride substrate fabrication concentrates among Asian foundries. Price volatility in indium phosphide wafers compresses module margins for European integrators.
- Line-of-sight limitation:Physical obstruction requirements restrict mobility applications. Warehouse automation buyers retain Wi-Fi for inventory drones despite Li-Fi bandwidth advantages.
- Spectrum allocation friction:The FCC's unlicensed visible light framework conflicts with municipal streetlight ownership structures. Smart city procurement delays while liability models clarify.
Strategic Opportunities
- Rail tunnel connectivity gaps:Deutsche Bahn and Japanese rail operators are piloting continuous Li-Fi coverage through electromagnetic-shielded tunnels. This addresses cellular dead zones without leaky feeder cable maintenance.
- Aviation assembly certification:EASA-aligned manufacturing protocols for electromagnetic-sensitive aircraft production create a regulatory moat. Specialized integrators capture this vertical before generalist entrants adapt.
- Micro-LED convergence:Display panel manufacturers are integrating transceiver functions into screen backlights. Consumer electronics and automotive HUD applications emerge from this technology fusion.
Industry Challenges
- Photonic IC design talent scarcity:Compound semiconductor expertise concentrates among legacy telecom vendors. Li-Fi specialists compete for analog circuit designers against lidar and optical computing recruiters.
- Legacy building integration complexity:Existing BMS protocols and PoE infrastructure require middleware development. System integrators absorb unexpected commissioning costs in early commercial deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Fidelity Market |
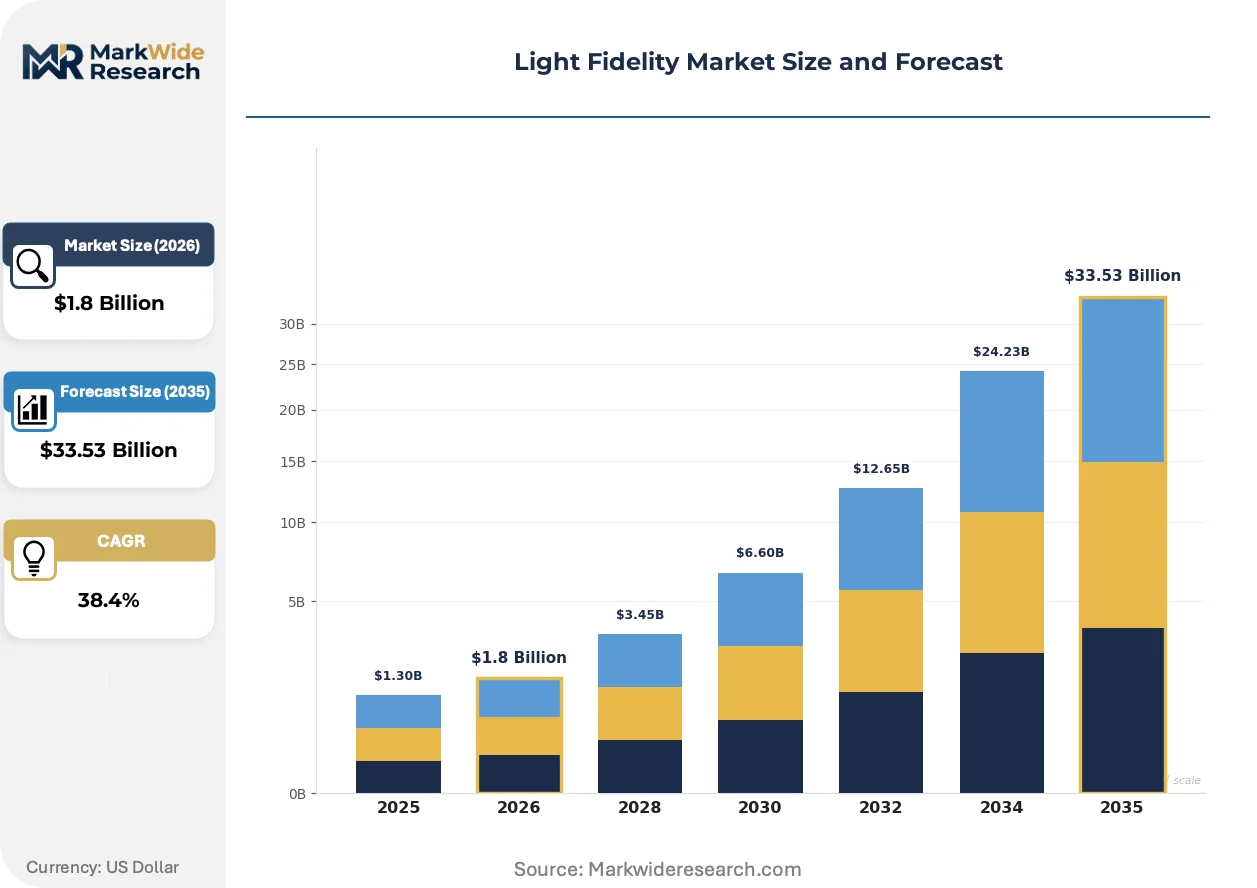
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.53 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Indoor Networking, Outdoor Connectivity, Smart Cities, Healthcare Technology: Li-Fi, VLC, Smart Lighting, Network Infrastructure End User: Retail, Education, Hospitality, Transportation Deployment: Enterprise, Residential, Industrial, Government |
| Companies Covered | pureLiFi, Oledcomm, Signify Holding, LightPointe Communications, Inc., Lucibel, Acuity Brands Lighting, Inc., Panasonic Corporation, Velmenni OÜ, VLNComm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Fidelity Market Strategic Shifts
Visible light communication is absorbing functionality from adjacent optical technologies as solid-state lighting and sensing converge. Three developments are compressing deployment timelines and reshaping competitive positioning.
Organic photodetector arrays are absorbing silicon CMOS sensor market share in indoor positioning applications. These flexible substrates enable curved luminaire designs that Wi-Fi access points cannot replicate. Hospital architects in the Netherlands and Singapore are specifying these configurations for patient tracking without RF exposure.
The EU AI Act's risk classification framework is extending to connected infrastructure procurement. Municipal buyers must document algorithmic transparency in traffic management systems. German smart city tenders now require Li-Fi vendors to submit conformity assessments alongside technical specifications.
Building operators are unbundling connectivity from facilities management contracts. Previously bundled Wi-Fi services now separate into distinct procurement decisions. This disintermediation favors specialized Li-Fi integrators in London and New York commercial real estate markets where landlords retain infrastructure ownership.
Light Fidelity Market Segmentation
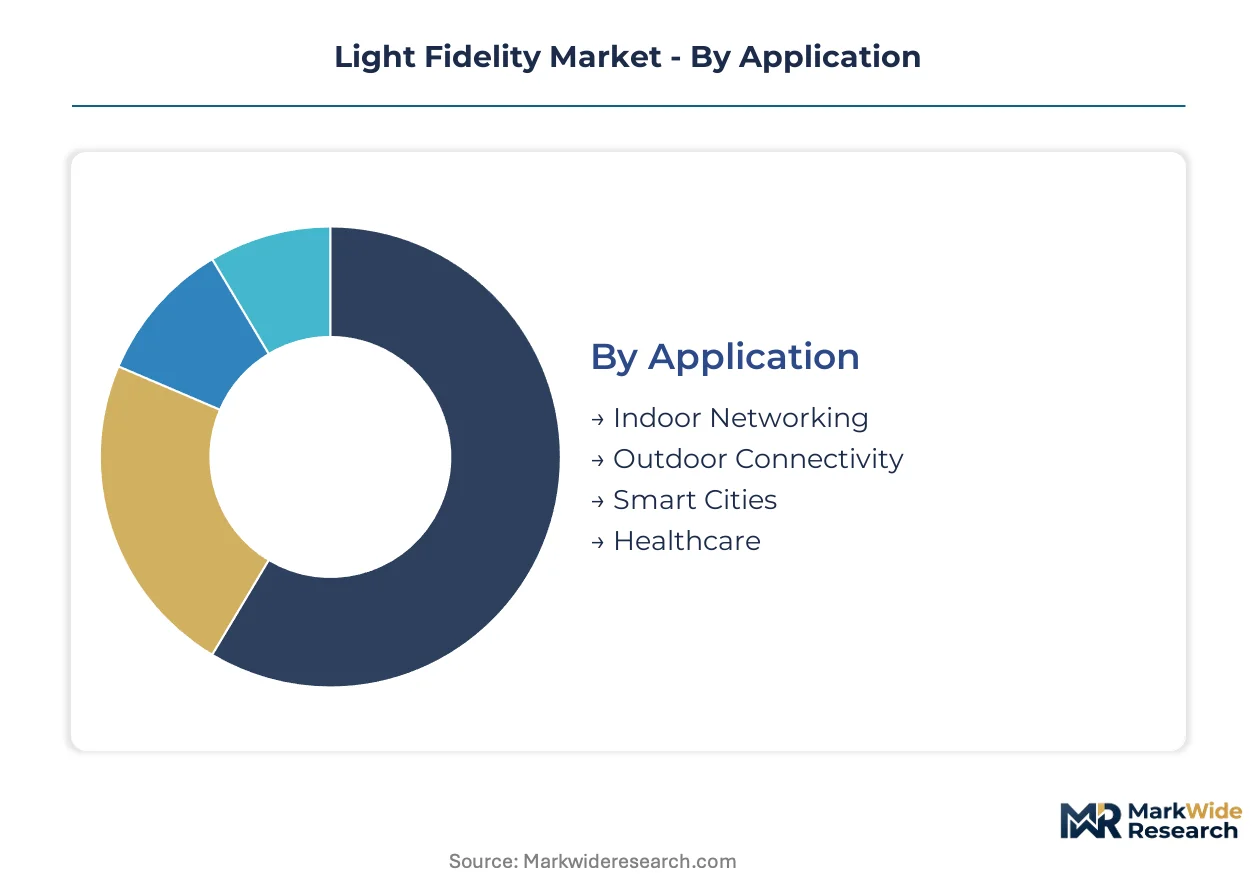
Li-Fi market segmentation reveals how photonic hardware configurations align with electromagnetic constraints and infrastructure ownership models across verticals. Procurement specifications diverge sharply between retrofit-friendly indoor deployments and greenfield outdoor installations requiring municipal coordination.
Application:
Standardization dominates high-volume indoor deployments while custom engineering prevails in mission-critical healthcare environments requiring RF-free certification.
- Indoor Networking:Enterprise conference facilities and hospital operating theaters in Germany and the United States specify IEEE 802.11bb-compliant hardware for secure, high-bandwidth connectivity without radio frequency interference. LED luminaire retrofit cycles accelerate deployment through existing electrical contractor channels.
- Smart Cities:Municipalities embed transceivers into streetlight infrastructure for traffic management and public safety networks. The EU AI Act's risk classification framework now requires algorithmic transparency documentation in German procurement tenders, extending deployment timelines.
- Outdoor Connectivity:Campus and stadium deployments leverage weatherized optical transceivers for dense spectator connectivity.
- Healthcare:Surgical robotics manufacturers mandate RF-free zones; Li-Fi satisfies requirements without cable installation complexity.
Most installed capacity flows through Indoor Networking. Expansion is steepest in Smart Cities.
Technology:
Cost tiers separate commoditized LED-integrated modules from specialized III-V semiconductor designs requiring captive fabrication capabilities.
- Li-Fi:Full bidirectional visible light communication systems achieving theoretical speeds exceeding 224 gigabits per second under laboratory conditions. pureLiFi's captive semiconductor design capabilities in Scotland sustain early-mover advantage through in-house photonic chip fabrication.
- VLC:Unidirectional broadcast configurations for signage and public information displays. Asian foundry concentration in gallium nitride substrate fabrication creates supply vulnerability for European integrators.
- Smart Lighting:Communication modules bundled into commercial lighting retrofits through Signify Holding's installed luminaire base.
- Network Infrastructure:Middleware and gateway systems bridging Li-Fi transceivers with legacy building management protocols.
Volume concentrates in Smart Lighting bundles. Margin capture is highest in Li-Fi systems with captive semiconductor supply.
End User:
Customer type determines procurement velocity, with transportation operators prioritizing reliability certification over cost minimization.
- Transportation:Deutsche Bahn and Japanese rail operators pilot continuous tunnel coverage through electromagnetic-shielded infrastructure. This addresses cellular dead zones without leaky feeder cable maintenance burdens.
- Education:Universities deploy high-density classroom connectivity where Wi-Fi spectrum congestion degrades performance. Procurement favors retrofit-friendly luminaire-integrated modules.
- Retail:Indoor positioning and customer analytics drive deployment in flagship stores.
- Hospitality:Hotels bundle connectivity into guest experience upgrades without RF exposure concerns.
Transportation absorbs the highest R&D investment per installation. Education delivers the fastest deployment velocity through standardized specifications.
Deployment:
Maturity gradients separate government pilots with extended evaluation timelines from industrial deployments demanding immediate operational continuity.
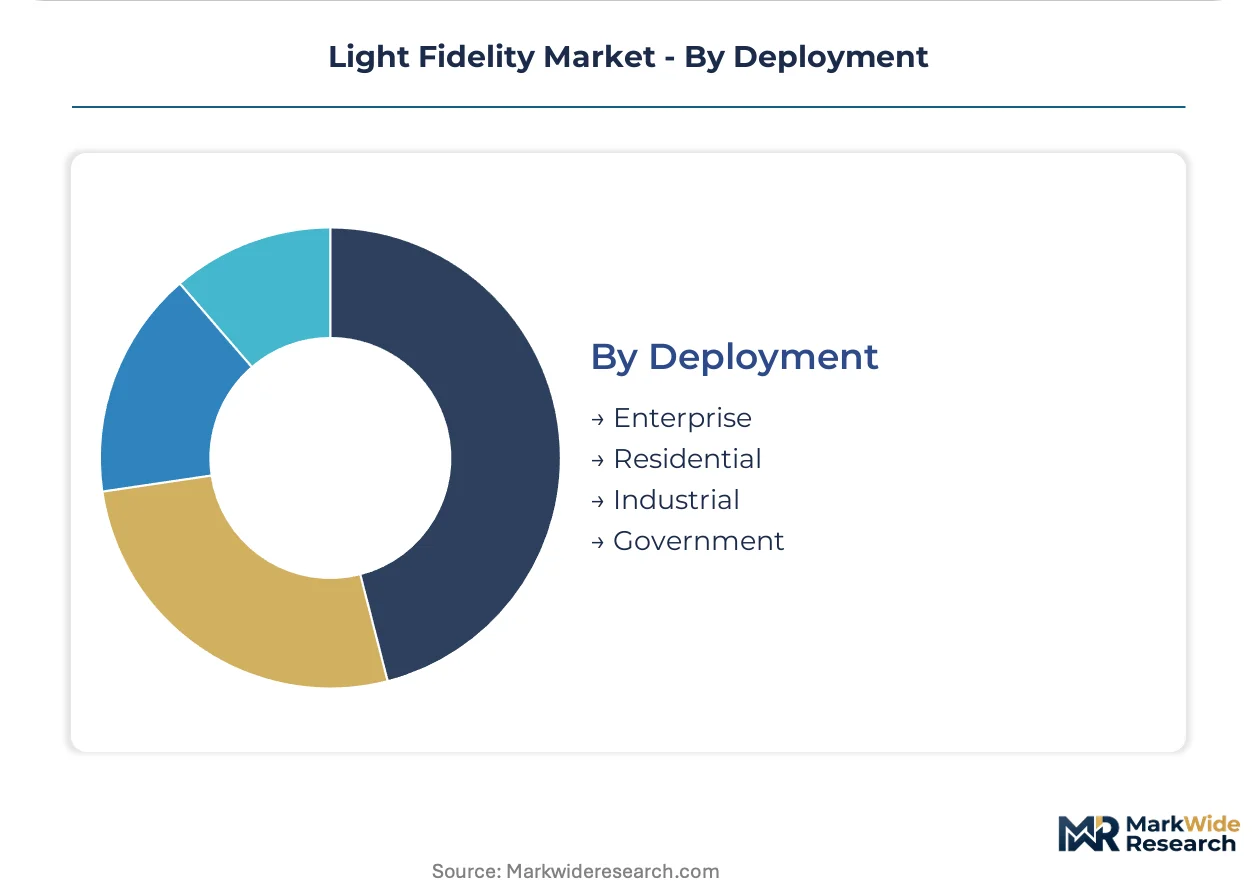
- Enterprise:Commercial building owners unbundle connectivity from facilities management contracts, creating distinct procurement decisions favoring specialized Li-Fi integrators in London and New York real estate markets.
- Industrial:Factory-floor automation clusters in Germany demand electromagnetic-interference-free connectivity for precision manufacturing. Oledcomm anchors this vertical through aviation-certified systems adapted for electromagnetic-sensitive production environments.
- Government:Defense contractors specify IEEE 802.11bb-compliant hardware in secure facility tenders, with procurement cycles extending through security clearance protocols.
- Residential:Consumer adoption remains nascent pending micro-LED convergence with display panel manufacturing.
Enterprise captures the largest revenue share. Industrial applications are climbing the fastest as manufacturing automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is steering Li-Fi module production toward jurisdictions with streamlined electromagnetic compliance pathways, while procurement clusters concentrate where industrial automation and healthcare infrastructure investments intersect.
Germany
Industrial automation clusters in Bavaria and North Rhine-Westphalia are piloting factory-floor Li-Fi networks for electromagnetic-sensitive manufacturing. The KBA and federal spectrum authorities coordinate with ETSI frameworks for visible light communication certification. Stuttgart's precision engineering corridor hosts Oledcomm's aviation-certified system adaptations for Airbus assembly lines.
United States
Hospital operating theaters in Texas and California are mandating RF-free zones for surgical robotics, absorbing Li-Fi infrastructure without cable installation complexity. The FCC governs unlicensed visible light spectrum usage while the FDA evaluates electromagnetic compatibility for medical device integration. Boston's healthcare technology cluster is deploying secure conference facilities with IEEE 802.11bb-compliant hardware.
Japan
Rail operators in the Tokyo-Osaka corridor are piloting continuous tunnel coverage through electromagnetic-shielded infrastructure, addressing cellular dead zones without leaky feeder maintenance burdens. METI coordinates standardization alignment with IEEE 802.11bb task group outputs. Nagoya's manufacturing belt is integrating Li-Fi transceivers into precision production environments.
United Kingdom
Commercial real estate markets in London are unbundling connectivity from facilities management contracts, creating distinct procurement decisions for specialized Li-Fi integrators. The UK's spectrum regulator aligns with ETSI interoperability frameworks for visible light communication. pureLiFi's captive semiconductor design capabilities in Scotland sustain early-mover advantage through in-house photonic chip fabrication.
Netherlands
Hospital architects in Amsterdam and Rotterdam are specifying organic photodetector arrays for patient tracking without RF exposure, enabling curved luminaire designs. The national regulator coordinates with EU AI Act conformity requirements for connected infrastructure procurement. Eindhoven's lighting technology cluster is advancing LED-integrated communication modules for commercial retrofit cycles.
Light Fidelity Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized certification verticals and captive semiconductor supply. The vendor base stratifies between lighting incumbents with installed luminaire bases and photonics specialists with compound semiconductor fabrication capabilities. Three archetypes dominate: LED-integrated module bundlers, aviation-certified system integrators, and captive chip designers. Competitive moves concentrate on strategic partnerships with electrical contractors and backward integration into gallium nitride substrate sourcing.
Among captive semiconductor designers, pureLiFi exemplifies the specialist archetype through Scotland-based photonic chip fabrication. Signify Holding represents the lighting incumbent vector, leveraging installed luminaire bases for module bundling into commercial retrofits. Oledcomm anchors the aviation-certified tier, occupying a position in electromagnetic-sensitive manufacturing protocols aligned with EASA requirements.
| Leading Market Players |
|---|
| pureLiFi |
| Oledcomm |
| Signify Holding |
| LightPointe Communications, Inc. |
| Lucibel |
| Acuity Brands Lighting, Inc. |
| Panasonic Corporation |
| Velmenni OÜ |
| VLNComm |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between aviation-compliant systems and commercial retrofit modules manifests in both pricing premiums and captive semiconductor sourcing strategies. EASA-aligned manufacturing protocols command substantial markups through specialized III-V fabrication, while LED-integrated bundles leverage volume scale from Signify's installed luminaire base.
Pricing Analysis
Distributor margins absorb 15-25 points on IEEE 802.11bb-certified hardware sold through electrical contractor channels in Germany and the United States. Three-tier pricing structure separates aviation-certified systems from enterprise indoor networking from unidirectional VLC signage, with certification level and captive chip design as primary differentiation drivers. Cost compression in commercial retrofit tiers is intensifying because Asian gallium nitride foundries dominate substrate supply. Hospital procurement committees demonstrate lowest price sensitivity due to RF-free zone mandates, while education buyers prioritize standardized luminaire-integrated modules.
Supply Chain Analysis
Freight costs for indium phosphide wafers and gallium nitride substrates from Asian foundries compress module margins for European integrators by 8-12 points. Photonic chip fabrication concentrates in Taiwan, South Korea, and Scotland, while LED luminaire assembly clusters in China, the Netherlands, and Mexico. Supply chain risk centers on single-source vulnerability for III-V semiconductor substrates amid geopolitical export restrictions. Distribution runs through electrical contractor relationships for commercial retrofits and direct OEM partnerships for aviation and rail certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in captive semiconductor design and aviation certification verticals as LED retrofit cycles commoditize commercial tiers. In-house photonic chip fabrication and EASA-aligned manufacturing protocols enable premium capture absent from bundled lighting modules.
For Market Incumbents: Deploy backward integration into gallium nitride substrate sourcing to defend against Asian foundry price volatility. Acquire specialized aviation certification capabilities before generalist lighting vendors adapt. Wi-Fi 6E and 7 substitution threats intensify in education and retail segments where line-of-sight limitations disadvantage Li-Fi mobility applications. For New Entrants and Emerging Players: Begin with rail tunnel connectivity pilots in Japan and Germany where cellular dead zones create immediate operational pain points. Target smart city traffic management tenders in Dutch and German municipalities where EU AI Act conformity requirements extend deployment timelines for incumbents. Pursue direct municipal procurement relationships bypassing legacy facilities management bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where photonic IC design talent scarcity fragments vendor capabilities across lidar, optical computing, and Li-Fi recruiting pools. Five-to-ten year viability favors captive semiconductor designers with Scotland or Taiwan fabrication access over pure-play integrators. Watch IEEE 802.11bb task group output velocity as inflection indicator for standardization-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication | In-house photonic chip design insulates pureLiFi against III-V substrate price volatility from Asian foundries. |
| Aviation Certification Investment | EASA-aligned protocols create regulatory moats for Oledcomm in Airbus assembly line deployments. |
| LED Luminaire Bundle Expansion | Signify leverages installed base to accelerate commercial retrofit velocity through electrical contractor channels. |
| Rail Tunnel Connectivity Pilot | Deutsche Bahn and Japanese operators address cellular dead zones without leaky feeder cable maintenance burdens. |
| Organic Photodetector Integration | Flexible substrates enable curved luminaire designs for Dutch hospital patient tracking without RF exposure. |
Study Parameters
Multiple input streams — primary interviews, regulatory filing analysis, and trade data reconciliation — were synthesized to construct market estimates. Conversations with photonic chip designers, hospital biomedical engineers, rail operator procurement leads, and smart city infrastructure planners informed demand-side validation. Secondary sources included FCC unlicensed spectrum filings, ETSI interoperability frameworks, IEEE 802.11bb task group documentation, and LED luminaire shipment databases. Bottom-up module deployment counts and top-down infrastructure investment flows were cross-referenced for triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions of application type, technology tier, end-user vertical, and deployment model. CAGRs derived from annualized growth rate fitting across modeled scenarios incorporated III-V semiconductor supply constraints, IEEE standardization timelines, and municipal procurement cycle durations. Industry-specific inputs included LED retrofit cycle frequencies, aviation certification lead times, and rail tunnel electromagnetic shielding penetration rates.
Several conditions sit outside the modeled scope, including potential 6 GHz Wi-Fi spectrum reallocation impacts, micro-LED convergence timelines with consumer display manufacturing, and geopolitical export restrictions on compound semiconductor substrates. Forecasts reflect assumptions about standardization adoption curves and infrastructure replacement cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Multefire Market
Wireless Technologies
5G WIT120 Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Wireless Camera Market