
 Public Wi-Fi Market | 2026-2036
Public Wi-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
Public Wi-Fi Market Analytics
Wi-Fi CERTIFIED Passpoint qualification is collapsing the barrier between telecom operators and venue owners who previously relied on fragmented captive portal systems. Cisco Systems leverages its enterprise switching heritage to anchor large-scale municipal contracts requiring seamless roaming. Aruba Networks competes through specialized hospitality and stadium deployments that sustain premium pricing for managed service bundles.
Public Wi-Fi denotes open wireless local area network infrastructure operating on unlicensed 2.4 GHz and 5 GHz spectrum bands, typically broadcasting SSIDs without subscriber authentication or through simplified login flows, designed to extend internet connectivity in spaces where cellular backhaul proves cost-prohibitive or capacity-constrained. The hardware layer employs IEEE 802.11ax (Wi-Fi 6) and emerging 802.11be (Wi-Fi 7) chipsets to support dense client environments exceeding one thousand simultaneous connections per access point. Deployment Model segmentation shows city-wide networks absorbing the largest capital allocation as municipalities bundle fiber backhaul with pole-mounted radios, while transport hubs represent the fastest-expanding sub-area driven by rail and aviation passenger volume recovery. Business Establishments retain the deepest margin pools through multi-year managed service contracts that wrap analytics, advertising insertion, and cybersecurity monitoring into recurring revenue streams.
The Federal Communications Commission governs unlicensed spectrum power limits and open internet principles affecting how U.S. providers monetize public hotspots, while the European Telecommunications Standards Institute shapes interoperability mandates that determine which equipment qualifies for WiFi4EU funding. India's Telecom Regulatory Authority enforces net neutrality provisions that constrain zero-rating partnerships between carriers and venue operators. Stakeholders must monitor spectrum reallocation debates and emerging national broadband strategies that could redirect subsidy flows from fiber-to-the-home toward wireless last-mile alternatives.
Market Dynamics
Municipal governments in India, Germany, and Brazil are bundling fiber backhaul with pole-mounted radios, collapsing the traditional separation between telecom infrastructure and city planning departments.
Growth Catalysts
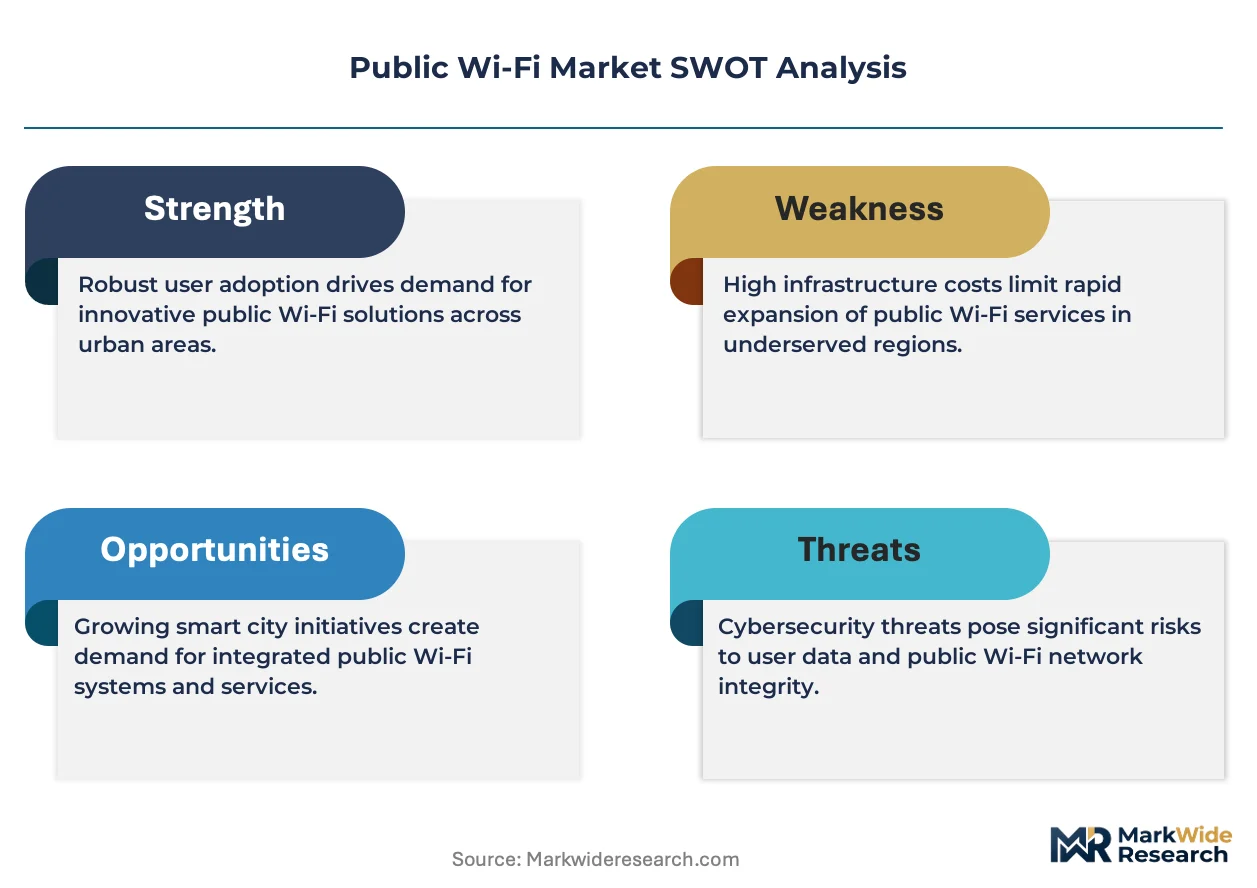
- WiFi4EU Voucher Scheme:The European Union's subsidy program accelerates access point deployment in transport hubs and public squares across member states, lowering capital barriers for municipalities.
- Indian Railway Digitization:Bulk procurement of carrier-grade access points for railway stations and metro systems creates sustained demand for high-density Wi-Fi 6 and Wi-Fi 7 hardware.
- Passpoint Certification:Seamless roaming protocols eliminate fragmented captive portal systems, enabling venue owners to monetize foot traffic through analytics partnerships.
Market Restraints
- Unlicensed Spectrum Congestion:2.4 GHz and 5 GHz bands face interference saturation in dense urban deployments, degrading quality-of-service guarantees for municipal contracts.
- Net Neutrality Constraints:India's Telecom Regulatory Authority limits zero-rating partnerships between carriers and venue operators, compressing advertising-supported revenue models.
- Fiber Backhaul Dependency:City-wide networks require trenching and dark fiber leases that extend deployment timelines and concentrate vendor selection among integrated infrastructure providers.
Strategic Opportunities
- Brazilian Smart City Programs:Municipal governments in São Paulo and Rio de Janeiro are expanding free access deployments, creating white space for managed service contracts with analytics bundling.
- Aviation Passenger Recovery:Airport terminals represent underpenetrated high-density environments where Wi-Fi 7 chipsets can command premium pricing for sub-10 millisecond latency guarantees.
- Managed Service Convergence:Hospitality and stadium operators are shifting from hardware purchases to multi-year contracts wrapping cybersecurity monitoring, advertising insertion, and usage analytics.
Industry Challenges
- RF Engineering Talent Scarcity:Dense client environments exceeding one thousand simultaneous connections per access point require specialized spectrum planning expertise that outpaces training pipeline output.
- Legacy System Integration:Transport hubs must bridge IEEE 802.11ax deployments with existing passenger information systems and security networks, creating interoperability testing bottlenecks.
- Certification Timeline Compression:Wi-Fi CERTIFIED Passpoint qualification cycles delay contract awards, forcing vendors to pre-certify hardware before municipal procurement windows open.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Wi-Fi Market |
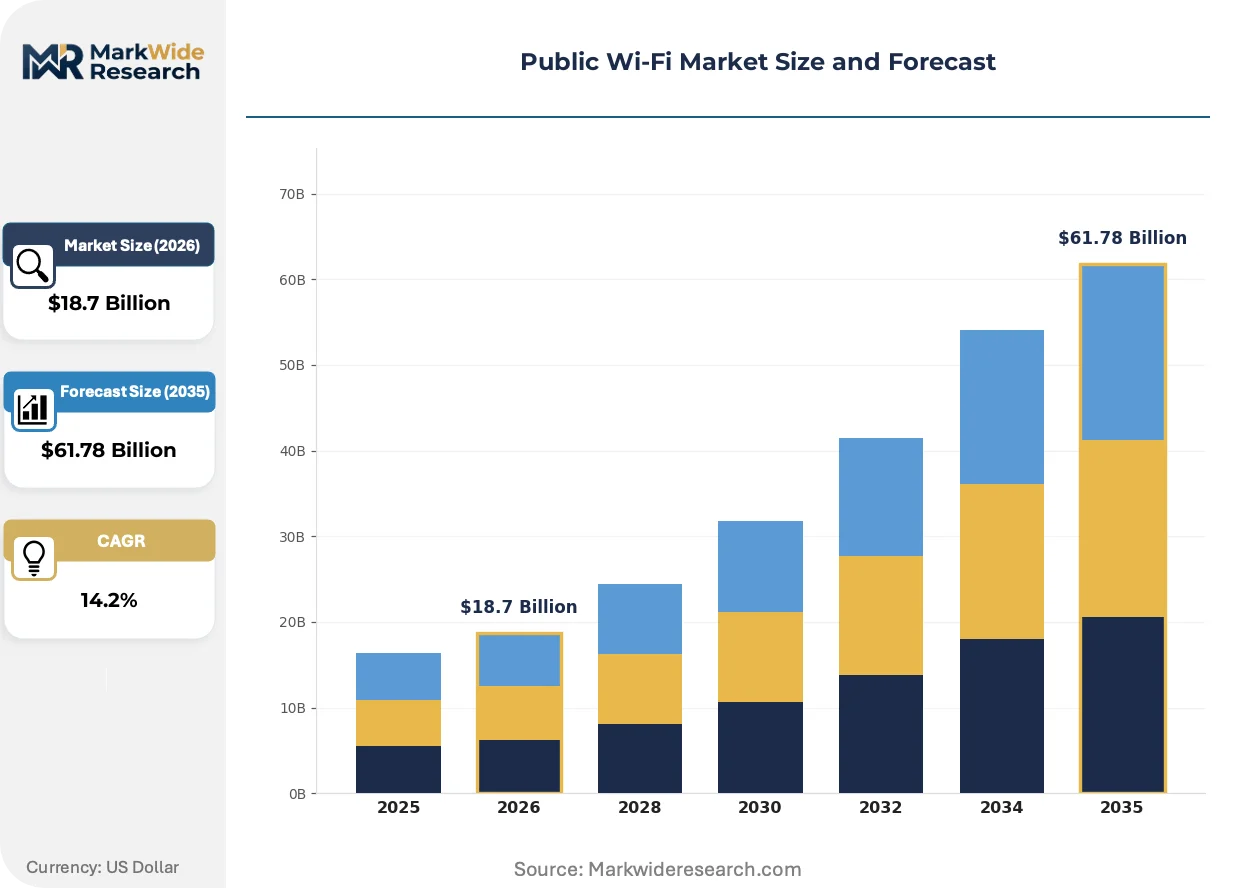
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Free Access, Subscription, Premium Access, Sponsorship End User: Tourists, Students, Professionals, Local Residents Deployment Model: City-wide Network, Campus Network, Business Establishments, Transport Hubs Access Method: Hotspot, Login Portal, Social Media Login, QR Code Access |
| Companies Covered | CommScope Holding Company, Aruba Networks, Cisco Systems, Ubiquiti Networks, TP-Link Technologies, Hewlett Packard Enterprise, Extreme Networks, Netgear, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Wi-Fi Market Evolving Landscape
Hardware differentiation is compressing as chipset commoditization meets software-defined network management, shifting value capture toward analytics platforms and recurring service layers.
Wi-Fi 7 (IEEE 802.11be) is fragmenting competitive positioning among access point vendors by enabling 320 MHz channel bandwidth and multi-link operation that legacy silicon cannot emulate. Railway operators in India are piloting these chipsets for passenger connectivity during peak congestion windows. The technology is fragmenting vendor tiers into those with captive semiconductor supply and those dependent on merchant silicon.
The European Telecommunications Standards Institute is mandating interoperability specifications that determine WiFi4EU funding eligibility, forcing equipment manufacturers to pre-validate against ETSI test suites before commercial launch. This regulatory pressure is compressing product development cycles and raising compliance costs for smaller hardware vendors. Municipal procurement teams in Germany and France are prioritizing pre-certified equipment to accelerate deployment timelines.
Buyer concentration is intensifying as railway authorities and airport operators consolidate vendor relationships around multi-year managed service agreements rather than discrete hardware purchases. Hospitality chains are unbundling after-sales support from initial equipment sales, preferring subscription models that include predictive maintenance and security patch management. This pattern is most visible in India's metro rail expansions and Brazil's stadium modernization programs.
Public Wi-Fi Market Segmentation
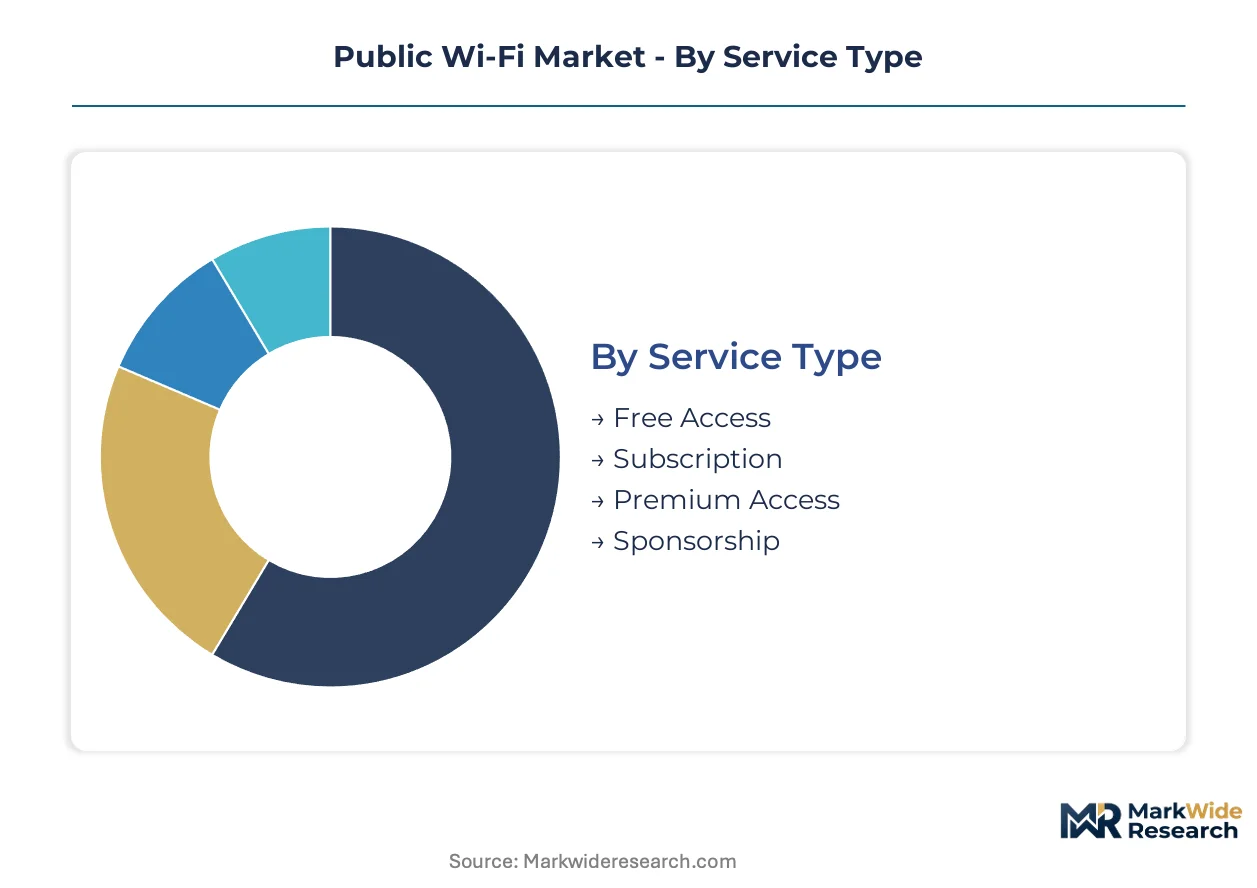
Public Wi-Fi monetization pathways diverge sharply across service tiers and deployment contexts. Vendor positioning depends on matching hardware specifications to density requirements while navigating regulatory constraints on data collection and zero-rating partnerships.
Service Type:
Margin pools concentrate in recurring revenue models that wrap analytics and managed security into multi-year contracts rather than one-time hardware sales.
- Free Access:Municipal governments in India and Brazil deploy tax-funded networks broadcasting open SSIDs without authentication. Railway stations in Mumbai and Delhi absorb bulk procurement of carrier-grade access points where advertising insertion subsidizes capital expenditure.
- Subscription:Tiered monthly plans with bandwidth guarantees generate predictable cash flows for venue operators. Airport terminals in Germany bundle priority lane access with premium Wi-Fi tiers, capturing business traveler willingness to pay for sub-10 millisecond latency.
- Premium Access:Dedicated VLANs with quality-of-service guarantees serve enterprise clients within hospitality environments. Managed service providers in São Paulo wrap cybersecurity monitoring and predictive maintenance into per-seat pricing.
- Sponsorship:Brand-funded deployments trade network naming rights and captive portal advertising for infrastructure investment. Retail chains in Rio de Janeiro leverage consumer goods partnerships to offset pole-mounted radio costs.
Free Access holds installed capacity. Premium Access is rotating up the share rankings.
End User:
Volume concentration tracks mobility patterns and device density rather than per-capita income, with transport corridors generating the highest simultaneous connection counts.
- Tourists:Roaming subscribers from foreign networks drive Passpoint certification demand in European transport hubs. ETSI interoperability mandates determine which access points qualify for WiFi4EU voucher redemption in French and German public squares.
- Students:Campus networks require seamless handoff between lecture halls and outdoor spaces. Brazilian federal universities bundle fiber backhaul with pole-mounted radios to serve dispersed residential colleges.
- Professionals:Co-working spaces and business districts prioritize low-latency video conferencing. India's metro rail expansions target this segment with Wi-Fi 7 pilot programs guaranteeing throughput during peak congestion.
- Local Residents:Municipal equity programs extend connectivity to underserved neighborhoods. São Paulo's smart city initiatives deploy free access in favela districts where cellular backhaul remains cost-prohibitive.
Professionals command pricing power. Local Residents are climbing the fastest as municipalities expand equity mandates.
Deployment Model:
Capital allocation tilts toward integrated infrastructure contracts where fiber trenching and radio installation collapse into single-vendor accountability.
- City-wide Network:Pole-mounted access points with mesh backhaul blanket urban cores. German municipalities bundle dark fiber leases with WiFi4EU-funded equipment, concentrating vendor selection among integrated providers.
- Campus Network:Distributed antenna systems serve universities and corporate parks with unified authentication. Indian Institutes of Technology deploy high-density Wi-Fi 6 across residential and academic zones exceeding one thousand simultaneous connections per access point.
- Business Establishments:Hospitality and retail operators shift from hardware purchases to subscription models. Stadium modernization programs in Brazil unbundle after-sales support into recurring contracts with analytics bundling.
- Transport Hubs:Railway stations and airports represent the steepest expansion trajectory for carrier-grade deployments. Indian Railway digitization drives sustained procurement of Wi-Fi 7 chipsets for passenger connectivity during volume recovery.
Business Establishments anchor recurring revenue. Transport Hubs are gaining share fastest as aviation and rail volumes normalize.
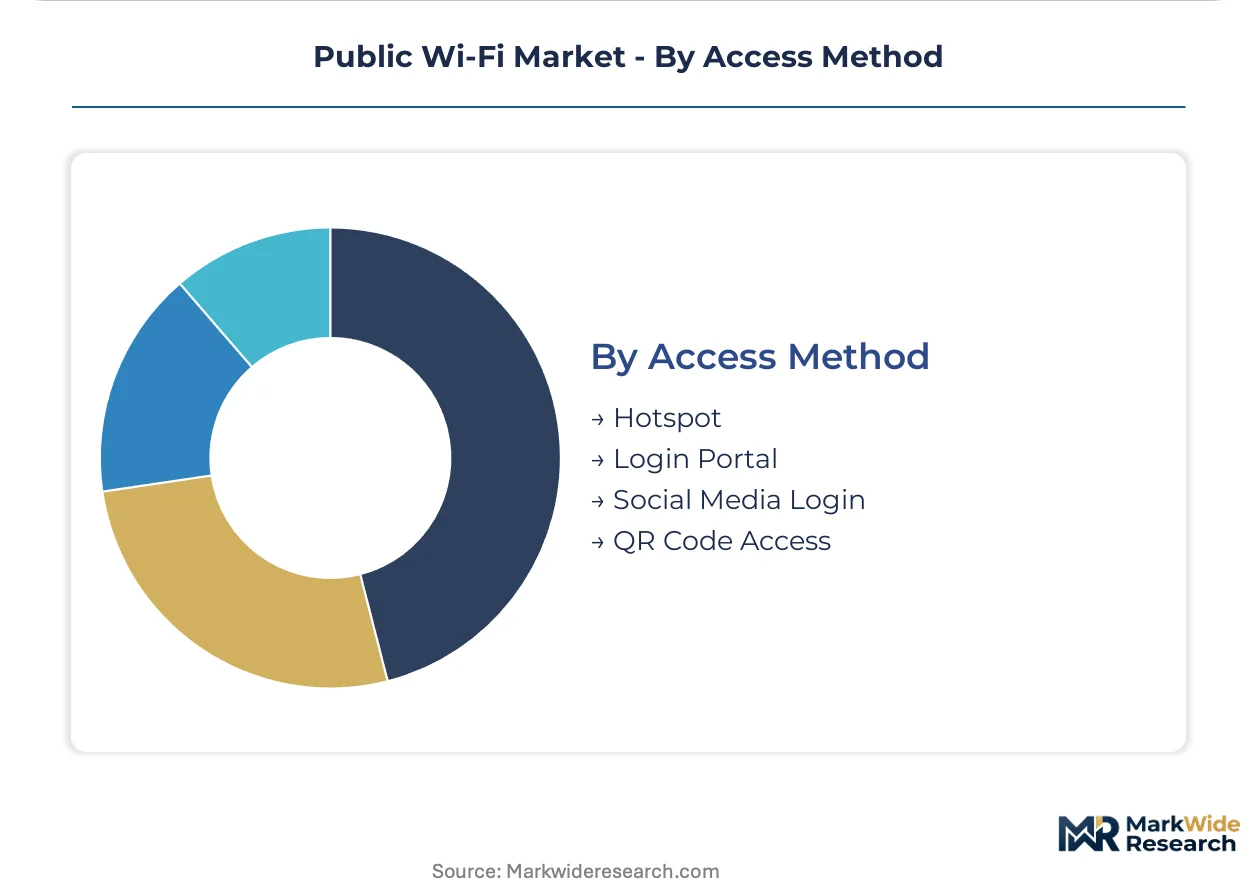
Access Method:
Authentication friction directly determines footfall conversion rates and analytics capture depth for venue monetization partnerships.
- Hotspot:Open SSID broadcasting without credential requirements minimizes barrier to entry. Brazilian municipal programs prioritize this method for universal access goals in public squares.
- Login Portal:Captive pages collect demographic data for advertising targeting. German transport hubs deploy ETSI-compliant portals to satisfy WiFi4EU funding eligibility.
- Social Media Login:OAuth integration enables one-click access with profile data sharing. Indian metro operators pilot these flows for passenger behavior analytics while navigating TRAI net neutrality constraints on zero-rating.
- QR Code Access:Printed codes at seating areas and retail displays reduce typing friction. Airport terminals in São Paulo deploy dynamic QR systems that rotate credentials for security segmentation.
Login Portal dominates current deployments. QR Code Access is rotating up the share rankings as contactless preferences persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy incentives are redirecting subsidy flows toward wireless last-mile infrastructure. Municipal procurement teams prioritize pre-certified equipment to compress deployment timelines. Railway digitization and smart city mandates concentrate capital allocation in transport corridors and urban cores.
India
Railway stations and metro systems in Mumbai and Delhi drive bulk procurement of carrier-grade access points. TRAI enforces net neutrality provisions that constrain zero-rating partnerships between carriers and venue operators. The Delhi-Mumbai Industrial Corridor anchors deployment of Wi-Fi 7 chipsets for passenger connectivity during peak congestion windows.
Germany
Municipal governments bundle dark fiber leases with pole-mounted radios for city-wide network coverage. ETSI interoperability mandates determine equipment qualification for WiFi4EU voucher redemption. Procurement teams in Bavaria and North Rhine-Westphalia prioritize pre-certified access points to accelerate public square deployments.
Brazil
São Paulo and Rio de Janeiro municipal programs expand free access deployments in favela districts where cellular backhaul remains cost-prohibitive. ANVISA and national telecom regulators shape equipment import standards for unlicensed spectrum devices. Stadium modernization programs in São Paulo state unbundle hardware purchases into multi-year managed service contracts.
United States
FCC power limits and open internet principles govern how providers monetize public hotspots in transport hubs and hospitality venues. The regulator's spectrum reallocation debates influence municipal vendor selection for integrated fiber-radio contracts. Chicago and Los Angeles anchor large-scale deployments requiring seamless roaming protocols.
United Kingdom
Transport for London and Network Rail consolidate vendor relationships around multi-year managed service agreements for station connectivity. GDPR compliance requirements constrain data collection flows from captive portal authentication systems. London and Manchester concentrate procurement of high-density Wi-Fi 6 hardware for aviation and rail passenger recovery.
Public Wi-Fi Market Competitive Landscape
Player mix skews toward integrated infrastructure providers with captive semiconductor supply and software-defined network management capabilities. Market structure concentrates around vendors capable of bundling fiber backhaul with pole-mounted radio installation. Three archetypes dominate: enterprise switching heritage players, specialized hospitality-stadium deployers, and merchant silicon-dependent hardware vendors. Competitive moves center on pre-certification against ETSI test suites and multi-year managed service contract capture.
Within the integrated infrastructure tier, Cisco Systems and Hewlett Packard Enterprise represent enterprise switching heritage that anchors municipal contracts requiring single-vendor accountability. Aruba Networks exemplifies the specialized hospitality-stadium deployer archetype, occupying a position where premium pricing for managed service bundles persists. Huawei Technologies sits within the scale-driven equipment manufacturer category, with procurement eligibility shaped by national security screening frameworks in multiple geographies.
| Leading Market Players |
|---|
| CommScope Holding Company |
| Aruba Networks |
| Cisco Systems |
| Ubiquiti Networks |
| TP-Link Technologies |
| Hewlett Packard Enterprise |
| Extreme Networks |
| Netgear |
| Huawei Technologies |
| Others |
Value Network & Pricing Analysis
Multi-year managed service contracts with take-or-pay structures lock in both semiconductor supply allocations and price visibility for municipal procurement teams across India and Germany. These agreements collapse hardware procurement, fiber backhaul leasing, and predictive maintenance into single-vendor accountability that shields buyers from spot-market volatility in Wi-Fi 6 and Wi-Fi 7 chipsets.
Pricing Analysis
Certification level (Wi-Fi CERTIFIED Passpoint and ETSI pre-validation) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects compliance cost absorption and interoperability guarantees. Cost compression in the economy tier is intensifying because merchant silicon vendors undercut integrated providers on upfront hardware costs. Municipal governments in Brazil exhibit the highest price sensitivity due to budget-constrained smart city mandates, while German transport authorities prioritize certification premiums for WiFi4EU eligibility.
Supply Chain Analysis
Port congestion along Asia-Pacific trade lanes elevates inbound logistics costs for access point manufacturers dependent on Taiwanese and South Korean semiconductor foundries. Component sourcing draws from Malaysia for PCB assembly, Vietnam for enclosure manufacturing, and China for power supply units. Single-source vulnerability in IEEE 802.11be chipset supply concentrates risk among vendors without captive fabrication. Distribution runs through systems integrators who bundle pole-mounted radio installation with fiber trenching contracts for city-wide network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wi-Fi 7 chipsets and Passpoint certification mandates are disrupting vendor tiers, compressing product development cycles and forcing pre-certification investments before procurement windows open.
For Market Incumbents: Consolidate around captive semiconductor supply agreements to secure allocation priority during foundry capacity constraints. Deepen backward integration into IEEE 802.11be silicon design to escape merchant silicon dependency that erodes margin differentiation. Defend municipal contract capture by pre-certifying hardware against ETSI test suites before German and French procurement cycles commence. For New Entrants and Emerging Players: Anchor in Brazilian stadium modernization programs and São Paulo favela connectivity initiatives where integrated infrastructure requirements remain underpenetrated. Target aviation passenger recovery corridors in Indian airport terminals demanding sub-10 millisecond latency guarantees that incumbent hospitality specialists have not addressed. Pursue managed service bundling with analytics partnerships rather than competing on discrete hardware pricing. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined network management platforms with recurring revenue attachment rates above hardware-only vendors. Long-term viability hinges on analytics and cybersecurity service layers that sustain pricing power as chipset commoditization accelerates. Monitor WiFi4EU voucher redemption velocity across German municipalities as the signal indicating subsidy flow sustainability and municipal procurement appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Chipset Pre-Certification | ETSI validation accelerates WiFi4EU voucher redemption timelines for German municipal contracts. |
| Managed Service Convergence | Analytics bundling captures recurring revenue from Brazilian stadium operators shifting from hardware purchases. |
| Fiber-Radio Integration | Pole-mounted access point deployment with dark fiber backhaul concentrates vendor selection among integrated providers. |
| Passpoint Roaming Partnerships | Seamless authentication protocols enable venue monetization through foot traffic analytics in Indian railway stations. |
| RF Engineering Talent Acquisition | Spectrum planning expertise scarcity constrains dense client environment deployments exceeding one thousand connections per access point. |
Research Methodology
Desk research of regulatory filings from TRAI, ETSI, and FCC; customs records for unlicensed spectrum equipment; and municipal procurement databases preceded structured interviews with municipal IT directors, railway authority network engineers, stadium operations managers, and hospitality technology procurement leads. Primary fieldwork with systems integrators and access point manufacturers was cross-validated against secondary sources including carrier capex disclosures and smart city program budgets. Bottom-up segmentation modeling triangulated with top-down market sizing across deployment models and service types.
Variance decomposition across the projection horizon isolates volume drivers (railway digitization, aviation recovery, municipal equity mandates) from price effects (certification premiums, managed service bundling, chipset generation transitions). Segmentation dimensions modeled include deployment model, service tier, end-user mobility pattern, and access method authentication friction. CAGRs derive from installed base replacement cycles and greenfield penetration rates in transport corridors. Forecast inputs incorporate ETSI interoperability mandate timelines and Indian Railway passenger volume normalization assumptions.
Material uncertainties — spectrum reallocation debates, net neutrality enforcement shifts, and semiconductor foundry capacity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding subsidy program continuity and passenger traffic recovery trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Li-Fi Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Wireless Access Point Market