
 Voice Over Wifi Market | 2026-2036
Voice Over Wifi Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Over Wifi Market Outlook
Enterprise-grade session initiation protocol is reorganizing how carriers architect indoor voice coverage. Cisco Systems Inc. leverages its installed base of enterprise networking gear to push converged WiFi-voice platforms into Fortune 500 accounts. Nokia Corporation anchors its portfolio through deep R&D intensity in 3GPP-compliant WiFi calling cores. Huawei Technologies Co. Ltd. competes aggressively on manufacturing scale, though its geographic dominance narrows outside Asia-Pacific markets.
Voice Over Wifi denotes the transmission of packetized voice traffic across IEEE 802.11 wireless local area networks using SIP signaling and RTP media transport, typically operating in unlicensed 2.4 GHz or 5 GHz spectrum bands with quality-of-service prioritization mechanisms to maintain sub-150 millisecond latency thresholds for conversational intelligibility. VoWLAN technology leads deployment volumes among enterprise buyers seeking to bypass cellular infrastructure costs, while cloud-based deployment models capture the fastest expansion as IT departments favor opex-light consumption over on-premises hardware cycles. Managed service types concentrate margin pools because recurring network management contracts lock in multi-year revenue streams that pure VoIP solution licenses cannot replicate.
The FCC mandates E911 location accuracy standards that force VoWiFi providers to deliver dispatchable address data for indoor callers, tightening product certification requirements across the United States. CE marking under the EU Radio Equipment Directive and Japan's MIC technical standards create parallel compliance corridors for equipment vendors selling into multiple jurisdictions. Stakeholders must monitor how 3GPP Release 18 enhancements to WiFi-calling handover protocols reshape vendor interoperability requirements before committing to platform selections.
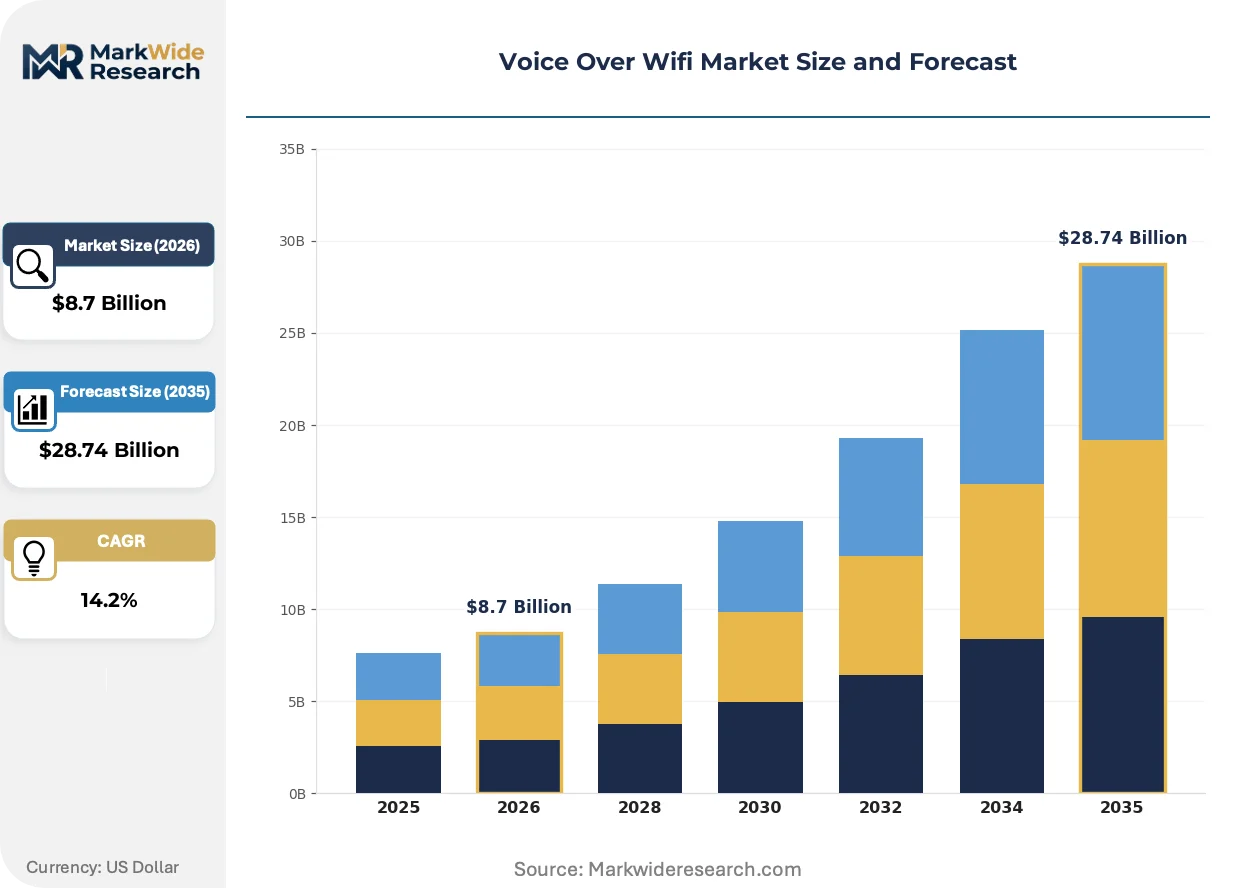
Market Dynamics
Enterprise IT departments are accelerating VoWiFi deployment to eliminate cellular dead zones in office complexes, while the FCC's spectrum policy reforms force carriers to prioritize indoor wireless coverage investments over macro network expansion.
Growth Catalysts
- E911 Mandates:The FCC requires dispatchable address data for indoor VoWiFi callers, compelling carriers to upgrade infrastructure and expand coverage footprints to maintain compliance.
- Enterprise Cost Avoidance:Fortune 500 facilities teams deploy VoWLAN to bypass recurring cellular infrastructure fees and eliminate coverage gaps in dense concrete structures.
- 3GPP Release 18:Enhanced WiFi-calling handover protocols improve interoperability between carrier networks and enterprise WiFi systems, reducing deployment friction.
Market Restraints
- Silicon Concentration:VoWiFi chipset supply concentrates among a handful of foundry operators in Taiwan, creating vulnerability to geopolitical disruption and capacity constraints.
- Unlicensed Spectrum Interference:Dense 2.4 GHz and 5 GHz deployments in urban environments degrade voice quality below conversational intelligibility thresholds during peak usage periods.
- CE Marking Complexity:The EU Radio Equipment Directive imposes extended certification timelines for multi-band WiFi voice equipment, delaying product launches by 6-12 months.
Strategic Opportunities
- Cloud-Native Architectures:IT departments favor opex-light consumption models over on-premises hardware cycles, expanding addressable market for managed VoWiFi services.
- Japan MIC Standards Alignment:Technical harmonization between Japanese and 3GPP standards creates export pathway for equipment vendors certified under unified testing regimes.
- Healthcare Vertical Penetration:Hospital systems require guaranteed indoor voice coverage for clinical staff, opening specialized deployment contracts with stringent latency requirements.
Industry Challenges
- SIP Engineering Talent Scarcity:Enterprise IT teams lack expertise in session initiation protocol configuration and quality-of-service tuning for converged networks.
- Legacy PBX Integration:Hybrid deployments require complex signaling gateway deployment between TDM infrastructure and packetized WiFi voice systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Over Wifi Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VoWLAN, PBX, SIP, RTP End User: Enterprises, Healthcare Facilities, Educational Institutes, Hospitality Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service Type: VoIP Solutions, Network Management, User Support, Consulting |
| Companies Covered | Huawei Technologies Co. Ltd., Nokia Corporation, Telefonaktiebolaget LM Ericsson, Cisco Systems Inc., Oracle Corporation, AT&T Inc., Verizon Wireless, T-Mobile USA Inc., Aptilo Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Over Wifi Market Strategic Shifts
VoWiFi technology is fragmenting into specialized deployment models as enterprise buyers demand carrier-grade reliability from unlicensed spectrum infrastructure.
Cloud-native IMS cores are decomposing traditional on-premises voice switching architectures. Mid-market enterprises adopt subscription-based calling platforms to eliminate hardware refresh cycles. This shift is compressing capital equipment sales while expanding recurring service revenue pools.
The FCC's indoor location accuracy mandates are tightening certification requirements for VoWiFi providers serving United States subscribers. Dispatchable address data obligations force infrastructure vendors to integrate enhanced positioning capabilities. Equipment manufacturers serving multi-jurisdiction markets must maintain parallel compliance corridors with CE marking and Japan MIC standards.
Facility managers now specify WiFi voice coverage during new construction planning rather than retrofitting cellular solutions. Design-build contractors embed converged network specifications into architectural drawings before ground-breaking. This behavior shift concentrates in United States commercial real estate developments targeting LEED certification and smart building credentials.
Voice Over Wifi Market Segmentation
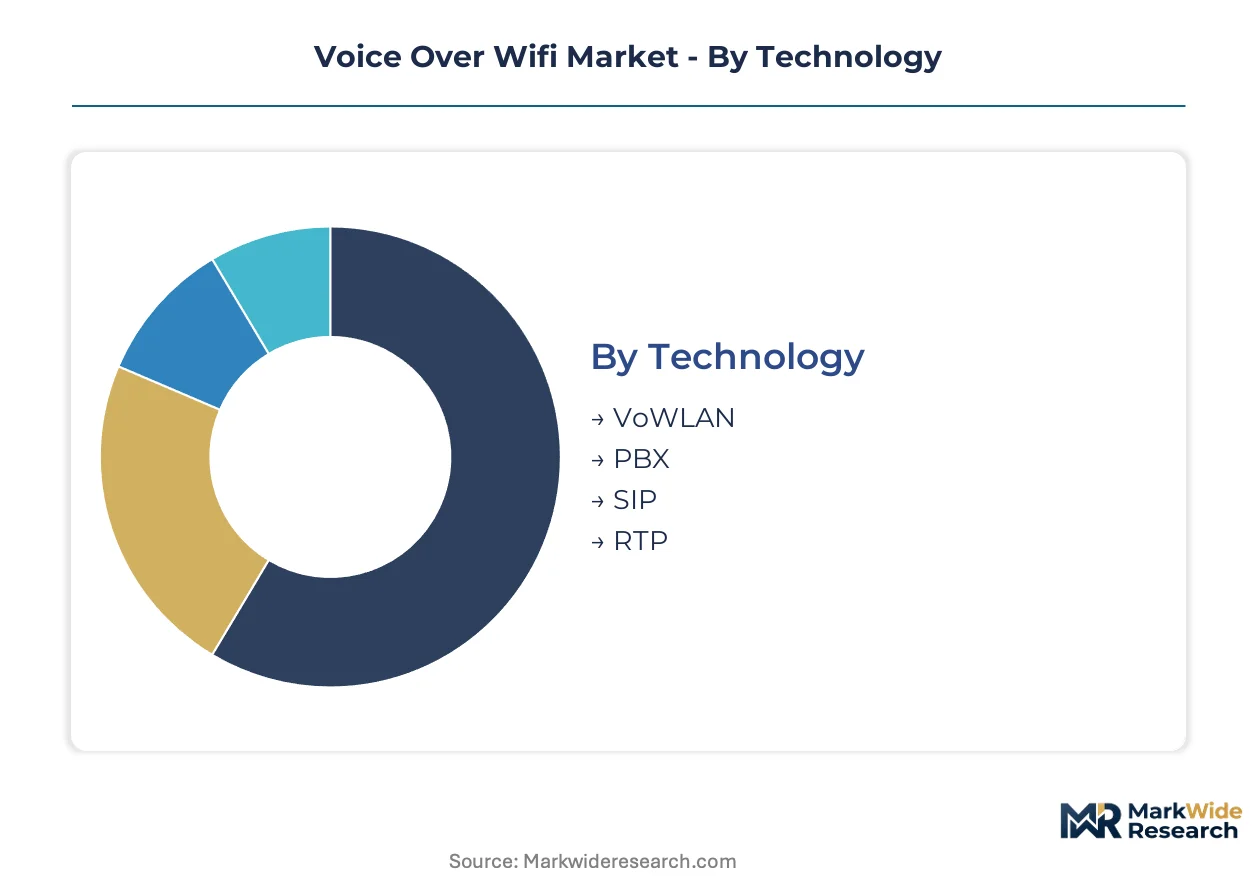
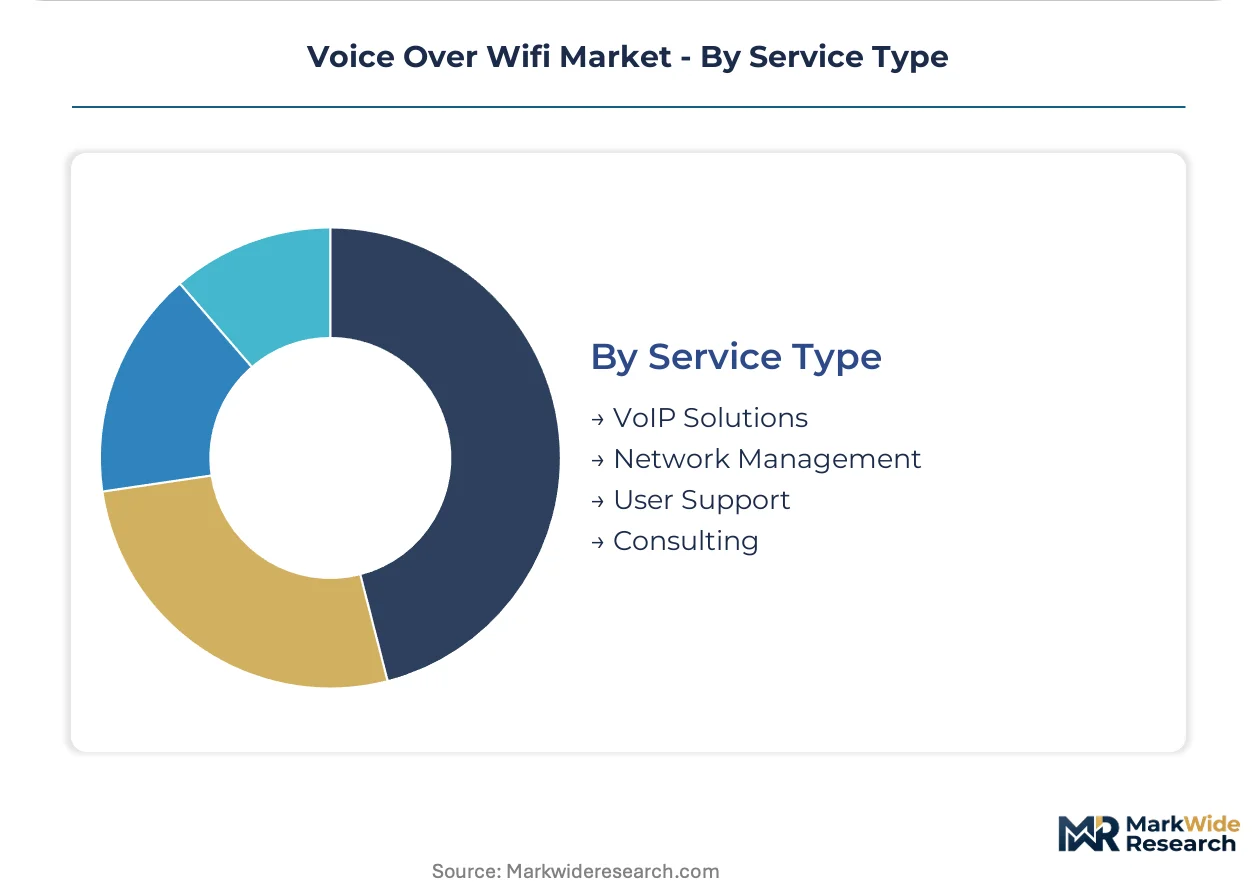
VoWiFi segmentation reflects divergent compliance burdens and infrastructure maturity across deployment modes. Technology choices determine spectral efficiency and handover reliability, while service models dictate margin durability through recurring revenue capture.
Technology:
FCC E911 mandates and EU Radio Equipment Directive certification requirements create divergent product development pathways for each protocol stack.
- VoWLAN:IEEE 802.11-based voice transmission dominates enterprise installations seeking to bypass cellular infrastructure costs entirely. Manufacturing facilities in Germany and hospital systems across the United States deploy VoWLAN to eliminate dead zones in dense concrete structures while satisfying OSHA and Joint Commission communication requirements.
- SIP:Session Initiation Protocol signaling enables carrier-grade interoperability between enterprise WiFi and mobile network cores. Japanese carriers leveraging MIC-aligned standards favor SIP trunking for converged indoor-outdoor voice handover in Tokyo and Osaka commercial districts.
- PBX:Legacy private branch exchange integration requires TDM-to-packet gateway deployment for hybrid voice architectures.
- RTP:Real-time Transport Protocol carries packetized media streams with quality-of-service prioritization mechanisms.
VoWLAN handles the majority of throughput; SIP is the fastest mover on share.
End User:
Cost tier differentiation separates capital-intensive healthcare deployments from subscription-favored hospitality rollouts.
- Enterprises:Fortune 500 facilities teams prioritize opex-light managed services over hardware ownership to accelerate coverage expansion. Financial services clusters in New York and London specify VoWiFi during new construction planning to satisfy business continuity regulators.
- Healthcare Facilities:Hospital systems require guaranteed sub-150 millisecond latency for clinical staff emergency communication. The Joint Commission and CMS conditions of participation mandate reliable indoor voice coverage, driving specialized deployment contracts with redundant infrastructure requirements.
- Educational Institutes:University campuses deploy converged WiFi-voice platforms to reduce cellular carrier dependency across distributed dormitory and classroom footprints.
- Hospitality:Hotel operators favor cloud-based consumption models to eliminate capital refresh cycles across property portfolios.
Enterprises absorb the largest deployment volumes; Healthcare Facilities are climbing the fastest on contract value per square foot.
Deployment:
Customer type preferences split between control-retentive on-premises buyers and agility-seeking cloud adopters.
- Cloud-Based:Subscription consumption eliminates hardware refresh cycles while compressing capital equipment sales. Mid-market enterprises across Australia and Singapore adopt cloud-native IMS cores to accelerate deployment timelines without dedicated SIP engineering staff.
- Managed:Recurring network management contracts lock in multi-year revenue streams that pure software licenses cannot replicate. Carriers in South Korea and the United States bundle managed VoWiFi with existing enterprise connectivity contracts to deepen account penetration.
- On-Premises:Government and defense installations mandate physical infrastructure control for security classification compliance.
- Hybrid:Transitional architectures bridge legacy PBX investment with packetized WiFi voice expansion.
Managed services capture the steepest expansion trajectory; On-Premises retains the largest installed base.
Service Type:
Margin concentration favors recurring revenue models over one-time license transactions.
- Network Management:Continuous monitoring and quality-of-service tuning generate durable revenue streams. Telecom operators in France and Canada package network management with SLAs guaranteeing E911 dispatchable address accuracy for indoor callers.
- VoIP Solutions:Software licensing faces pricing pressure as cloud-native alternatives displace perpetual purchase models.
- User Support:Help desk and troubleshooting services attach to enterprise contracts as retention mechanisms.
- Consulting:SIP engineering talent scarcity creates premium billing rates for protocol configuration and interoperability testing.
Network Management dominates recurring revenue pools; Consulting commands the highest hourly rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
VoWiFi infrastructure investment concentrates in economies with dense commercial real estate and stringent indoor coverage mandates. Carrier deployment priorities diverge sharply between markets with FCC-style E911 obligations and those with lighter regulatory frameworks.
United States
Enterprise IT departments in Manhattan and Chicago accelerate VoWiFi deployment to eliminate cellular dead zones in legacy office towers. The FCC mandates dispatchable address accuracy for indoor callers, compelling infrastructure upgrades across nationwide carrier networks. Dallas-Fort Worth hosts concentrated vendor engineering operations serving North American enterprise accounts.
Germany
Industrial manufacturing clusters in Bavaria and Baden-Württemberg deploy VoWLAN to bypass recurring cellular infrastructure fees in dense concrete facilities. CE marking under the EU Radio Equipment Directive imposes extended certification timelines for multi-band equipment. Frankfurt's financial district specifies converged WiFi-voice platforms during new construction planning to satisfy business continuity regulators.
Japan
Tokyo and Osaka commercial districts favor SIP trunking for converged indoor-outdoor voice handover in high-density urban environments. METI-aligned technical standards harmonize with 3GPP frameworks, streamlining equipment certification for domestic vendors. Nagoya's automotive manufacturing corridors require guaranteed indoor voice coverage for just-in-time production coordination.
South Korea
Seoul Capital Area carriers bundle managed VoWiFi with existing enterprise connectivity contracts to deepen account penetration in chaebol-affiliated facilities. The country's national telecommunications regulator enforces strict quality-of-service benchmarks for packetized voice services. Busan-Ulsan industrial zones deploy redundant infrastructure to satisfy stringent latency requirements for shipyard operations.
United Kingdom
London financial services clusters specify VoWiFi during new construction planning to satisfy Prudential Regulation Authority business continuity requirements. Ofcom spectrum policy reforms prioritize indoor wireless coverage investments in historic structures with poor cellular penetration. Manchester and Birmingham commercial developments target smart building credentials through converged network specifications.
Voice Over Wifi Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the VoWiFi infrastructure stack. The market structures around three tiers: integrated networking conglomerates with enterprise installed bases, pure-play telecom equipment vendors with 3GPP-compliant cores, and carrier-affiliated service operators with captive subscriber relationships. Strategic differentiation centers on interoperability certification depth and managed service attach rates rather than hardware pricing alone. Competitive moves concentrate on cloud-native IMS core development and vertical-specific latency guarantee programs.
Among integrated networking specialists, Cisco Systems Inc. and Nokia Corporation exemplify contrasting geographic positioning strategies. Huawei Technologies Co. Ltd. occupies a distinct manufacturing-scale archetype with concentrated dominance in Asia-Pacific markets. Telefonaktiebolaget LM Ericsson represents the pure-play telecom equipment vendor model with standardized 3GPP-aligned portfolio architecture. These three anchors collectively illustrate how vendor selection criteria diverge between enterprise buyers prioritizing existing infrastructure compatibility and carriers demanding release-compliant interoperability.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Cisco Systems Inc. |
| Oracle Corporation |
| AT&T Inc. |
| Verizon Wireless |
| T-Mobile USA Inc. |
| Aptilo Networks |
| Others |
Value Chain & Pricing Dynamics
FCC E911 location accuracy mandates gate both supplier qualification and price differentiation simultaneously, forcing equipment vendors to absorb enhanced positioning certification costs before accessing United States carrier procurement channels while creating tiered margin structures between dispatchable-address-compliant and non-compliant product lines.
Pricing Analysis
FCC dispatchable address requirements dictate the pricing tier structure across VoWiFi infrastructure, separating premium-grade certified cores from standard enterprise WiFi gear lacking E911 integration. Price differentiation rests on certification depth and managed service bundling rather than hardware specifications alone. Pricing pressure stems from cloud-native IMS alternatives compressing perpetual license values. Mid-market enterprises exhibit highest price sensitivity, while healthcare facilities prioritize latency guarantees over capital expenditure minimization.
Supply Chain Analysis
Just-in-time inventory strategies dominate chipset procurement for VoWiFi equipment manufacturers, though strategic stockpiling of 3GPP-compliant WiFi calling cores has intensified following Taiwan foundry capacity constraints. Supply concentrates in Taiwan, South Korea, and China for baseband processors and RF front-end components. Raw material dependencies include silicon wafers, GaAs substrates, and specialized antenna substrates. Single-source vulnerability in advanced node foundry capacity creates structural risk. Distribution runs through carrier-direct procurement channels and enterprise networking distributors serving Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
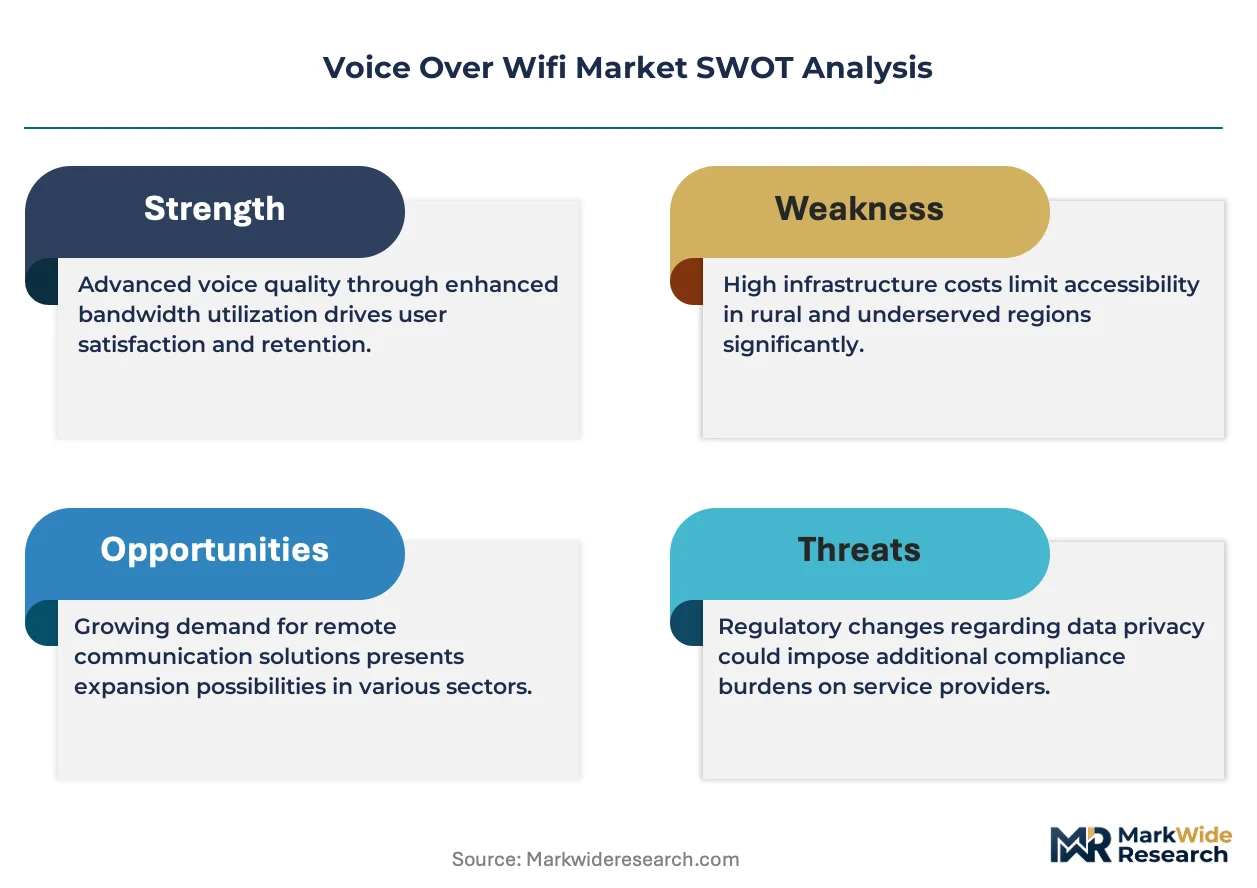
VoWiFi infrastructure represents a service-attach opportunity where recurring network management contracts expand faster than hardware sales, with managed service margins capturing multi-year revenue streams that perpetual licenses cannot replicate.
For Market Incumbents: Consolidate around cloud-native IMS core development and vertical-specific latency guarantee programs to defend against pure-play SIP engineering specialists eroding enterprise accounts. Deepen certification investment in FCC dispatchable address compliance to maintain carrier procurement eligibility. Prioritize backward integration into WiFi chipset supply to mitigate Taiwan foundry concentration risk. For New Entrants and Emerging Players: Lead with healthcare vertical penetration targeting hospital systems requiring guaranteed sub-150 millisecond latency for clinical emergency communication, where Joint Commission mandates create non-discretionary procurement budgets. Target mid-market enterprises in Australia and Singapore lacking dedicated SIP engineering staff. Position through subscription-based managed service offerings to bypass incumbent hardware installed base advantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as software-defined architectures displace proprietary hardware switching. Long-term viability favors vendors with recurring revenue attach rates above industry medians. Acquisition targets should demonstrate MIC-aligned certification pathways for Japanese market access. Watch 3GPP Release 18 handover protocol adoption rates as inflection indicator for interoperability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native IMS Core Development | Decomposes proprietary hardware architectures into subscription revenue streams for mid-market enterprise penetration. |
| FCC E911 Certification Investment | Unlocks carrier-direct procurement channels requiring dispatchable address accuracy for indoor voice coverage. |
| Healthcare Vertical Specialization | Captures premium contract values from hospital systems mandating redundant infrastructure for clinical communication. |
| Managed Service Bundling | Locks multi-year revenue streams through continuous quality-of-service tuning and network monitoring contracts. |
| 3GPP Release 18 Alignment | Ensures interoperability certification for enhanced WiFi-calling handover protocols across carrier networks. |
Study Parameters
A standing panel of carrier network architects, enterprise IT directors, SIP engineering specialists, and healthcare facilities technology officers provided ongoing calibration across primary interviews combined with secondary validation from FCC filings, 3GPP release documentation, carrier capex disclosures, and equipment vendor SEC filings. Bottom-up deployment volume estimates triangulated against top-down service revenue projections.
Consistency checks validated volume and value outputs against external benchmarks across technology type, deployment model, service type, and end-user vertical segmentation throughout the forecast period. CAGRs derived from logistic diffusion modeling of enterprise adoption curves and carrier infrastructure refresh cycles. Industry-specific inputs included E911 mandate compliance timelines and 3GPP standardization roadmaps.
The analysis sits within stated boundaries; outcomes outside sustained carrier investment in indoor coverage infrastructure or accelerated cloud-native adoption would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement continuity and foundry capacity availability. Revision becomes warranted when Taiwan geopolitical risk or unlicensed spectrum congestion crosses operational thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Wireless LAN Controller Market