
 Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market | 2026-2036
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market Analytics
IMS-based voice architecture is fragmenting across hybrid cloud and on-premise deployment models, forcing vendors to support multi-environment orchestration. Ericsson AB sustains R&D intensity in 5G voice continuity protocols. Nokia Corporation anchors geographic dominance through carrier-grade IMS contracts with European operators. Huawei Technologies leverages integrated radio-access-to-core portfolios to compete in markets with aggressive infrastructure buildouts.
Voice Over LTE and Voice Over Wi-Fi denote packet-switched voice services transported over LTE radio bearers or untrusted Wi-Fi access points via secured IPsec tunnels to the operator IMS core, with mandatory support for single-radio voice continuity, QoS marking through QCI=1 bearers, and seamless handover between access technologies. The technology dimension shows VoLTE occupying mature margin pools in developed markets while VoWiFi captures incremental coverage in dense urban and indoor environments. The deployment model dimension reveals cloud-based IMS functions growing fastest as operators virtualize network functions to reduce capex cycles.
3GPP, GSMA, and national telecom regulators including the FCC and Ofcom shape demand through spectrum reframing mandates and voice-service quality obligations that accelerate circuit-switched network retirement. CE marking under the EU Radio Equipment Directive and FCC Part 27 equipment authorization create divergent compliance pathways for handset and infrastructure vendors. Stakeholders must monitor 3GPP Release 18 work on AI-native voice quality optimization and decide whether to prioritize R&D investment in predictive codec adaptation or spectrum aggregation for voice bearers.
Market Dynamics
Spectrum reframing mandates from national regulators are forcing accelerated circuit-switched network retirement, compelling mobile operators to migrate voice traffic onto packet-switched IMS cores ahead of legacy infrastructure end-of-life deadlines.
Growth Catalysts
- 3GPP Release 18 AI-native voice quality frameworks:Standardization bodies are embedding machine learning into codec adaptation protocols, enabling predictive bandwidth management that sustains call clarity during network congestion.
- India rural circle expansion:Domestic operators are extending IMS core deployments to tier-3 and tier-4 markets, converting previously unserved populations into addressable subscribers for VoLTE services.
- GSMA IR.92 interoperability mandates:Compliance frameworks are eliminating proprietary implementations that previously fragmented handset-to-network compatibility, reducing integration friction for multi-vendor deployments.
Market Restraints
- Silicon supply concentration:Baseband processor fabrication depends on a narrow geographic cluster of advanced foundry capacity, exposing equipment vendors to allocation volatility during demand surges.
- IMS core capex intensity:Virtualized network function deployments require substantial upfront investment in cloud-native orchestration layers before operational savings materialize.
- Wi-Fi calling quality variability:Untrusted access point performance inconsistency degrades user experience in residential environments where broadband backhaul lacks QoS prioritization.
Strategic Opportunities
- Enterprise unified communications convergence:Fixed-mobile integration is dissolving boundaries between cellular voice and corporate PBX systems, opening subscription bundles for mobile operators.
- Indoor coverage densification:VoWiFi penetration in high-rise commercial and residential structures addresses macro network propagation limitations without additional radio access infrastructure.
- EU Radio Equipment Directive certification harmonization:Streamlined CE marking pathways are reducing time-to-market for multi-band handsets targeting cross-border operator procurement.
Industry Challenges
- Legacy SS7 interworking complexity:Maintaining signaling compatibility between modern IMS cores and remaining circuit-switched networks demands specialized protocol translation gateways.
- Voice engineer skill scarcity:Packet-switched telephony expertise remains concentrated among a limited pool of specialists familiar with SIP trunking, Diameter routing, and policy control functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market |
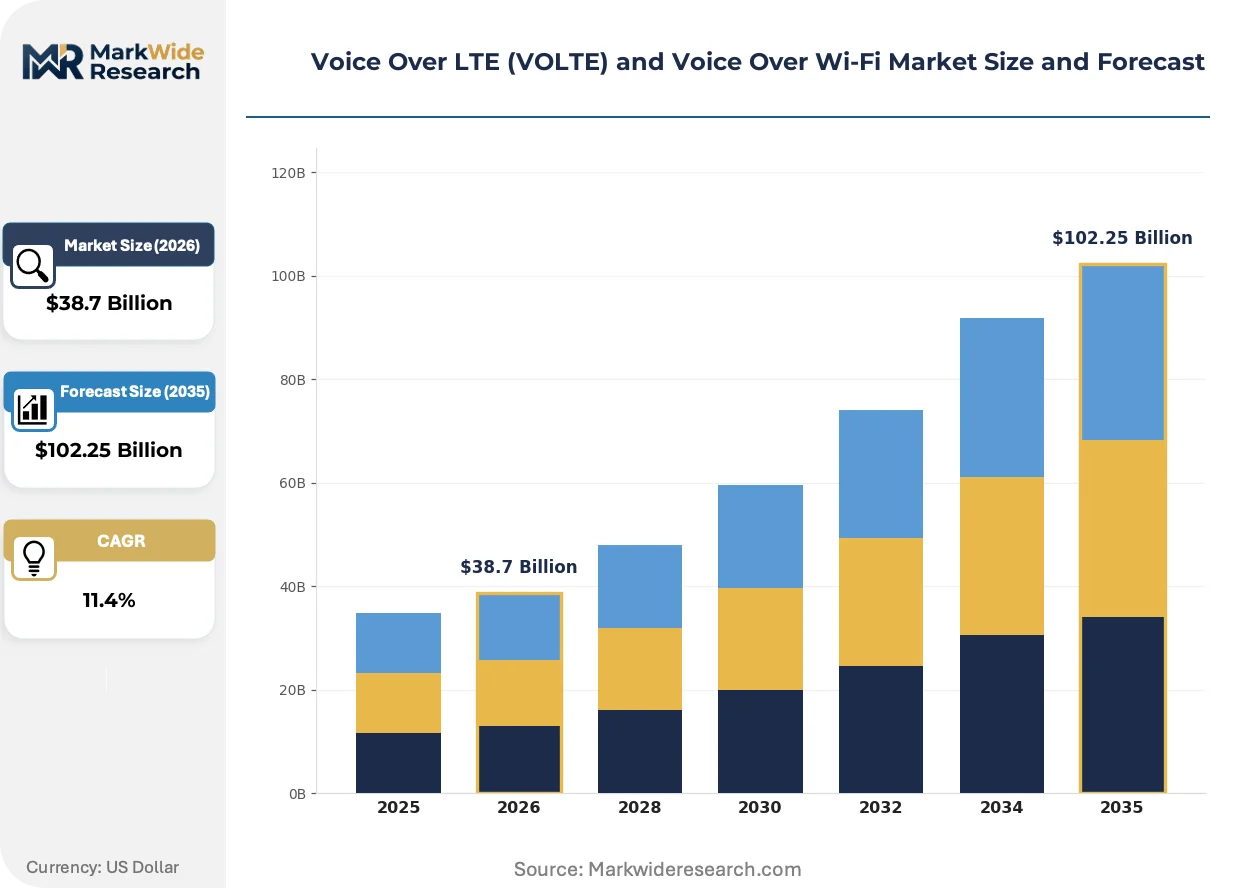
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VoLTE, VoWiFi, Circuit-Switched Fallback, IMS Deployment Model: On-Premise, Cloud, Hybrid, Private Network Service Type: VoIP Services, Messaging Services, Video Services, Data Services End User: Consumers, Enterprises, Telecom Operators, Government |
| Companies Covered | Huawei Technologies, Nokia Corporation, Ericsson AB, Qualcomm Incorporated, Samsung Electronics, Cisco Systems, ZTE Corporation, Ribbon Communications, Mavenir Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market Evolving Landscape
Artificial intelligence is penetrating voice service architectures, reshaping how operators manage quality-of-experience and how regulators frame performance obligations for next-generation networks.
AI-driven codec adaptation is digitizing real-time voice quality optimization by dynamically adjusting compression algorithms based on predicted network conditions. Mobile operators in South Korea and Japan are piloting these capabilities in dense urban deployments. The technology is digitizing traditional network planning cycles, compressing months of drive-test analysis into continuous automated parameter tuning.
The EU AI Act risk classification framework is imposing algorithmic transparency requirements on automated voice quality management systems deployed within member states. Equipment vendors must now document training data provenance and decision logic for machine learning models influencing emergency call routing. German and French operators are responding by segregating AI voice functions into explainable sub-modules subject to third-party audit.
Enterprise procurement of voice services is fragmenting from bundled mobile contracts toward modular API-based communications platforms. Large employers in financial services and logistics verticals are disaggregating voice minutes from data allowances, purchasing carrier-grade SIP connectivity separately from consumer-grade mobile subscriptions. This pattern is most pronounced in North American and Nordic markets where IT departments retain direct vendor negotiation authority.
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market Segmentation
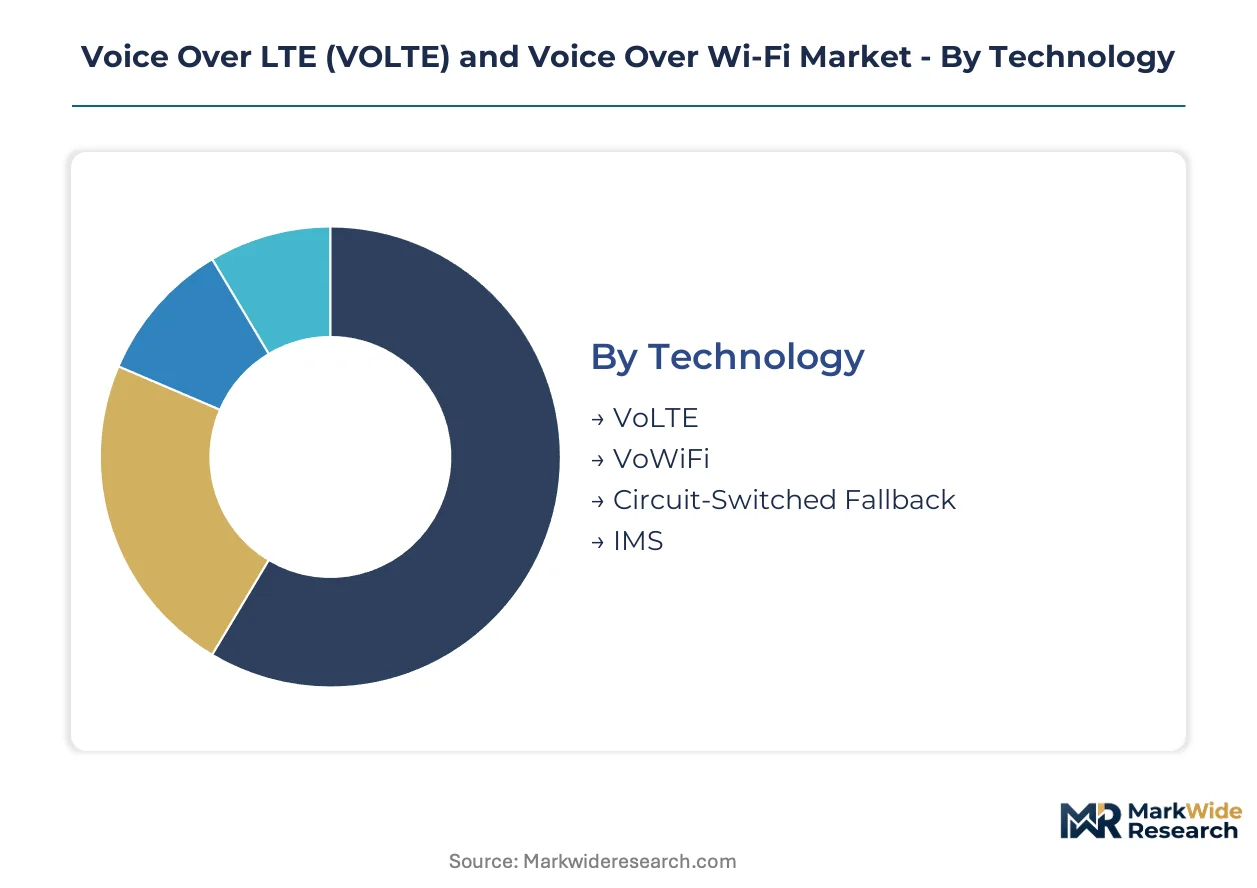
Segmentation in the VoLTE and VoWi-Fi market reveals distinct procurement rhythms across technology layers and deployment models. Operators balance long-cycle infrastructure commitments against rapidly iterating service bundles.
Technology:
VoLTE turns over fastest as operators complete circuit-switched migrations, while IMS core infrastructure refreshes slowest given architectural lock-in.
- VoLTE:Packet-switched voice transported over LTE radio bearers with QCI=1 bearers for quality-of-service marking. Demand concentrates in India as Reliance Jio and Bharti Airtel extend IMS deployments to rural circles.
- VoWiFi:Voice services delivered via untrusted Wi-Fi access points through IPsec tunnels to operator IMS cores. Dense urban environments in South Korea and Japan drive adoption where macro coverage fails indoors.
- Circuit-Switched Fallback:Interim voice continuity mechanism during LTE-to-2G/3G handover. Operators in Southeast Asia retain limited deployments pending full VoLTE coverage completion.
- IMS:IP Multimedia Subsystem core architecture enabling session initiation protocol routing. European operators under GSMA IR.92 mandates prioritize multi-vendor interoperability certification.
VoLTE dominates installed base. VoWiFi is where expansion concentrates.
Deployment Model:
Cost tier separation runs deepest here, with cloud-native functions commanding premium orchestration spending against depreciated on-premise hardware.
- On-Premise:Physical IMS core equipment housed in operator data centers with dedicated hardware redundancy. Incumbent European carriers maintain these deployments for regulatory data sovereignty compliance.
- Cloud:Virtualized network functions running on public or private cloud infrastructure with Kubernetes orchestration. Indian operators favor this model for rapid rural circle scaling without capital-heavy buildouts.
- Hybrid:Mixed environment combining on-premise control plane functions with cloud-based media processing. Japanese operators deploy hybrid architectures to balance latency requirements against elastic capacity needs.
- Private Network:Dedicated IMS infrastructure for isolated enterprise or government voice services. German industrial campuses and South Korean smart factory zones drive demand for guaranteed quality-of-service isolation.
On-premise retains the largest revenue pool. Cloud deployments are climbing the fastest.
Service Type:
Application maturity varies sharply, with messaging services iterating fastest through rich communication services upgrades.
- VoIP Services:Core packet-switched voice delivery including HD voice and emergency calling. Enterprise unified communications convergence in North American financial services verticals displaces traditional PBX procurement.
- Messaging Services:SMS-over-IP and rich communication services with multimedia sharing. South Korean operators lead RCS deployment density, forcing handset ecosystem alignment.
- Video Services:ViLTE and video-over-WiFi with synchronized voice channels. Indoor coverage densification in high-rise residential towers across Singapore and Hong Kong propels adoption.
- Data Services:Concurrent bearer management for voice-data multiplexing during active calls. 5G voice continuity protocols in Release 18 specifications enable seamless session persistence across access transitions.
VoIP services anchor revenue stability. Messaging services are gaining share fastest.
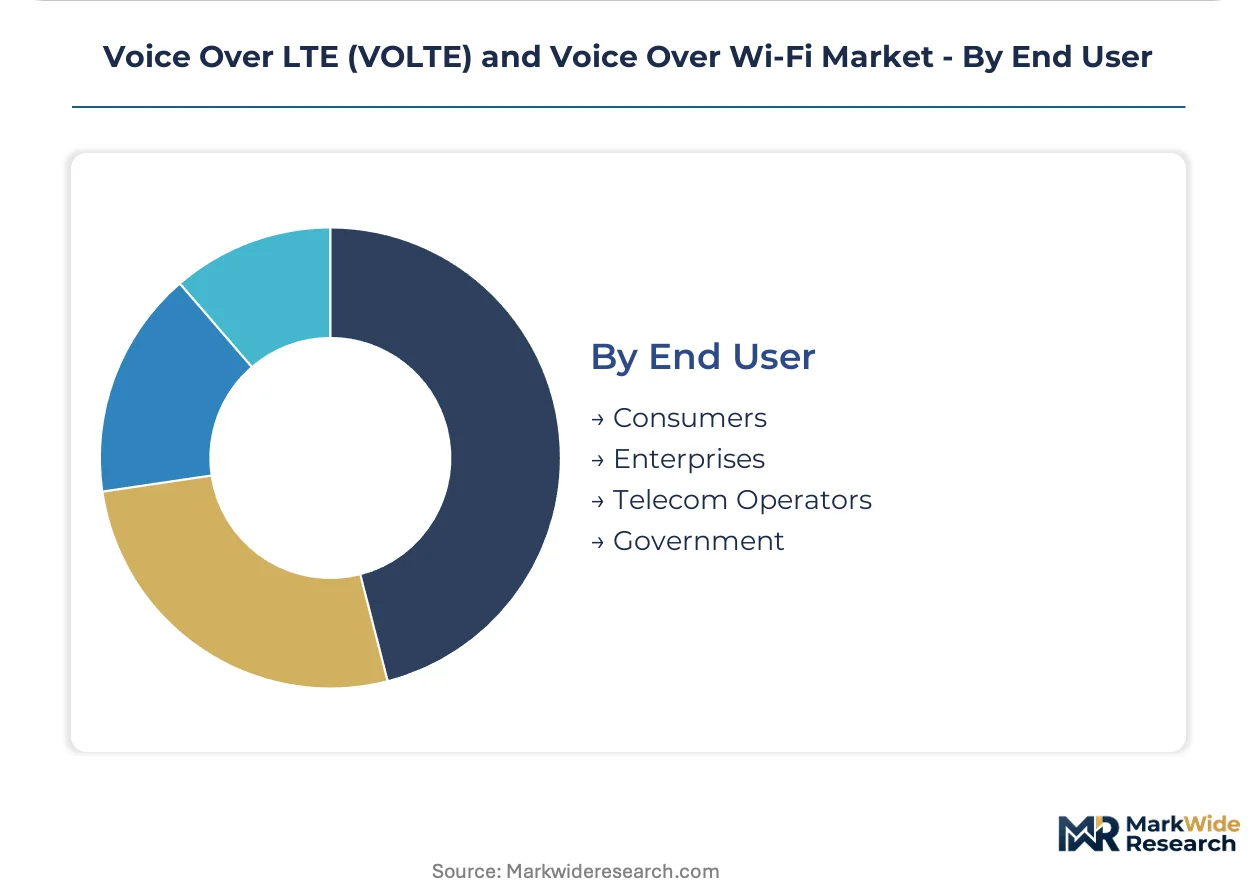
End User:
Customer type determines contract structure, with telecom operators locking in longest procurement cycles through multi-year IMS core agreements.
- Consumers:Individual subscribers accessing VoLTE and VoWiFi through retail mobile plans. India's tier-3 and tier-4 market expansion converts previously unserved populations into addressable subscribers.
- Enterprises:Corporate entities procuring fixed-mobile integration and API-based communications platforms. Nordic IT departments disaggregate voice minutes from data allowances, purchasing carrier-grade SIP connectivity separately.
- Telecom Operators:Mobile network operators building or upgrading IMS infrastructure for subscriber voice services. Southeast Asian operators accelerate migration to reclaim spectrum efficiency under national reframing mandates.
- Government:Public sector entities requiring secure, sovereign voice infrastructure with emergency service prioritization. EU AI Act transparency requirements impose algorithmic audit obligations on automated voice quality systems deployed for critical services.
Telecom operators command the largest absolute spending. Enterprises are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish and Swedish equipment exports supply Indian and Southeast Asian operators building rural IMS infrastructure. Equipment flows concentrate where spectrum reframing deadlines force accelerated circuit-switched retirement.
India
Reliance Jio and Bharti Airtel extend IMS core deployments to tier-3 and tier-4 rural circles, converting unserved populations into VoLTE subscribers. TRAI mandates quality-of-service benchmarks for voice over data networks that accelerate legacy network shutdown timelines. Mumbai and Delhi-NCR host the densest concentration of carrier data centers orchestrating cloud-native virtualized network functions.
South Korea
SK Telecom and KT Corporation pilot AI-native voice quality optimization in dense Seoul deployments. The Korea Communications Commission enforces strict latency thresholds for emergency voice services that shape equipment procurement specifications. Busan-Ulsan industrial corridors drive private network IMS demand for smart factory voice isolation.
Germany
Deutsche Telekom and Vodafone Germany maintain on-premise IMS cores for regulatory data sovereignty compliance under GDPR and national security frameworks. The Federal Network Agency mandates circuit-switched network retirement deadlines that compel packet-switched migration. Bavaria and North Rhine-Westphalia concentrate carrier data center infrastructure for low-latency voice processing.
United States
Verizon and AT&T expand VoWiFi penetration in high-rise residential towers across Manhattan and Chicago where macro coverage fails indoors. FCC Part 27 equipment authorization requirements create divergent compliance pathways for multi-band handset vendors. The Pacific Northwest and Texas Triangle host cloud infrastructure supporting virtualized IMS orchestration layers.
Japan
NTT Docomo and KDDI deploy hybrid cloud-on-premise architectures balancing latency requirements against elastic capacity needs. METI guidelines promote AI-driven network automation standards that influence vendor R&D priorities. The Tokyo-Yokohama corridor and Osaka-Kobe industrial zones concentrate subscriber density driving indoor coverage densification investments.
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market Competitive Landscape
On the supply side, the industry is consolidating around integrated radio-access-to-core portfolios and specialized IMS software vendors. Tier-one equipment manufacturers compete through carrier-grade multi-vendor interoperability certification. Three archetypes dominate: integrated infrastructure conglomerates, pure-play IMS software specialists, and semiconductor baseband providers. Competitive moves center on strategic partnerships for cloud-native orchestration and geographic expansion through carrier procurement cycles in emerging markets.
Within the integrated infrastructure tier, Huawei Technologies and Nokia Corporation exemplify archetypes competing through end-to-end portfolio breadth. Ericsson AB occupies a position representing Scandinavian R&D-intensive equipment vendors. These three anchors illustrate how vendor strategies diverge between geographic market focus and deployment model specialization across on-premise, cloud, and hybrid IMS architectures.
| Leading Market Players |
|---|
| Huawei Technologies |
| Nokia Corporation |
| Ericsson AB |
| Qualcomm Incorporated |
| Samsung Electronics |
| Cisco Systems |
| ZTE Corporation |
| Ribbon Communications |
| Mavenir Systems |
| Others |
Value Network & Pricing Analysis
Taiwanese advanced foundry concentration for baseband processors funnels pricing power downstream toward equipment vendors serving Indian and Southeast Asian operators, compressing margins for IMS software specialists competing on interoperability certification.
Pricing Analysis
Cloud-native IMS deployments command premium pricing against depreciated on-premise hardware installations. Three-tier pricing structure across premium carrier-grade, standard virtualized, and economy bare-metal configurations separates vendors with GSMA IR.92 certification from uncertified competitors. Pricing pressure stems from silicon allocation volatility during demand surges. Tier-3 mobile operators in rural India exhibit highest price sensitivity; European incumbents with data sovereignty mandates show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for multi-band handset vendors seeking FCC Part 27 authorization. Baseband processor fabrication draws from Taiwan, South Korea, and mainland China. Silicon wafers, IP core licensing, and radio frequency front-end modules constitute critical input dependencies. Single-source vulnerability in 3nm fabrication capacity threatens equipment delivery schedules. Distribution runs through carrier procurement departments with multi-year IMS core framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IMS interoperability standardization is collapsing proprietary voice architectures into platform economies where API-based communications platforms displace bundled mobile contracts, reshaping how operators monetize subscriber relationships.
For Market Incumbents: Insulate carrier-grade IMS positions through backward integration into cloud-native orchestration layers and accelerated certification under EU AI Act transparency frameworks. OTT voice applications threaten subscription revenue pools. Vertical control over virtualized network function deployment protects margin structures. For New Entrants and Emerging Players: Pursue enterprise unified communications convergence in North American financial services verticals where IT departments disaggregate voice procurement from consumer mobile plans. Fixed-mobile integration APIs represent the most penetrable white-space. Carrier-grade SIP connectivity sold separately from data allowances offers direct go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native IMS software specialists with demonstrated multi-vendor interoperability certification and Kubernetes orchestration expertise. Long-term viability hinges on 5G voice continuity protocol adoption across the analysis window. Target acquisition archetype: virtualized network function vendors with Indian operator deployment references. Signal to monitor: 3GPP Release 18 AI-native voice quality framework commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native IMS Virtualization | Reduces capex cycles for Indian operators expanding into tier-3 rural circles. |
| GSMA IR.92 Interoperability Certification | Eliminates handset-to-network fragmentation in multi-vendor European deployments. |
| AI-Native Voice Quality Optimization | Enables predictive codec adaptation under South Korean latency mandates. |
| Enterprise API Platform Integration | Dissolves boundaries between cellular voice and corporate PBX systems in Nordic markets. |
| Private Network IMS Deployment | Delivers guaranteed quality-of-service isolation for German industrial campuses. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of 3GPP release documentation, GSMA technical specifications, national regulatory filings with TRAI and the FCC, and equipment vendor SEC disclosures. Interviews conducted with IMS core architects at tier-1 operators, virtualization engineers at cloud infrastructure providers, procurement directors at European carriers, and policy leads at standards bodies. Bottom-up subscriber penetration models triangulate against top-down infrastructure spending forecasts.
Forecast inputs span technology migration timelines, spectrum reframing deadlines, and cloud-native deployment adoption curves across the projection horizon. Segmentation dimensions include deployment model architecture, service type maturity, end-user procurement structure, and regional regulatory cluster. CAGRs derive from equipment vendor revenue recognition patterns and operator disclosed subscriber conversion rates. Voice engineer labor scarcity and silicon foundry capacity constraints inform supply-side boundary conditions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers into virtualized network function orchestration would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Wireless Charger Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Wireless Access Point Market